
 Asia-Pacific Handheld Vacuum Cleaner Market | 2026-2036
Asia-Pacific Handheld Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Handheld Vacuum Cleaner Market Insights
Lithium-ion battery energy density improvements and brushless DC motor miniaturization are reshaping handheld vacuum cleaner engineering across Asia-Pacific. Dyson leverages proprietary cyclonic separation patents to sustain premium positioning in Japan and South Korea. Tineco anchors its growth through direct-to-consumer digital channels and rapid product refresh cycles. Baofumei Technology specializes in cost-optimized motor assemblies that supply multiple white-label brands across Southeast Asia.
Asia-Pacific handheld vacuum cleaners are portable suction devices typically weighing under three kilograms, powered by rechargeable battery packs with voltages ranging from 18V to 25V, and engineered for intermittent cleaning tasks in constrained spaces. The residential end user segment dominates unit volume, though commercial adoption in hospitality chains and co-working spaces is expanding fastest. Battery-powered product types command the widest margin pools as consumers prioritize cordless mobility over tethered alternatives. Cyclonic and HEPA filter technologies attract regulatory preference and premium pricing in markets with stringent indoor air quality standards.
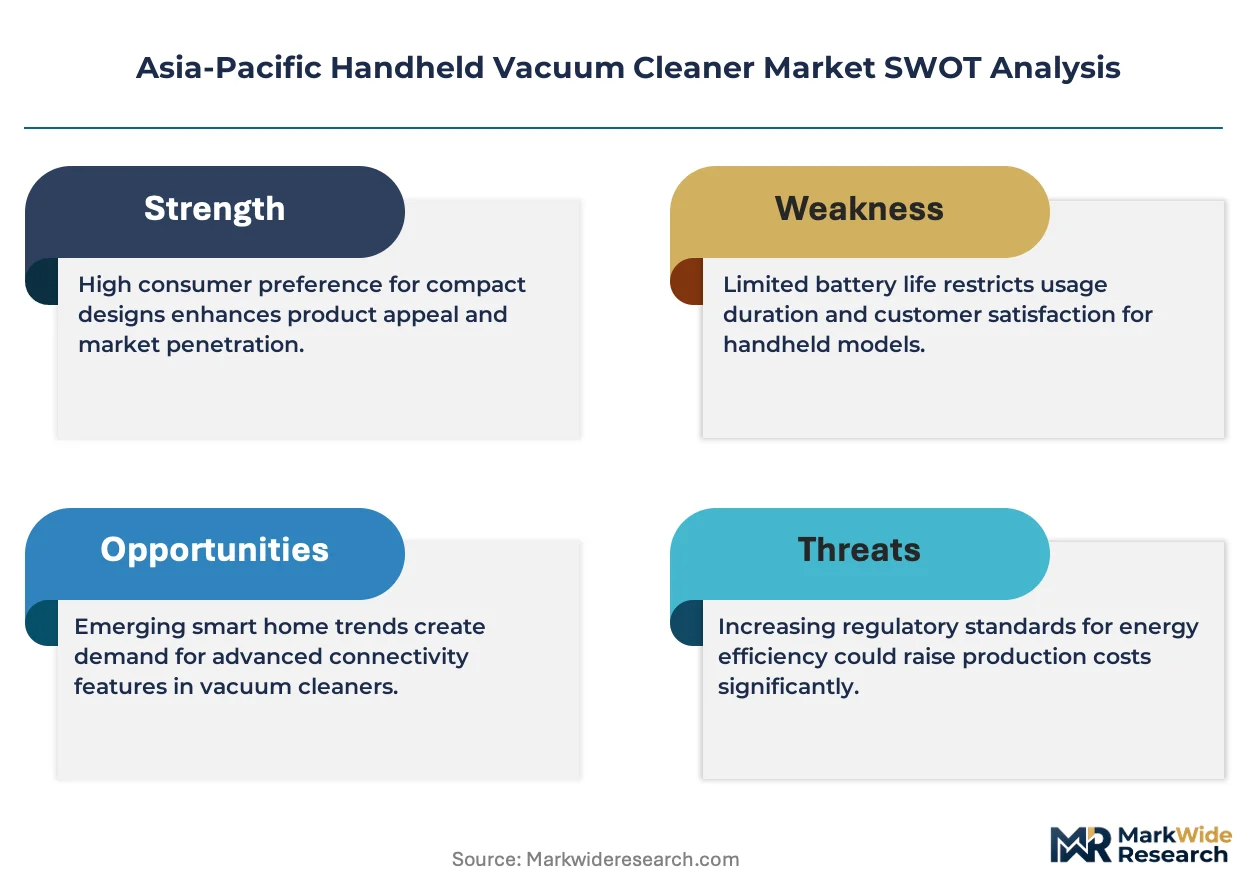
China's SAMR enforces GB standards for appliance energy consumption and electromagnetic compatibility, while India's BIS mandates safety certifications for lithium-ion battery packs used in cordless appliances. Japan's METI administers Top Runner efficiency programs that push manufacturers toward higher motor performance per watt. Stakeholders must monitor how evolving battery safety protocols and recycling mandates across multiple Asia-Pacific jurisdictions will reshape component sourcing and after-service obligations.
Market Dynamics
Urban apartment dwellers in dense metropolitan areas are compressing cleaning cycles into smaller time windows, forcing manufacturers to prioritize suction-to-weight ratios and rapid-charge architectures over raw power specifications.
Growth Catalysts
- China's dual carbon goals:Beijing's emission reduction mandates are accelerating brushless DC motor adoption across domestic supply chains, creating efficiency thresholds that filter into export-ready products.
- Co-working space operators:Flexible workspace providers across Singapore and Australia are standardizing cordless handheld units for daily maintenance, generating recurring bulk procurement volumes.
- Lithium-ion energy density gains:Cell chemistry improvements are extending runtime-to-weight ratios, enabling 25V platforms that match previous 40V tethered performance in sub-2kg form factors.
Market Restraints
- Raw material concentration:Rare earth magnet supply from Chinese processors creates single-point vulnerability for motor assembly cost stability.
- India's BIS certification timelines:Extended safety testing protocols for lithium-ion battery packs delay product launches by 4-7 months versus comparable ASEAN markets.
- Technical ceiling on miniaturization:Thermal management constraints in sub-1.5kg chassis limit sustained high-power operation to under 8 minutes.
Strategic Opportunities
- Vietnam's manufacturing corridors:Da Nang and Hai Phong industrial zones offer tariff-advantaged assembly capacity for brands targeting ASEAN duty-free trade blocs.
- Japan's METI Top Runner program:Efficiency benchmarking creates regulatory preference for premium-tier products that exceed baseline wattage standards.
- Direct-to-consumer live commerce:Shopee and Lazada streaming channels are collapsing traditional distributor margins in Indonesia and Philippines, enabling first-party data capture.
Industry Challenges
- Battery pack recycling compliance:Emerging extended producer responsibility laws across South Korea and Taiwan require reverse logistics infrastructure that most mid-tier brands lack.
- IP fragmentation in cyclonic separation:Patent thickets around multi-cone architectures force engineering teams into workarounds that compromise dust separation efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Handheld Vacuum Cleaner Market |
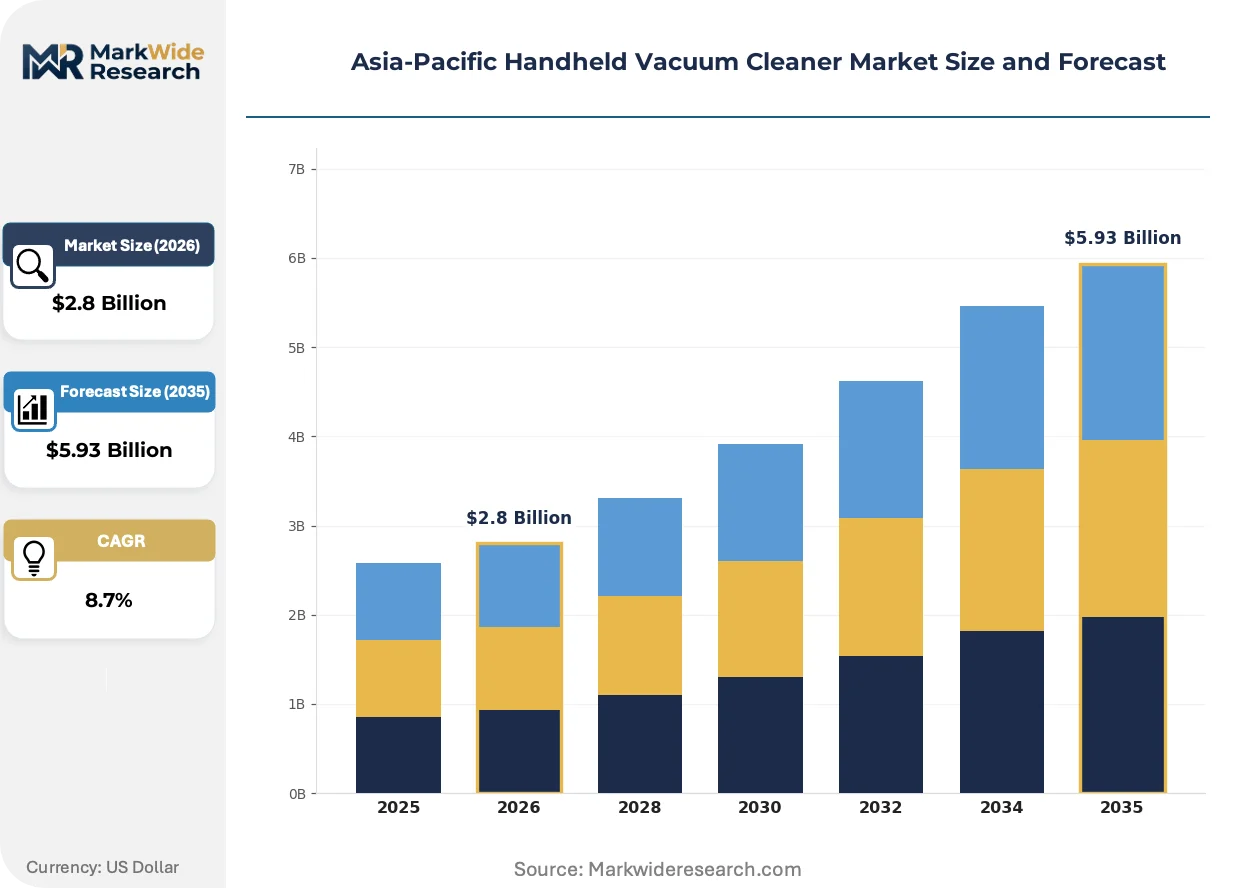
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery-Powered, Cordless, Multi-Surface, Compact Technology: Cyclonic, HEPA Filter, Suction Technology, Portable End User: Residential, Commercial, Automotive, Industrial Distribution Channel: Online, Retail Store, Direct Sales, Wholesalers |
| Companies Covered | Dyson, Samsung Electronics, LG Electronics, Philips, Electrolux, Miele, Tineco, Baofumei Technology, Roidmi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Handheld Vacuum Cleaner Market Trends and Innovations
Handheld vacuum engineering is pivoting from motor-centric competition toward integrated system optimization, where battery management algorithms and filtration architecture determine premium positioning more than raw suction metrics alone.
Smart battery management systems with cell-level monitoring and adaptive discharge curves are digitizing maintenance scheduling and warranty risk assessment for fleet operators. Hospitality chains in Australia's Gold Coast and Queensland are piloting connected units that transmit usage telemetry to central facilities management platforms. This connectivity layer is digitizing the transition from capital equipment sales toward service-contract revenue models.
India's BIS energy-efficiency labeling requirements are tightening permissible standby power draw and charging loss coefficients for cordless appliances sold domestically. Manufacturers must redesign power bricks and standby circuits to meet these thresholds, compressing margin structures on economy-tier SKUs. The western coastal manufacturing corridors around Mumbai and Pune are experiencing the fastest certification backlog volumes as brands rush to comply before enforcement windows tighten.
Urban consumers in China's tier-one cities are unbundling after-sales service expectations from initial purchase decisions, treating handheld vacuums as disposable appliances rather than repairable durables. E-commerce platforms are responding with subscription-based filter replacement and battery refresh programs. This behavioral pivot is most visible in Shanghai and Shenzhen, where same-day delivery infrastructure supports consumables replenishment at scale.
Asia-Pacific Handheld Vacuum Cleaner Market Segmentation
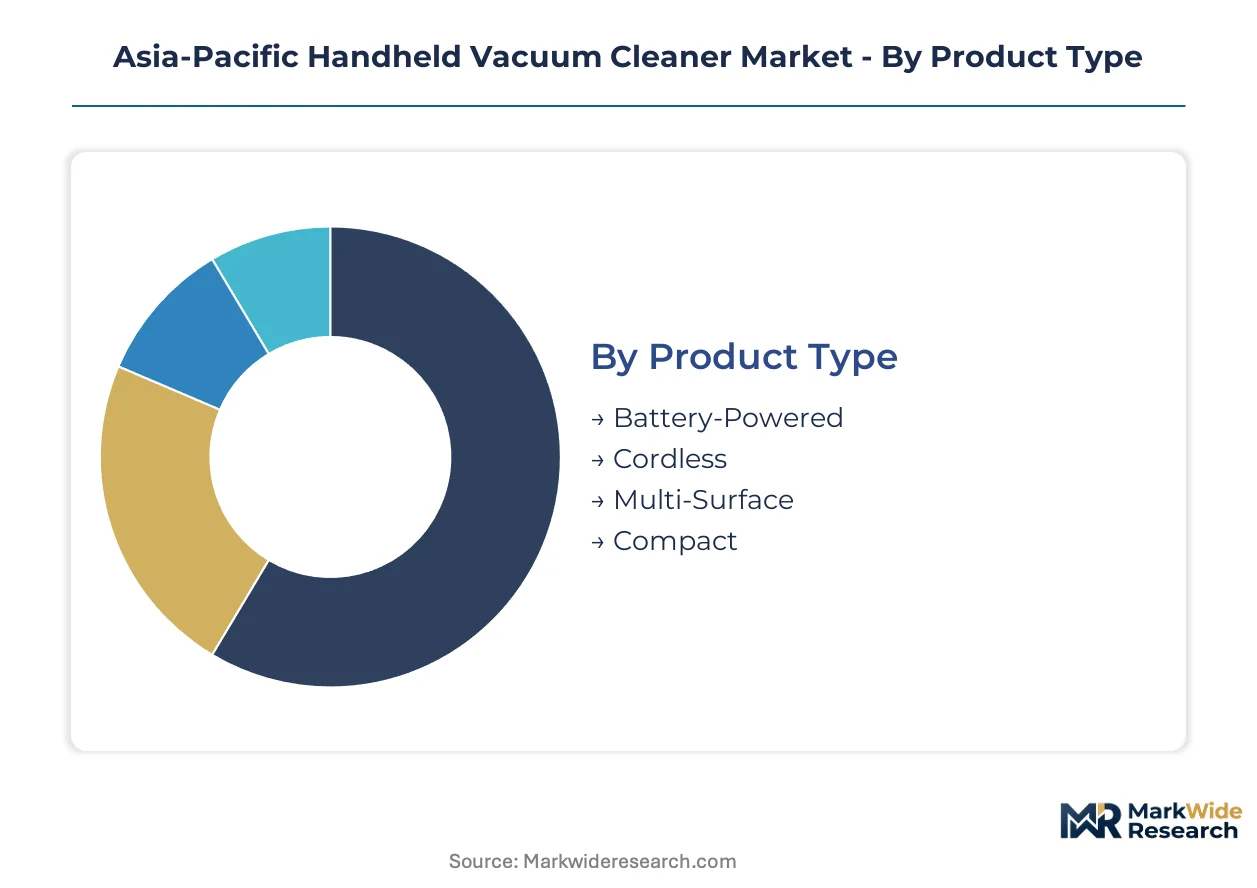
Handheld vacuum cleaner segmentation across Asia-Pacific reveals distinct turnover velocities, with battery-powered platforms cycling through consumer replacement decisions faster than commercial-grade units. Understanding these cadence differences helps manufacturers align inventory planning with regional purchasing patterns and regulatory compliance timelines.
Product Type:
Battery-powered units turn inventory fastest through retail channels, while compact models linger longest in household replacement cycles due to lower utilization intensity.
- Battery-Powered:Rechargeable lithium-ion platforms operating at 18V to 25V deliver cordless mobility for intermittent cleaning tasks. Demand concentrates in China's tier-one cities where apartment dwellers prioritize storage efficiency and rapid-charge architectures over raw suction specifications. These units anchor the widest margin pools as consumers trade tethered alternatives for maneuverability.
- Cordless:This designation overlaps with battery-powered architectures but emphasizes the absence of power tethering as the primary purchasing criterion. India's western coastal manufacturing corridors generate the steepest procurement volumes for export-ready cordless SKUs targeting ASEAN duty-free trade blocs.
- Multi-Surface:Configurable brush heads and suction modulation adapt to hard floors, upholstery, and vehicle interiors.
- Compact:Sub-1.5kg form factors prioritize storage footprint over sustained runtime, appealing to dense metropolitan households with severe space constraints.
Compact models anchor the volume base while battery-powered configurations gain share at the steepest rate.
Technology:
Cost tier separation is pronounced, with cyclonic systems commanding premium positioning against entry-level suction technology variants.
- Cyclonic:Multi-cone separation architectures spin particulate matter from airflow without filter saturation, extending maintenance intervals. Japan and South Korea drive premium-tier demand where METI efficiency benchmarking rewards superior dust separation performance per watt consumed.
- HEPA Filter:High-efficiency particulate arresting media capture 99.97% of particles at 0.3 microns, satisfying stringent indoor air quality standards. Australia's hospitality chains and co-working operators specify HEPA-equipped units for commercial deployment across Queensland and New South Wales.
- Suction Technology:Conventional motor-driven airflow without advanced separation mechanisms dominates economy-tier pricing.
- Portable:Lightweight chassis engineering under 3kg enables single-handed operation for vehicle and quick-spot cleaning applications.
Suction technology anchors the volume base while HEPA filter configurations gain share at the steepest rate.
End User:
Application intensity varies dramatically, with automotive detailing requiring specialized attachments versus residential spot-cleaning tolerating generic configurations.
- Residential:Apartment dwellers in dense metropolitan areas compress cleaning cycles into smaller time windows, forcing prioritization of suction-to-weight ratios. China's tier-one cities and India's urban corridors generate the dominant unit volumes as nuclear household formation accelerates.
- Commercial:Flexible workspace providers across Singapore and Australia standardize cordless handheld units for daily maintenance, generating recurring bulk procurement volumes with centralized facilities management oversight.
- Automotive:Specialized crevice tools and brush attachments address vehicle interior geometries, with demand clustering around aftermarket service centers.
- Industrial:Heavy-duty particulate handling in manufacturing environments requires reinforced filtration and thermal management beyond standard consumer specifications.
Residential applications anchor the volume base while commercial end use gains share at the steepest rate.
Distribution Channel:
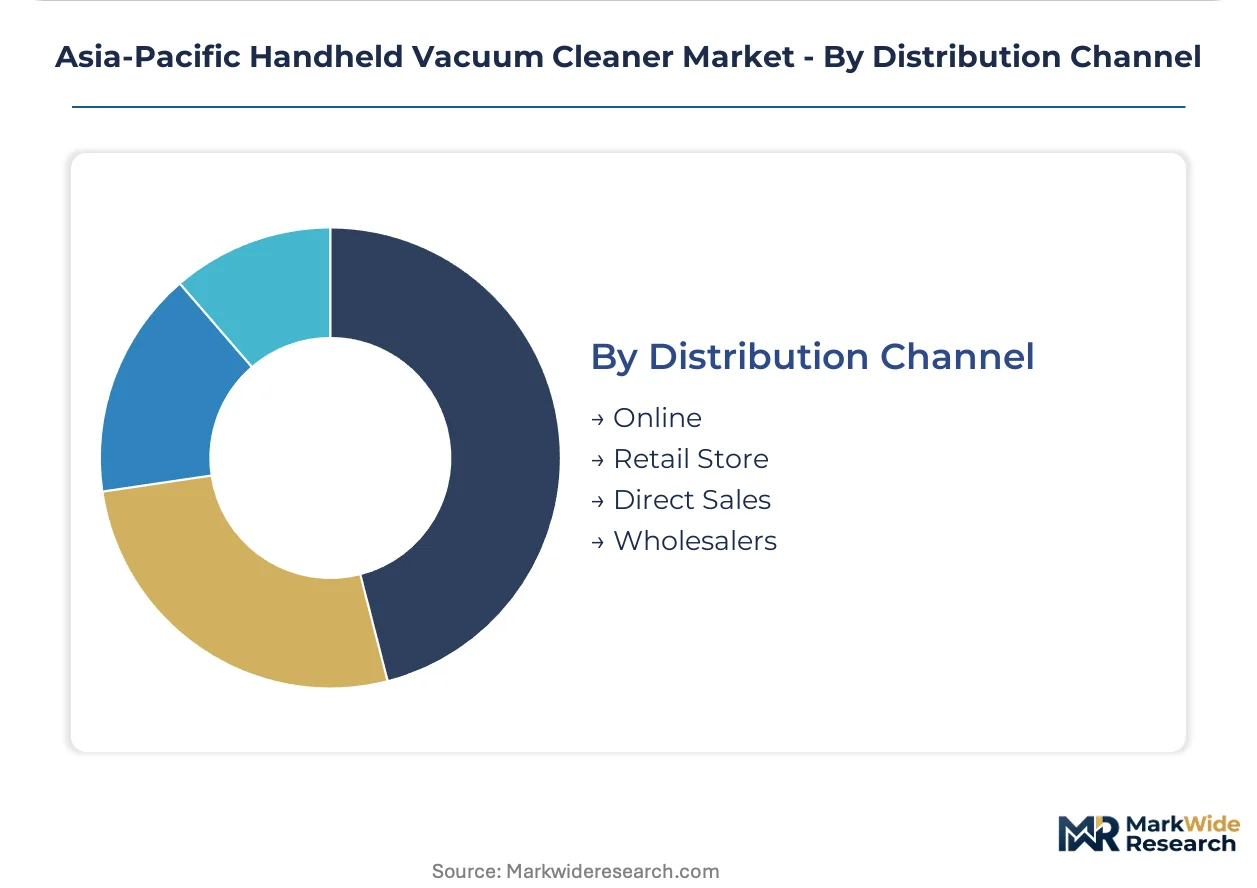
Margin structure diverges sharply between first-party digital capture and traditional wholesale intermediation.
- Online:Shopee and Lazada streaming channels collapse traditional distributor margins in Indonesia and Philippines, enabling direct-to-consumer live commerce with first-party data capture. Subscription-based filter replacement programs emerge through platform-integrated fulfillment infrastructure.
- Retail Store:Physical touchpoints allow motor noise and weight assessment prior to purchase, sustaining relevance in Japan and South Korea where premium positioning benefits from experiential validation.
- Direct Sales:Manufacturer-controlled channels bypass retail margin stacking, concentrating in enterprise procurement for hospitality fleet deployments.
- Wholesalers:Regional distributors aggregate smaller retail accounts across fragmented Southeast Asian markets with underdeveloped logistics networks.
Retail stores anchor the volume base while online channels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters across Asia-Pacific shape regional trade flows, with assembly capacity concentrating in tariff-advantaged zones that feed duty-free ASEAN blocs and higher-margin developed markets. Import demand clusters in dense metropolitan corridors where apartment dwellers prioritize cordless mobility.
China
Tier-one cities including Shanghai and Shenzhen compress cleaning cycles into smaller time windows, prioritizing suction-to-weight ratios and rapid-charge architectures. SAMR enforces GB standards for appliance energy consumption and electromagnetic compatibility that filter into export-ready products. The Yangtze River Delta and Pearl River Delta industrial corridors anchor brushless DC motor supply chains serving domestic and overseas brands.
Japan
Experiential retail validation sustains premium positioning for cyclonic separation technologies in Tokyo and Osaka metropolitan markets. METI administers Top Runner efficiency programs that push manufacturers toward higher motor performance per watt. The Kanto region concentrates R&D facilities optimizing dust separation efficiency under stringent benchmarking protocols.
India
Western coastal manufacturing corridors around Mumbai and Pune generate steepest certification backlog volumes as brands rush BIS compliance for lithium-ion battery packs. BIS energy-efficiency labeling requirements tighten permissible standby power draw and charging loss coefficients. The Maharashtra-Gujarat industrial belt experiences fastest procurement volume growth for export-ready cordless SKUs targeting ASEAN markets.
South Korea
Seoul Capital Area households demonstrate strongest preference for HEPA-equipped units satisfying stringent indoor air quality standards. Extended producer responsibility laws for battery pack recycling require reverse logistics infrastructure that reshapes after-service obligations. The Busan-Ulsan manufacturing zone supplies motor assemblies integrating METI-aligned efficiency benchmarks for premium-tier export production.
Australia
Hospitality chains and co-working operators across Queensland and New South Wales specify HEPA-equipped units for commercial fleet deployment. TGA-aligned product safety expectations influence procurement specifications for connected units transmitting usage telemetry to facilities management platforms. The Sydney-Melbourne corridor pilots subscription-based filter replacement programs leveraging same-day delivery infrastructure.
Asia-Pacific Handheld Vacuum Cleaner Market Competitive Landscape
On the supply side, the industry is tiered across premium technology licensors, scale-driven assembly specialists, and white-label component suppliers. Dyson anchors the premium tier through proprietary cyclonic separation patents, while Tineco and Baofumei Technology occupy distinct positions in direct-to-consumer digital channels and cost-optimized motor assemblies respectively. Strategic moves concentrate on direct-to-consumer live commerce expansion and Vietnam-based tariff-advantaged capacity relocation.
Within the premium technology tier, Dyson exemplifies patent-protected cyclonic separation positioning in Japan and South Korea. Among China-based fabricators, Tineco represents direct-to-consumer digital channel penetration with rapid product refresh cycles, while Baofumei Technology occupies the cost-optimized motor assembly segment supplying multiple white-label brands across Southeast Asia. Samsung Electronics and LG Electronics anchor diversified electronics conglomerate positioning, leveraging existing battery management and motor control competencies from adjacent appliance categories.
| Leading Market Players |
|---|
| Dyson |
| Samsung Electronics |
| LG Electronics |
| Philips |
| Electrolux |
| Miele |
| Tineco |
| Baofumei Technology |
| Roidmi |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor's container cost dynamics compress margin structures for brushless DC motor assemblies while amplifying price differentiation between premium cyclonic systems and economy-tier suction technology variants across Asia-Pacific distribution networks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with METI-aligned efficiency certifications and HEPA filtration grades driving price differentiation. Cost compression in economy-tier SKUs intensifies because India's BIS standby power mandates force power brick redesigns. Hospitality chains demonstrate least price sensitivity due to fleet standardization requirements, while individual residential purchasers in Southeast Asia exhibit highest sensitivity to per-unit acquisition costs.
Supply Chain Analysis
Extended payment terms from Chinese rare earth processors to Vietnam-based assembly facilities are reshaping working capital requirements for motor sourcing. Supply concentrates in China for lithium-ion cell chemistry, South Korea for battery management systems, and Vietnam for tariff-advantaged final assembly. Brushless DC motors, neodymium magnets, and HEPA filter media constitute critical input dependencies. Single-source vulnerability in Chinese rare earth magnet processing creates procurement risk. Distribution runs through Shopee and Lazada live commerce channels for direct-to-consumer capture, alongside traditional wholesale aggregation for fragmented Southeast Asian retail accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific handheld vacuum cleaner demand is accelerating through lithium-ion energy density inflections that displace tethered alternatives, while China's dual carbon goals and India's BIS efficiency mandates reshape compliance thresholds for market participation.
For Market Incumbents: Entrench proprietary cyclonic separation positioning through patent portfolio enforcement in Japan and South Korea, while expanding Vietnam-based assembly capacity to neutralize tariff exposure. Battery pack recycling infrastructure investment addresses emerging extended producer responsibility laws across South Korea and Taiwan. Channel control through direct-to-consumer live commerce platforms protects margin pools from distributor margin stacking. For New Entrants and Emerging Players: Mid-market commercial co-working operators in Australia's Queensland and New South Wales represent the most penetrable entry point, given standardized fleet procurement cycles and centralized facilities management oversight. Vietnam's Da Nang industrial zone offers tariff-advantaged manufacturing capacity for ASEAN duty-free trade bloc targeting. Subscription-based filter replacement programs through platform-integrated fulfillment provide differentiated go-to-market positioning against transactional competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates seeking to monetize non-core motor control and battery management competencies adjacent to handheld vacuum applications. Long-term viability centers on brands capturing recurring consumables revenue through connected unit telemetry and predictive maintenance scheduling. Monitor BIS certification backlog resolution velocity as inflection indicator for India's market accessibility improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Live Commerce Expansion | Shopee and Lazada streaming channels collapse distributor margins while enabling first-party data capture in Indonesia and Philippines. |
| Vietnam Manufacturing Footprint Relocation | Da Nang and Hai Phong industrial zones provide tariff-advantaged assembly capacity for ASEAN duty-free trade bloc access. |
| Connected Unit Telemetry Integration | Smart battery management systems digitize maintenance scheduling for hospitality fleet operators across Australia's Gold Coast. |
| Battery Pack Recycling Infrastructure Buildout | Extended producer responsibility laws in South Korea and Taiwan require reverse logistics capabilities most mid-tier brands currently lack. |
| HEPA Filtration Certification Investment | METI Top Runner efficiency benchmarking in Japan rewards superior dust separation performance per watt consumed. |
Research Methodology
Desk research of customs trade records, BIS certification filings, and METI efficiency benchmarking databases preceded structured interviews with product development directors at motor assembly specialists, procurement leads at hospitality fleet operators, channel managers at Shopee and Lazada, and regulatory affairs specialists navigating India's BIS timelines. Bottom-up unit shipment estimates triangulated against top-down category spending data from retail audit sources.
Assumptions around lithium-ion energy density improvement trajectories and brushless DC motor cost curves remained fixed across the projection horizon, while tariff regime variations and BIS enforcement timing were stress-tested. Segmentation dimensions modeled include product type, technology tier, end-user application intensity, and distribution channel structure. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and household formation projections, with co-working space penetration rates and live commerce adoption curves serving as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in residential construction permitting velocity, co-working space lease renewal rates, or rare earth magnet export licensing would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cutlery Market
Household Items
Dishwasher Tablets Market
Household Items
Home Use Air Purifiers Market
Household Items
Sanitary Metal Ware Market
Household Items
Toilet Paper Market
Household Items
Brush Cover Market
Household Items
United States Smart Shower Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Hands-Free Faucet Market
Household Items
Memory Foam Market
Household Items
Insulated Tumblers Market
Household Items
Smart Bath Heater Market
Household Items
Electric Air Freshener Market
Household Items
Folded Tissues Market
Household Items
Beach Towel Market