
 Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market | 2026-2036
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market Size, Share, and Industry Trends Forecast 2026-2036
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market Insights
Modular radome-integrated antenna assemblies is broadening buyer choice across defense and commercial procurement channels. Toray Advanced Composites leverages its carbon fiber prepreg dominance to supply lightweight radome skins for satellite ground terminals. Northrop Grumman anchors its position through captive manufacturing of ballistic-grade radomes for airborne radar platforms. Thales competes on electromagnetic transparency engineering, sustaining long-term contracts with European defense ministries.
Impact-resistant composite radome structures for high-bandwidth antennas are fiber-reinforced polymer shells, typically 2-15 mm thick, engineered to protect phased-array and parabolic antennas while maintaining dielectric constants below 4.0 across Ku-, Ka-, and Q-bands. These structures serve military surveillance, commercial satellite uplink, and 5G backhaul applications where signal integrity must survive hail, bird strike, and debris impact. Carbon fiber formulations lead the material segment due to stiffness-to-weight advantages in aerospace deployments, while fiberglass retains cost competitiveness for terrestrial telecommunications. Resin transfer molding dominates volume production for complex-curvature military radomes, though vacuum infusion gains traction among commercial operators seeking lower tooling investments for batch-scale wireless networking radomes.
The FAA mandates lightning protection and structural load certification under FAR Part 25 for airborne radome installations, while the FCC enforces radio frequency emission controls that dictate composite dielectric specifications. EASA's CS-25 airworthiness standards and the EU Green Deal's embodied-carbon tracking are reshaping material selection for European aerospace suppliers. Stakeholders must monitor evolving spectrum allocation rulings from national regulators and decide whether to qualify alternative resin systems before next-generation antenna architectures freeze design requirements.
Market Dynamics
The FAA's tightening electromagnetic interference standards for 5G-adjacent antenna installations are forcing composite radome manufacturers to reformulate dielectric materials and recertify product lines ahead of design freezes for next-generation radar platforms.
Growth Catalysts
- Defense procurement acceleration:United States defense contractors are expanding orders for advanced radome systems to equip next-generation airborne and naval radar platforms with impact-resistant protection.
- CS-25 airworthiness standards:EASA's evolving certification requirements for lightning protection and structural load are compelling European aerospace suppliers to upgrade composite formulations for satellite communication radomes.
- Terrestrial telecommunications deployment:5G backhaul infrastructure buildouts in Germany and surrounding markets are generating batch-scale demand for cost-optimized fiberglass radomes with standardized curvature profiles.
Market Restraints
- Carbon fiber supply concentration:Aerospace-grade carbon fiber prepreg production concentrates among a limited set of Japanese and American suppliers, creating input vulnerability for radome skin manufacturers.
- Resin system qualification timelines:FAA Part 25 and EASA CS-25 certification cycles for alternative resin formulations extend 18-36 months, freezing material innovation until design architectures stabilize.
- Metallic radome persistence:Certain military radar platforms continue specifying metallic nose radomes for extreme ballistic protection, limiting polymer composite penetration in high-threat airborne segments.
Strategic Opportunities
- Modular assembly architectures:Standardized radome-integrated antenna modules are opening procurement channels to mid-tier commercial satellite operators previously excluded from custom military supply chains.
- EU Green Deal embodied-carbon tracking:European aerospace clusters around Munich and Hamburg are incentivizing low-carbon composite formulations, creating first-mover advantage for bio-based resin developers.
- Vacuum infusion process adoption:Commercial wireless networking operators are adopting lower-tooling production methods for small-batch radome manufacturing, reducing capital barriers to entry.
Industry Challenges
- Electromagnetic transparency engineering talent:The specialized skill set combining dielectric material science with antenna performance optimization remains scarce across European and American engineering labor markets.
- Phased-array integration complexity:Next-generation active electronically scanned arrays require radome designs with variable thickness profiles and embedded heating elements, multiplying qualification test matrices.
- Multi-band certification burden:Simultaneous Ku-, Ka-, and Q-band operational requirements demand extensive anechoic chamber testing, compressing development timelines for product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market |
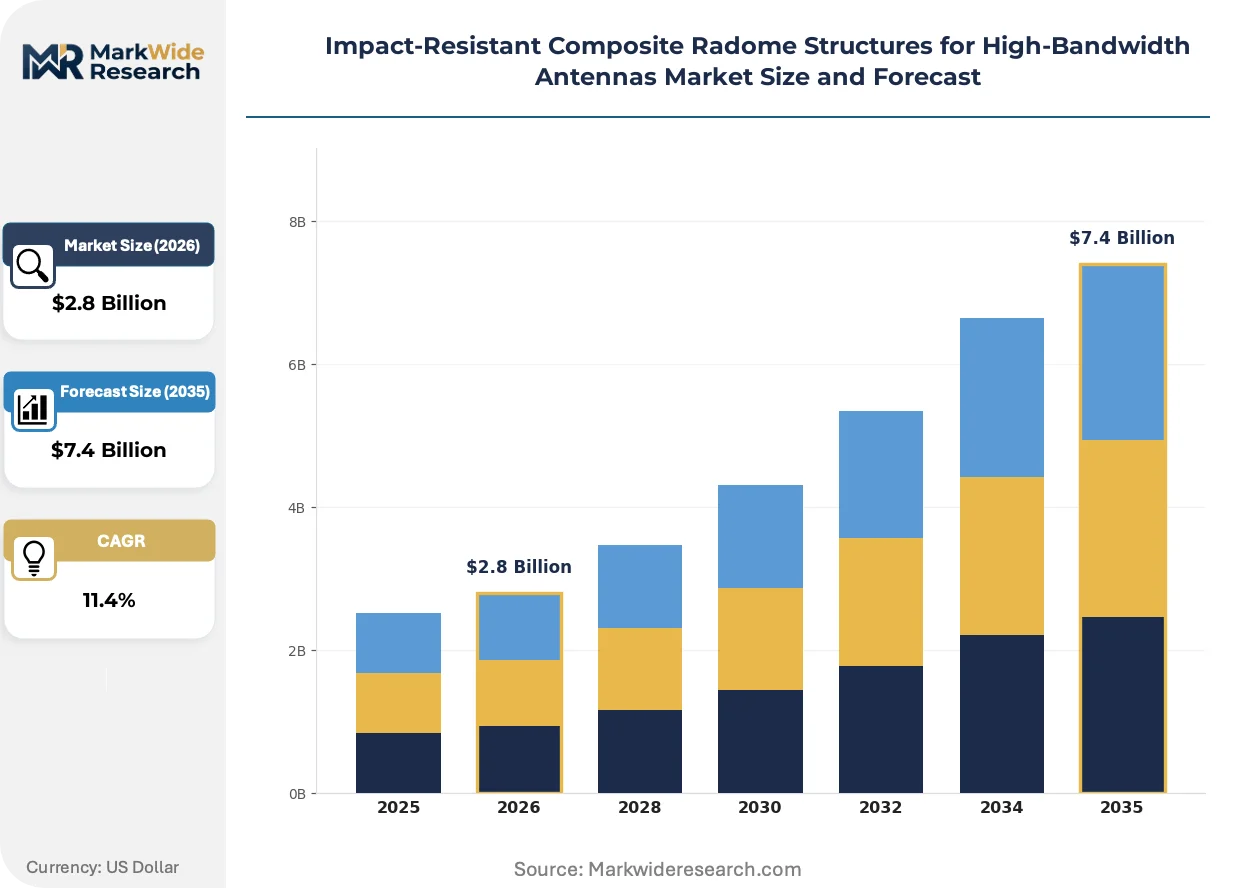
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fiberglass, Carbon Fiber, Aramid Fiber, Polyester Resin, Epoxy Resin, Vinyl Ester Technology: Pultrusion, Resin Transfer Molding, Vacuum Infusion, Compression Molding, Autoclave Processing Application: Satellite Communications, Radar Systems, Aerospace Surveillance, Telecommunications, Wireless Networking End User: Defense Contractors, Commercial Operators, Telecommunication Providers, Research Institutions |
| Companies Covered | Toray Advanced Composites, Northrop Grumman, Leonardo, Thales, General Dynamics Mission Systems, L3Harris Technologies, Honeywell International, Astronics, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market Trends and Innovations
Material-process convergence and regulatory recalibration are compressing traditional radome development cycles while opening new procurement pathways for specialized composite structures.
Multi-layer sandwich construction incorporating quartz fiber skins and syntactic foam cores is unifying ballistic protection with electromagnetic transparency in a single structural solution. Military airborne radar platform developers in the United States are specifying these configurations for next-generation surveillance aircraft. The technology is unifying previously separate radome and airframe structural functions, reducing overall antenna system mass and assembly complexity.
REACH substance restrictions and the EU Green Deal's embodied-carbon tracking requirements are reshaping material selection protocols for European aerospace suppliers. Manufacturers must now document cradle-to-gate carbon intensity for carbon fiber and resin systems used in satellite communication radomes. German aerospace clusters are responding by qualifying bio-epoxy alternatives and recycling pathways for production scrap.
Defense procurement officers are consolidating vendor relationships around full-system suppliers capable of delivering radome-integrated antenna assemblies rather than discrete components. This pattern compresses the traditional multi-vendor qualification process into single-source contracting for platform integrators. The shift is most visible in United States next-generation radar programs, where prime contractors now specify performance at the antenna-radome subsystem level.
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market Segmentation
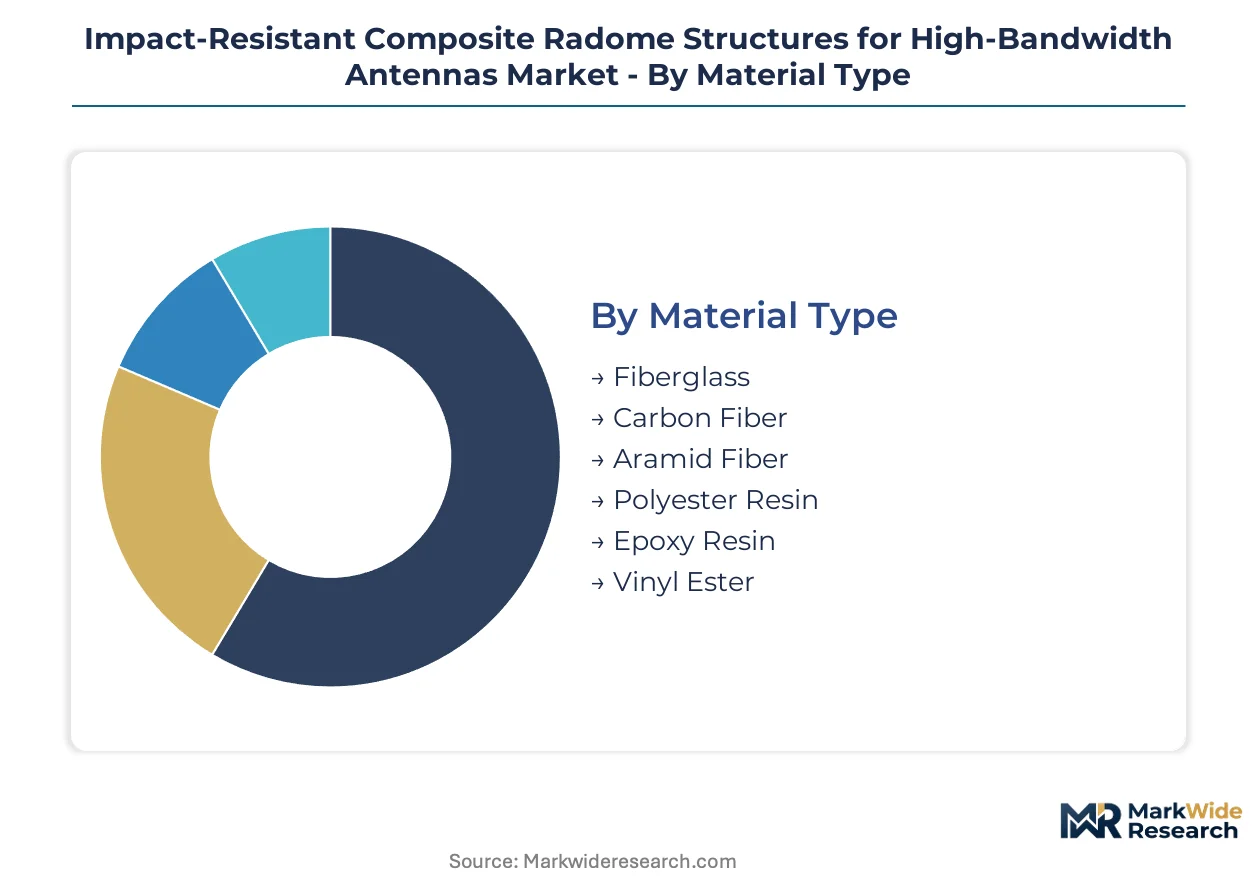
Segmentation in composite radome markets reveals distinct procurement pathways where material selection, manufacturing technology, and end-use requirements intersect. Defense contractors prioritize ballistic-grade carbon fiber formulations processed through autoclave methods, while commercial operators seek cost-optimized fiberglass alternatives using vacuum infusion. Understanding these divides enables suppliers to align certification investments with addressable demand pools.
Material Type:
Standalone radome skins operate as bolt-on protective shells for existing antenna installations, whereas embedded formulations integrate directly into airframe structures during platform assembly.
- Carbon Fiber:Aerospace-grade prepreg laminates deliver stiffness-to-weight ratios critical for airborne radar platforms. United States defense contractors specify Toray T800-grade formulations for next-generation surveillance aircraft where every kilogram determines fuel endurance. FAA Part 25 certification cycles for new carbon fiber radome designs extend 24-36 months, freezing supplier relationships once qualified.
- Fiberglass:E-glass and S-glass woven reinforcements retain dielectric stability across Ku- and Ka-band frequencies at substantially lower material costs than carbon alternatives. German telecommunications infrastructure buildouts around Munich and Hamburg are absorbing batch-scale fiberglass radome production for 5G backhaul towers where capital efficiency outweighs weight minimization.
- Aramid Fiber:Kevlar-based composites absorb impact energy through micro-fracture mechanisms without catastrophic failure, suiting naval radar installations exposed to debris and hail.
- Polyester Resin:Orthophthalic and isophthalic formulations serve cost-sensitive terrestrial applications where thermal performance requirements remain modest.
- Epoxy Resin:High-performance thermoset systems dominate aerospace-qualified radomes requiring glass transition temperatures above 180°C for supersonic flight envelopes.
- Vinyl Ester:Hybrid resin chemistry bridges polyester cost structures with epoxy-grade chemical resistance, finding niche adoption in marine radar housings.
Volume placements concentrate in fiberglass for terrestrial telecommunications; the faster expansion belongs to carbon fiber as airborne radar platforms multiply.
Technology:
Process selection tracks batch size and geometric complexity, with high-volume military programs tolerating capital-intensive tooling that commercial operators reject.
- Resin Transfer Molding:Closed-mold injection of catalyzed resin into pre-positioned fiber preforms enables complex-curvature radomes with repeatable wall thickness control. Northrop Grumman and Lockheed Martin suppliers rely on RTM for ballistic-grade airborne radomes where dimensional precision affects electromagnetic transparency. Tooling costs exceed $500,000 per mold cavity, restricting this method to programs with committed multi-year procurement volumes.
- Vacuum Infusion:Atmospheric pressure-driven resin distribution through dry fiber stacks eliminates matched-metal tooling requirements. Commercial satellite ground terminal manufacturers in Germany and the United States are adopting vacuum infusion for small-batch wireless networking radomes where design flexibility outweighs cycle time efficiency. Process qualification under EASA CS-25 remains incomplete, limiting aerospace applications.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies produces constant-cross-section profiles suited to linear antenna array housings rather than curved radome geometries.
- Compression Molding:Matched-die forming of sheet molding compound delivers high-volume throughput for standardized radome shapes in automotive-adjacent telecommunications equipment.
- Autoclave Processing:Elevated temperature and pressure consolidation of prepregs yields aerospace-grade laminates with void contents below 1%, mandatory for FAA Part 25 structural radome installations.
Capital deployment concentrates in autoclave and RTM infrastructure for defense programs; vacuum infusion is climbing the fastest among commercial entrants seeking lower barriers to production scale.
Application:
Application segmentation separates frequency-regulated domains where electromagnetic transparency engineering dominates from mechanically-driven use cases where impact resistance governs specification.
- Satellite Communications:Ground terminal radomes and airborne satcom housings require precise dielectric constant control across 12-18 GHz and 26.5-40 GHz bands. Thales and Airbus suppliers in European aerospace clusters are qualifying multi-layer quartz fiber syntactic foam cores that unify Ka-band transparency with bird-strike survivability. EASA CS-25 lightning protection mandates add 8-12 months to certification timelines for satellite communication radomes on commercial aircraft.
- Radar Systems:Active electronically scanned array protection demands variable-thickness radome profiles that minimize beam steering distortion. United States Navy and Air Force programs are consolidating procurement around full-system suppliers capable of integrating heating elements for de-icing and moisture elimination.
- Aerospace Surveillance:High-altitude long-endurance unmanned platforms specify radomes as primary structural elements, loading flight stresses through the antenna housing itself.
- Telecommunications:5G millimeter-wave small cell backhaul in German urban corridors uses standardized radome geometries where electromagnetic performance requirements relax relative to aerospace grades.
- Wireless Networking:Private LTE and industrial IoT infrastructure deploys cost-optimized radome solutions with minimal certification burden beyond FCC Part 15 emission controls.
Procurement volume concentrates in radar systems for defense modernization; satellite communications is gaining share fastest as commercial space constellations multiply ground terminal requirements.
End User:
End user categories diverge sharply on qualification tolerance, with defense contractors accepting 36-month development cycles that commercial operators reject as uncompetitive.
- Defense Contractors:Prime integrators including Northrop Grumman, Raytheon, and Thales specify radome-integrated antenna subsystems rather than discrete components. United States Department of Defense procurement officers are consolidating vendor relationships around full-system suppliers capable of delivering ballistic-grade protection with embedded electromagnetic transparency engineering. Multi-band qualification across X-, Ku-, Ka-, and Q-bands demands extensive anechoic chamber testing that excludes mid-tier competitors.
- Commercial Operators:Satellite service providers and aviation leasing companies procure radomes as aftermarket replacements or line-fit options on existing platforms. Lufthansa Technik and similar MRO specialists in Hamburg source radome repairs through qualified sub-tier suppliers rather than original equipment manufacturers.
- Telecommunication Providers:Deutsche Telekom and Verizon infrastructure divisions specify radomes for 5G backhaul towers where FCC electromagnetic interference standards dictate dielectric material selection.
- Research Institutions:National laboratories and university antenna test ranges purchase developmental radome prototypes in unit quantities for experimental phased-array architectures.
Contract value concentrates in defense contractor procurement; commercial operators are expanding fastest as satellite ground terminal markets democratize access to previously military-exclusive supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in aerospace clusters with deep defense procurement ties, while consumption spreads across commercial satellite ground terminals and 5G infrastructure. The United States and Germany dominate carbon fiber radome manufacturing, whereas telecommunications deployment drives absorption in urban corridors worldwide.
United States
Defense modernization programs and FAA Part 25 certification requirements anchor demand for ballistic-grade airborne radomes. The FAA mandates lightning protection and structural load certification that extends development cycles to 24-36 months. Aerospace manufacturing clusters in California and Texas concentrate prime contractor activity for next-generation radar platforms.
Germany
EASA CS-25 airworthiness standards and EU Green Deal embodied-carbon tracking reshape material selection for satellite communication radomes. Munich and Hamburg aerospace clusters specialize in multi-layer quartz fiber syntactic foam cores that unify Ka-band transparency with impact resistance. REACH substance restrictions accelerate bio-epoxy qualification timelines.
United Kingdom
Defense procurement through the Ministry of Defence sustains demand for radome-integrated antenna subsystems on airborne early warning platforms. UK Space Agency funding for satellite ground terminals expands commercial addressable market. Manufacturing concentrates around aerospace supply chains in the Midlands and Southwest England.
France
Thales anchors electromagnetic transparency engineering capabilities serving European defense ministries and commercial aviation. ANSM and DGAC regulations govern radome installations on civil aircraft registered in France. Toulouse and Paris aerospace clusters integrate radome production into broader antenna system supply chains.
Japan
METI industrial policy supports carbon fiber prepreg supply security for aerospace applications. Toray Advanced Composites leverages domestic carbon fiber dominance to supply lightweight radome skins for satellite ground terminals. Manufacturing concentrates in the Chubu region around Nagoya aerospace infrastructure.
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market Competitive Landscape
The competitive structure tilts toward vertically integrated defense primes with captive manufacturing capabilities. Tier-one suppliers combine electromagnetic transparency engineering with ballistic protection certification, while mid-tier commercial specialists compete on vacuum infusion process efficiency. Two archetypes dominate: full-system integrators delivering radome-integrated antenna assemblies, and material-focused suppliers of qualified prepreg formulations. Consolidation moves center on defense procurement channel capture and geographic expansion into German telecommunications infrastructure markets.
Among defense prime contractors, Northrop Grumman and Thales exemplify the full-system integrator archetype, anchoring positions through long-term relationships with United States Department of Defense and European defense ministries respectively. Toray Advanced Composites occupies a distinct position as a material supplier leveraging carbon fiber prepreg dominance to serve both aerospace and commercial satellite terminal manufacturers. These three entities represent the span from upstream material control through downstream subsystem integration.
| Leading Market Players |
|---|
| Toray Advanced Composites |
| Northrop Grumman |
| Leonardo |
| Thales |
| General Dynamics Mission Systems |
| L3Harris Technologies |
| Honeywell International |
| Astronics |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Captive manufacturing by defense primes anchors supply positions and pricing power for ballistic-grade radome systems, while commercial operators rely on outsourced vacuum infusion specialists who compete on batch-scale efficiency rather than certification barriers. This bifurcation concentrates margin capture among vertically integrated aerospace suppliers serving United States Department of Defense programs, leaving price-taker dynamics for fiberglass radome producers supplying German telecommunications infrastructure.
Pricing Analysis
Cost-down pressure on commercial fiberglass radomes accelerates because Deutsche Telekom and Verizon infrastructure divisions are consolidating vendor panels for 5G backhaul deployments. Three-tier pricing structure across FAA-certified aerospace, EASA-qualified commercial aviation, and uncertified terrestrial telecommunications segments reflects qualification investment recovery timelines. Aerospace-grade carbon fiber radomes command sustained premiums due to 24-36 month FAA Part 25 certification cycles that freeze supplier relationships. Telecommunications providers exhibit highest price sensitivity, accepting standardized curvature profiles in exchange for per-unit cost minimization.
Supply Chain Analysis
Direct-to-OEM channels handle defense contractor demand for radome-integrated antenna subsystems, while distributor-mediated supply serves commercial satellite ground terminal operators. Raw material sourcing draws from Japanese carbon fiber prepreg suppliers, German quartz fiber specialists, and American epoxy resin formulators. Aerospace-grade carbon fiber production concentrates among Toray and Hexcel facilities, creating single-source vulnerability for radome skin manufacturers. Distribution runs through qualified sub-tier suppliers in Hamburg and Munich aerospace clusters for European commercial aviation aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-system integrators as defense procurement officers abandon multi-vendor qualification processes, forcing component specialists to merge or exit.
For Market Incumbents: Extend electromagnetic transparency engineering capabilities into adjacent satellite ground terminal markets before vacuum infusion specialists capture commercial volume. Lock in long-term carbon fiber prepreg supply agreements with Toray to defend against input concentration risk. Acquire vacuum infusion process specialists in Germany to secure telecommunications infrastructure channels. For New Entrants and Emerging Players: Capture batch-scale wireless networking radome production for private LTE and industrial IoT infrastructure where FCC Part 15 emission controls impose minimal certification burden. Target German 5G backhaul tower installations around Munich and Hamburg where capital efficiency outweighs brand loyalty. Enter through vacuum infusion process qualification rather than autoclave infrastructure investment. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime contractor acquisition of electromagnetic transparency engineering boutiques. Long-term viability favors suppliers with dual-use capabilities spanning aerospace certification and commercial process efficiency. Watch for FAA spectrum allocation rulings as inflection indicator for next-generation antenna architecture design freezes.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Investment in Alternative Resin Systems | Bio-epoxy formulations aligned with EU Green Deal embodied-carbon tracking secure European aerospace contracts. |
| Backward Integration into Carbon Fiber Prepreg Supply | Captive T800-grade material control insulates Northrop Grumman against Japanese supplier concentration. |
| Vacuum Infusion Process Scale-Up | Lower-tooling production methods enable German mid-tier entrants to serve commercial satellite operators. |
| Multi-Band Anechoic Chamber Certification | Simultaneous Ku-, Ka-, and Q-band qualification excludes competitors from United States radar programs. |
| Modular Radome-Antenna Assembly Integration | Single-source contracting preference by defense primes compresses traditional multi-vendor procurement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with radome engineering directors, defense procurement officers, EASA certification specialists, composite materials procurement leads, and telecommunications infrastructure planners. FAA Part 25 certification databases, EASA CS-25 airworthiness directives, FCC electromagnetic interference rulings, and EU REACH substance restriction notices provided regulatory boundary conditions. Bottom-up demand modeling across material type, manufacturing technology, and application segments triangulated against top-down aerospace and telecommunications capital expenditure trends.
Segment-level granularity tracked carbon fiber, fiberglass, and aramid fiber formulations separately by resin system chemistry, with manufacturing technology disaggregated across autoclave, RTM, and vacuum infusion process economics. Application modeling distinguished satellite communications, radar systems, and telecommunications infrastructure by electromagnetic performance requirements and certification burden. CAGRs derived from volume-weighted average growth across defense modernization cycles and commercial space constellation deployment schedules. Forecast inputs incorporated FAA spectrum allocation timelines and EU Green Deal embodied-carbon compliance trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to defense budget appropriation volatility and next-generation antenna architecture standardization. Forecasts reflect documented assumptions regarding certification cycle durations and raw material supply concentration. Periodic stress-testing of base assumptions is recommended against evolving electromagnetic interference standards and alternative resin system qualification progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aircraft Exterior Structure Digital Twin Platforms Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Aircraft Insulation Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Europe Drone Motor Market