
 Naval Combat Systems Market | 2026-2036
Naval Combat Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Combat Systems Market Outlook
Buyer concentration among Western naval services is shifting toward multi-year fleet modernization programs that bundle sensors, weapons, and network infrastructure into single awards. BAE Systems plc anchors British and Australian surface combatant programs through sustained investment in integrated mission systems. Lockheed Martin Corporation dominates Aegis combat system integration for the U.S. Navy and allied destroyer fleets. Thales Group competes across European frigate programs with specialized sonar and radar offerings.
Naval combat systems encompass the integrated sensor, weapon, command, and communication architectures that enable surface vessels and submarines to detect, track, engage, and assess threats across electromagnetic and acoustic domains, typically operating in saltwater environments with shock-hardened electronics rated to MIL-STD-901D. These systems serve the primary purpose of delivering decisive tactical advantage through fused situational awareness and coordinated weapons employment. Weapons systems and command and control systems occupy the largest margin pools due to long development cycles and sovereign security restrictions that limit vendor substitution. Surveillance systems leveraging radar technology and sonar systems represent the fastest-expanding technology layer as navies prioritize undersea domain awareness against quiet diesel-electric submarines.
Procurement authorities in the United States operate under NIST cybersecurity frameworks and DoD 5000 acquisition regulations that mandate zero-trust architectures for all networked combat systems. European programs face REACH chemical restrictions on submarine battery materials alongside CE marking requirements for commercial-off-the-shelf subcomponents integrated into military platforms. India's Ministry of Defence applies BIS standards and phased manufacturing requirements through the PLI scheme to compel domestic production of combat system electronics. Stakeholders must monitor how evolving electromagnetic spectrum allocation rules and export control revisions affect cross-border subsystem integration timelines.
Market Dynamics
Integrated command architectures are compressing procurement timelines as naval forces abandon siloed sensor upgrades in favor of unified combat management platforms that fuse electromagnetic and acoustic domains into single vendor relationships.
Growth Catalysts
- DoD 5000 acquisition reforms:The United States mandates zero-trust network architectures for all naval combat systems, accelerating replacement of legacy point-to-point data links with hardened mesh topologies across destroyer and submarine fleets.
- Quiet diesel-electric submarine proliferation:China's expanding undersea fleet and Iranian Kilo-class acquisitions are forcing Western navies to prioritize sonar system modernization and undersea domain awareness investments.
- NATO interoperability mandates:Allied surface combatant programs now require common data link standards and shared electromagnetic warfare protocols, bundling cross-border procurement into multi-year framework agreements.
Market Restraints
- Gallium nitride foundry concentration:Advanced radar transmitter production depends on three qualified semiconductor fabrication facilities in the United States and Japan, creating single-source vulnerability for next-generation active electronically scanned arrays.
- REACH chemical restrictions:European submarine battery procurement faces constrained supply of nickel-metal hydride electrolyte formulations as ECHA registration requirements eliminate non-compliant Asian suppliers from qualified vendor lists.
- Legacy analog sonar incompatibility:Existing hull-mounted arrays on Cold War-era frigates cannot interface with digital beamforming processors without complete transducer replacement, extending refit timelines.
Strategic Opportunities
- Indian PLI scheme localization:India's phased manufacturing requirements for combat system electronics create captive demand for foreign subsystem vendors establishing joint ventures with Bharat Electronics and Data Patterns.
- AI-enabled predictive maintenance:Machine learning algorithms applied to vibration and thermal sensor data from gas turbine generator sets are enabling condition-based overhaul scheduling that compresses lifecycle support costs.
- Commercial LEO constellation integration:Low Earth orbit broadband providers are negotiating military service level agreements that would offload beyond-line-of-sight communications from dedicated military satellites to commercial infrastructure.
Industry Challenges
- Systems engineering talent scarcity:The specialized skill set integrating radar, electronic warfare, and fire control software into real-time operating environments concentrates among defense contractors with security clearance pipelines, constraining workforce expansion.
- MIL-STD-901D shock certification delays:New electronics enclosures for submarine applications face 18-24 month qualification timelines at Navy-qualified test facilities, compressing program schedules regardless of design maturity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Combat Systems Market |
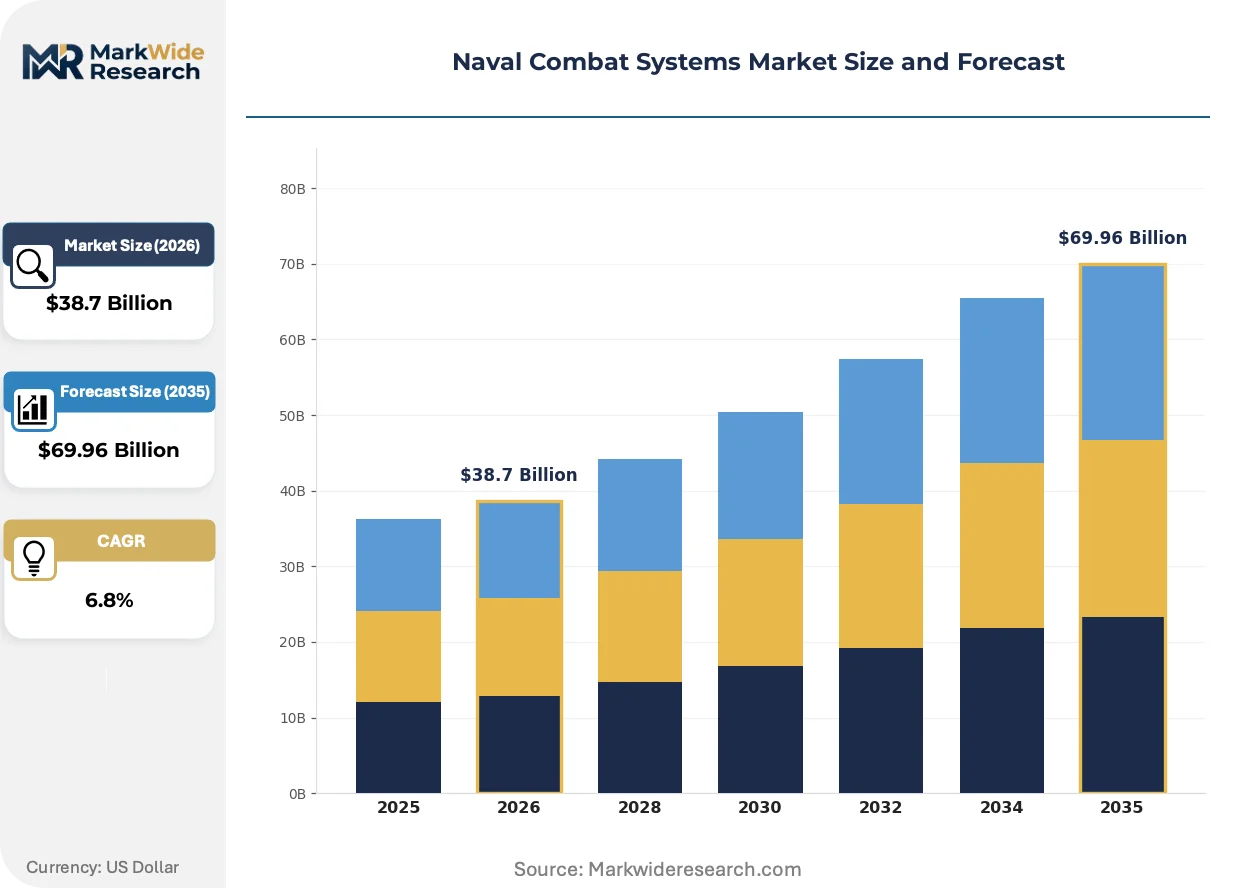
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weapons Systems, Surveillance Systems, Communication Systems, Command and Control Systems End User: Navies, Defense Contractors, Government Agencies, Military Alliances Technology: Electromagnetic Warfare, Cybersecurity Solutions, Radar Technology, Sonar Systems Application: Coastal Defense, Anti-Submarine Warfare, Naval Operations, Force Protection |
| Companies Covered | BAE Systems plc, Northrop Grumman Corporation, Lockheed Martin Corporation, Saab AB, L3Harris Technologies Inc, Raytheon Technologies Corporation, General Dynamics Corporation, Kongsberg Gruppen AS, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Combat Systems Market Strategic Shifts
Electromagnetic spectrum warfare capabilities are displacing kinetic weapons as the primary competitive differentiator in surface combatant design, with software-defined radio architectures enabling rapid reprogramming against evolving threat signatures.
Conformal phased array radar is overtaking rotating mechanically scanned systems as the dominant approach to surface ship air defense. These flush-mounted antenna arrays eliminate deck penetration and topside weight while enabling simultaneous multi-target tracking. The United States Navy and Royal Navy are mandating conformal configurations for next-generation frigate programs. This technology is compressing radar cross-section and enabling distributed aperture concepts that treat the entire hull as a sensor surface.
EU AI Act risk classification rules are redefining autonomous weapon system development pathways for European naval programs. High-risk algorithmic decision support now requires conformity assessment procedures and human oversight documentation before operational deployment. French and German submarine combat system integrators are restructuring software development workflows to segregate AI-enabled target classification modules from legacy rule-based engagement authorities.
Fleet-wide availability contracts are displacing transactional spare parts purchasing for integrated combat system suites. Royal Australian Navy and Royal Canadian Navy surface combatant programs now specify contractor logistics support encompassing training, technical documentation, and obsolescence management across 25-year service lives. This model concentrates vendor accountability but requires sophisticated performance metric definition to align commercial incentives with operational readiness requirements.
Naval Combat Systems Market Segmentation
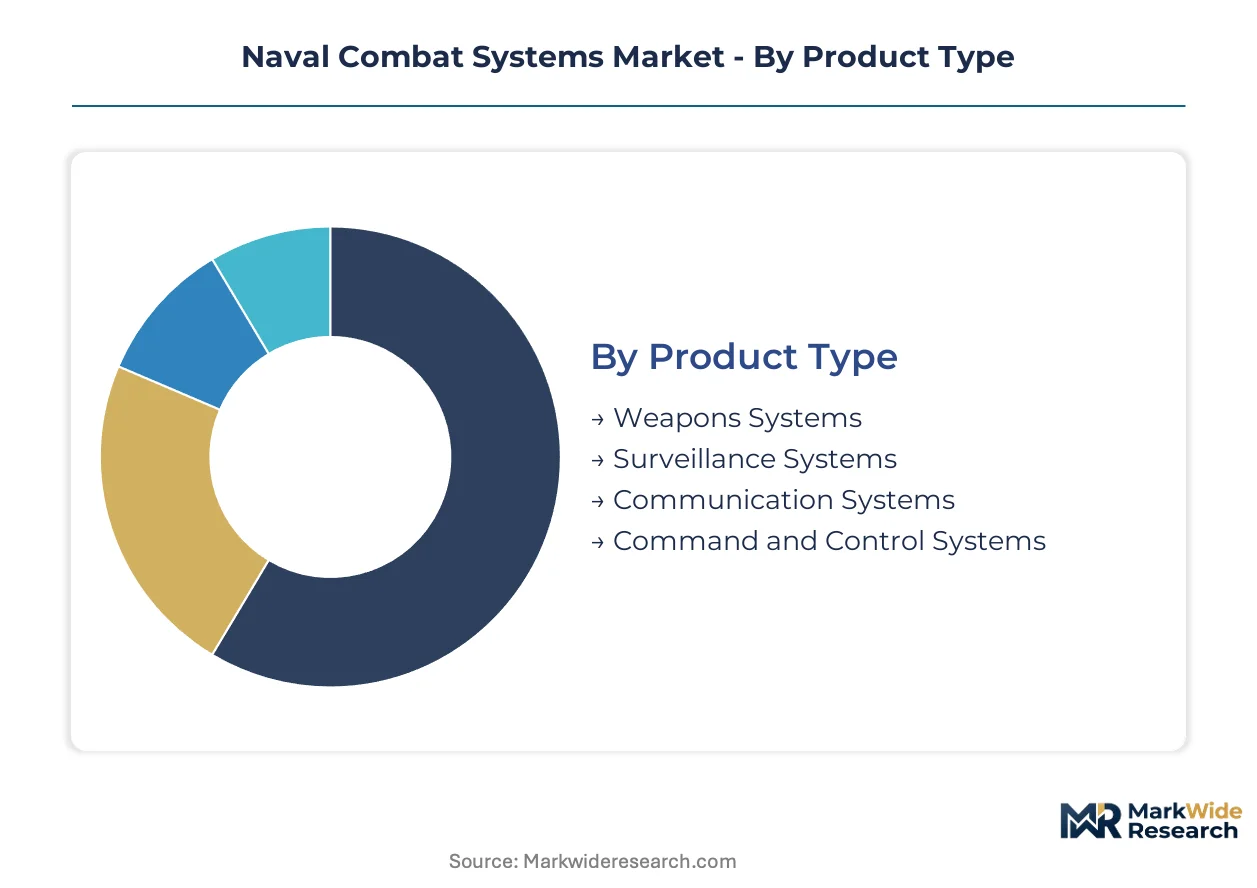
Segmentation in naval combat systems reveals how procurement authority, threat environment, and platform architecture reshape vendor relationships. Buyers prioritize integrated suites over point solutions, compressing supplier bases around systems integrators capable of fusing multiple technology layers.
Product Type:
Cost tier differentiation separates sovereign-proprietary development from commercial-off-the-shelf integration pathways.
- Weapons Systems:Missile launchers, torpedo tubes, and directed energy platforms require MIL-STD-901D shock certification and sovereign security clearances. United States Navy destroyer programs bundle vertical launch systems with fire control software into single-source contracts with Lockheed Martin. Volume sits with weapons systems; growth tilts toward command and control systems.
- Surveillance Systems:Hull-mounted and towed sensor arrays integrate radar, electro-optical, and electronic support measures into unified detection fabrics. Royal Navy Type 26 frigate procurement mandates conformal phased array radar configurations that eliminate rotating antenna mechanics. Australian surface combatant programs drive demand for over-the-horizon targeting capabilities.
- Communication Systems:Satellite terminals, tactical data links, and underwater acoustic networks enable distributed fleet coordination. NATO interoperability standards now mandate common Link-16 and Link-22 protocols across allied procurement.
- Command and Control Systems:Combat management computers fuse sensor inputs into engagement decisions through real-time operating systems. Indian Navy modernization applies BIS standards to compel domestic software integration.
Margin concentration follows development cycle length, with weapons and command architectures capturing value through multi-decade platform lock-in.
End User:
Application maturity varies sharply between operational fleets and developmental consortiums.
- Navies:Surface fleet and submarine commands specify integrated combat system suites through multi-year framework agreements. United States, United Kingdom, and India anchor procurement volume with concurrent destroyer, frigate, and submarine programs. Volume sits with navies; growth tilts toward military alliances.
- Defense Contractors:Prime integrators subcontract sensor and weapon modules from tiered supplier bases while retaining systems engineering accountability. BAE Systems, Thales Group, and Lockheed Martin structure vendor relationships around security-cleared manufacturing facilities.
- Government Agencies:Research laboratories and test ranges qualify subsystem performance against operational requirements before fleet integration. Defense Advanced Research Projects Agency funding accelerates electromagnetic warfare prototyping.
- Military Alliances:NATO and AUKUS framework agreements bundle cross-border procurement into shared technical standards and pooled development costs. Interoperability mandates reshape competitive positioning toward vendors with multi-national security clearances.
Procurement authority is concentrating among alliance structures that distribute development burden across member state budgets.
Technology:
Supply concentration in semiconductor fabrication and rare earth processing constrains technology deployment timelines.
- Electromagnetic Warfare:Software-defined radio architectures enable rapid reprogramming against evolving threat signatures without hardware replacement. Gallium nitride transmitter foundries in the United States and Japan limit active electronically scanned array production capacity. Volume sits with radar technology; growth tilts toward cybersecurity solutions.
- Cybersecurity Solutions:Zero-trust network architectures segment combat system data flows to contain intrusions. DoD 5000 acquisition reforms mandate NIST framework compliance for all networked naval platforms.
- Radar Technology:Conformal phased arrays displace mechanically scanned systems by distributing aperture across hull surfaces. Royal Navy and United States Navy next-generation frigate programs mandate flush-mounted configurations.
- Sonar Systems:Digital beamforming processors and towed array technologies address quiet diesel-electric submarine proliferation in the Pacific and Middle East. Hull-mounted analog arrays on legacy frigates require complete transducer replacement for compatibility.
Technology substitution accelerates where digital architectures displace analog predecessors.
Application:
Geography and threat environment reshape capability prioritization across fleet segments.
- Coastal Defense:Littoral combat platforms and shore-based missile batteries protect harbors and maritime economic zones. Indian and Iranian procurement emphasizes fast attack craft with integrated anti-ship missiles.
- Anti-Submarine Warfare:Undersea domain awareness investments concentrate in the Pacific against Chinese submarine fleet expansion. Sonar modernization and unmanned underwater vehicle deployment dominate Western navy programs.
- Naval Operations:Blue-water fleet projection requires integrated air defense, surface warfare, and strike capabilities across carrier strike groups. United States Navy distributed maritime operations concepts drive networking requirements.
- Force Protection:Close-in weapon systems and electronic countermeasures defend high-value units against asymmetric threats. Strait of Hormuz patrol operations emphasize layered defense against small boat swarms.
Capability gaps in undersea detection are redirecting investment toward anti-submarine warfare applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride foundry capacity in the United States and Japan anchors semiconductor supply for active electronically scanned arrays, while submarine battery chemical processing concentrates in European and Asian industrial corridors.
United States
Destroyer modernization and Aegis combat system upgrades drive procurement volume through 2035. DoD 5000 acquisition reforms mandate zero-trust network architectures for all naval platforms. Norfolk and San Diego naval clusters concentrate shipyard maintenance and combat system integration activity.
United Kingdom
Type 26 frigate production and Dreadnought submarine programs sustain multi-year framework agreements. Ministry of Defence procurement operates under UK Strategic Defence Review timelines and NATO interoperability mandates. Glasgow shipyards and Portsmouth naval base anchor surface combatant construction and fleet maintenance operations.
India
Indigenous aircraft carrier follow-on programs and Scorpene submarine fleet expansion create sustained demand. Ministry of Defence applies PLI scheme phased manufacturing requirements to compel domestic electronics production. Mumbai and Visakhapatnam naval dockyards concentrate combat system integration and hull construction capacity.
Germany
212CD submarine development for Norway and Germany drives sonar system modernization investments. ECHA REACH chemical restrictions constrain nickel-metal hydride battery electrolyte sourcing for undersea platforms. Kiel and Eckernförde naval facilities anchor submarine construction and acoustic testing infrastructure.
Japan
Mogami-class frigate serial production and Aegis system destroyer upgrades sustain combat system demand. METI industrial policy coordinates gallium nitride foundry capacity expansion for radar transmitter production. Yokosuka and Sasebo naval districts concentrate surface fleet maintenance and integrated mission system installation.
Naval Combat Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cybersecurity and artificial intelligence integration pathways. The vendor structure concentrates around systems integrators with sovereign security clearances and multi-decade platform relationships. Three archetypes dominate: defense conglomerates with full-spectrum combat system portfolios, specialized sensor and electronic warfare houses, and national champions serving single-country naval programs. Competitive dynamics center on multi-year fleet availability contracts and cross-border alliance framework agreements.
Among defense conglomerates with integrated mission system capabilities, BAE Systems plc, Lockheed Martin Corporation, and Thales Group exemplify the tier-one archetype. These entities occupy positions spanning surface combatant and submarine combat management integration, with relationships structured around multi-decade platform support obligations. Their market presence reflects sustained investment in security-cleared manufacturing infrastructure and sovereign defense industrial base maintenance requirements.
| Leading Market Players |
|---|
| BAE Systems plc |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Saab AB |
| L3Harris Technologies Inc |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| Kongsberg Gruppen AS |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed defense conglomerates with multi-decade platform relationships anchor pricing discipline across naval combat systems, compressing margins for commercial-off-the-shelf subsystem vendors while extracting premium terms from foreign buyers lacking domestic integration capabilities. Their captive access to security-cleared manufacturing infrastructure and MIL-STD-901D shock certification pipelines creates asymmetric bargaining power that flows through to procurement contract structures.
Pricing Analysis
Volume concentrates in weapons systems and command architectures; margins concentrate in sovereign-proprietary development pathways with multi-decade lock-in. Pricing stratifies across sovereign-integrated, alliance-certified, and commercial-subsystem tiers, with differentiation driven by security clearance depth and shock-hardening certification level. Cost compression in commercial sensor modules is intensifying because gallium nitride foundry capacity constraints force buyers toward sole-source negotiations. Foreign navies without domestic integration capabilities exhibit highest price sensitivity; United States Navy programs with Aegis combat system standardization show lowest sensitivity due to platform continuity requirements.
Supply Chain Analysis
Direct-to-naval-authority channels handle fleet-wide availability contracts, bypassing traditional distribution intermediaries. Semiconductor fabrication concentrates in the United States and Japan for gallium nitride transmitter production; submarine battery chemical processing rests on European and Asian industrial corridors for nickel-metal hydride electrolyte formulations. Raw material dependencies span rare earth elements for radar magnets, high-purity gallium for active electronically scanned arrays, and specialized nickel alloys for hull-mounted sonar transducers. Single-source vulnerability in qualified foundry capacity poses structural supply chain risk. Distribution runs through prime integrator relationships with sovereign security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is accelerating as NATO interoperability mandates and zero-trust cybersecurity requirements force smaller subsystem vendors into acquisition by tier-one integrators capable of spanning multi-domain certification pipelines.
For Market Incumbents: Deploy fleet-wide availability contracting to deepen platform lock-in across 25-year service life commitments, capturing lifecycle support revenue streams that transactional spare parts purchasing cannot match. Acquire specialized sonar and electromagnetic warfare boutiques in Germany and Japan to secure gallium nitride foundry adjacencies and ECHA-compliant battery supply chains. This counters emerging AI-enabled predictive maintenance entrants seeking to displace traditional overhaul scheduling. For New Entrants and Emerging Players: Launch via cybersecurity subsystem integration into Indian Navy modernization programs, exploiting PLI scheme localization requirements that compel joint ventures with Bharat Electronics and Data Patterns. Target underpenetrated anti-submarine warfare applications in Pacific littoral zones where quiet diesel-electric submarine proliferation outpaces Western sonar modernization budgets. Position through commercial LEO constellation military service level agreements as an alternative to dedicated satellite infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier sensor specialists with ECHA REACH-compliant chemical processing capabilities in European submarine battery corridors. Long-term viability hinges on positioning within AUKUS or NATO framework agreement supply chains rather than single-nation procurement. Watch for electromagnetic spectrum allocation rule revisions as inflection indicators for cross-border subsystem integration timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Integration | DoD 5000 compliance mandates reshape competitive positioning toward NIST-certified vendors. |
| Conformal Phased Array Deployment | Royal Navy and United States Navy frigate programs eliminate rotating antenna mechanics entirely. |
| AI-Enabled Predictive Maintenance | Machine learning algorithms applied to gas turbine vibration data compress lifecycle support costs. |
| PLI Scheme Joint Venture Formation | India's phased manufacturing requirements compel foreign subsystem vendors toward domestic partnerships. |
| Gallium Nitride Foundry Capacity Expansion | METI-coordinated investments in Japan anchor active electronically scanned array transmitter supply. |
Study Parameters
Multi-period observation of naval procurement award patterns, subsystem integration timelines, and certification pipeline backlogs anchored the trend analysis, supplemented by interviews with combat system program managers, security-cleared manufacturing facility directors, naval shipyard procurement officers, and electromagnetic warfare R&D leads. Secondary validation drew from SEC 10-K filings of defense conglomerates, DoD contract announcement databases, NATO standardization agreement repositories, and ECHA chemical registration disclosures. Bottom-up segment sizing triangulated against top-down fleet modernization budget allocations.
Segment-weighting applied product type, end user, technology layer, and application mission profiles across the modeling period, with CAGRs derived from regression analysis of historical award values against projected hull construction schedules. Forecast inputs incorporated gallium nitride foundry capacity expansion timelines, submarine battery chemistry regulatory pathways, and alliance framework agreement negotiation statuses.
The model assumes a particular technology adoption path; alternative pathways for software-defined radio architectures or autonomous weapon system human oversight requirements would alter the outlook. Forecasts reflect base-case assumptions regarding NATO interoperability mandate implementation pace and Indian PLI scheme enforcement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Combat Management System Market
Naval Warfare
Sea Based C4ISR Market
Naval Warfare
Littoral Warship Market