
 Natural Food Colors Market | 2026-2036
Natural Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food Colors Market Intelligence
Non-GMO Project Verified certification is bifurcating the competitive landscape for natural food color suppliers. GNT Group B.V. specializes in vertically integrated color solutions derived from edible fruits and vegetables. Sensient Technologies Corporation leverages its global manufacturing footprint to offer a broad portfolio of natural colors and conversion services. Oterra A/S competes on its extensive R&D in color stability and application-specific formulations for dairy and beverages.
Natural food colors are pigments derived from sources like vegetables, fruits, and minerals, used to impart or restore color in food products. Their production involves extraction processes like solvent extraction or pressing, followed by purification and concentration to achieve specific hue and stability characteristics. Carotenoids, sourced from carrots and tomatoes, represent a dominant product type due to their stability in bakery and snack applications. Demand for anthocyanins, sourced from berries and purple corn, is accelerating within the beverage segment for their vibrant red, purple, and blue shades.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) strictly define permissible sources and purity levels. In China, GB standards govern additive approvals, influencing market access for international suppliers. Ingredient suppliers must now decide between investing in microencapsulation for higher stability or focusing on cost optimization for high-volume colorants.
Market Dynamics
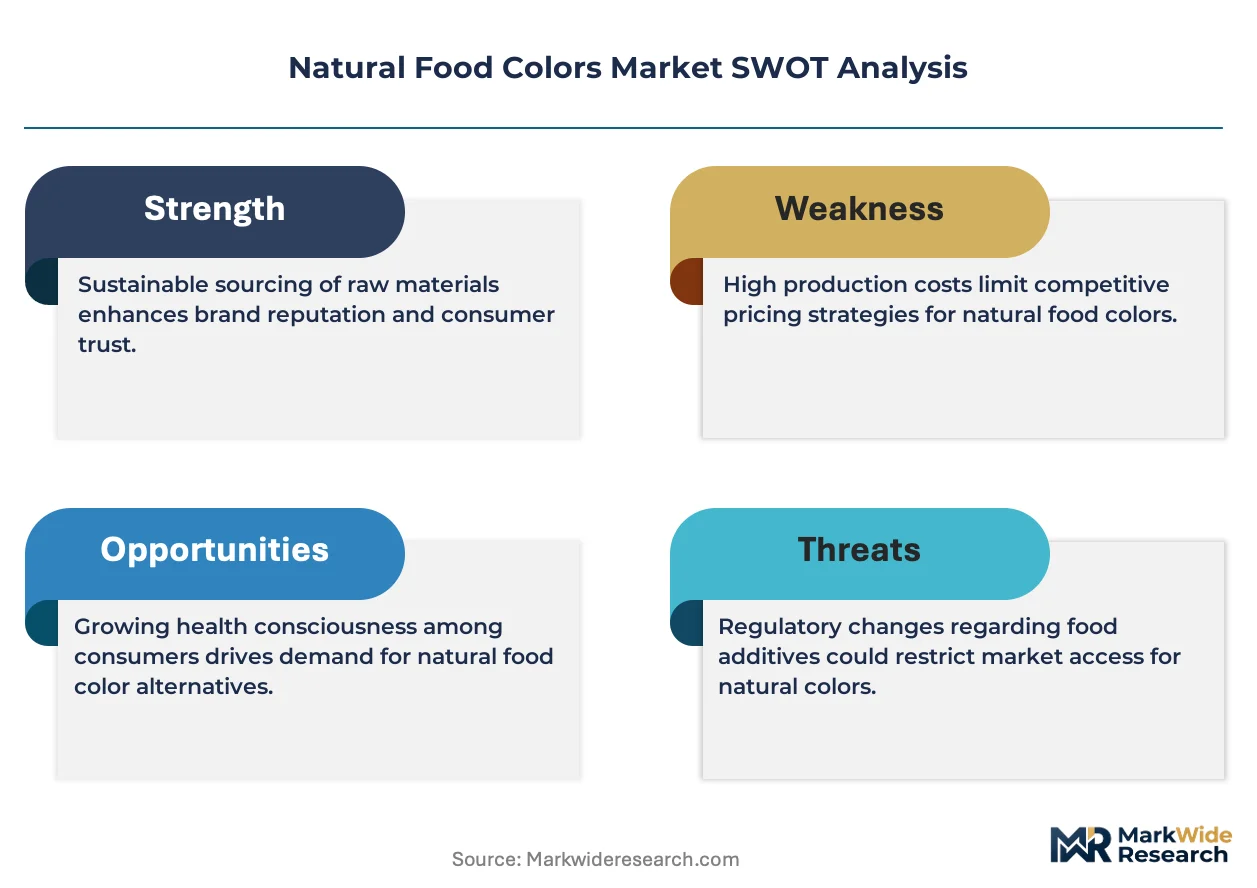
The fundamental dynamic shaping the natural food colors market is the non-negotiable consumer and regulatory push for 'clean labels'. This pressure for ingredient transparency is compelling food and beverage manufacturers to actively reformulate products, replacing synthetic dyes with plant-derived alternatives.
Growth Catalysts
- Regulatory Mandates:Stricter food safety frameworks, such as those from the European Food Safety Authority (EFSA), are limiting the use of certain synthetic colors and creating a direct regulatory tailwind for natural alternatives across the food industry.
- Beverage Sector Reformulation:Demand from beverage manufacturers is a primary catalyst as they seek vibrant, stable natural colors like anthocyanins to replace synthetic options in juices, carbonated drinks, and flavored waters, responding to consumer health perceptions.
- High-Stability Color Demand:Food innovation hubs, particularly in countries like Germany, are concentrating demand for advanced, high-stability natural colors that can withstand harsh processing conditions in novel food product development.
Market Restraints
- Cost Disparity:The higher cost of raw material sourcing and complex extraction for natural colors compared to chemically synthesized dyes creates a significant price barrier, particularly for manufacturers in price-sensitive, high-volume food categories.
- Technical Instability:Natural pigments often exhibit lower stability when exposed to heat, light, or pH changes during processing and shelf life, posing a technical restraint for applications requiring long-term color consistency without specialized formulation.
- Agricultural Supply Volatility:Supply of raw materials like specific fruits and vegetables is subject to seasonality, weather events, and crop diseases, leading to potential price fluctuations and sourcing inconsistencies for color manufacturers.
Strategic Opportunities
- Encapsulation Technologies:Investing in microencapsulation and other stabilization technologies presents a major opportunity. These processes protect fragile colorants, expanding their use into challenging applications like baked goods and extending product shelf life.
- Plant-Based Meat Coloring:The expanding plant-based food sector provides a significant opportunity for colors that can mimic the appearance of traditional meat, such as beet and paprika extracts, creating a more appealing consumer product.
- Untapped Asian Markets:As clean-label consciousness grows in Southeast Asian economies, a strategic opportunity exists for suppliers to introduce natural color solutions tailored to local cuisines and regulatory environments, which are currently underpenetrated.
Industry Challenges
- Navigating Global Regulations:A primary operational challenge is managing the complex and divergent approval processes and purity standards for food additives set by bodies like the U.S. FDA, EFSA, and China's GB standards.
- Color Standardization:Achieving consistent batch-to-batch color expression from naturally variable agricultural sources requires sophisticated quality control and blending processes, posing a continuous challenge for ingredient suppliers.
- Capital-Intensive Processing:The extraction, purification, and concentration of natural colors require substantial capital investment in specialized equipment, creating a high barrier to entry and challenging the return on investment for smaller players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food Colors Market |
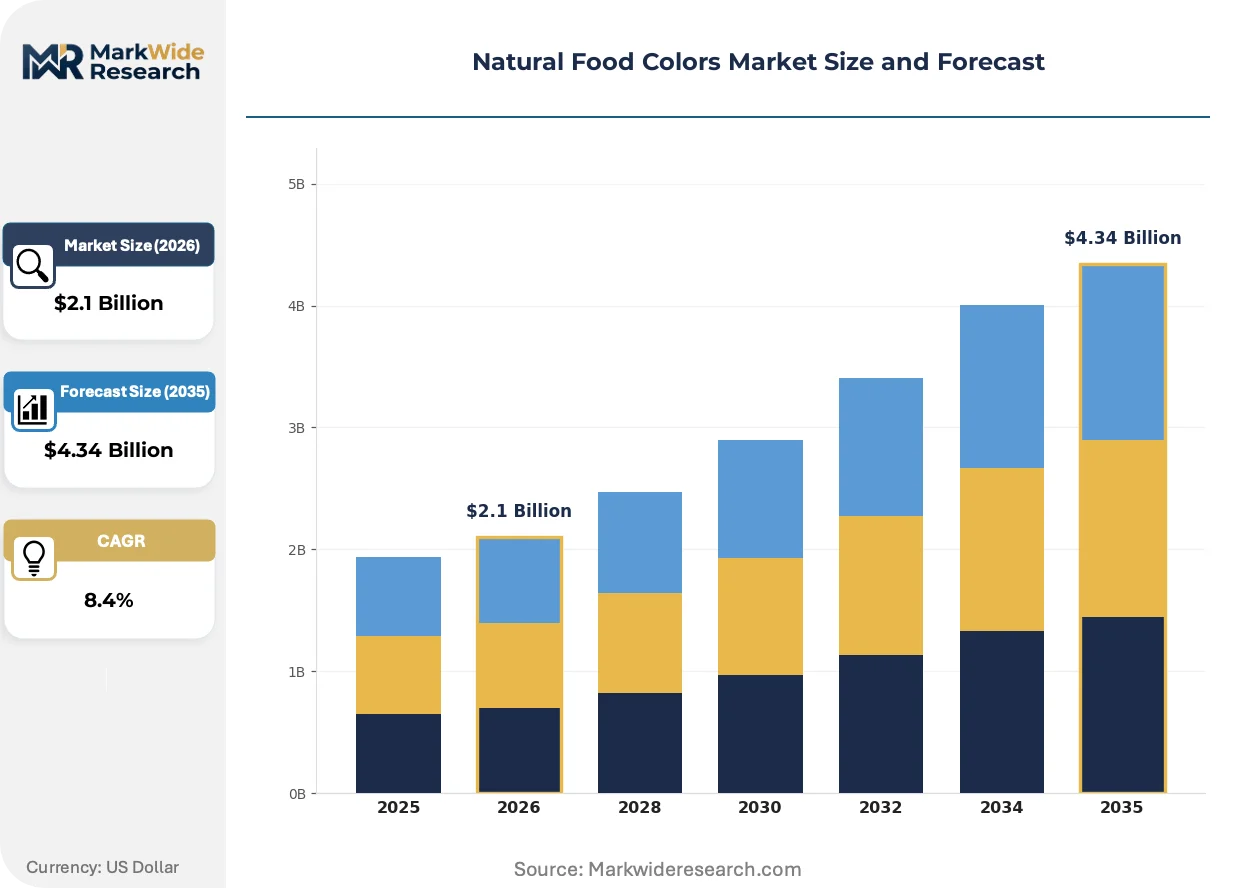
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anthocyanins, Carotenoids, Chlorophyll, Betalains, Curcuminoids Application: Beverages, Confectionery, Dairy Products, Bakery, Snacks End User: Food & Beverage Manufacturers, Nutraceutical Producers, Cosmetic Companies, Pharmaceutical Firms Distribution Channel: Direct Sales, Distributors, Online Retailers, Specialty Stores, Wholesalers |
| Companies Covered | Sensient Technologies Corporation, Givaudan S.A., Döhler GmbH, GNT Group B.V., Oterra A/S, Archer Daniels Midland Company, International Flavors & Fragrances Inc., DSM-Firmenich, Kalsec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food Colors Market Strategic Shifts & Innovations
Technological advancements in extraction and stabilization are reshaping the performance capabilities of natural colors. This evolution allows suppliers to meet increasingly specific and demanding formulation requirements from food and beverage manufacturers seeking both clean labels and vibrant, stable products.
Microencapsulation technology provides a protective barrier for sensitive color pigments, shielding them from degradation by heat, light, or oxygen. Premium food and beverage producers are rapidly adopting this technology for applications like functional drinks and dairy alternatives. This innovation is bifurcating the supplier landscape, creating a divide between firms offering high-performance encapsulated colors and those providing basic, lower-cost extracts.
China's GB standards for food additives are imposing stricter requirements on source traceability and purity levels for ingredients. This regulatory shift compels international suppliers to invest in extensive local testing and potential reformulation to secure or maintain market access. The beverage and confectionery segments are most affected, forcing a strategic prioritization of compliance for any company targeting this major consumer market.
A prominent demand-side shift involves certification-driven sourcing, especially the requirement for Non-GMO Project Verified ingredients. This trend disrupts traditional procurement models that focused primarily on color specification and price, now compelling suppliers to manage and certify entire supply chains. This purchasing behavior is most visible within the North American organic and natural foods sector, impacting bakery, snack, and cereal categories.
Natural Food Colors Market Segmentation
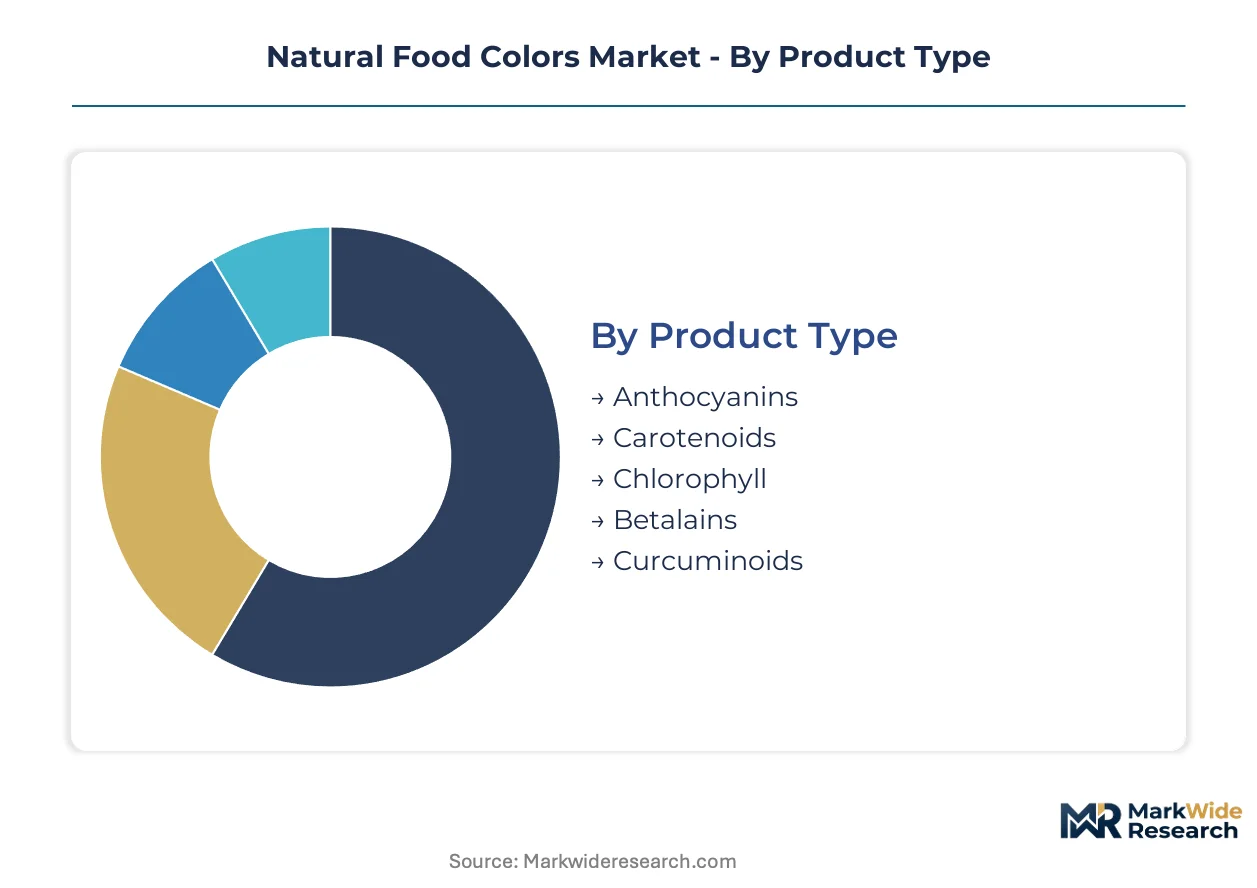
The Natural Food Colors Market segmentation provides a granular view of product types, applications, end users, and distribution channels, revealing distinct demand patterns and supply chain dynamics. Understanding these segments is critical for manufacturers to tailor product development and market entry strategies effectively. This detailed analysis highlights areas of concentration and expansion within the natural color industry.
Product Type:
Product type segmentation reveals how specific colorants fulfill diverse functional and aesthetic requirements across different regions and product categories. Certain pigments demonstrate inherent stability advantages in specific processing environments, influencing their export potential and domestic market saturation.
- Anthocyanins:These water-soluble pigments are derived from sources like berries and purple corn, imparting vibrant red, purple, and blue hues. Demand for anthocyanins is accelerating within the beverage segment across Europe and North America for their clean label appeal and strong visual impact.
- Carotenoids:Fat-soluble pigments extracted from carrots and tomatoes provide yellow, orange, and red colors, known for their stability in various food matrices. Carotenoids represent a dominant product type due to their robust performance in bakery and snack applications, particularly in markets like the United States.
- Chlorophyll:Green pigment extracted from plant sources such as spinach and alfalfa, used to impart natural green colors in food products and dietary supplements.
- Betalains:Red and yellow pigments found in beets and prickly pear, offering vibrant color for dairy and confectionery applications, especially in markets seeking unique color profiles.
- Curcuminoids:Yellow pigments derived from turmeric, valued for their bright color and moderate stability, finding use in sauces, beverages, and savory applications globally.
Carotenoids holds the largest share; momentum sits with Anthocyanins.
Application:
The application landscape demonstrates how different food and beverage categories drive volume demand for natural color solutions. Each application presents unique technical challenges and opportunities for color stability and integration. Manufacturers must address specific processing conditions and consumer expectations for each product type.
- Beverages:This segment requires highly stable, often water-soluble pigments capable of maintaining color integrity in acidic or carbonated environments. Demand from beverage manufacturers is a primary catalyst in Europe and North America as they reformulate to replace synthetic dyes.
- Bakery:Bakery products necessitate heat-stable, often fat-soluble colorants that can withstand high temperatures and extended bake times without degradation. This application sees significant demand in the North American organic and natural foods sector for items like cereals and snacks.
- Confectionery:Utilizes a wide array of natural colors for vibrant sweets and candies, balancing color stability with visual appeal in products consumed globally.
- Dairy Products:Incorporates natural colors for yogurts, cheeses, and milk alternatives, focusing on pH stability and creamy texture compatibility.
- Snacks:Employs carotenoids and other stable pigments for savory and sweet snack items, ensuring consistent color during processing and shelf life.
The beverage segment captures substantial market revenue, while bakery applications demonstrate consistent expansion.
End User:
End user segmentation highlights the diverse industries that procure natural food colors, each with distinct regulatory compliance and formulation requirements. The specific needs of each customer type influence the technical specifications and certifications required from suppliers.
- Food & Beverage Manufacturers:These entities seek diverse color solutions for reformulating existing products and developing new ones, aligning with clean label consumer demands. This segment represents the largest consumer of natural colors, driven by global regulatory pressures from bodies like the EFSA and FDA.
- Nutraceutical Producers:This sector requires colors that do not interfere with active ingredients and offer stability in supplement formulations, often prioritizing plant-derived and organic certifications. Demand is growing in North America and Europe for natural-looking health products.
- Cosmetic Companies:Integrate natural pigments for products like lipsticks and foundations, emphasizing ethical sourcing and skin compatibility in their product lines.
- Pharmaceutical Firms:Utilize natural colors for tablet coatings and liquid medications, prioritizing purity, stability, and stringent regulatory compliance for patient safety.
Food & Beverage Manufacturers represent the primary consumer base, with nutraceutical applications expanding most quickly.
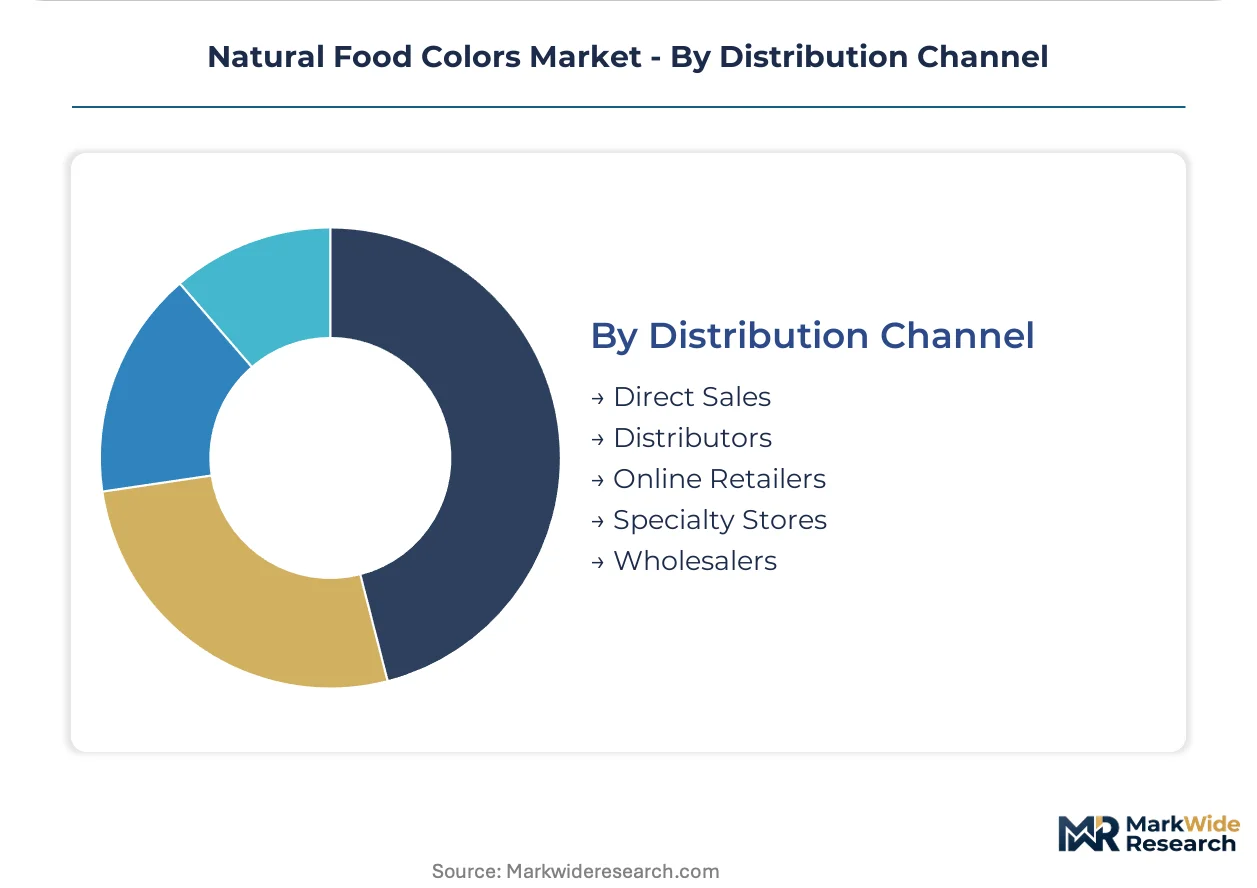
Distribution Channel:
Distribution channels reflect the varied routes through which natural food colors reach their end users, impacting pricing strategies and market reach. The choice of channel often depends on customer size, technical support needs, and geographic scope, influencing profit margins for suppliers.
- Direct Sales:This channel involves direct engagement between large color manufacturers and major food producers, facilitating custom formulations and extensive technical support. Direct sales are preferred by food innovation hubs, particularly in countries like Germany, for high-stability colorants.
- Distributors:Distributors serve as intermediaries, offering broader market reach and localized logistics for small to mid-sized manufacturers. This channel is prevalent in fragmented markets where localized supply chains and diverse product portfolios are critical.
- Online Retailers:Provide accessible platforms for a wider range of natural color ingredients, catering to smaller businesses, startups, and niche product developers.
- Specialty Stores:Cater to artisanal food producers and home users seeking specific or organically certified natural colorants for specialized applications.
- Wholesalers:Supply bulk quantities of common natural colorants to food processors and smaller distributors, emphasizing cost-effectiveness and volume.
Direct sales channels secure significant volume, while distributors ensure widespread market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global natural food colors market benefits from well-established trade routes and logistics networks that facilitate raw material sourcing and product distribution. Major ports and international air freight hubs across key regions support the efficient movement of specialized colorants. These infrastructure assets underpin the market's global reach and supply chain resilience.
United States
United States consumers drive demand for clean label products, increasing the use of natural colors in bakery and snack applications. The U.S. Food and Drug Administration (FDA) strictly regulates food additives, influencing permissible natural color sources and purity. California's food innovation ecosystem, particularly in areas like Silicon Valley, fosters demand for Non-GMO Project Verified ingredients.
Germany
Germany's food innovation hubs concentrate demand for advanced, high-stability natural colors that withstand harsh processing conditions. European Food Safety Authority (EFSA) mandates influence ingredient selection, favoring natural alternatives over synthetic dyes. Cities like Munich and Hamburg serve as centers for food and beverage research, driving new product development with natural colorants.
China
China's beverage and confectionery segments exhibit accelerating demand for natural colors as clean label consciousness grows among consumers. GB standards govern additive approvals, influencing market access for international suppliers. Shanghai and Beijing's major food processing centers require compliant and cost-effective natural color solutions for high-volume production.
Brazil
Brazil's expanding plant-based food sector provides a significant opportunity for natural colors that mimic traditional meat appearances. ANVISA regulations influence food additive approval processes, impacting product formulations. São Paulo's vibrant food and beverage industry actively seeks stable natural colors for local cuisine and export markets.
India
India's growing processed food sector and traditional food product reformulation drive demand for natural color solutions. Food Safety and Standards Authority of India (FSSAI) standards define permissible food colors and purity levels. Mumbai and Delhi's food manufacturing hubs require consistent and affordable natural colorants for diverse product lines.
Natural Food Colors Market Key Industry Players
Listed leaders compete with private specialists across product innovation and market reach within the natural food colors market. The competitive structure is a mix of established, diversified chemical and food ingredient giants and specialized, agile natural color producers. Key strategic archetypes include vertically integrated raw material processors, R&D-intensive color stability experts, and broad-portfolio providers leveraging global manufacturing footprints. Dominant competitive moves involve strategic partnerships for new applications and continuous portfolio diversification to meet evolving clean label demands.
Specialists in vertically integrated solutions include GNT Group B.V., a Netherlands-based company, which exemplifies a focus on controlled sourcing and processing of edible fruits and vegetables. Sensient Technologies Corporation, a US-based entity, occupies a position as a broad portfolio provider, leveraging its global manufacturing footprint for diverse natural color offerings. Oterra A/S, a Denmark-based firm, anchors the segment for extensive R&D in color stability and application-specific formulations, particularly for dairy and beverages.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Givaudan S.A. |
| Döhler GmbH |
| GNT Group B.V. |
| Oterra A/S |
| Archer Daniels Midland Company |
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Kalsec Inc. |
| Others |
Cost & Logistics Intelligence
Natural color ingredient lead times, influenced by agricultural cycles and processing complexity, directly impact pricing power for specialized formulations. This dynamic shapes inventory management across the value chain.
Pricing Analysis
Volume-based discount structures characterize pricing for natural food colors, with long-term contracts for major food and beverage manufacturers. Price differentiation stems from certification levels like Non-GMO Project Verified and enhanced stability performance from microencapsulation technologies. Cost compression in high-volume food categories is intensifying due to agricultural supply volatility for key raw materials. Small and mid-sized manufacturers exhibit higher price sensitivity compared to food innovation hubs seeking advanced, high-stability formulations.
Supply Chain Analysis
The seasonal nature of agricultural harvests creates a chokepoint in the natural food color supply chain. Geographic supply concentrates in regions like China, Europe, and North America, drawing from raw materials such as berries for anthocyanins and carrots for carotenoids. Agricultural supply volatility, stemming from weather events and crop diseases, represents a significant structural risk. Distribution runs through direct sales to major food and beverage manufacturers and via distributors for broader market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural food colors market presents a fragmentation opportunity, driven by the clean label demand from consumers, which continuously creates specialized niches for diverse color solutions. This shift compels targeted innovation across product types.
For Market Incumbents: Compound investments in microencapsulation technologies to protect sensitive natural pigments from degradation, mitigating the technical instability threat. Diversify raw material sourcing across multiple geographies to reduce agricultural supply volatility and secure consistent colorant availability. Control high-volume, price-sensitive segments by optimizing extraction costs and leveraging scale.
For New Entrants and Emerging Players: Anchor in niche applications requiring unique color profiles or specialized stability, such as plant-based meat alternatives or functional beverages. Target underpenetrated Asian markets by developing solutions tailored to local cuisines and GB standards compliance. Offer certification-driven products, like Non-GMO Project Verified ingredients, as a clear go-to-market differentiator for premium segments.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty ingredient consolidation play because regulatory tailwinds and consumer preferences for clean labels are structural and enduring. Identify R&D-intensive firms specializing in high-stability natural color formulations or those with proprietary extraction technologies as prime acquisition targets. Watch for increased adoption of microencapsulation in mainstream food categories as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Encapsulation R&D | Protects fragile pigments from degradation, expanding natural color use into challenging bakery and beverage applications. |
| Expand Raw Material Supply Base | Mitigates agricultural supply volatility, ensuring consistent availability of essential raw materials for color manufacturers. |
| Develop Application-Specific Formulations | Addresses unique technical challenges in dairy and confectionery, optimizing color stability for diverse product matrices. |
| Pursue Non-GMO Project Verified Certification | Responds to consumer clean label demands, particularly in North American organic and natural foods sectors. |
| Establish Localized Production in Asia | Navigates China's GB standards and localizes costs, gaining market access in high-growth Asian economies. |
Research Approach
A spread of perspectives from food and beverage R&D directors, ingredient procurement managers, and regulatory affairs specialists converged on the working assumptions for this analysis. Primary interviews were combined with secondary validation from sources including FDA guidelines, EFSA opinions, and company annual reports. This approach ensured bottom-up market insights were triangulated with top-down industry data.
Product type, application, end user, distribution channel, and stability profile represented the segmentation dimensions modeled across the analysis window. Quantitative forecasts were derived using an analytical framework that integrated historical market trends and projected shifts in consumer demand. Key inputs included raw material price trends and regulatory approval timelines for specific natural colorants.
Material uncertainties — unforeseen regulatory changes, extreme weather events impacting harvests, or significant breakthroughs in synthetic dye alternatives — sit outside the modeled envelope. Forecasts reflect documented assumptions but remain subject to revision. Practitioners should keep alternative scenarios live as global trade policies and climate patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
Roast Flavoring Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Annatto Extract Market