
 Naringin Market | 2026-2036
Naringin Market Size, Share, and Industry Trends Forecast 2026-2036
Naringin Market Analytics
The gap between pharmaceutical-grade naringin and commodity citrus extract is shifting from a quality spread to a pricing chasm, with certification costs and chromatographic purity thresholds now separating viable suppliers from margin-trapped traders. Layn Corp leverages its vertical integration from citrus orchards to purified isolates, sustaining cost advantages that commodity resellers cannot replicate. Xi'An Xuhuang Bio-Tech anchors its position through concentrated R&D spending on crystallization protocols, while Herbchem Biotech competes by dominating the lower-purity nutraceutical segment with aggressive channel control in domestic Chinese markets.
Naringin is a flavanone glycoside comprising naringenin bound to neohesperidose, typically extracted from grapefruit peel via solvent extraction or supercritical CO2 processing, with pharmaceutical applications demanding purity levels exceeding 98% by HPLC. The powder segment leads volume due to its stability in bulk pharmaceutical manufacturing, though liquid formulations for functional beverages represent the fastest-expanding margin pool as beverage brands seek clean-label solubility solutions. Nutraceuticals occupies the mature core, while pharmaceutical-grade extract commands the deepest margin concentration despite smaller absolute tonnage.
China's NMPA and SAMR enforce GB standards on botanical extract purity and heavy metal limits, while the EU's EFSA and Novel Food Regulation govern market access for naringin as a food ingredient across member states. These frameworks elevate compliance costs for cross-border suppliers but simultaneously screen out unqualified competitors, tightening the vendor base. Stakeholders must monitor evolving pharmacopeial monographs and extraction solvent restrictions to anticipate which purity tiers will command sustainable premiums.
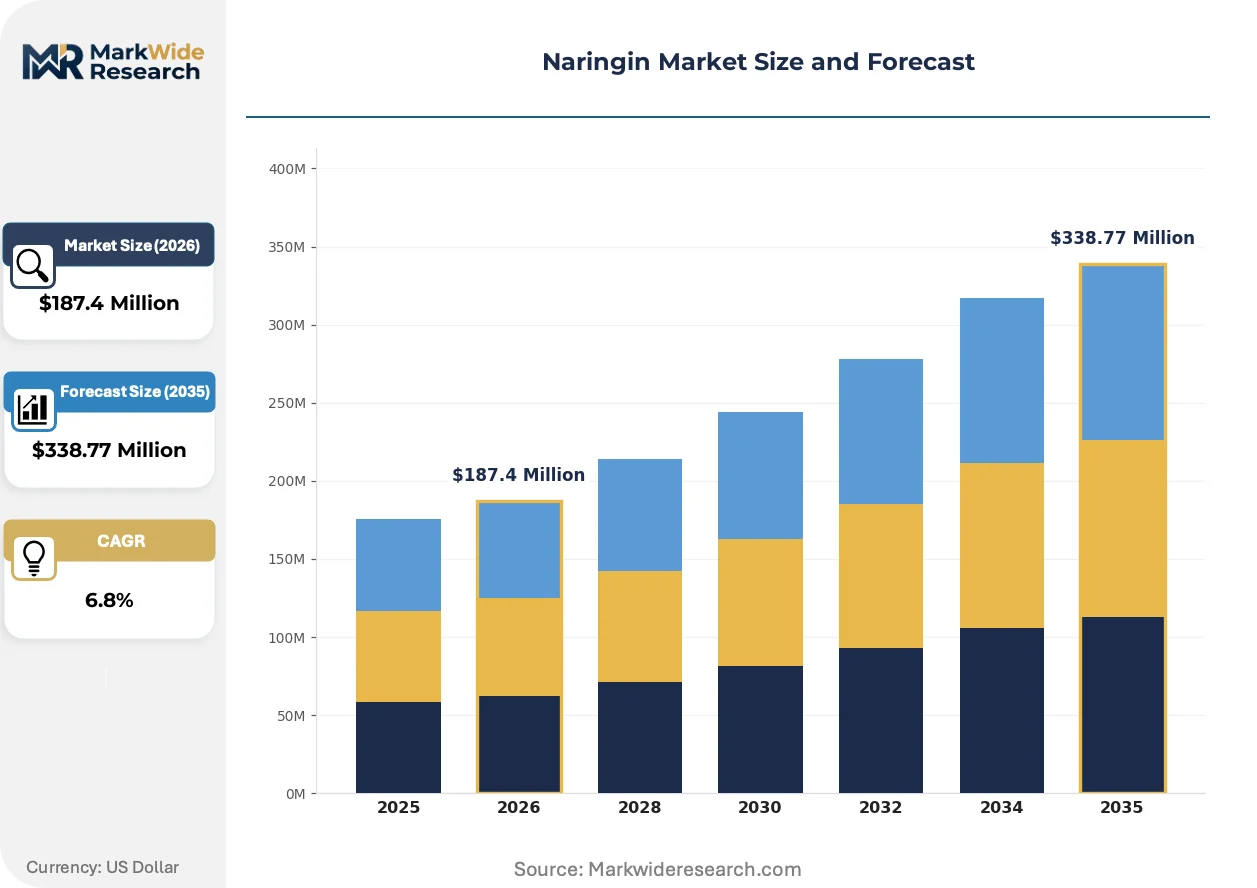
Market Dynamics
Pharmaceutical-grade purity thresholds are compressing the supplier base as chromatographic certification costs screen out commodity traders, concentrating viable production among integrated extractors with captive citrus feedstock.
Growth Catalysts
- EU Novel Food Regulation:EFSA clearance for naringin as a novel food ingredient opens shelf space in functional beverage formulations across member states.
- Supercritical CO2 processing:This solvent-free extraction method reduces residual petrochemicals, satisfying clean-label procurement mandates from German and US pharmaceutical formulators.
- Jiangsu-Zhejiang citrus clusters:Proximity of raw material processing to extraction facilities shortens supply chains for high-purity isolates.
Market Restraints
- Grapefruit peel supply volatility:Weather-driven citrus crop fluctuations in Florida and São Paulo states generate raw material price instability.
- China GB standard compliance costs:SAMR-mandated heavy metal testing and botanical extract purity documentation impose fixed cost burdens on smaller exporters.
- Synthetic flavonoid substitutes:Chemically produced hesperidin and rutin analogs compete on price in lower-specification nutraceutical applications.
Strategic Opportunities
- India nutraceutical penetration:FSSAI's evolving standards for botanical extracts create first-mover positioning for certified suppliers in underdeveloped domestic channels.
- Liposomal encapsulation convergence:Combining naringin with phospholipid delivery systems unlocks bioavailability improvements for pharmaceutical drug delivery partnerships.
- Direct-to-manufacturer platforms:B2B marketplace procurement bypasses traditional distributor markups for mid-volume pharmaceutical buyers.
Industry Challenges
- Pharmacopeial monograph alignment:Divergent USP, EP, and ChP chromatographic methods force dual-method validation investments for cross-border suppliers.
- Crystallization scale-up capex:Pharmaceutical-grade isolation requires GMP-compliant cleanroom infrastructure that locks working capital for 18-24 month certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naringin Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Capsule, Liquid Application: Food & Beverage, Nutraceuticals, Pharmaceuticals, Cosmetics End User: Food Manufacturers, Dietary Supplement Companies, Pharmaceutical Firms, Cosmetic Brands Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Maxsun Industries, Layn Corp, Xi'An Xuhuang Bio-Tech, Lianyuan Kang Biotech, Herbchem Biotech, DESTILACIONES BORDAS CHINCHURRETA, Otto Chemie Pvt. Ltd., XI'AN RONG ZHI BIO-TECH CO., LTD., Benepure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naringin Market Evolving Landscape
Clean-label solubility requirements are forcing extraction technology upgrades while regulatory convergence around heavy metal limits compresses the viable supplier universe.
Supercritical CO2 extraction systems are expanding into pharmaceutical-grade naringin production as solvent residue regulations tighten. German and US drug manufacturers now specify sub-ppm petrochemical thresholds in raw material qualification protocols. This technology shift is expanding into mid-tier Chinese processors that previously relied on ethanol-based methods, raising capital barriers for market entry.
REACH registration requirements for botanical extracts are forcing EU importers to document full supply chain substance volumes. ECHA's updated guidance on flavonoid classification triggers downstream notification obligations for naringin concentrations above 0.1% in formulated products. Cosmetic and nutraceutical blenders in France and Germany are responding by consolidating supplier relationships to reduce registration duplication costs.
Certificate-of-analysis-driven procurement now dominates pharmaceutical raw material purchasing, displacing spot-market spot-checking. Buyers in North American compounding pharmacies demand lot-specific HPLC purity data with heavy metal certificates before releasing purchase orders. This behavioral shift concentrates contract volumes with laboratories maintaining in-house analytical capabilities, visible most acutely in New Jersey and California formulation clusters.
Naringin Market Segmentation
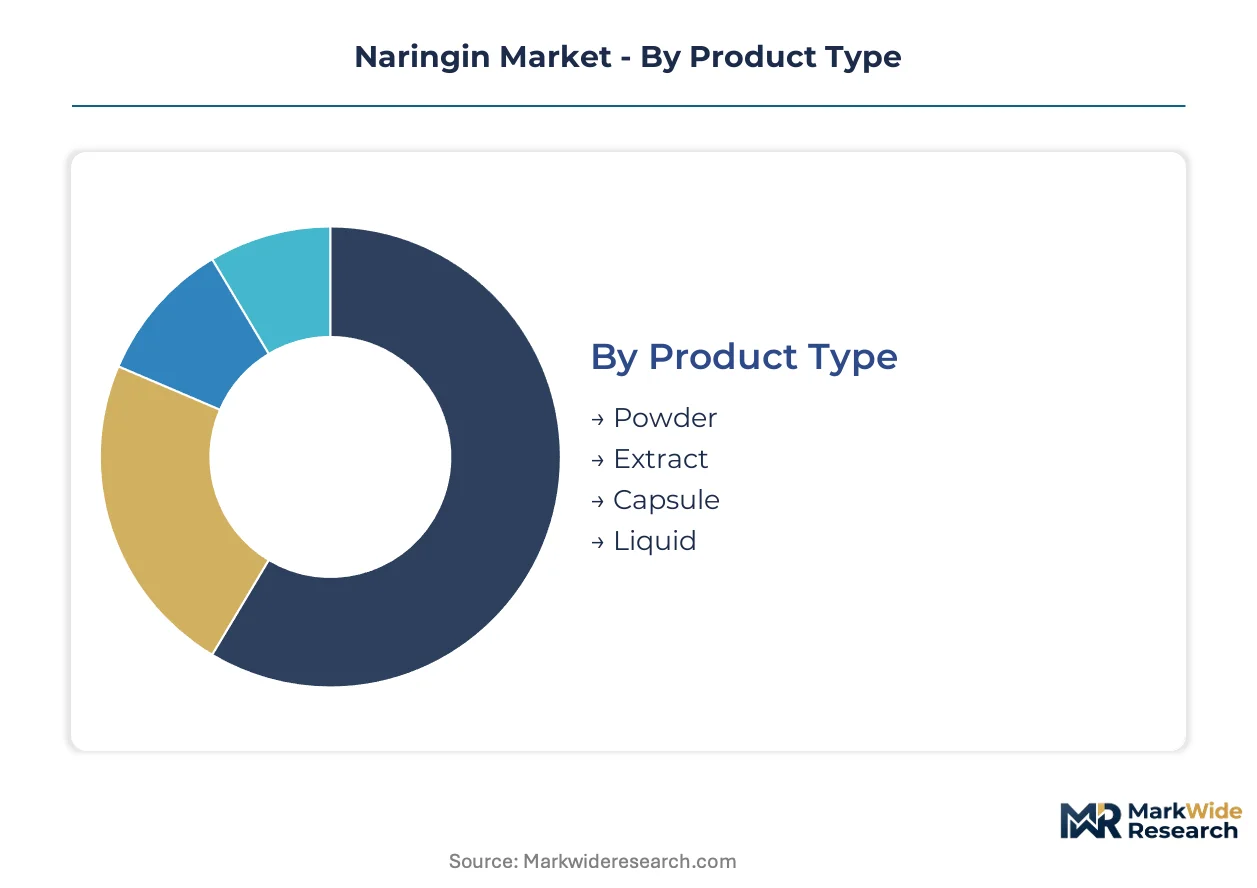
Purity thresholds and formulation requirements fragment procurement behavior across buyer categories. Pharmaceutical formulators, nutraceutical blenders, and beverage manufacturers each demand distinct specification tiers that reshape supplier positioning.
Product Type:
Stability requirements and handling economics drive format selection, with bulk pharmaceutical manufacturing favoring shelf-stable powders while functional beverage brands prioritize solubility.
- Powder:Crystalline isolate exceeding 98% HPLC purity dominates bulk drug manufacturing due to extended stability and precise dosing. German and US pharmaceutical formulators specify powder grades for tablet compression and capsule filling operations.
- Liquid:Solubilized concentrates enable clean-label beverage formulations without emulsifier additives. Demand concentrates in functional drink development labs across California and New Jersey seeking rapid dissolution profiles.
- Extract:Standardized botanical preparations serve mid-tier nutraceutical applications with 40-70% flavonoid content.
- Capsule:Pre-formulated dosage units bypass in-house encapsulation infrastructure for smaller dietary supplement brands.
Powder leads on scale; liquid leads on momentum.
Application:
Regulatory pathway complexity separates commercial tiers, with pharmaceutical drug delivery commanding certification investment while food-grade applications face lighter documentation burdens.
- Pharmaceuticals:Drug delivery systems and API adjuvants require USP-grade monograph compliance with full impurity profiling. EMA and FDA inspection readiness shapes supplier qualification timelines for European and North American formulators.
- Food & Beverage:Novel food clearance under EFSA frameworks opens formulation flexibility across EU member states. Clean-label positioning drives adoption in functional beverage categories seeking grapefruit-derived credentials.
- Nutraceuticals:Dietary supplement applications anchor volume through established GRAS and novel food dossiers in multiple jurisdictions.
- Cosmetics:Topical antioxidant formulations utilize lower-purity grades with reduced certification overhead for skincare and personal care brands.
Nutraceuticals anchors absolute volume; food and beverage applications are expanding most quickly.
End User:
Procurement sophistication varies dramatically, with pharmaceutical quality units demanding certificate-of-analysis documentation that screens out commodity traders.
- Pharmaceutical Firms:GMP-compliant raw material qualification mandates chromatographic purity verification with heavy metal screening. New Jersey and California formulation clusters concentrate contract volumes with laboratories maintaining in-house analytical capabilities.
- Dietary Supplement Companies:Mid-tier buyers balance specification compliance against price sensitivity, often accepting food-grade purity for non-therapeutic positioning.
- Food Manufacturers:Beverage and functional food processors prioritize solubility and flavor masking over pharmaceutical-grade documentation.
- Cosmetic Brands:Marketing-driven procurement emphasizes natural-origin claims with minimal regulatory filing requirements.
Pharmaceutical firms set the specification ceiling; dietary supplement companies provide the volume base.
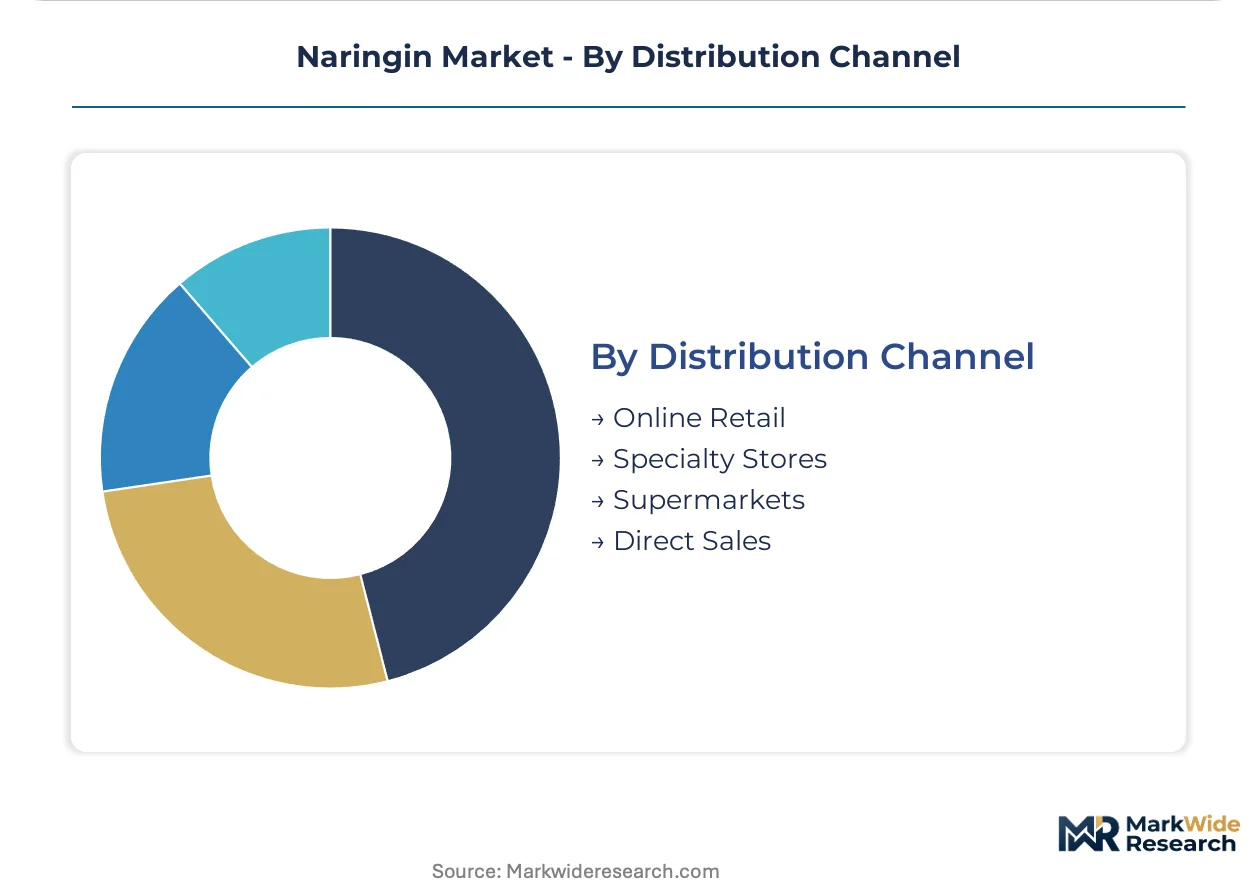
Distribution Channel:
Order size and technical support requirements determine channel selection, with large pharmaceutical buyers bypassing intermediaries while smaller formulators rely on distributor inventory.
- Direct Sales:Contract manufacturing agreements and long-term supply contracts dominate pharmaceutical-grade procurement. Technical account management supports method validation and regulatory filing assistance.
- Online Retail:E-procurement platforms serve mid-volume buyers seeking transparent pricing and rapid sample turnaround for formulation development.
- Specialty Stores:Regional distributors maintain inventory for nutraceutical and cosmetic manufacturers with intermittent purchasing patterns.
- Supermarkets:Mass-market retail channels primarily serve consumer-facing finished goods rather than industrial raw material procurement.
Direct sales commands the specification-intensive tier; online retail is gaining share fastest among emerging formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized extraction chemists and citrus processing engineers concentrate in Jiangsu and Zhejiang provinces, where proximity to raw material feedstock and pharmaceutical formulation clusters creates talent density unmatched elsewhere.
China
Pharmaceutical-grade naringin isolation demands chromatographic purification infrastructure that clusters in Jiangsu and Zhejiang provinces. SAMR-enforced GB standards on botanical extract purity and heavy metal documentation screen out smaller exporters. The Yangtze River Delta corridor anchors captive citrus processing capacity feeding high-purity isolate production.
United States
New Jersey and California formulation clusters drive certificate-of-analysis procurement for compounding pharmacies and drug delivery system developers. FDA inspection readiness and USP monograph compliance shape supplier qualification timelines. Florida citrus volatility generates raw material price instability that concentrates risk management expertise in procurement teams.
Germany
Supercritical CO2 extraction specifications from German pharmaceutical formulators establish solvent residue benchmarks sub-ppm. EFSA novel food clearance opens functional beverage formulation channels across EU member states. The Rhine-Ruhr industrial corridor concentrates botanical extract analytical laboratories serving cross-border qualification protocols.
India
FSSAI's evolving botanical extract standards create first-mover positioning for certified suppliers in underdeveloped domestic nutraceutical channels. CDSCO pharmaceutical regulation alignment pressures importers toward pharmacopeial-grade documentation. Maharashtra and Gujarat processing hubs attract investment in citrus-derived flavonoid isolation capacity.
Brazil
São Paulo state citrus crop fluctuations transmit price volatility into global feedstock markets. ANVISA pharmaceutical regulation governs import qualification for drug delivery applications. The Southeast region's processing infrastructure remains concentrated in commodity juice extraction rather than high-purity isolate production.
Naringin Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade purity tiers, while commodity resellers face margin compression from certification cost burdens. The supplier base concentrates among integrated extractors with captive citrus feedstock and in-house analytical capabilities. Three archetypes dominate: vertically integrated orchard-to-isolate operators, R&D-intensive crystallization specialists, and channel-dominant nutraceutical commodity suppliers. Capacity expansion in supercritical CO2 systems and strategic partnerships for liposomal encapsulation represent the dominant competitive vectors.
Within the integrated extraction tier, Layn Corp exemplifies orchard-to-isolate backward integration that commodity traders cannot replicate. Xi'An Xuhuang Bio-Tech occupies a position among crystallization protocol specialists investing concentrated R&D spending. Herbchem Biotech anchors the lower-purity nutraceutical segment through aggressive domestic Chinese channel control. These three represent the structural segmentation between premium pharmaceutical qualification and volume-driven commodity supply.
| Leading Market Players |
|---|
| Maxsun Industries |
| Layn Corp |
| Xi'An Xuhuang Bio-Tech |
| Lianyuan Kang Biotech |
| Herbchem Biotech |
| DESTILACIONES BORDAS CHINCHURRETA |
| Otto Chemie Pvt. Ltd. |
| XI'AN RONG ZHI BIO-TECH CO., LTD. |
| Benepure |
| Others |
Value Network & Pricing Analysis
Pharmaceutical formulators in Germany and the United States anchor procurement volumes for high-purity naringin, concentrating contract pricing power among integrated extractors with captive citrus feedstock and in-house chromatographic certification capabilities.
Pricing Analysis
Certificate-of-analysis bundling separates pharmaceutical-grade contracts from spot-market transactions. Pricing stratifies across premium, standard, and economy tiers based on HPLC purity thresholds and heavy metal documentation depth. Cost compression in the nutraceutical segment is intensifying because synthetic flavonoid substitutes compete on price in lower-specification applications. Dietary supplement companies exhibit the highest price sensitivity, while German drug manufacturers prioritize solvent-residue compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Jiangsu and Zhejiang provinces feed hub-and-spoke patterns serving pharmaceutical formulation clusters. Manufacturing concentrates in China, with secondary processing nodes in Germany and the United States. Feedstock draws from grapefruit peel supply chains tethered to Florida and São Paulo citrus crop cycles. Single-source vulnerability runs through Jiangsu-Zhejiang extraction capacity concentration. Distribution runs through direct sales contracts for pharmaceutical buyers and specialty distributors for nutraceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers as supercritical CO2 processing costs decline and EFSA novel food clearance opens premium beverage formulation channels.
For Market Incumbents: To counter synthetic flavonoid substitution in lower-purity segments, crystallization specialists should deepen backward integration into captive citrus orchards while expanding GMP-compliant cleanroom capacity to shorten FDA and EMA qualification timelines for drug delivery partnerships. For New Entrants and Emerging Players: Begin with FSSAI-compliant supply to India's underdeveloped domestic nutraceutical channels, where botanical extract standards are evolving and certified suppliers face limited competition. Liposomal encapsulation partnerships with pharmaceutical formulators offer the most penetrable go-to-market angle for bioavailability differentiation. For Investors and Strategic Acquirers: Pharmaceutical-grade extractors with in-house analytical capabilities are the most active acquirer targets in this space, as consolidation pressures screen out commodity traders unable to absorb chromatographic certification costs. The long-term viability window favors integrated orchard-to-isolate operators. Watch ECHA guidance updates on flavonoid classification thresholds as the inflection signal for downstream notification cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Reduces residual petrochemicals below German pharmaceutical formulator sub-ppm specifications. |
| Backward Integration into Citrus Orchards | Locks raw material supply against Florida and São Paulo weather-driven price volatility. |
| Liposomal Encapsulation Partnership | Unlocks bioavailability improvements for EMA and FDA drug delivery system filings. |
| EFSA Novel Food Dossier Investment | Opens functional beverage shelf space across EU member states with clean-label positioning. |
| GMP Cleanroom Certification | Enables USP-grade monograph compliance for New Jersey and California pharmaceutical clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction chemists, pharmaceutical quality officers, citrus processing engineers, and regulatory affairs specialists at NMPA and SAMR with secondary validation from customs trade data, EFSA novel food registers, USP monograph updates, and pharmacopeial filing databases. Bottom-up capacity modeling and top-down demand triangulation anchored value estimates.
Segment-weighting across the projection horizon applied purity tier, application end-use, and regional regulatory cluster dimensions. CAGRs derived from production capacity buildout trajectories, EFSA clearance timelines, and pharmaceutical formulation partnership announcements. Forecast inputs included supercritical CO2 system installation rates and Jiangsu-Zhejiang citrus processing yield data.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, synthetic flavonoid substitution acceleration, and extreme weather impacts on São Paulo citrus harvests. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Maple Extracts Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market