
 Vanillin Market | 2026-2036
Vanillin Market Size, Share, and Industry Trends Forecast 2026-2036
Vanillin Market Analysis
Specialized biochemical engineering talent is reorganizing vanillin supply chains as fermentation-based production scales compete with petrochemical routes. Borregaard AS anchors European biovanillin output through its wood-lignin processing complex in Norway. Solvay SA dominates legacy guaiacol-based synthetic production from its Belgian operations. dsm-firmenich leverages integrated fragrance-flavor R&D to extend natural vanillin portfolios for premium food clients.
Vanillin is a phenolic aldehyde (C8H8O3) extracted from vanilla pods or synthesized from guaiacol or lignin, with a characteristic melting point of 81–83°C and threshold detection near 20 ppb in aqueous solutions. It functions primarily as a flavor enhancer masking bitterness and as a fragrance fixative in compounded perfumes. Synthetic vanillin occupies the volume base across commodity food applications while natural vanillin commands premium positioning in organic and clean-label product lines. Ethyl vanillin delivers roughly three times the flavor intensity of standard vanillin and captures concentrated margin pools in high-end confectionery and pharmaceutical coatings.
EU REACH restrictions on petrochemical feedstocks and FDA food additive safety assessments shape formulation choices and market access conditions for both synthetic and natural grades. China's NMPA and GB standards for food flavorants govern import specifications and domestic manufacturing licensing for vanillin destined to food manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions where natural extraction claims face tightening evidentiary standards while synthetic alternatives confront feedstock sustainability scrutiny.
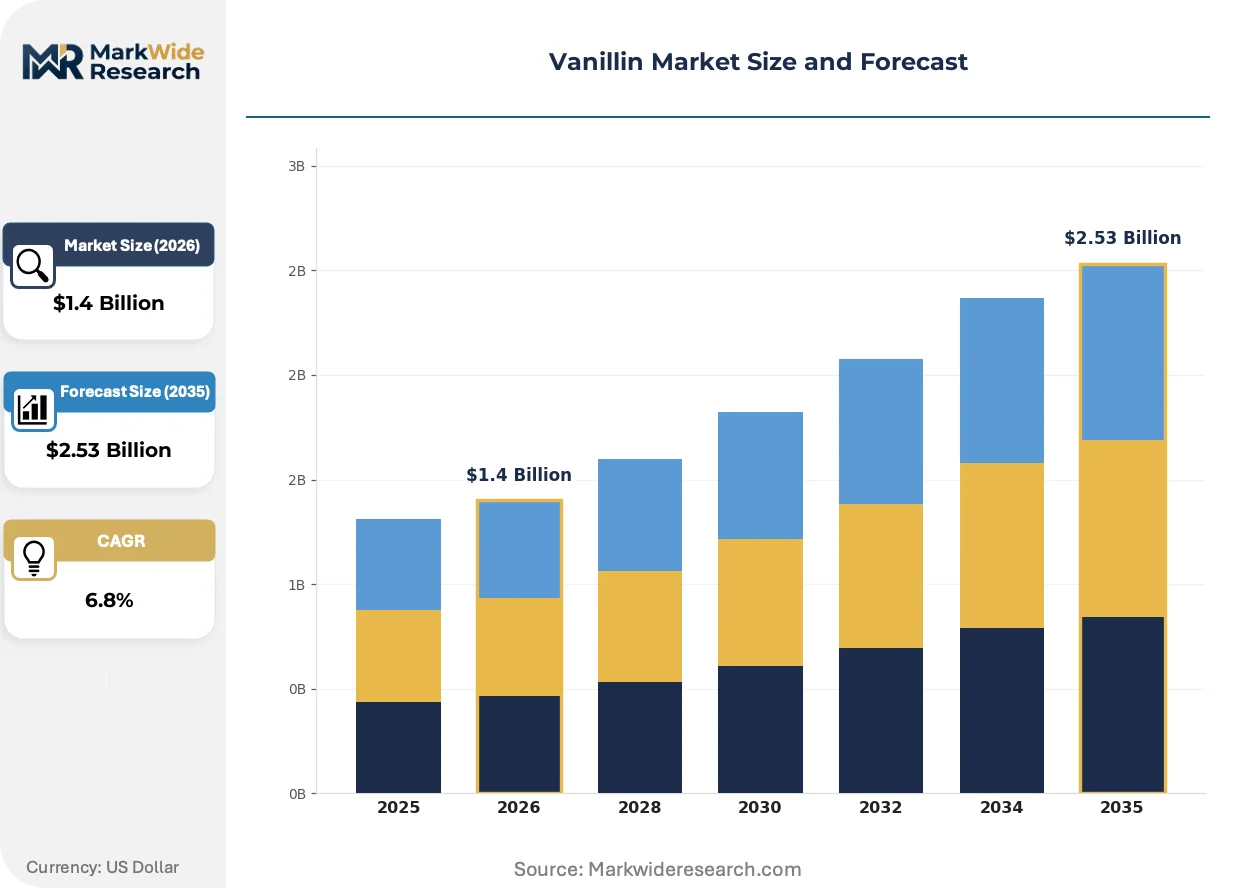
Market Dynamics
Biovanillin fermentation capacity is scaling rapidly as lignin-to-vanillin conversion economics improve and REACH restrictions tighten synthetic feedstock access across European manufacturing.
Growth Catalysts
- EU Green Deal chemical transition:REACH restrictions on petrochemical-derived additives accelerate lignin-based extraction investments in Norwegian and Belgian processing facilities.
- China's processed food expansion:Domestic flavor houses in Jiangsu and Zhejiang provinces scale biovanillin output to serve regional confectionery and bakery sector procurement.
- Clean-label formulation mandates:Packaged goods manufacturers in organic and premium segments specify natural vanillin grades to meet retailer certification requirements.
Market Restraints
- Guaiacol price volatility:Synthetic vanillin producers face input cost pressure from petrochemical feedstock fluctuations and energy-intensive phenol derivative processing.
- Nordic supply concentration:Wood-lignin biovanillin output clusters in Norway and Sweden, creating geographic single-point vulnerability for European natural grade procurement.
- Ethyl vanillin substitution ceiling:Threefold intensity advantage in high-end confectionery limits standard vanillin price realization in premium coating applications.
Strategic Opportunities
- India FSSAI natural flavorant pathway:Regulatory clarity on extraction-source labeling creates first-mover positioning for biovanillin suppliers in domestic processed dairy and sweets manufacturing.
- Pharmaceutical coating applications:Bitterness-masking demand in pediatric and geriatric drug formulations expands vanillin procurement beyond traditional food channels.
- Carbon accounting integration:EU CSRD disclosure requirements favor fermentation-based vanillin with verifiable Scope 3 reductions in corporate sustainability reporting.
Industry Challenges
- Fermentation scale-up expertise:Biochemical engineering talent scarcity constrains lignin-to-vanillin yield optimization and commercial batch consistency.
- Natural certification evidentiary burden:EU and FDA documentation requirements for extraction-source claims extend product qualification timelines and legal compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanillin Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Vanillin, Synthetic Vanillin, Ethyl Vanillin, Vanillin Derivatives Application: Food & Beverage, Fragrances, Pharmaceuticals, Cosmetics End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Fragrance Houses Distribution Channel: Online Retailers, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Symrise AG, Camlin Fine Sciences Ltd., Borregaard AS, Prinova Group LLC, Merck KGaA, dsm-firmenich, Advanced Biotech, Solvay SA, Givaudan S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanillin Market Emerging Trajectories
Vanillin production technology is splitting along feedstock lines as fermentation economics improve and regulatory pressure on petrochemical routes intensifies across multiple jurisdictions.
Precision fermentation of lignin-derived substrates is bifurcating the natural vanillin supply base. Food manufacturers in organic and clean-label segments adopt biovanillin at accelerating rates as batch consistency matches extraction-grade quality. Synthetic guaiacol-based production is compressing into commodity applications where cost minimization dominates formulation decisions.
REACH authorization requirements for phenol derivatives are tightening synthetic vanillin manufacturing compliance burdens in Belgium and neighboring jurisdictions. ECHA substance evaluation protocols extend registration renewal cycles and demand expanded toxicological dossiers from legacy producers. Natural extraction and fermentation grades capture preferential positioning in EU-destined flavor formulations as downstream customers pre-empt supply disruption risks.
Direct procurement contracts between food manufacturers and biovanillin fermenters are shortening traditional distribution channels. Large confectionery and packaged goods groups in China and Europe establish captive supply relationships with lignin processors to secure volume commitments and price visibility. This disintermediation concentrates most visibly in premium organic segments where extraction-source traceability commands contractual specification priority.
Vanillin Market Segmentation
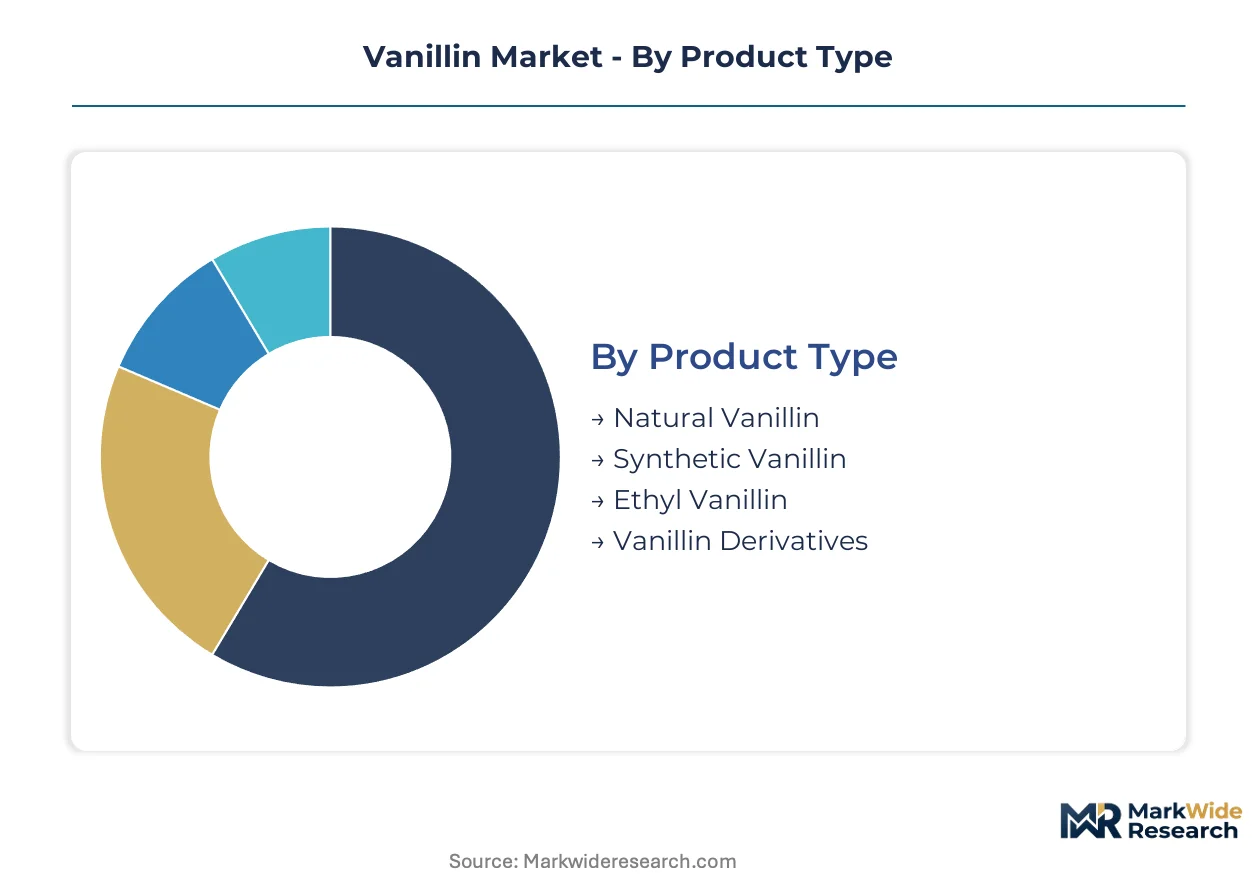
Vanillin procurement patterns diverge sharply across product grades and end-use specifications. Food manufacturers drive volume concentration in synthetic grades while fragrance houses and organic food producers anchor premium natural extraction demand.
Product Type:
Natural vanillin serves export-led premium formulations in EU and North American organic markets. Synthetic grades dominate domestic procurement across Asian processed food manufacturing.
- Natural Vanillin:Extracted from vanilla pods or fermented from lignin substrates, this grade carries extraction-source certification requirements under EU REACH and FDA frameworks. Demand concentrates in organic confectionery and premium ice cream manufacturing across Germany, France, and the Netherlands as retailers mandate clean-label ingredient disclosure.
- Synthetic Vanillin:Manufactured from guaiacol or lignin through petrochemical or biorefinery routes, this grade delivers cost-optimized flavor coverage for mass-market baked goods and beverages. Procurement clusters in China's domestic processed food sector where Jiangsu and Zhejiang flavor houses scale fermentation capacity to serve regional bakery and dairy expansion.
- Ethyl Vanillin:Delivers approximately three times the flavor intensity of standard vanillin, capturing concentrated demand in high-end confectionery coatings and pharmaceutical bitterness masking.
- Vanillin Derivatives:Includes specialty modified compounds for fragrance fixative and polymer intermediate applications.
Synthetic vanillin holds the largest share; momentum sits with natural extraction and fermentation grades.
Application:
Cost tier stratification separates commodity flavor coverage from premium positioning across end-use segments.
- Food & Beverage:The dominant volume channel spanning baked goods, confectionery, dairy, and beverage formulations. Synthetic grades serve mass-market applications while natural vanillin penetrates organic and clean-label product lines under EU Green Deal chemical transition requirements.
- Fragrances:Vanillin functions as a fixative in compounded perfumes and personal care products. Demand concentrates in French and Swiss fragrance houses sourcing extraction-grade material for luxury positioning.
- Pharmaceuticals:Bitterness-masking applications in pediatric and geriatric drug formulations expand procurement beyond traditional food channels.
- Cosmetics:Fragrance and masking agent in skincare and haircare formulations, typically specifying cosmetic-grade purity standards.
Food and beverage applications command the dominant volume position; pharmaceuticals represent the steepest expansion trajectory.
End User:
Customer type determines procurement structure, with large manufacturers pursuing direct supply relationships and smaller buyers relying on distributor networks.
- Food Manufacturers:Span multinational packaged goods groups to regional bakery and dairy processors. Direct procurement contracts with lignin processors are shortening traditional distribution channels for premium organic segments.
- Cosmetic Companies:Formulate vanillin into skincare, haircare, and personal care products with emphasis on fragrance stability and skin safety profiles.
- Pharmaceutical Firms:Specify pharmacopeia-grade material for drug coating and excipient applications under FDA and EMA quality frameworks.
- Fragrance Houses:Source extraction-grade natural vanillin for luxury perfume compounding, prioritizing batch consistency and traceability documentation.
Food manufacturers represent the largest procurement base; pharmaceutical firms are gaining share fastest.
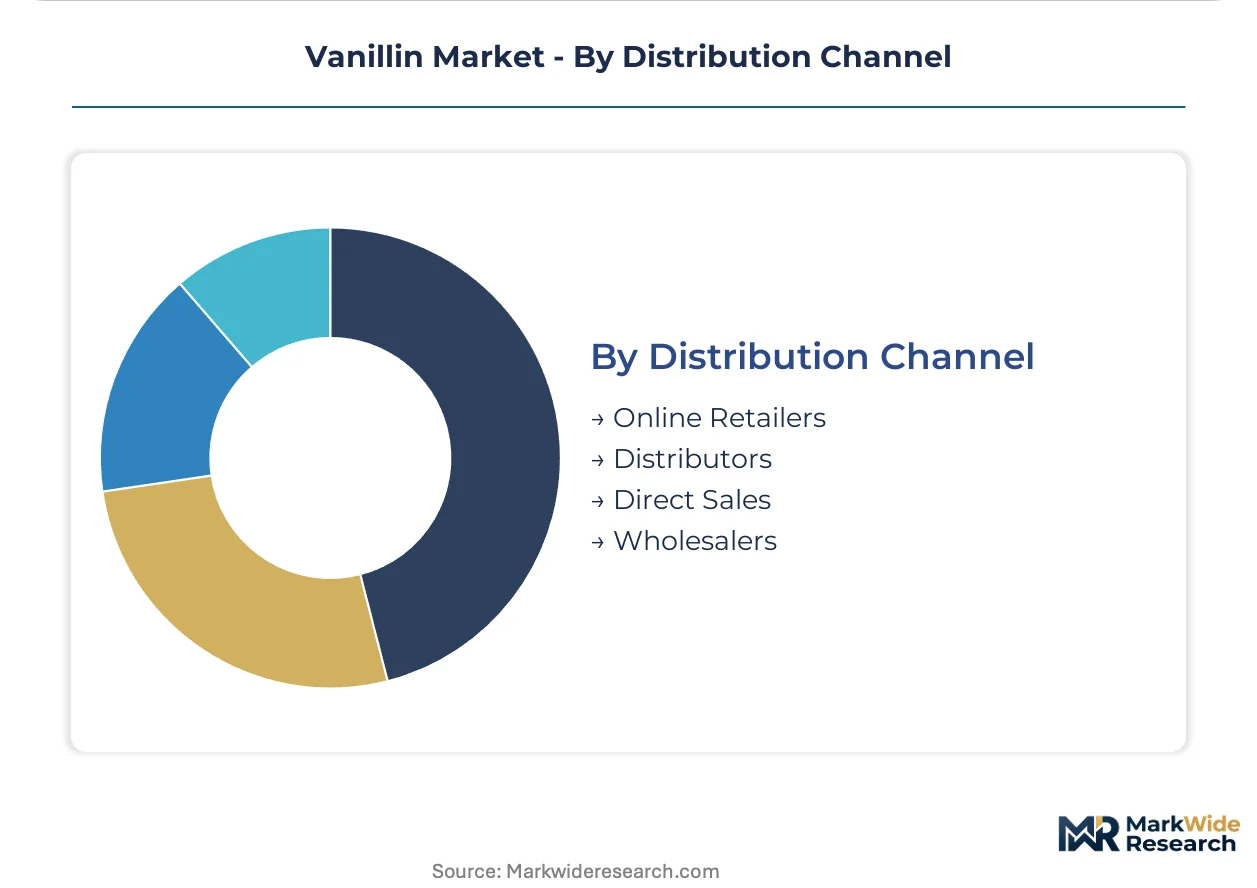
Distribution Channel:
Supply concentration in Nordic lignin processing and Belgian petrochemical routes shapes channel selection across geographies.
- Direct Sales:Large confectionery and packaged goods groups in China and Europe establish captive supply relationships with Borregaard and domestic fermenters to secure volume commitments and price visibility.
- Distributors:Regional chemical distributors serve mid-tier food manufacturers and cosmetic formulators requiring smaller batch sizes and technical support.
- Online Retailers:Emerging channel for specialty and research-grade vanillin serving small-scale food artisans and independent cosmetic producers.
- Wholesalers:Traditional bulk channel for commodity synthetic grades serving industrial food processing in price-sensitive markets.
Direct sales capture the largest volume; online retailers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes synthetic vanillin at industrial scale for mass-market processed foods, while Germany and France prioritize natural extraction grades for organic retail certification. This consumption-mix differential shapes procurement strategies and regulatory compliance investments across manufacturing bases.
China
Jiangsu and Zhejiang provinces host expanding biovanillin fermentation facilities serving domestic bakery and dairy sector procurement. NMPA and GB standards for food flavorants govern manufacturing licensing and import specifications for vanillin destined to food manufacturers. Shanghai-based flavor houses scale lignin-to-vanillin conversion capacity to capture regional processed food expansion.
Germany
Organic confectionery and premium ice cream manufacturers drive natural vanillin demand under retailer clean-label mandates. EU REACH restrictions on petrochemical-derived additives accelerate lignin-based extraction investments. Cologne and Hamburg anchor distribution networks for extraction-grade material serving EU-destined formulations.
United States
Fragrance houses in New York and New Jersey source extraction-grade natural vanillin for luxury perfume compounding. FDA food additive safety assessments shape formulation choices for both synthetic and natural grades. Chicago and Minneapolis food manufacturers specify natural grades for organic product lines under retailer certification requirements.
France
Paris and Grasse fragrance houses anchor premium natural vanillin procurement for luxury positioning. EU Green Deal chemical transition frameworks tighten synthetic additive restrictions. Lyon-based flavor formulators integrate biovanillin into clean-label confectionery applications for export markets.
India
Maharashtra and Gujarat processed dairy and sweets manufacturers present first-mover opportunities for biovanillin suppliers. FSSAI regulatory clarity on extraction-source labeling creates positioning pathways for natural flavorant claims. Mumbai flavor houses scale procurement to serve domestic confectionery sector expansion.
Vanillin Market Vendor Landscape
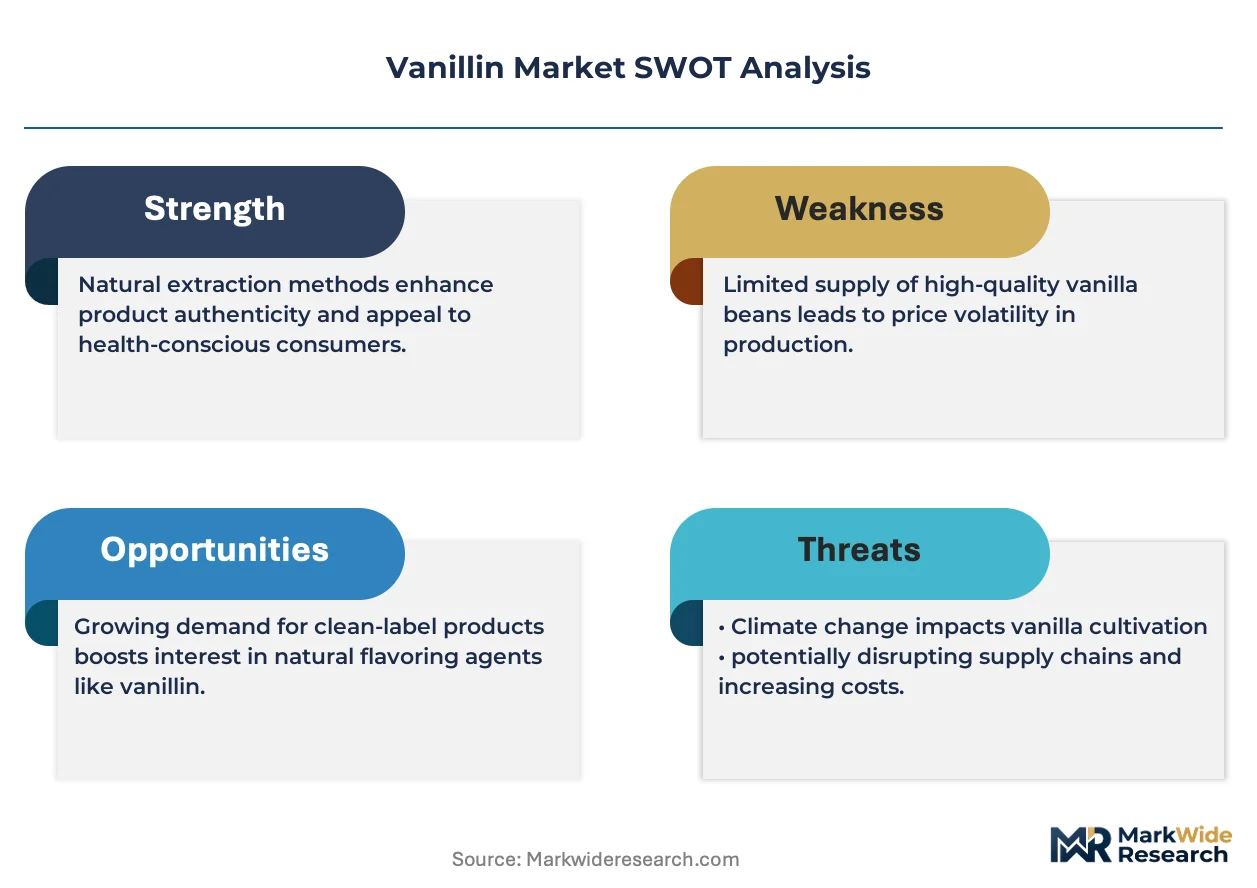
A small set of integrated leaders sits above a broader specialist tier in the vanillin market structure. Integrated fragrance-flavor conglomerates and wood-lignin processors occupy the upper tier with captive raw material access and downstream formulation integration. Specialist biochemical engineering firms and regional chemical manufacturers populate the lower tier, competing on fermentation yield optimization and batch consistency. Competitive moves concentrate on strategic partnerships with lignin processors and capacity expansion in biovanillin fermentation.
Within the integrated tier, Symrise AG and dsm-firmenich exemplify fragrance-flavor conglomerates with R&D integration across natural extraction portfolios. Among wood-lignin specialists, Borregaard AS anchors European biovanillin output through Norwegian processing infrastructure. Solvay SA occupies a position representing legacy petrochemical-based synthetic production, facing feedstock sustainability scrutiny under REACH frameworks.
| Leading Market Players |
|---|
| Symrise AG |
| Camlin Fine Sciences Ltd. |
| Borregaard AS |
| Prinova Group LLC |
| Merck KGaA |
| dsm-firmenich |
| Advanced Biotech |
| Solvay SA |
| Givaudan S.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Borregaard AS and European confectionery groups lock in lignin-derived biovanillin supply access while providing price visibility against guaiacol feedstock volatility. These contracts concentrate procurement power among large food manufacturers seeking extraction-source traceability under EU REACH frameworks.
Pricing Analysis
Contract-based long-term offtake structures dominate premium natural vanillin tiers, while spot-market transactions govern commodity synthetic grades. Price differentiation separates certified organic extraction grades from standard fermentation batches, with volume scale driving discounts in bulk pharmaceutical coating applications. Cost compression in synthetic guaiacol-based production is intensifying because petrochemical feedstock fluctuations squeeze margins at Solvay SA's Belgian operations. Mass-market bakery manufacturers exhibit highest price sensitivity, while fragrance houses in Grasse show lowest sensitivity due to luxury positioning requirements.
Supply Chain Analysis
Norway and Sweden anchor European biovanillin output through Borregaard AS's wood-lignin processing infrastructure, while Belgium hosts legacy synthetic production. Raw material dependencies center on phenol derivatives for guaiacol routes, lignin feedstock from pulp and paper operations, and fermentation substrates for biovanillin conversion. Single-source vulnerability clusters in Nordic lignin processing, where geographic concentration creates disruption risk for natural grade procurement. Distribution runs through direct sales channels for large food manufacturers and regional chemical distributors serving mid-tier cosmetic formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vanillin procurement is shifting toward platform-based ecosystem integration as direct digital contracts between fermenters and food manufacturers displace traditional distributor networks. This interoperability inflection favors players with verifiable carbon accounting and extraction-source documentation systems.
For Market Incumbents: Compound defensive positioning by securing captive lignin supply agreements with Nordic pulp processors and accelerating fermentation yield optimization investments. Biovanillin batch consistency gaps threaten premium segment retention as Chinese flavor houses scale competing capacity. Backward integration into wood-lignin sourcing anchors margin defense against feedstock cost volatility.
For New Entrants and Emerging Players: Technical support gaps in small-batch natural certification documentation present white-space entry points for specialist compliance service providers. India's FSSAI regulatory clarity on extraction-source labeling offers the most penetrable geography for biovanillin market establishment. Pharmaceutical bitterness-masking applications provide a defensible go-to-market angle with higher margin tolerance than commodity food channels.
For Investors and Strategic Acquirers: Fermentation-engineering boutiques with proven lignin-to-vanillin yield optimization represent priority acquisition targets for portfolio diversification. Long-term viability over the coming decade hinges on regulatory divergence between EU Green Deal chemical transition acceleration and slower feedstock restriction adoption in Asian jurisdictions. Watch for ECHA substance evaluation protocol expansions as the inflection signal indicating synthetic route compliance cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Supply | Borregaard AS's Norwegian wood-processing complex secures feedstock autonomy against pulp market volatility. |
| Fermentation Capacity Expansion | Jiangsu and Zhejiang flavor houses scale biovanillin output to capture China's processed dairy sector procurement. |
| Green Manufacturing Transition | EU CSRD disclosure requirements favor fermentation routes with verifiable Scope 3 carbon reductions. |
| Long-term Supply Agreement | Direct contracts between lignin processors and confectionery groups shorten traditional distribution channels. |
| Joint Venture | Partnerships between fragrance houses and biovanillin fermenters secure extraction-grade traceability for luxury positioning. |
Methodological Framework
Desk research of customs trade data, ECHA substance registration databases, and FSSAI regulatory filings preceded structured interviews with fermentation engineering directors, procurement leads at European confectionery groups, and regulatory affairs specialists at flavor houses. Primary fieldwork with lignin processing plant managers and downstream food manufacturer R&D directors combined with secondary validation from SEC 10-K disclosures and industry association reports. Bottom-up capacity modeling and top-down demand estimation provided triangulation across the analysis window.
Variance decomposition across product grade tiers, end-use industry applications, and regional regulatory clusters shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level demand elasticity modeling and production capacity expansion timelines. Fermentation yield improvement curves and REACH authorization renewal cycles served as industry-specific forecast inputs.
Material uncertainties — feedstock cost volatility, regulatory enforcement intensity divergence, and biovanillin batch consistency scaling — sit outside the modeled envelope. Forecasts reflect assumptions about lignin substrate availability and synthetic route compliance burden escalation. Recalibration cycles align with material shifts in ECHA evaluation protocols and EU Green Deal implementation pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Asia-Pacific Flavor and Fragrance Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Global Anthocyanin Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Flavored Salt Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Italy Food Colorants Market