
 Shelf-Stable Mezze Fermentation Ingredient Systems Market | 2026-2036
Shelf-Stable Mezze Fermentation Ingredient Systems Market Size, Share, and Industry Trends Forecast 2026-2036
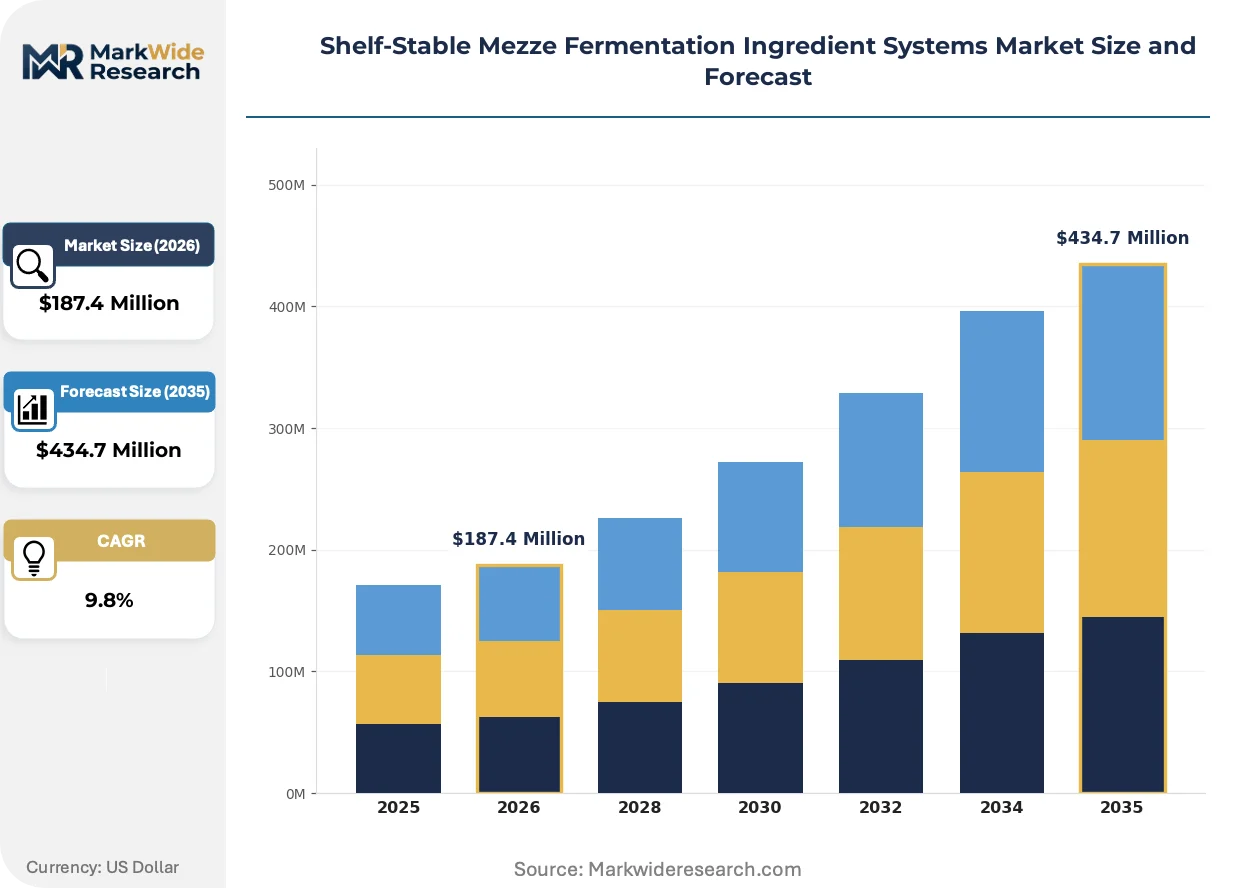
Shelf-Stable Mezze Fermentation Ingredient Systems Market Insights
Modular starter culture kits paired with standalone preservation agents is restructuring how food manufacturers configure their ingredient procurement. Kerry leverages its fermentation science platform to anchor clean-label positioning across Mediterranean applications. Corbion competes through specialized lactic acid bacteria portfolios optimized for extended shelf life in ambient mezze products.
Shelf-stable mezze fermentation ingredient systems comprise controlled microbial cultures, enzymatic preparations, and acidification agents engineered to achieve ambient stability without synthetic preservatives while preserving organoleptic integrity. Starter cultures dominate value capture due to strain-specific intellectual property and performance differentiation in hummus and tahini processing. Enzyme blends represent the fastest-expanding category as manufacturers seek accelerated fermentation cycles and consistent texture profiles in high-volume baba ganoush and dip production.
FDA food additive regulations and USDA organic certification standards govern product formulations in North America, while EFSA and EU Green Deal sustainability frameworks shape strain approval and clean-label claims across European markets. Compliance with these overlapping regimes determines market access and premium positioning for ingredient suppliers. Stakeholders must monitor evolving strain registration pathways and carbon accounting requirements to sustain competitive positioning as regulatory stringency intensifies.
Market Dynamics
EU Green Deal food waste reduction mandates are compressing synthetic preservative tolerance while accelerating clean-label fermentation adoption across Mediterranean packaged food supply chains. This regulatory pressure is restructuring ingredient procurement toward microbial preservation systems.
Growth Catalysts
- EU Green Deal Framework:Binding food waste reduction targets force manufacturers toward natural preservation pathways. Strain-optimized fermentation systems satisfy clean-label requirements without shelf-life sacrifice.
- Hummus Processing Scale-Up:Industrial tahini and hummus lines in Turkey and Lebanon require consistent acidification control. Starter culture systems deliver batch-to-batch pH stability at high throughput.
- Enzymatic Acceleration:Protease and lipase blends cut fermentation cycle times by 40-60% in baba ganoush production. Speed-to-market pressures reward enzyme-adopting facilities.
Market Restraints
- Strain IP Concentration:Proprietary lactic acid bacteria portfolios concentrate among three European culture houses. Licensing fees inflate ingredient costs for mid-tier manufacturers.
- Chickpea Price Volatility:Drought cycles in North American and Australian growing regions destabilize base material costs. Fermentation system ROI fluctuates with commodity input swings.
- EFSA Novel Strain Approval:Registration timelines for non-traditional microbes extend 18-24 months. Innovation velocity compresses against regulatory friction.
Strategic Opportunities
- Lebanese Export Infrastructure:Port modernization at Beirut and Tripoli enables ambient-stable mezze distribution to Gulf Cooperation Council markets. Fermentation ingredient demand tracks outbound cargo growth.
- Plant-Based Dairy Convergence:Yogurt-alternative manufacturers repurpose mezze-optimized cultures for cashew and oat bases. Cross-application licensing expands addressable market.
- USDA Organic Certification Pathway:Premium private-label programs specify organic-compliant preservation. Early organic strain registration captures shelf-space allocation.
Industry Challenges
- Microbiome Specialist Scarcity:Industrial strain optimization requires rare cross-training in food science and genomics. Recruitment competition with pharmaceutical fermentation intensifies.
- Legacy Equipment Retrofit Costs:Ambient-stable processing demands closed-system bioreactor investment. Capital deployment timelines strain mid-cap manufacturer balance sheets.
- Multi-Jurisdiction Label Compliance:Simultaneous FDA, EFSA, and Gulf Standard Organization claims require divergent documentation. Regulatory affairs headcount expands disproportionately to revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf-Stable Mezze Fermentation Ingredient Systems Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starter Cultures, Enzyme Blends, Acidulants, Flavor Enhancers, Preservation Agents, Texture Modifiers Application: Hummus Production, Tahini Processing, Baba Ganoush Preparation, Pickled Vegetables, Dips & Spreads, Mezze Platters End User: Food Manufacturers, Gourmet Caterers, Specialty Food Retailers, Restaurants, Foodservice Distributors, Artisan Producers Form: Powder, Liquid Concentrate, Freeze-Dried, Granules, Emulsions, Gel |
| Companies Covered | Corbion, IFF, Kerry, Novonesis, Handary, Kalsec, Lallemand, DSM-Firmenich, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf-Stable Mezze Fermentation Ingredient Systems Market Trends and Innovations
Fermentation ingredient delivery formats are fragmenting toward application-specific configurations. Technology convergence between strain engineering and enzymatic acceleration is compressing development cycles. Procurement patterns favor suppliers bundling technical service with culture supply.
Lyophilized starter culture concentrates with tunable activity levels are modularizing how manufacturers configure production lines. Mid-scale hummus processors in Greece and Turkey adopt plug-in culture sachets matched to batch volume. This technology is modularizing capital deployment by eliminating centralized fermentation infrastructure.
EFSA's 2023 updated guidance on Qualified Presumption of Safety strains tightens dossier requirements for novel microbial submissions. Culture suppliers must now submit whole-genome sequencing data and toxigenicity assessments. Small strain developers face compliance cost barriers while established players consolidate registration expertise.
Ingredient purchasing is consolidating toward multi-year supply agreements with embedded technical support. Large Mediterranean dip manufacturers bypass distributors to contract directly with Kerry and Corbion fermentation divisions. This pattern concentrates procurement power among vertically integrated food groups in Spain and Italy.
Shelf-Stable Mezze Fermentation Ingredient Systems Market Segmentation
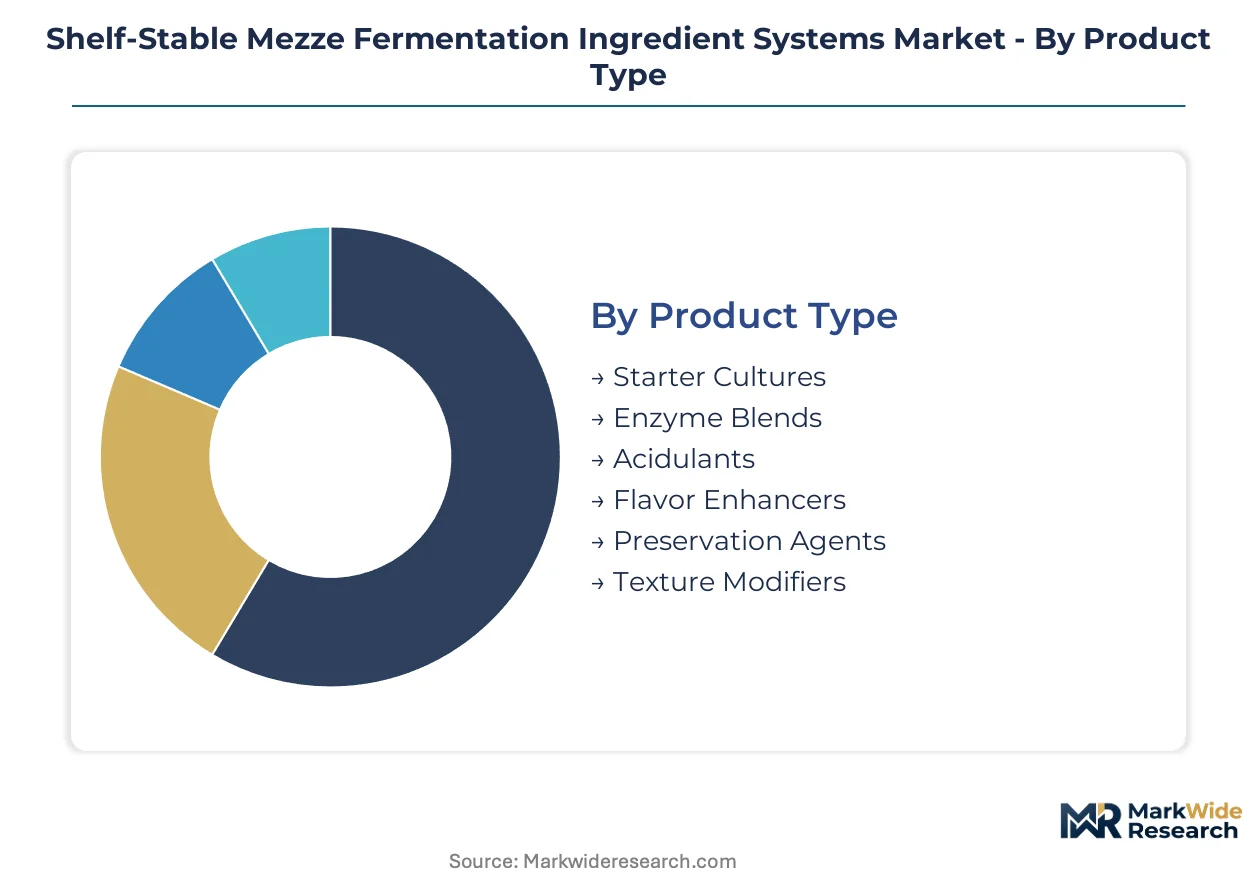
Segmentation in shelf-stable mezze fermentation ingredient systems reveals how procurement patterns diverge between industrial-scale hummus processors and artisan producers. Understanding these splits enables suppliers to calibrate strain portfolios, delivery formats, and technical service bundles to specific operational constraints.
Product Type:
Standardization dominates starter culture and acidulant supply, while enzyme blends and texture modifiers command premium customization fees based on application-specific performance targets.
- Starter Cultures:Proprietary lactic acid bacteria and yeast consortia deliver controlled acidification for ambient stability. Demand clusters with industrial hummus manufacturers in Turkey and Lebanon seeking batch-to-batch pH consistency at high throughput. Strain-specific intellectual property creates supplier stickiness and recurring licensing revenue.
- Enzyme Blends:Protease, lipase, and amylase combinations accelerate fermentation cycles and standardize texture profiles. Greek and Turkish baba ganoush processors adopt these most aggressively to compress production timelines without sacrificing organoleptic quality. Speed-to-market pressures reward facilities investing in enzymatic acceleration.
- Acidulants:Food-grade organic acids adjust final pH and enhance microbial inhibition in ambient-stable formulations.
- Flavor Enhancers:Fermentation-derived taste compounds intensify umami and depth in reduced-sodium mezze applications.
- Preservation Agents:Natural antimicrobial compounds extend shelf life without synthetic additive declarations on clean-label products.
- Texture Modifiers:Hydrocolloid and starch systems stabilize emulsions in tahini and hummus during temperature fluctuations.
Most installed capacity flows through starter cultures. Expansion is steepest in enzyme blends.
Application:
Volume concentration in hummus and tahini processing contrasts with margin-rich specialty niches in pickled vegetables and mezze platters where formulation complexity justifies premium ingredient pricing.
- Hummus Production:Industrial-scale chickpea processing requires consistent acidification control and texture stabilization. Turkish manufacturers along the Aegean coast represent the densest demand cluster, with facilities running continuous fermentation lines requiring reliable culture supply contracts.
- Tahini Processing:Sesame paste stabilization demands precise moisture management and oxidative stability. Lebanese processors in Bekaa Valley and Mount Lebanon govern regional supply, exporting ambient-stable products through modernized Beirut and Tripoli port infrastructure.
- Baba Ganoush Preparation:Smoked eggplant emulsions require enzymatic intervention to achieve uniform texture at commercial scale.
- Pickled Vegetables:Traditional fermentation preservation of cucumbers, turnips, and peppers for mezze accompaniment.
- Dips & Spreads:Multi-component ambient-stable formulations combining base ingredients with flavor and preservation systems.
- Mezze Platters:Pre-assembled combinations requiring coordinated ingredient stability across heterogeneous components.
Procurement volumes peak in hummus production. Margin expansion concentrates in mezze platters.
End User:
Food manufacturers prioritize supply security and technical support, while artisan producers trade volume discounts for flexibility in minimum order quantities and strain selection.
- Food Manufacturers:Large-scale Mediterranean dip producers in Spain and Italy contract directly with fermentation ingredient suppliers, bypassing distributors to secure multi-year agreements with embedded technical service. These vertically integrated groups concentrate procurement power and demand consistent strain performance at industrial throughput.
- Gourmet Caterers:High-end foodservice operations in Athens and Istanbul specify premium fermentation systems for differentiated mezze offerings. Reputation sensitivity drives willingness to pay for certified organic and heritage strain formulations.
- Specialty Food Retailers:Private-label programs require organic-compliant preservation pathways to capture premium shelf-space allocation.
- Restaurants:Consistent house-made mezze quality depends on reliable starter culture performance across variable kitchen conditions.
- Foodservice Distributors:Broadline suppliers aggregate demand across multiple operator types, favoring standardized ingredient specifications.
- Artisan Producers:Small-batch operations in rural Greece and Cyprus seek modular culture formats with low capital requirements.
Revenue concentration sits with food manufacturers. Fastest account growth emerges among gourmet caterers.
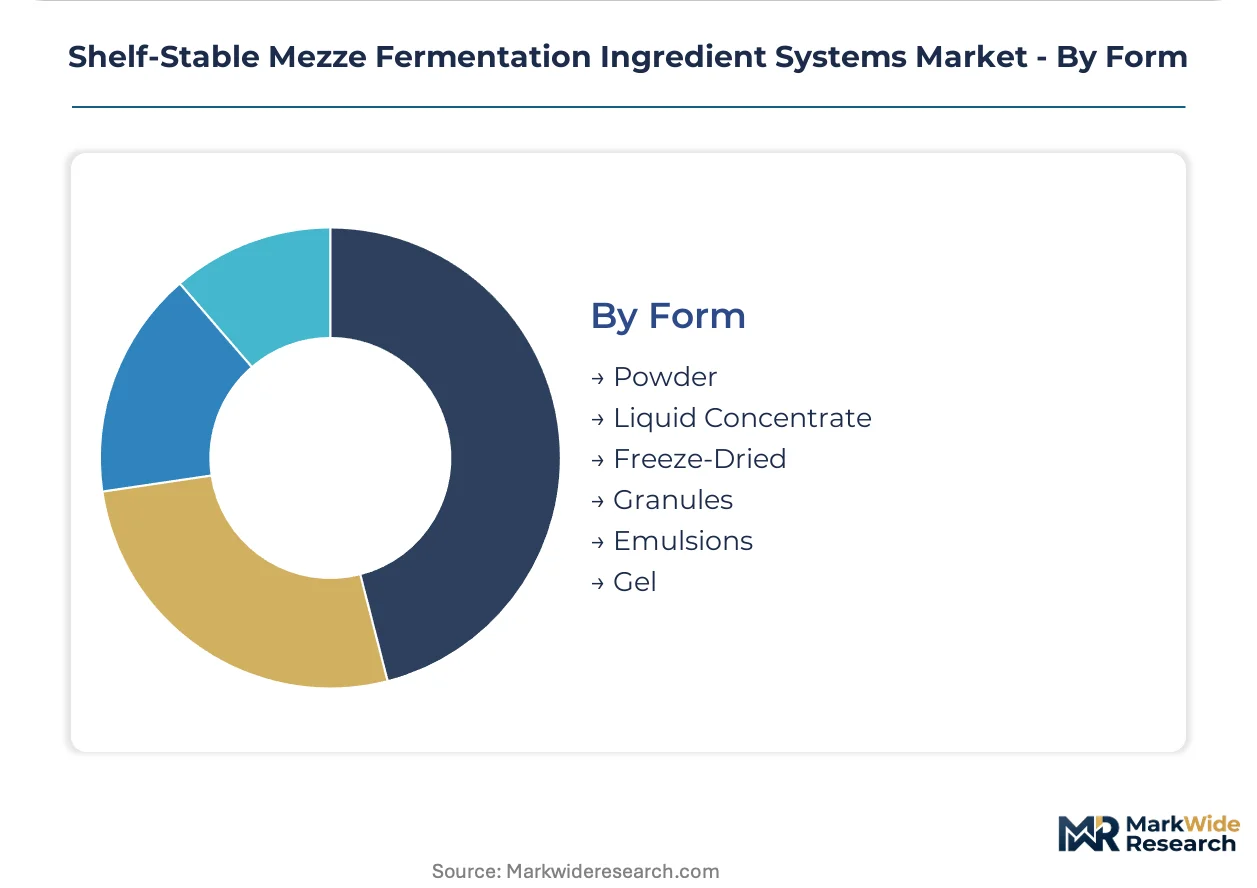
Form:
Powder and freeze-dried formats minimize cold chain dependency, while liquid concentrates and emulsions serve integrated processors with dedicated fermentation infrastructure.
- Powder:Spray-dried culture preparations offer extended ambient stability and simplified logistics. Mid-scale processors throughout Greece and Turkey adopt powder formats for inventory flexibility and reduced refrigeration capital.
- Liquid Concentrate:High-activity fermentation inoculants for facilities with on-site propagation capability. Large hummus manufacturers in Lebanon prefer liquid formats for direct dosing into continuous processing lines, eliminating rehydration steps.
- Freeze-Dried:Lyophilized preparations with tunable activity levels enable precise batch matching.
- Granules:Free-flowing particulate formats for automated dosing systems in high-volume production environments.
- Emulsions:Pre-dispersed lipid-based delivery systems for hydrophobic active ingredients in oil-rich tahini applications.
- Gel:Structured matrices protecting sensitive strains through gastric transit in probiotic-enhanced mezze variants.
Distribution volumes favor powder. Adoption momentum builds in liquid concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation-based preservation of mezze originated in the Levant and Anatolia, where olive oil and lactic acid cultures enabled ambient storage of chickpea and eggplant preparations long before industrial refrigeration. Modern ingredient systems now export these traditional methods to packaged food manufacturers worldwide.
Turkey
Industrial hummus production along the Aegean coast drives concentrated demand for starter culture systems with batch-to-batch pH consistency. The Turkish Food Codex aligns with EU Green Deal sustainability frameworks, accelerating clean-label preservation adoption. Izmir and Manisa host the densest processor clusters, where facilities run continuous fermentation lines requiring reliable culture supply contracts.
Lebanon
Tahini stabilization and ambient-stable dip production dominate fermentation ingredient procurement from Bekaa Valley processors. Port modernization at Beirut and Tripoli enables Gulf Cooperation Council export expansion, tracking outbound cargo growth. The Lebanese Ministry of Economy's food export promotion programs subsidize cold chain elimination through fermentation-based preservation.
Greece
Artisan producers in rural Macedonia and Thessaly adopt modular lyophilized culture formats with low capital requirements. EU Green Deal food waste reduction mandates compress synthetic preservative tolerance across Mediterranean packaged food supply chains. Athens-based gourmet caterers specify premium fermentation systems for differentiated mezze offerings, driving certified organic strain demand.
Italy
Vertically integrated food groups in Emilia-Romagna and Lombardy contract directly with fermentation ingredient suppliers, bypassing distributors for multi-year technical service agreements. EFSA's updated Qualified Presumption of Safety guidance tightens novel microbial submission requirements. Bologna and Modena processors lead adoption of enzymatic acceleration for high-volume baba ganoush production.
United States
USDA organic certification pathways attract premium private-label programs specifying organic-compliant preservation for shelf-space allocation. FDA food additive regulations govern strain approval and clean-label claims in North American markets. California and New York processors experiment with cross-application licensing of mezze-optimized cultures into plant-based dairy alternatives.
Shelf-Stable Mezze Fermentation Ingredient Systems Market Competitive Landscape
The competitive structure tilts toward multinational culture houses with proprietary strain portfolios and embedded technical service capabilities. Three European suppliers concentrate proprietary lactic acid bacteria intellectual property, extracting licensing fees that inflate ingredient costs for mid-tier manufacturers. Strategic moves center on multi-year supply agreements with direct manufacturer contracting and enzymatic acceleration technology licensing to compress fermentation cycle times.
Among diversified fermentation science platforms, Kerry and Corbion occupy anchor positions representing integrated technical service bundling with culture supply. Novonesis exemplifies the specialized microbial culture archetype following its formation through Chr. Hansen and Novozymes consolidation. Lallemand sits within the yeast and bacteria specialist tier with heritage strain development capabilities. These three companies structure procurement patterns as large Mediterranean dip manufacturers bypass distribution channels entirely.
| Leading Market Players |
|---|
| Corbion |
| IFF |
| Kerry |
| Novonesis |
| Handary |
| Kalsec |
| Lallemand |
| DSM-Firmenich |
| Angel Yeast |
| Others |
Pricing and Supply Chain Analysis
Chickpea futures volatility cascades through fermentation ingredient supply chains, compressing margins for mid-tier processors while amplifying pricing power among culture houses with captive strain portfolios. Turkish and Lebanese manufacturers absorb commodity swings through long-term offtake contracts, whereas Greek artisan producers face spot-market exposure that stratifies procurement tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs starter culture supply, with organic certification and strain heritage commanding 15-25% uplifts over conventional tiers. Price differentiation hinges on EFSA dossier completeness and embedded technical service depth, not merely culture activity levels. Cost compression in standard-tier enzyme blends is intensifying because Novonesis and Kerry are bundling accelerated fermentation consulting with volume commitments. Mid-tier Turkish hummus processors show highest price sensitivity, while Athens-based gourmet caterers accept premium positioning for heritage strain provenance.
Supply Chain Analysis
Single-source vulnerability sits with Dutch and Danish culture houses that concentrate proprietary lactic acid bacteria intellectual property. Manufacturing draws from fermentation capacity in the Netherlands, Denmark, and France, with freeze-drying infrastructure concentrated near Brussels and Copenhagen. Raw material dependencies include whey permeate for culture propagation, nitrogen sources for biomass yield, and specialized packaging films for oxygen barrier protection. Tariff exposure on EU-origin cultures entering Gulf Cooperation Council markets threatens margin stability for Lebanese exporters. Distribution runs through direct manufacturer contracting for large Mediterranean dip producers, bypassing traditional ingredient distributors entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU Green Deal compliance costs in Western Europe and Lebanon's subsidized export infrastructure, where fermentation-based preservation eliminates cold-chain capital requirements.
For Market Incumbents: Anchor clean-label positioning through early organic strain registration with USDA and EFSA, locking shelf-space allocation before regulatory stringency peaks. Defend against emerging enzymatic acceleration specialists by acquiring proprietary protease portfolios or licensing exclusive distribution rights. Backward integration into culture propagation infrastructure in Izmir and Manisa secures supply continuity against Dutch-Danish concentration risk. For New Entrants and Emerging Players: Enter via modular lyophilized culture formats targeting Greek and Cypriot artisan producers excluded from distributor minimums. White-space concentrates in probiotic-enhanced mezze variants requiring gastric-stable gel delivery matrices, plus cross-application licensing to plant-based dairy manufacturers in California and New York. Go-to-market leverage rests on embedded microbiome technical service, not commodity culture supply. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized enzymatic acceleration developers holding 40-60% cycle-time reduction IP. Five-to-ten-year viability favors targets with dual EFSA-FDA strain registration expertise and existing technical service headcount. Signal to monitor: Lebanese port throughput recovery at Beirut and Tripoli as inflection indicator for Gulf-bound ambient-stable mezze demand.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Strain Registration | Unlocks EU market access and commands premium positioning against unregistered competitors. |
| Enzymatic Acceleration Licensing | Compresses baba ganoush production timelines for high-volume Italian and Spanish processors. |
| Direct Manufacturer Contracting | Bypasses distributor margins and embeds technical service for Turkish industrial hummus lines. |
| Organic Certification Pathway | Captures USDA-compliant private-label shelf-space allocation in premium retail channels. |
| Lebanese Export Infrastructure Leverage | Exploits subsidized cold-chain elimination for Gulf Cooperation Council market penetration. |
Research Methodology
Bottom-up fermentation ingredient demand modeling reconciled against top-down culture house production tracking forms the analytical core. Primary interviews with plant managers at Turkish and Lebanese hummus processors, procurement leads at Spanish and Italian vertically integrated food groups, and regulatory affairs directors at culture suppliers validated volume assumptions. Secondary sources included EFSA novel food submissions, EU Green Deal implementation progress reports, Lebanese Ministry of Economy export statistics, and customs records tracking ambient-stable mezze shipments through Beirut and Tripoli. Triangulation between end-use consumption patterns and supply-side capacity utilization reconciles demand-supply balances.
Historical trendline analysis across installed fermentation capacity and culture shipment volumes established baseline growth trajectories. Segmentation modeling incorporated product type, application, end-user category, and geographic production hub dimensions. CAGR derivation rested on regression analysis of processor expansion announcements, port modernization timelines, and regulatory approval velocity. Forecast inputs included EFSA dossier submission rates, enzymatic acceleration adoption curves at Italian baba ganoush facilities, and cross-application licensing activity in plant-based dairy alternatives.
Inputs from culture house production disclosures and Lebanese export promotion filings were available through the study window; gaps in proprietary strain performance data introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding EFSA approval timelines, chickpea harvest stability, and Gulf Cooperation Council import tariff regimes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
D-Limonene Market