
 Oil Soluble Flavors Market | 2026-2036
Oil Soluble Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Soluble Flavors Market Analytics
Southeast Asia is reshaping competitive dynamics in oil-soluble flavors through expanded extraction and compounding capacity in Indonesia and Vietnam. Givaudan leverages backward integration into spice and herb sourcing to secure aromatic raw material streams. Firmenich anchors its position through biotechnology-driven molecule synthesis for high-heat-stable flavor variants. Kerry Group competes by embedding flavor systems directly into customer co-development programs across European and North American food manufacturers.
Oil-soluble flavors comprise lipophilic aromatic compounds—typically terpenes, esters, aldehydes, and oleoresins—dispersed in carrier oils such as MCT, sunflower, or soybean oil, engineered to withstand temperatures above 150°C without volatilization during frying or baking processes. The natural product type commands premium positioning as clean-label formulations restrict synthetic additive use in retail-facing food products. Synthetic variants still dominate volume in industrial bakery applications where cost thresholds override label claims. Liquid form leads distribution due to ease of incorporation into fat-based matrices, though spray-dried formats are gaining traction in powdered seasoning blends for snack coatings.
The FDA governs flavor substance safety through GRAS determinations and Food Additive Regulations under 21 CFR, while the European Food Safety Authority enforces purity specifications through EU Regulation 1334/2008 on flavorings and food ingredients with flavoring properties. EFSA evaluations of thermal degradation byproducts now influence reformulation decisions among suppliers seeking unified product platforms for transatlantic distribution. Stakeholders must track evolving FEMA GRAS assessments and EFSA re-evaluations of key carriers to anticipate reformulation cycles and avoid stranded inventory in dual-regulated supply chains.
Market Dynamics
Clean-label reformulation is compressing synthetic flavor margins while concentrating procurement power among bakery and confectionery manufacturers seeking EU Green Deal-compliant natural alternatives. This structural shift is redrawing supplier relationships across the value chain.
Growth Catalysts
- REACH compliance mandates:European manufacturers are accelerating natural oil-soluble flavor adoption to meet tightening purity standards for imports under ECHA enforcement.
- High-heat stability demand:Industrial frying and baking above 150°C requires specialized terpene and oleoresin formulations that resist thermal degradation.
- Cologne-Hamburg cluster concentration:German confectionery hubs are driving specialized procurement for customized flavor profiles at scale.
Market Restraints
- Carrier oil price volatility:MCT and sunflower oil input costs fluctuate with commodity crop yields, squeezing compounder margins unpredictably.
- Raw material geographic concentration:Spice and herb aromatic sourcing clusters in Southeast Asia create supply vulnerability during regional climate events.
- Thermal degradation byproduct scrutiny:EFSA re-evaluations of heat-generated impurities are extending reformulation cycles and stranding legacy inventories.
Strategic Opportunities
- Indonesia extraction capacity expansion:Local oleoresin processing infrastructure is reducing import dependency for ASEAN food manufacturers.
- Biotechnology-driven molecule synthesis:Precision fermentation and enzymatic conversion are opening pathways to rare terpenes without agricultural cultivation constraints.
- Spray-dried format penetration:Powdered oil-soluble flavors are capturing snack seasoning applications previously served by liquid-only systems.
Industry Challenges
- Dual-regulation compliance talent scarcity:Formulation chemists capable of navigating simultaneous FDA GRAS and EFSA 1334/2008 requirements command premium compensation.
- Legacy equipment retrofit costs:Spray-drying infrastructure investments strain mid-tier flavor houses competing against integrated multinationals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Soluble Flavors Market |
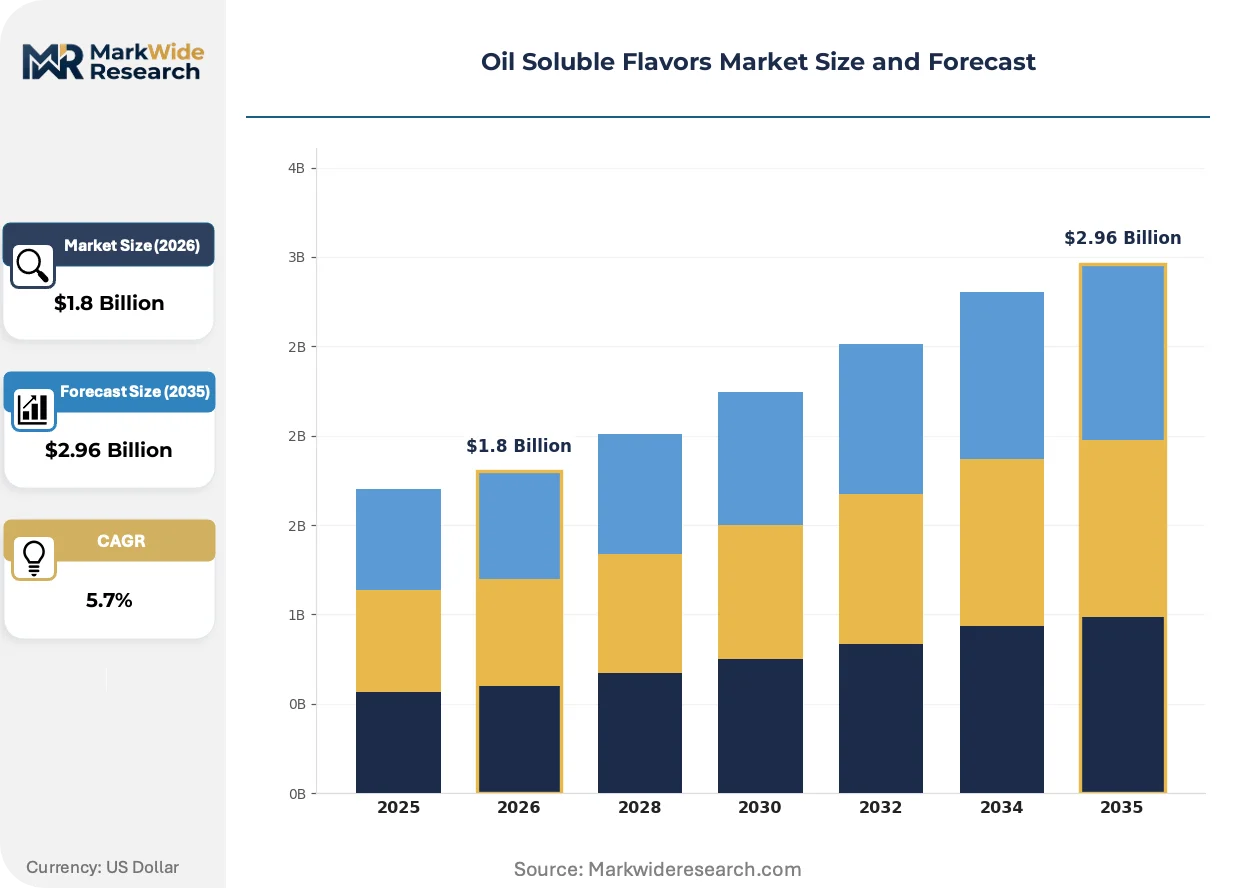
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Blends Application: Beverages, Bakery, Confectionery, Snacks Form: Liquid, Powder, Spray-dried, Emulsion End User: Food Industry, Beverage Manufacturers, Cosmetic Companies, Nutraceuticals |
| Companies Covered | Givaudan, Firmenich, Symrise, International Flavors & Fragrances, Mane, Kerry Group, Sensient, Takasago, Archer Daniels Midland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Soluble Flavors Market Evolving Landscape
Biotechnology and thermal stability engineering are converging to redefine competitive advantage in oil-soluble flavor production. Suppliers are racing to align innovation pipelines with diverging transatlantic regulatory timelines.
Enzymatic ester synthesis is migrating from laboratory-scale demonstration to commercial deployment for high-value aldehyde production. Specialty chemical producers in the Netherlands and Switzerland are scaling bioreactor capacity to serve premium confectionery accounts. This technology is migrating from cost-prohibitive niche applications to mainstream bakery formulations, compressing the price gap between natural and synthetic variants.
EFSA's expanded thermal degradation byproduct evaluations under EU Regulation 1334/2008 are forcing systematic reformulation of frying-stable flavor systems. Manufacturers serving transatlantic markets must now maintain parallel inventory streams or pursue lowest-common-denominator formulations. High-heat bakery applications in Southern Europe face the steepest compliance costs as local regulators anticipate Brussels enforcement patterns.
Co-development partnerships between flavor houses and finished goods manufacturers are displacing transactional spot purchasing in North American contract baking. Long-term technical collaboration agreements now govern two-thirds of volume commitments among top-20 snack producers. This relationship compression is most visible in the US Midwest, where regional bakery co-manufacturers consolidate supplier panels to three preferred partners.
Oil Soluble Flavors Market Segmentation
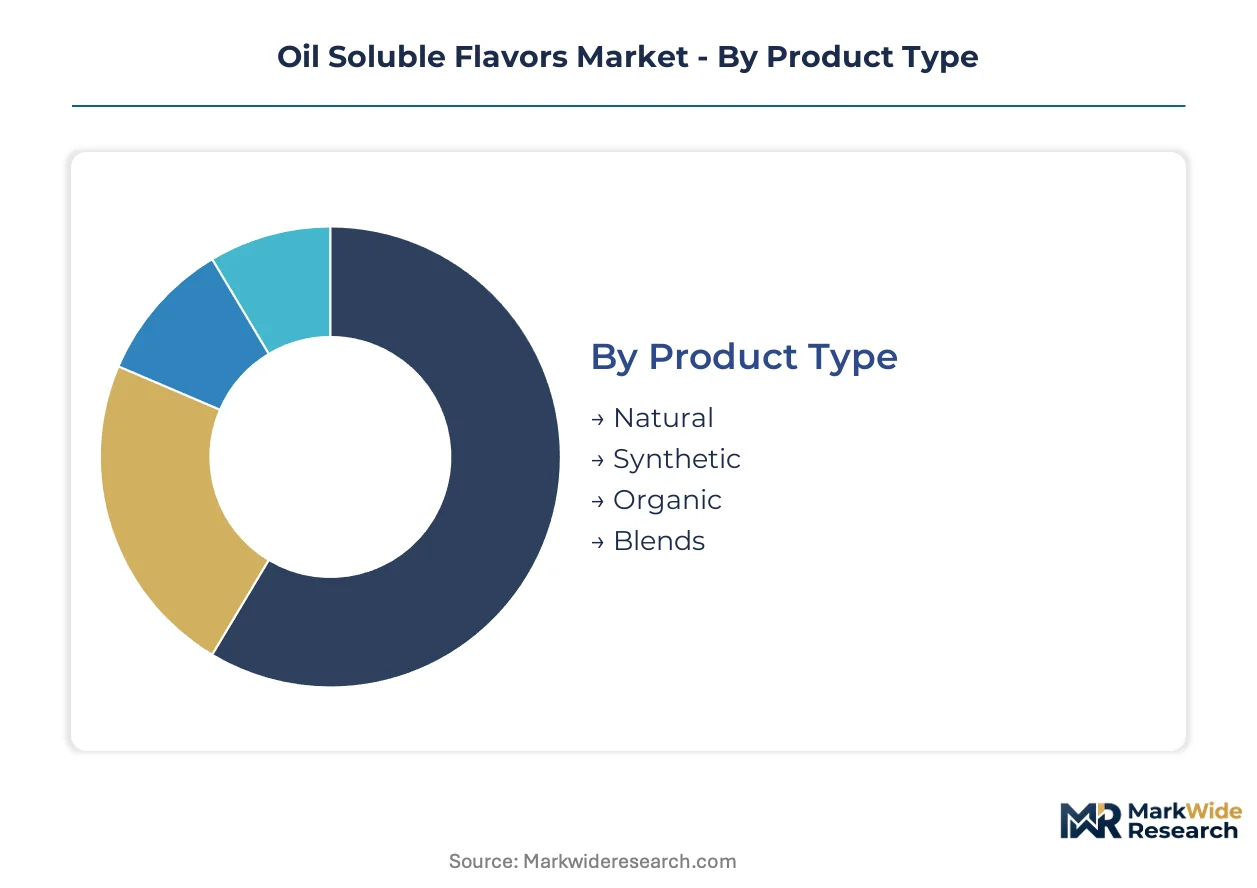
Oil-soluble flavor segmentation reveals how formulation requirements diverge across thermal stability needs, regulatory compliance thresholds, and carrier system compatibility. Procurement patterns in this market track closely to the technical service intensity each segment demands from compounders.
Product Type:
After-sales technical support intensity varies sharply across this category, with natural variants requiring ongoing reformulation assistance as raw material batches fluctuate in aromatic profile.
- Natural:Derived from spice oleoresins, herb extracts, and fruit essential oils dispersed in carrier oils. German confectionery manufacturers around Cologne and Hamburg drive specialized procurement for customized terpene profiles that withstand high-heat processing without degradation.
- Synthetic:Manufactured through chemical synthesis of esters, aldehydes, and ketones engineered for precise flavor replication and batch consistency. Industrial bakery applications in cost-sensitive segments favor these variants where EU Green Deal label claims carry less weight than price thresholds.
- Organic:Certified organic aromatic compounds sourced from organically cultivated botanicals with full traceability documentation. Premium retail brands seeking dual FDA-EFSA compliance for transatlantic distribution concentrate demand here.
- Blends:Hybrid formulations combining natural extracts with synthetic molecules to balance cost, stability, and label positioning. Co-manufacturers in the US Midwest leverage these for flexible procurement across multiple customer specifications.
Natural holds the largest share; momentum sits with Organic as clean-label reformulation accelerates.
Application:
Volume concentration patterns in this category map directly to processing temperature requirements and the specialized heat-stable formulations each application demands.
- Beverages:Lipophilic flavor systems for dairy-based drinks, flavored oils, and functional beverages requiring oil dispersion rather than water solubility. Southeast Asian extraction hubs in Indonesia and Vietnam supply oleoresin inputs for regional beverage manufacturing expansion.
- Bakery:High-heat-stable terpene and oleoresin formulations engineered to resist volatilization above 150°C during industrial baking processes. EFSA thermal degradation byproduct evaluations are extending reformulation cycles for frying-stable systems in Southern European markets.
- Confectionery:Precision-flavored fat-based systems for chocolate, coatings, and filled products demanding precise melt-point compatibility. Biotechnology-driven molecule synthesis from Swiss and Dutch producers is penetrating premium confectionery accounts.
- Snacks:Oil-based seasoning carriers for fried and extruded products where flavor must survive aggressive thermal processing. Spray-dried format adoption is capturing seasoning applications previously limited to liquid-only systems.
Bakery commands the greatest volume; snack applications are climbing the fastest as powdered format technology advances.
Form:
Supply chain configuration in this category determines distribution economics, with liquid formats dominating bulk tanker delivery while dried forms reduce freight costs for distant markets.
- Liquid:Standard oil-dispersed aromatic compounds in MCT, sunflower, or soybean carrier oils for direct incorporation into fat-based matrices. Cologne-Hamburg confectionery clusters prefer liquid delivery for continuous processing lines.
- Powder:Absorbed or plated flavors where liquid concentrates are fixed onto carbohydrate carriers for dry blend compatibility. Snack seasoning manufacturers value the handling efficiency and reduced leakage risk.
- Spray-dried:Encapsulated oil-soluble flavors where aromatic cores are protected within modified starch or gum arabic shells. ASEAN food manufacturers are adopting these for extended shelf stability in tropical climates.
- Emulsion:Oil-in-water or water-in-oil dispersed systems bridging lipophilic flavors into aqueous applications. Beverage manufacturers leverage these for visual stability in cloudy drink formulations.
Liquid retains dominant share; spray-dried is gaining share fastest as encapsulation technology costs decline.
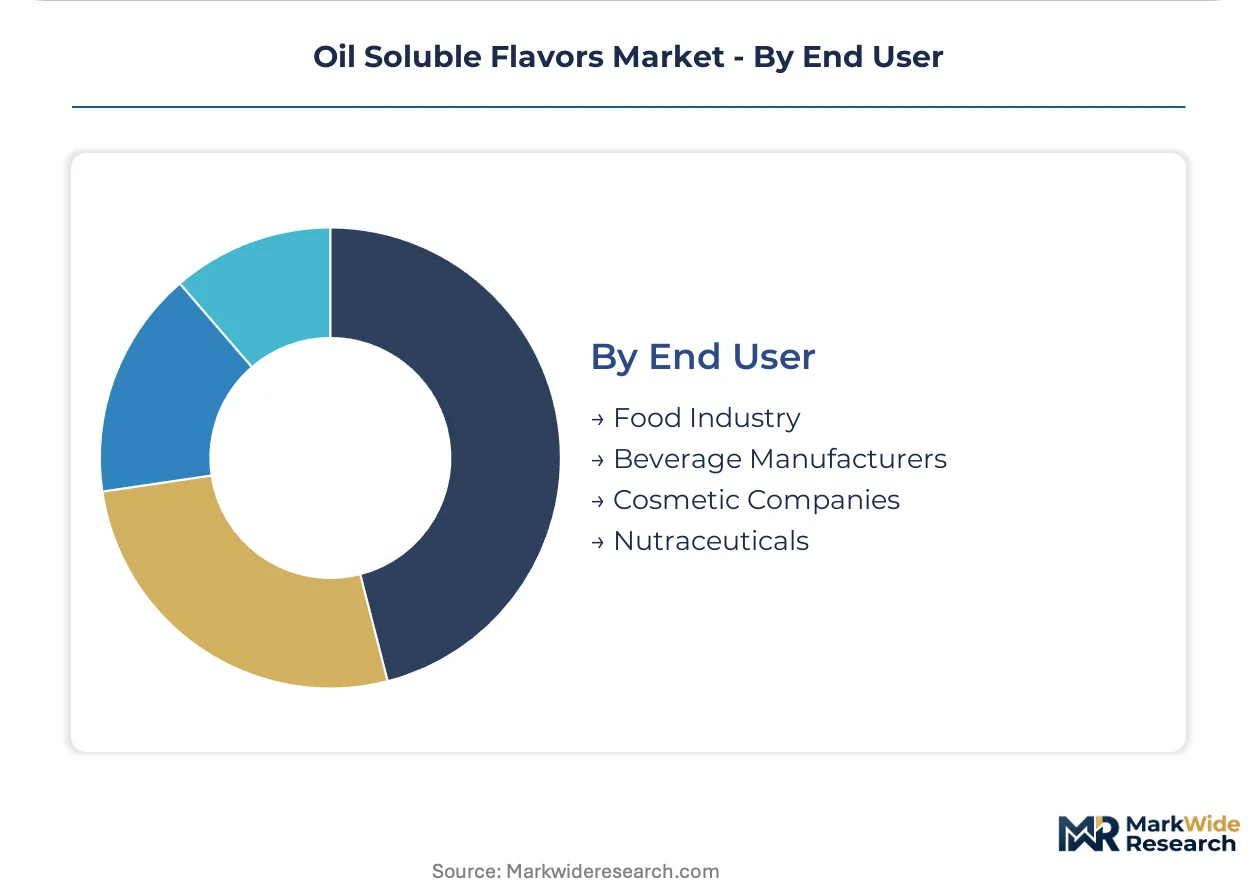
End User:
Customer technical sophistication in this category ranges from commodity procurement by large food manufacturers to specialized formulation partnerships with nutraceutical developers.
- Food Industry:Broad-spectrum manufacturers of processed foods, baked goods, and prepared meals requiring scalable flavor systems. Long-term co-development agreements now govern two-thirds of volume commitments among top-20 producers.
- Beverage Manufacturers:Dairy, functional drink, and flavored oil producers needing stable oil-dispersed flavor throughout shelf life. These accounts prioritize GRAS documentation for FDA compliance in export markets.
- Cosmetic Companies:Personal care and fragrance applications where oil-soluble aromatics serve as functional ingredients rather than flavor additives. REACH compliance mandates from ECHA are tightening purity specifications for European cosmetic flavor imports.
- Nutraceuticals:Supplement and functional food producers masking active ingredients with palatable oil-based flavor systems. Biotechnology-derived rare terpenes from precision fermentation are opening novel formulation pathways for this segment.
Food Industry holds the largest share; nutraceuticals show the steepest expansion trajectory as functional food formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA anchors European demand through EU Regulation 1334/2008 enforcement, while FDA GRAS determinations govern transatlantic formulation strategies. Southeast Asian extraction hubs and German confectionery clusters concentrate specialized procurement.
Germany
Cologne and Hamburg drive concentrated confectionery demand for customized terpene profiles. REACH compliance mandates from ECHA accelerate natural oil-soluble flavor adoption among importers. The Rhineland-Palatinate region hosts compounding facilities serving industrial bakery accounts.
United States
Midwest contract baking co-manufacturers consolidate supplier panels to three preferred partners. FDA Food Additive Regulations under 21 CFR govern thermal stability requirements for frying applications. Chicago-area flavor houses embed technical collaboration into two-thirds of volume commitments.
Indonesia
Local oleoresin processing infrastructure reduces ASEAN food manufacturer import dependency. National food safety regulations align with Codex standards for oleoresin purity specifications. Java-based extraction facilities expand capacity to serve regional beverage manufacturing growth.
Switzerland
Swissmedic oversight applies to cosmetic flavor imports requiring REACH-equivalent documentation. Precision fermentation specialists scale bioreactor capacity for rare terpene production. Basel-region biotechnology clusters anchor high-heat-stable molecule synthesis.
Vietnam
Expanded spice and herb aromatic sourcing supports regional compounding operations. Ministry of Health circulars govern food additive safety assessments for imported oleoresins. Ho Chi Minh City processing zones concentrate spray-drying infrastructure investments.
Oil Soluble Flavors Market Competitive Landscape
Integrated multinationals and specialized regional compounders split the market along technical service intensity lines. Consolidation pressure concentrates procurement power among bakery and confectionery manufacturers seeking unified transatlantic compliance. Three archetypes dominate: biotechnology-driven synthesis specialists, backward-integrated spice sourcers, and embedded co-development partners. Competitive moves center on capacity expansion in Southeast Asian extraction zones and strategic partnerships for dual-regulation formulation expertise.
Within the biotechnology-driven tier, Firmenich and Givaudan exemplify divergent sourcing strategies. Firmenich occupies a position anchored in Swiss precision fermentation capabilities. Givaudan represents backward integration into agricultural aromatic streams. Kerry Group sits within the embedded partnership archetype, with its Irish public limited company structure supporting long-term technical collaboration frameworks.
| Leading Market Players |
|---|
| Givaudan |
| Firmenich |
| Symrise |
| International Flavors & Fragrances |
| Mane |
| Kerry Group |
| Sensient |
| Takasago |
| Archer Daniels Midland |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors carry oleoresin concentrates from Southeast Asian extraction hubs into European compounding facilities, with container rate volatility feeding directly into MCT carrier oil cost pass-throughs and downstream price stratification across natural, synthetic, and organic grade tiers.
Pricing Analysis
Geographic price spreads between Indonesian oleoresin feedstock and German finished flavor deliveries compress compounder margins when freight rates spike. Pricing stratifies across premium, standard, and economy tiers anchored to EU Organic certification, REACH compliance documentation, and volume commitment scale. Cost compression in synthetic variants is intensifying as bakery manufacturers reformulate toward natural alternatives. Industrial bakery accounts exhibit highest price sensitivity; premium confectionery and nutraceutical developers show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize procurement between German confectionery clusters and Southeast Asian spice sourcers, straining working capital for mid-tier compounders. Supply concentration rests on Indonesia, Vietnam, and India for oleoresin extraction; the Netherlands and Switzerland for biotechnology synthesis. Raw material dependencies include turmeric oleoresin, vanilla extract, and MCT carrier oils. Single-source vulnerability concentrates in climate-exposed Indonesian spice cultivation. Distribution runs through bulk tanker liquid delivery to Cologne-Hamburg industrial zones and spray-dried powder shipments to ASEAN snack manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
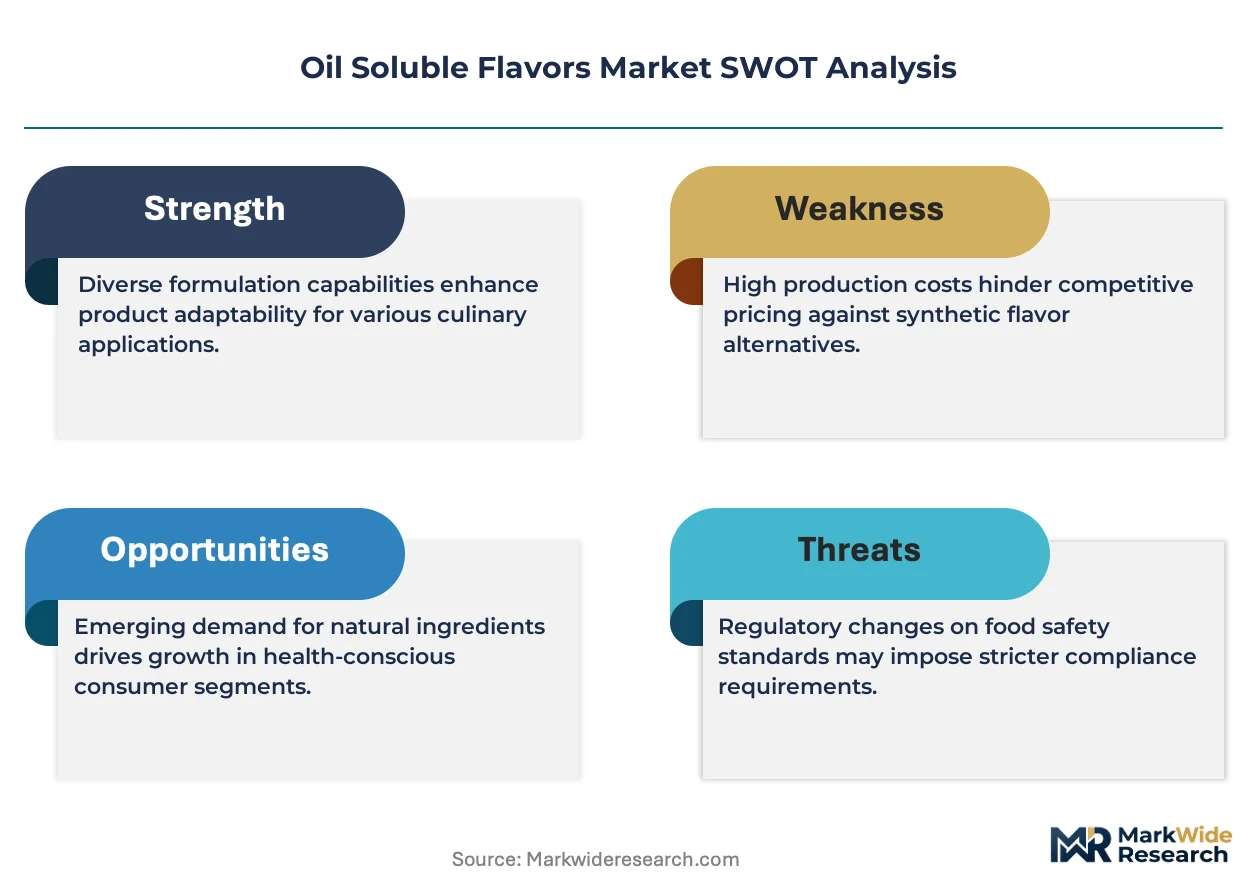
Oil-soluble flavor incumbents face substitution pressure from enzymatic synthesis pathways that bypass agricultural cultivation entirely, threatening the traditional spice-sourcing moat.
For Market Incumbents: Build regulatory expertise moats by embedding dual FDA-EFSA formulation teams within customer technical service units. Deepen backward integration into Indonesian oleoresin processing infrastructure to secure aromatic raw material streams against climate disruption. Counter biotechnology-driven molecule synthesis entrants by accelerating high-heat stability patent filings. For New Entrants and Emerging Players: Establish a beachhead in spray-dried format production for ASEAN snack seasoning applications where encapsulation technology costs are declining fastest. Target nutraceutical accounts seeking rare terpene formulations from precision fermentation, as this segment shows steepest expansion trajectory. Pursue co-development partnership structures rather than transactional spot sales to secure volume commitments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-driven synthesis specialists with commercial-scale bioreactor capacity over traditional agricultural extraction plays. Long-term viability over the next decade hinges on defensible intellectual property in thermal stability engineering and regulatory dossier depth. Watch EFSA thermal degradation byproduct enforcement patterns as the inflection signal for reformulation-driven demand surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleoresin Processing | Captures Indonesian spice aromatic streams before competitor procurement locks supply. |
| Dual-Regulation Formulation Certification | Enables unified product platforms for transatlantic distribution without parallel inventory. |
| Precision Fermentation Scale-Up | Opens rare terpene production pathways independent of agricultural cultivation constraints. |
| Spray-Drying Infrastructure Investment | Captures snack seasoning applications from liquid-only systems in tropical climates. |
| Co-Development Partnership Structuring | Displaces transactional purchasing through embedded technical collaboration agreements. |
Research Methodology
The analysis maps natural extraction, synthetic chemistry, biotechnology synthesis, and hybrid blend sub-sectors, each validated through formulation chemists, procurement directors at bakery and confectionery manufacturers, regulatory affairs specialists, and flavor house technical sales executives. Primary interview findings triangulated against EFSA re-evaluation databases, FDA GRAS notice filings, EU customs trade data for oleoresin imports, and REACH registration dossiers. Bottom-up segment sizing cross-checked with top-down market reconstruction.
Assumptions held fixed include EFSA enforcement timelines for thermal degradation byproducts, FDA GRAS determination pathways, and biotechnology cost reduction curves; variables stress-tested encompass carrier oil commodity price bands, freight rate corridors, and climate event frequency in Southeast Asian growing regions. The projection horizon spans product type, application, form, and end user dimensions, with CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated oleoresin yield projections, bioreactor capacity buildout schedules, and reformulation cycle timing across regulated jurisdictions.
Stress conditions across MCT and sunflower oil price volatility, EFSA re-evaluation acceleration, and Indonesian climate disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Egypt Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Global Natural Food Colorants Market