
 Farnesol Market | 2026-2036
Farnesol Market Size, Share, and Industry Trends Forecast 2026-2036
Farnesol Market Analysis
Subscription-based technical service layers around fragrance formulation is hardening what buyers expect from farnesol suppliers. Symrise AG leverages its integrated aroma-molecule platform to sustain long-term contracts with European cosmetics houses. BASF SE anchors global production scale for terpene-derived ingredients, while International Flavors & Fragrances differentiates through biotechnology routes to farnesol synthesis.
Farnesol is an acyclic sesquiterpene alcohol with the molecular formula C15H26O, typically extracted from essential oils or produced via fermentation of yeast strains engineered for terpene pathways; it functions primarily as a natural deodorant active, antimicrobial agent, and fragrance fixative across personal care formulations. The cosmetics segment dominates volume consumption due to farnesol's dual role as both functional ingredient and scent component in premium skincare lines. Within application categories, skincare absorbs the largest share of farnesol supply, though haircare represents the fastest-expanding demand pool as scalp-health positioning gains traction in mass-market channels.
REACH registration requirements in Europe and FDA oversight of cosmetic ingredient safety in the United States shape formulation standards and supplier qualification protocols for farnesol deployment. ECHA's evolving restrictions on certain synthetic preservatives redirect formulators toward farnesol as a compliant antimicrobial alternative in rinse-off and leave-on products. Stakeholders must monitor regulatory divergence between EU hazard classification updates and US cosmetic modernization legislation to anticipate reformulation cycles and raw-material qualification timelines.
Market Dynamics
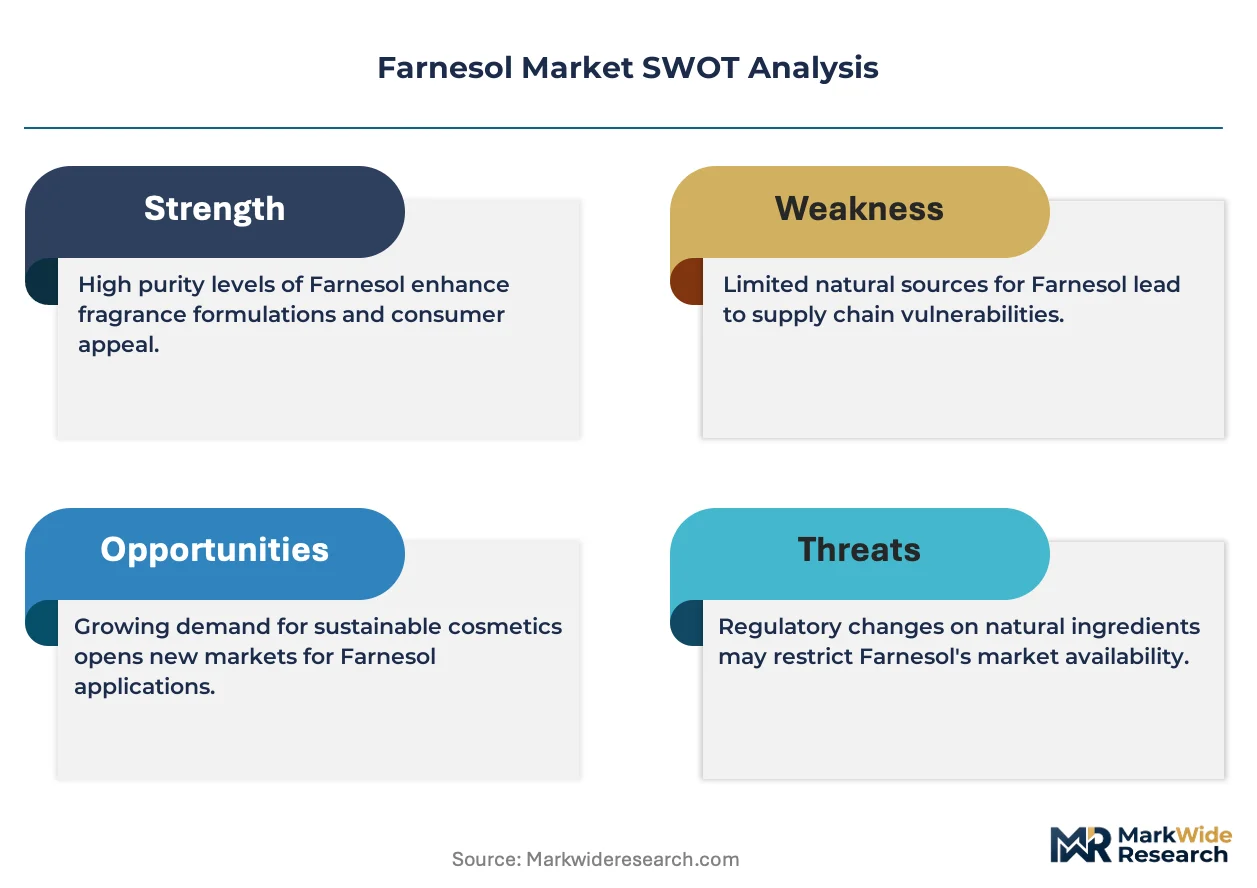
REACH registration requirements in Europe are compressing the synthetic preservative supply base, redirecting formulator procurement toward farnesol as a compliant antimicrobial alternative in rinse-off and leave-on cosmetic products.
Growth Catalysts
- ECHA preservative restrictions:REACH Annex V updates are disqualifying conventional synthetic antimicrobials from deodorant formulations, creating immediate substitution demand for farnesol's bacteriostatic properties.
- Clean-label positioning:Premium skincare houses in France and Germany are reformulating around natural-identical terpene alcohols to meet retailer clean-beauty certification standards.
- Fermentation pathway maturation:Engineered yeast strain development is reducing batch-to-batch variability in biotech-derived farnesol, improving supply security for fragrance compounders.
Market Restraints
- Feedstock volatility:Essential oil extraction from acacia and neroli sources faces agricultural yield fluctuation tied to Mediterranean climate patterns.
- Supplier concentration:Commercial-scale farnesol synthesis remains concentrated among three German chemical manufacturers with captive terpene feedstock access.
- Technical substitution:Phenoxyethanol and ethylhexylglycerin blends retain cost advantages in mass-market deodorant segments where label claims are less stringent.
Strategic Opportunities
- Scalp-health positioning:Haircare brands are incorporating farnesol into pre-shampoo treatments targeting microbiome balance, opening volume demand outside traditional skincare.
- US cosmetic modernization:FDA's expanded post-market surveillance authority is elevating documentation requirements where farnesol's established safety profile offers compliance advantages.
- Biotech-differentiated supply:Fermentation-derived farnesol with carbon-14 verification commands premium positioning in certified natural fragrance portfolios.
Industry Challenges
- REACH dossier maintenance:Extended one substance, one registration obligations require ongoing toxicological data generation that strains mid-tier supplier resources.
- Bioprocess scale-up:Transitioning from pilot-scale yeast fermentation to industrial bioreactor operation demands specialized biochemical engineering talent in short supply across European contract manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farnesol Market |
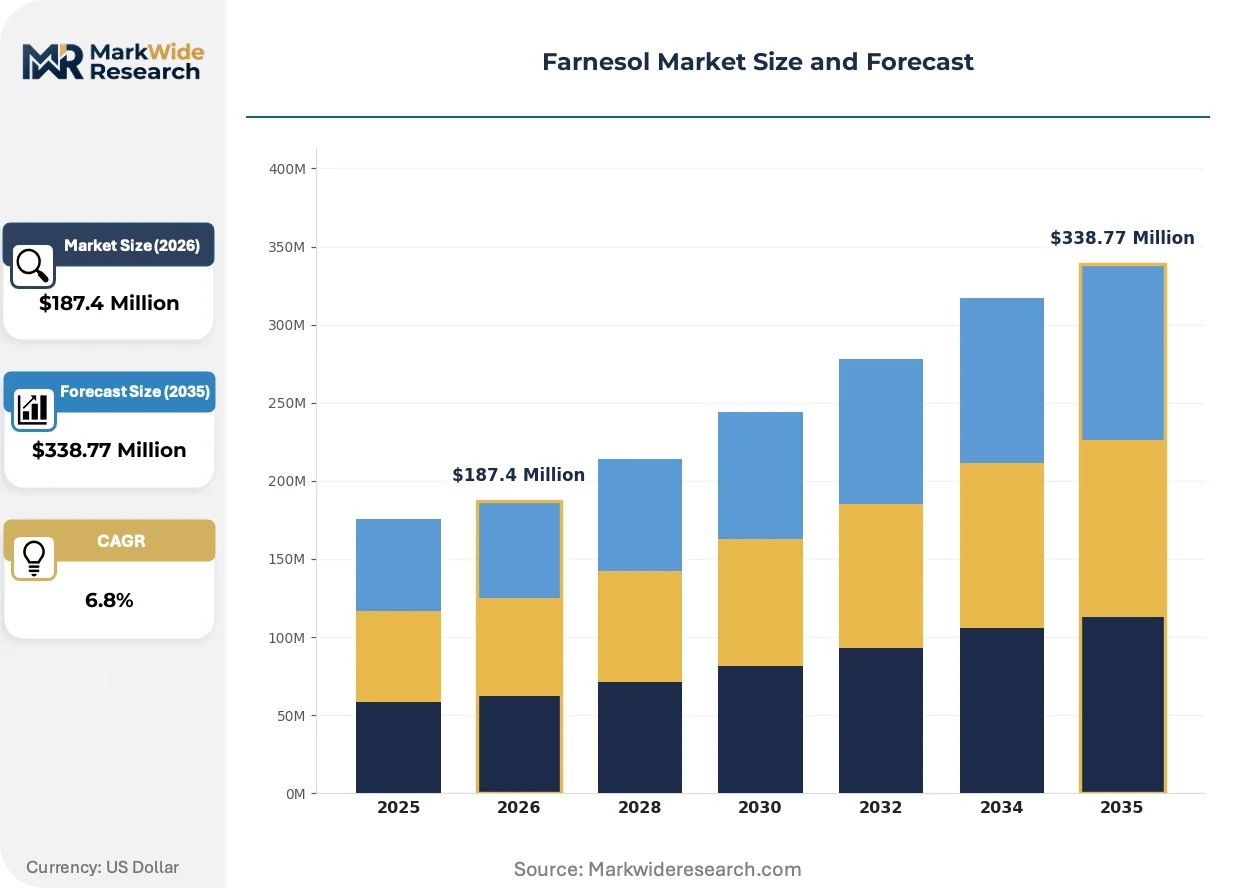
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Fragrances, Personal Care, Pharmaceuticals Application: Skincare, Haircare, Oral Care, Scented Products End User: Individuals, Manufacturers, Retailers, Distributors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Symrise AG, Vigon International, Noéma, Bontoux, Merck KGaA, BASF SE, Kraton Corporation, International Flavors & Fragrances, Carbone Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farnesol Market Emerging Trajectories
Biotechnology routes to terpene synthesis are maturing alongside tightening chemical safety frameworks, reshaping how fragrance houses qualify and procure farnesol across formulation portfolios.
Precision fermentation platforms using engineered Saccharomyces cerevisiae strains are integrating metabolic pathway optimization with real-time metabolite monitoring to deliver consistent C15 terpene alcohol titers. Specialty fragrance compounders in Switzerland and southern Germany are adopting these biotech supplies for natural-certified product lines. The technology is integrating carbon-14 isotope verification as a standard specification, compressing acceptance timelines for synthetic-extraction hybrid positioning.
EU F-Gas Regulation phase-down schedules are indirectly pressuring solvent-dependent extraction processes, accelerating interest in aqueous bioprocess alternatives for farnesol isolation. German chemical manufacturers are retrofitting existing terpene facilities to accommodate fermentation-derived feedstocks. Personal care formulators seeking supply chain resilience are diversifying qualification portfolios across both extraction and biotech origins.
Subscription-based technical service contracts are displacing transactional raw-material purchasing in European cosmetics procurement. Fragrance houses now expect integrated formulation support, stability testing, and regulatory documentation bundled with farnesol supply. This model concentrates purchasing power among integrated aroma-molecule platforms with in-house analytical capabilities, most visible in long-term agreements between French luxury skincare brands and full-service ingredient suppliers.
Farnesol Market Segmentation
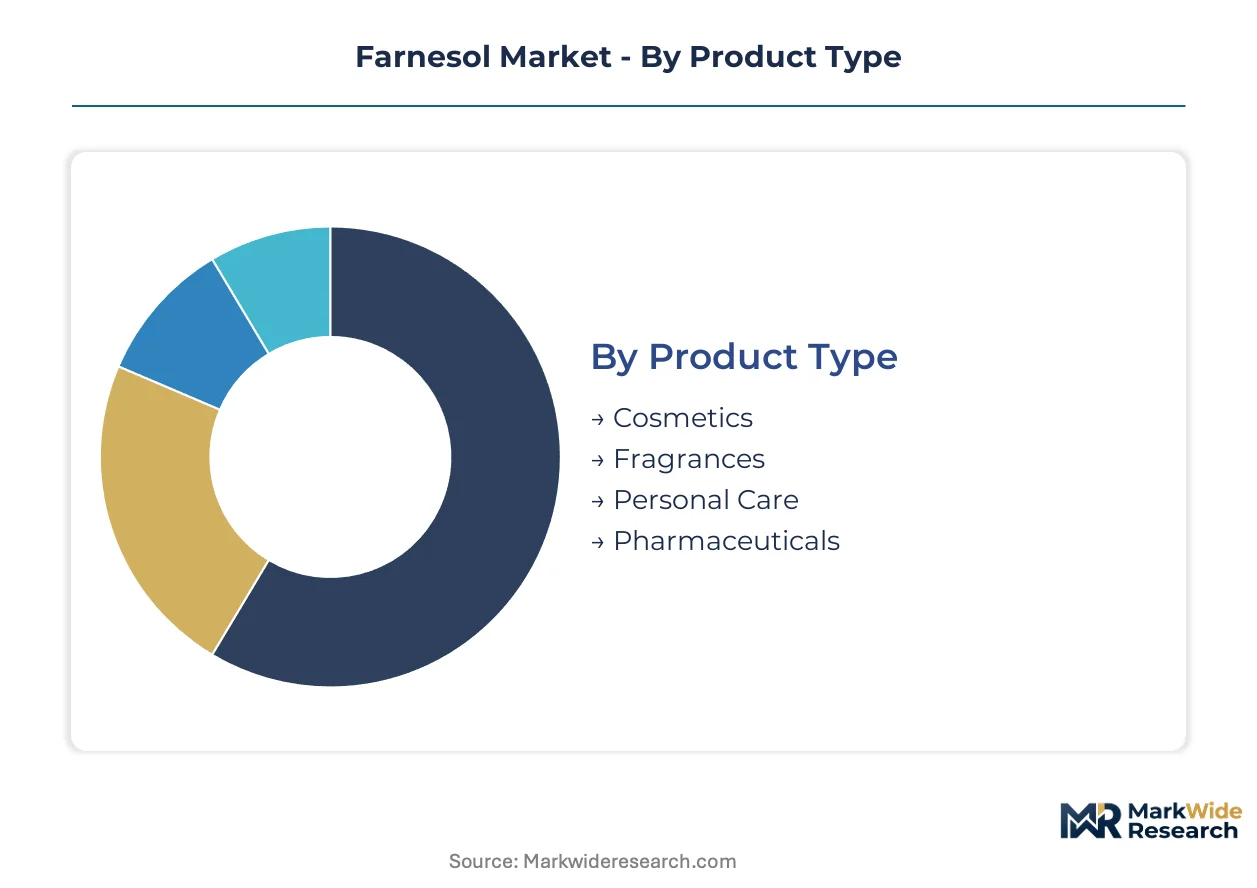
Farnesol procurement patterns diverge sharply across specification grades and customer sophistication tiers. Formulators prioritize carbon-14 verification and REACH dossier completeness when segmenting supplier qualifications.
Product Type:
Specification chemistry separates commodity-grade supplies from certified natural-identical terpene alcohols commanding formulation premiums.
- Cosmetics:High-purity farnesol serves dual roles as deodorant active and fragrance fixative in premium skincare formulations. Demand concentrates in French and German cosmetics houses reformulating around REACH-compliant antimicrobial alternatives.
- Fragrances:Natural-certified terpene alcohols integrate into luxury perfume bases requiring carbon-14 isotope verification. Swiss and southern German fragrance compounders dominate procurement for certified clean-label positioning.
- Personal Care:Mid-tier farnesol grades supply mass-market deodorant and body wash segments.
- Pharmaceuticals:GMP-compliant farnesol supports topical antimicrobial applications with documented safety profiles.
Mature deployment sits with Cosmetics. Newer deployment is concentrated in Fragrances.
Application:
Volume distribution tracks formulation complexity and regulatory exposure across rinse-off and leave-on product categories.
- Skincare:Leave-on facial serums and moisturizers absorb the largest farnesol volumes due to dual functional-scent positioning. Premium lines in France prioritize natural-identical terpene alcohols for clean-beauty retailer certification.
- Haircare:Pre-shampoo scalp treatments represent the steepest expansion trajectory as microbiome-balancing claims gain mass-market traction. German haircare brands are accelerating procurement for therapeutic positioning.
- Oral Care:Mouthwash and toothpaste formulations utilize farnesol's bacteriostatic properties for natural antimicrobial claims.
- Scented Products:Home fragrance and ambient scent applications leverage farnesol as a fixative base.
Established consumption centers on Skincare. Fastest volume gains are materializing in Haircare.
End User:
Procurement scale and technical service expectations stratify sharply across buyer sophistication tiers.
- Individuals:Direct-to-consumer farnesol purchases remain negligible due to handling restrictions and formulation expertise requirements.
- Manufacturers:Cosmetics and fragrance compounders drive volume demand with integrated technical service expectations bundled into supply contracts.
- Retailers:Clean-beauty certification programs at specialty retailers are upstreaming farnesol specification requirements to supplier qualification protocols.
- Distributors:Chemical distributors handle commodity-grade farnesol flows to mid-tier formulators lacking direct supplier relationships.
Contract concentration sits with Manufacturers. Emerging specification pressure originates from Retailers.
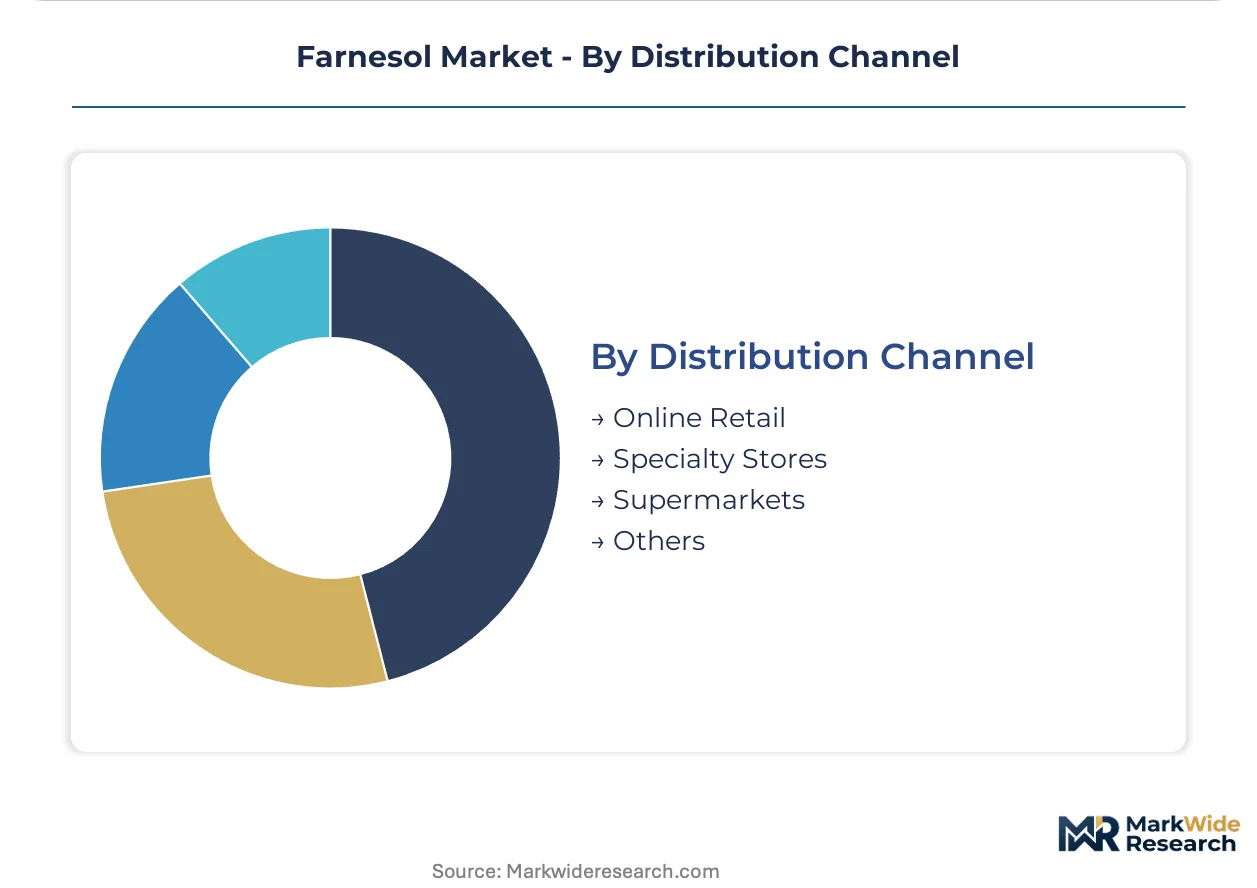
Distribution Channel:
Channel selection correlates with batch size requirements and regulatory documentation needs.
- Online Retail:E-procurement platforms serve small-batch formulators and independent cosmetics brands seeking rapid qualification.
- Specialty Stores:Dedicated ingredient distributors provide technical support and stability testing for premium fragrance houses.
- Supermarkets:Mass-market personal care manufacturers source through consolidated chemical distribution networks.
- Others:Direct manufacturer relationships dominate large-volume contracts with integrated aroma-molecule platforms.
High-touch deployment sits with Specialty Stores. Volume scaling concentrates through direct manufacturer channels classified under Others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European farnesol manufacturing through integrated chemical corridors linking the Rhine-Neckar metropolitan region to downstream fragrance compounders in Geneva and Grasse.
Germany
Baden-Württemberg's specialty chemical cluster drives farnesol demand for REACH-compliant deodorant reformulations. ECHA's Annex V preservative restrictions accelerate substitution away from synthetic antimicrobials. BASF SE's Ludwigshafen complex supplies captive terpene feedstocks to regional fragrance houses.
France
Grasse-based fragrance compounders procure natural-identical farnesol for luxury perfume certifications. ANSM cosmetic safety guidelines tighten documentation requirements for leave-on skincare. Parisian clean-beauty retailers upstream specification demands to supplier qualification protocols.
Switzerland
Geneva's specialty fragrance houses adopt carbon-14 verified farnesol for natural-certified product lines. Swissmedic oversight of cosmetic ingredient safety elevates analytical documentation standards. Basel's biochemical engineering talent pool supports precision fermentation scale-up for biotech-derived supplies.
United States
New Jersey's fragrance compounding corridor sources farnesol for deodorant applications amid FDA cosmetic modernization. The agency's expanded post-market surveillance authority favors ingredients with established safety profiles. California's clean-beauty certification programs drive premium-grade procurement from domestic distributors.
China
Shanghai's cosmetics manufacturing base imports high-purity farnesol for skincare export production. NMPA cosmetic ingredient filing requirements align formulation standards with EU benchmarks. Guangdong's personal care clusters trial fermentation-derived terpene alcohols for cost-competitive natural claims.
Farnesol Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the farnesol supply base. Integrated chemical conglomerates with captive terpene feedstock access dominate commercial-scale synthesis. Three strategic archetypes populate the competitive landscape: integrated aroma-molecule platforms, specialty fragrance distributors, and biotech-enabled fermentation specialists. Capacity expansion in precision fermentation and strategic partnerships for REACH dossier maintenance represent the dominant competitive moves reshaping supplier relationships.
Within the integrated platform tier, Symrise AG and BASF SE exemplify archetypes of full-service ingredient supply. Symrise anchors long-term technical service contracts with European cosmetics houses through its aroma-molecule integration. BASF SE occupies the scale-driven position with global terpene-derived production infrastructure. International Flavors & Fragrances sits within the biotechnology-differentiated segment, representing fermentation-route positioning for natural-certified fragrance portfolios.
| Leading Market Players |
|---|
| Symrise AG |
| Vigon International |
| Noéma |
| Bontoux |
| Merck KGaA |
| BASF SE |
| Kraton Corporation |
| International Flavors & Fragrances |
| Carbone Scientific |
| Others |
Supply Flow & Price Mechanics
Biochemical engineering talent concentration in Basel's precision fermentation cluster widens labor-cost spreads between premium biotech-derived farnesol and commodity extraction grades. REACH dossier maintenance burdens and carbon-14 verification requirements compress margins for mid-tier suppliers while rewarding integrated aroma-molecule platforms with captive analytical capabilities.
Pricing Analysis
Value-based pricing anchors on antimicrobial efficacy outcomes and fragrance fixative performance in leave-on formulations. Three-tier pricing structure across natural-certified, REACH-compliant, and commodity grades separates Swiss fragrance houses from German mass-market manufacturers from Asian export producers. Cost compression in the commodity tier intensifies because phenoxyethanol blends retain cost advantages where label claims are less stringent. Mass-market personal care manufacturers exhibit highest price sensitivity; luxury skincare houses prioritize certification completeness over unit economics.
Supply Chain Analysis
Domestic-content mandates under EU Green Deal sourcing guidelines are redirecting procurement toward fermentation-derived supplies with verifiable European production footprints. Commercial-scale synthesis concentrates in Germany, Switzerland, and France, with Ludwigshafen anchoring captive terpene feedstock integration. Essential oil extraction draws from acacia and neroli agricultural sources across Mediterranean growing regions. Single-source vulnerability sits with the three German chemical manufacturers controlling commercial bioprocess scale-up. Distribution runs through integrated technical service contracts displacing transactional raw-material purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farnesol supply remains structurally constrained by precision fermentation scale-up bottlenecks, propping pricing for verified natural-identical grades. Capacity expansion timelines and REACH registration backlogs limit near-term supply elasticity.
For Market Incumbents: Anticipate substitution pressure from engineered yeast strain developers by securing long-term offtake agreements with fragrance houses before biotech routes achieve cost parity. Defend position through backward integration into captive terpene feedstock production and in-house carbon-14 verification laboratories that compress supplier qualification timelines for clean-beauty retailers.
For New Entrants and Emerging Players: Capture white-space opportunity in scalp-health haircare applications where microbiome-balancing claims command formulation premiums with lower regulatory exposure than leave-on skincare. Target German haircare manufacturers accelerating procurement for therapeutic positioning. Enter through fermentation-derived supply with carbon-14 verification as the primary differentiation lever.
For Investors and Strategic Acquirers: Re-rating potential sits with biotech-enabled fermentation specialists given ECHA's accelerating synthetic preservative restrictions and the premium commanded by natural-certified terpene alcohols. Long-term viability favors precision fermentation platforms with demonstrated industrial bioreactor operation and established REACH dossiers. Watch for FDA cosmetic modernization implementation as the inflection signal elevating documentation requirements toward EU benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Engineered yeast strain development reduces batch-to-batch variability for fragrance compounders in Geneva and Grasse. |
| Backward Integration into Terpene Feedstock | Captive acacia and neroli sourcing insulates against Mediterranean agricultural yield fluctuations. |
| REACH Dossier Maintenance Investment | Ongoing toxicological data generation secures long-term supplier qualification for European cosmetics houses. |
| Carbon-14 Verification Capability | Analytical documentation meets Swissmedic standards and Swiss fragrance house natural-certification requirements. |
| Technical Service Contract Bundling | Integrated formulation support and stability testing concentrates purchasing power among full-service ingredient platforms. |
Methodological Framework
Independent corroboration across regulatory filings, customs trade records, and fragrance house procurement disclosures underwrites the qualitative findings. Primary interviews with biochemical engineering directors at precision fermentation facilities, procurement leads at French and German cosmetics manufacturers, REACH regulatory consultants, and specialty fragrance compounders in Switzerland combined with secondary validation from ECHA registration databases, SEC 10-K filings for listed aroma-molecule suppliers, and Swissmedic cosmetic ingredient safety guidelines. Bottom-up volume modeling and top-down value triangulation cross-checked against trade flow data.
Rate-of-change decomposition separates volume drivers from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type grade tier, application category, end-user sophistication tier, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated ECHA Annex V update timelines and FDA cosmetic modernization implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to precision fermentation scale-up success rates and divergence between EU hazard classification updates and US cosmetic safety legislation. Forecasts reflect documented assumptions around regulatory implementation schedules and bioprocess technology maturation curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
France Food Colorants Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Oil Soluble Flavors Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Savory Extract Market