
 North America Licorice Extract Market | 2026-2036
North America Licorice Extract Market Size, Share, and Industry Trends Forecast 2026-2036
North America Licorice Extract Market Analytics
Pharmaceutical applications are rebalancing toward botanical excipients and active pharmaceutical ingredients as synthetic alternatives face scrutiny. Mafco Worldwide LLC dominates conventional extract supply chains through backward integration into raw licorice root sourcing. Biomatrix International LLC differentiates via certified organic and non-GMO extraction protocols for premium nutraceutical clients. NOW Foods competes on manufacturing scale, operating cGMP-compliant facilities that supply private-label and branded channels across mass-market retail.
North America licorice extract comprises concentrated derivatives of Glycyrrhiza glabra and Glycyrrhiza uralensis roots, typically standardized to glycyrrhizin content ranging from three percent to twenty percent by weight through aqueous or ethanol extraction methods. Powder extract leads volume consumption in food and beverage manufacturing due to handling efficiency and shelf stability in seasoning blends and confectionery bases. Liquid extract captures premium positioning in pharmaceutical and cosmetics applications where solubility and rapid dispersion justify higher unit economics. Granule extract represents the fastest-growing format among nutraceutical end users seeking direct-compression tableting compatibility.
The FDA's NDI notification pathway and USP dietary supplement monographs govern botanical identity and purity standards, while Health Canada's Natural and Non-prescription Health Products Directorate imposes parallel site licensing requirements for cross-border suppliers. The EPA's pesticide residue monitoring program and state-level California Proposition 65 warning obligations add compliance layers that favor larger extractors with dedicated quality infrastructure. Stakeholders must monitor evolving monograph revisions and state-level contaminant thresholds to sustain market access across the fragmented North American regulatory landscape.
Market Dynamics
Regulatory fragmentation across the US-Canada border is fragmenting supply chain economics, as dual compliance regimes force extractors to maintain parallel quality infrastructures or surrender cross-border market access.
Growth Catalysts
- Digestive health formulations:Nutraceutical brands are expanding glycyrrhizin-standardized procurement for gut microbiome support products targeting irritable bowel syndrome applications.
- FDA NDI pathway maturation:Clarified notification requirements for botanical derivatives are reducing approval uncertainty for novel licorice-based dietary ingredients entering US commerce.
- Ethanol extraction scale-up:Midwestern processing facilities are deploying continuous-flow systems that cut solvent recovery costs while preserving flavonoid integrity for premium pharmaceutical grades.
Market Restraints
- Raw root supply concentration:Over seventy percent of conventional Glycyrrhiza glabra sourcing concentrates in Central Asian cultivation belts exposed to climate volatility and geopolitical transit friction.
- California Proposition 65 litigation exposure:Heavy metal warning obligations for botanical extracts create liability thresholds that disproportionately burden small-batch artisanal suppliers lacking in-house toxicology capabilities.
- Synthetic sweetener substitution:High-purity stevia glycosides and monk fruit extracts are capturing cost-sensitive confectionery accounts previously committed to licorice-derived flavor masking.
Strategic Opportunities
- Direct-compression nutraceuticals:Granule extract formats compatible with high-speed tableting equipment are opening white space among Canadian contract manufacturers serving aging-population supplement demand.
- Cosmeceutical melanin inhibition:Liquiritin-rich fractions are penetrating prestige skincare pipelines targeting hyperpigmentation correction in dermatologist-dispensed channels.
- USDA organic certification acceleration:Streamlined group certification protocols for medicinal herb operations are lowering entry barriers for Appalachian and Pacific Northwest growers seeking premium positioning.
Industry Challenges
- USP monograph alignment timelines:Botanical identity testing protocol revisions are forcing extractors to revalidate high-performance liquid chromatography methods against revised glycyrrhizin reference standards.
- Specialized extraction engineering talent:Scarcity of process chemists experienced in supercritical CO2 adaptation for heat-sensitive glycyrrhetinic acid derivatives is constraining capacity expansion at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Licorice Extract Market |
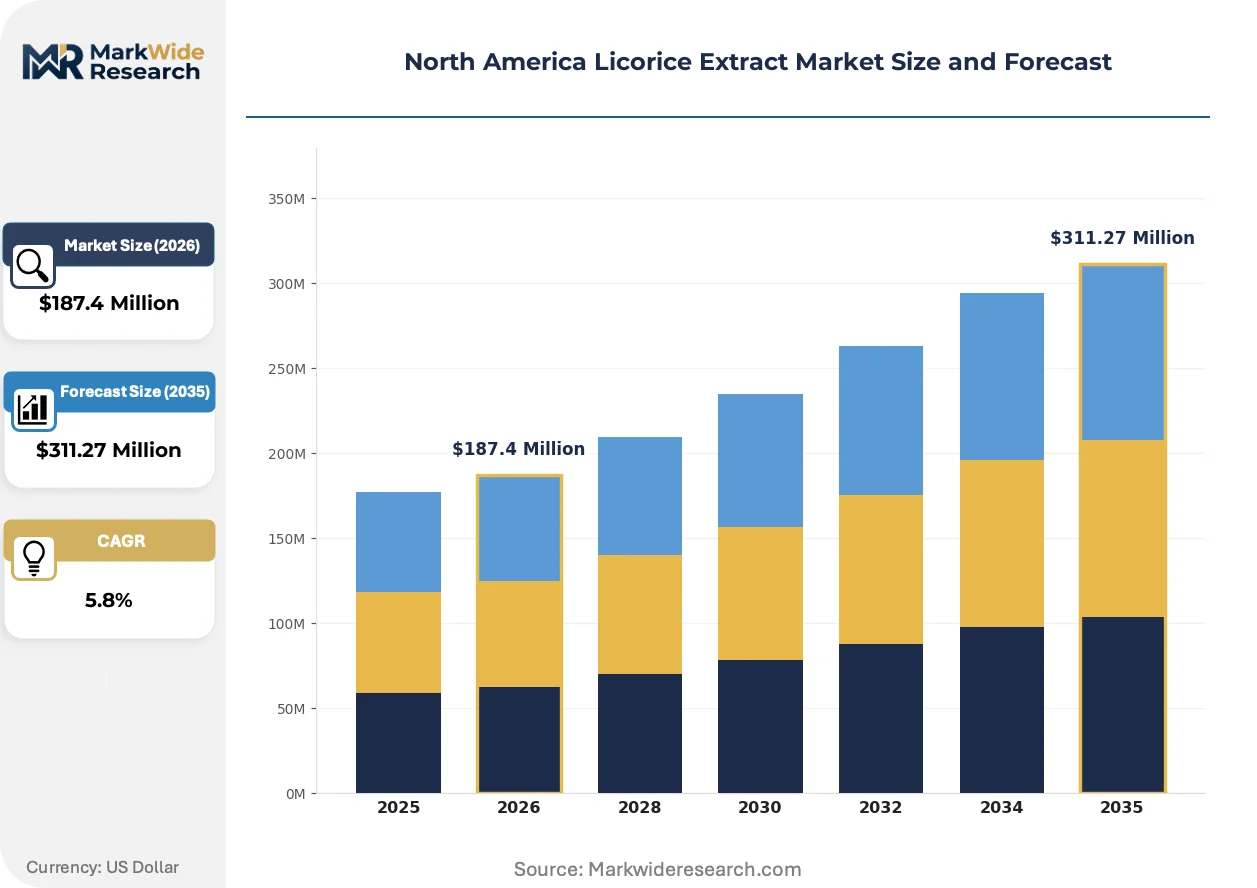
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Granule Extract, Block Extract Application: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Beverage Companies, Pharmaceutical Companies, Cosmetic Brands Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Mafco Worldwide LLC, Biomatrix International LLC, Bio-Botanica Inc., NOW Foods, Norevo GmbH, Maruzen Pharmaceuticals Co. Ltd., F&C Licorice Ltd., Swanson, Nature's Sunshine Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Licorice Extract Market Evolving Landscape
Extraction technology convergence with precision fermentation is reshaping competitive boundaries, as biosynthetic routes challenge agricultural dependency while conventional processors defend terroir-based differentiation.
Supercritical CO2 extraction systems with integrated fractionation modules are electrifying the economics of high-value glycyrrhetinic acid isolation. Pharmaceutical API manufacturers in New Jersey and Massachusetts are adopting these units to bypass ethanol-based residual solvent concerns. The technology is electrifying price compression in the twenty-percent glycyrrhizin segment while enabling premium positioning for deglycyrrhizinated fractions.
Health Canada's Natural and Non-prescription Health Products Directorate is tightening site licensing requirements for foreign suppliers, mandating on-site audits for botanical extractors seeking Canadian product licenses. The policy is diverting US-based mid-tier suppliers toward third-party contract manufacturing arrangements with domestic licensees. Nutraceutical brands with existing Health Canada approvals are consolidating supplier relationships to reduce requalification exposure.
Direct-procurement contracting between extractors and end-formulators is displacing traditional ingredient distributor intermediaries. California-based natural products manufacturers are negotiating multi-year offtake agreements with Arizona and Nevada processing facilities, securing volume commitments in exchange for transparency into cultivation batch records. The shift is most visible in respiratory health applications where traceability claims command shelf price premiums.
North America Licorice Extract Market Segmentation
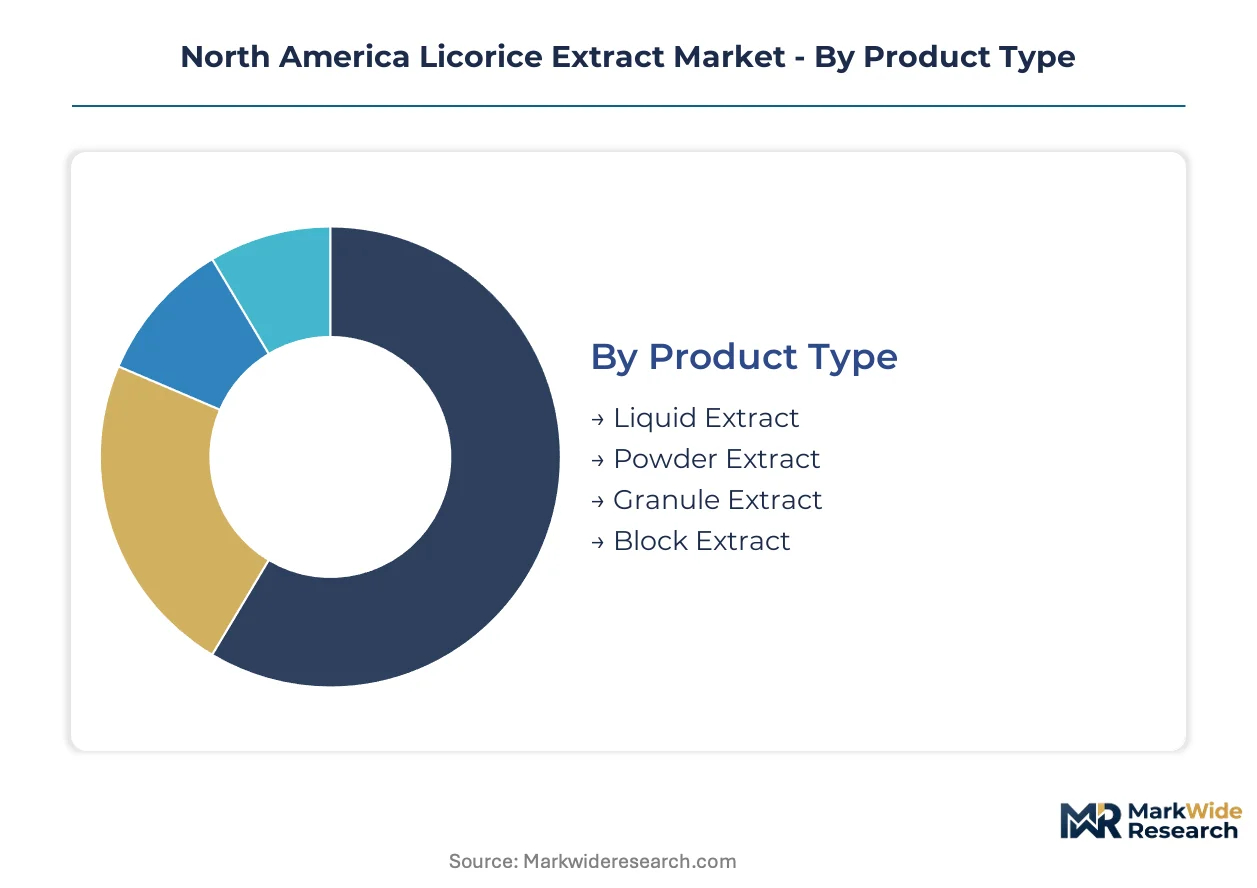
Segmentation in North America licorice extract reveals how product formats align with distinct compliance burdens and processing economics. Powder and liquid forms dominate divergent value chains, while granule formats are penetrating direct-compression nutraceutical manufacturing.
Product Type:
Integration depth varies sharply: powder and liquid extracts serve as standalone inputs requiring minimal downstream processing, while granule and block formats embed deeper into finished product manufacturing lines.
- Powder Extract:Spray-dried or vacuum-dried concentrate standardized to glycyrrhizin content, optimized for seasoning blends and confectionery bases. Midwestern flavor houses in Illinois and Ohio drive procurement for processed food clients seeking handling efficiency and extended shelf stability. FDA food additive compliance requirements favor suppliers with validated drying protocols and batch homogeneity documentation.
- Liquid Extract:Aqueous or hydroalcoholic solution retaining volatile aromatic compounds, prized in pharmaceutical and cosmetics applications where rapid dispersion matters. New Jersey and Massachusetts API manufacturers specify liquid formats to bypass residual solvent concerns in parenteral preparations. Higher unit economics reflect cold-chain logistics and custom concentration tuning.
- Granule Extract:Agglomerated particles engineered for high-speed tableting compatibility, gaining traction among Canadian contract manufacturers serving aging-population supplement demand.
- Block Extract:Solid mass concentrate requiring mechanical comminution before use, retained in artisanal confectionery and traditional apothecary channels.
Powder extract leads volumes today; granule extract is gaining share fastest.
Application:
Margin structures diverge by regulatory intensity, with pharmaceutical and nutraceutical applications commanding premium positioning against commoditized food uses.
- Food & Beverage:Flavor masking and sweetening in confectionery, chewing gum, and alcoholic beverages. California-based natural products manufacturers source deglycyrrhizinated grades for reduced-sodium product lines. Substitution pressure from high-purity stevia glycosides constrains pricing power in cost-sensitive accounts.
- Pharmaceuticals:Botanical excipients and active pharmaceutical ingredients for respiratory and gastrointestinal indications. Synthetic alternative scrutiny is rebalancing procurement toward glycyrrhetinic acid derivatives for demulcent and anti-inflammatory formulations.
- Cosmetics:Liquiritin-rich fractions targeting melanin inhibition in prestige skincare pipelines. Dermatologist-dispensed channels in Texas and Florida specify standardized extracts for hyperpigmentation correction.
- Nutraceuticals:Glycyrrhizin-standardized ingredients for digestive health and adrenal support supplements. Direct-procurement contracting is displacing traditional distributor intermediaries as brands seek cultivation batch transparency.
Food and beverage anchors volume; nutraceuticals exhibit the steepest expansion trajectory.
End User:
Customer scale determines specification complexity, with multinational pharmaceutical companies imposing stricter identity testing than regional food manufacturers.
- Food Manufacturers:Processed meat, snack, and bakery producers in the Midwest and Southeast specifying licorice extract for flavor modulation and shelf-life extension.
- Beverage Companies:Craft distillers and functional drink formulators in Colorado and Oregon sourcing for bitterness masking and botanical positioning.
- Pharmaceutical Companies:Multinational and specialty generic manufacturers requiring USP monograph compliance and validated supply chain documentation for ANDA submissions.
- Cosmetic Brands:Clean beauty and prestige skincare houses in California and New York specifying organic-certified extracts for melanin inhibition claims.
Food manufacturers generate the highest absolute demand; cosmetic brands are expanding procurement most aggressively.
Distribution Channel:
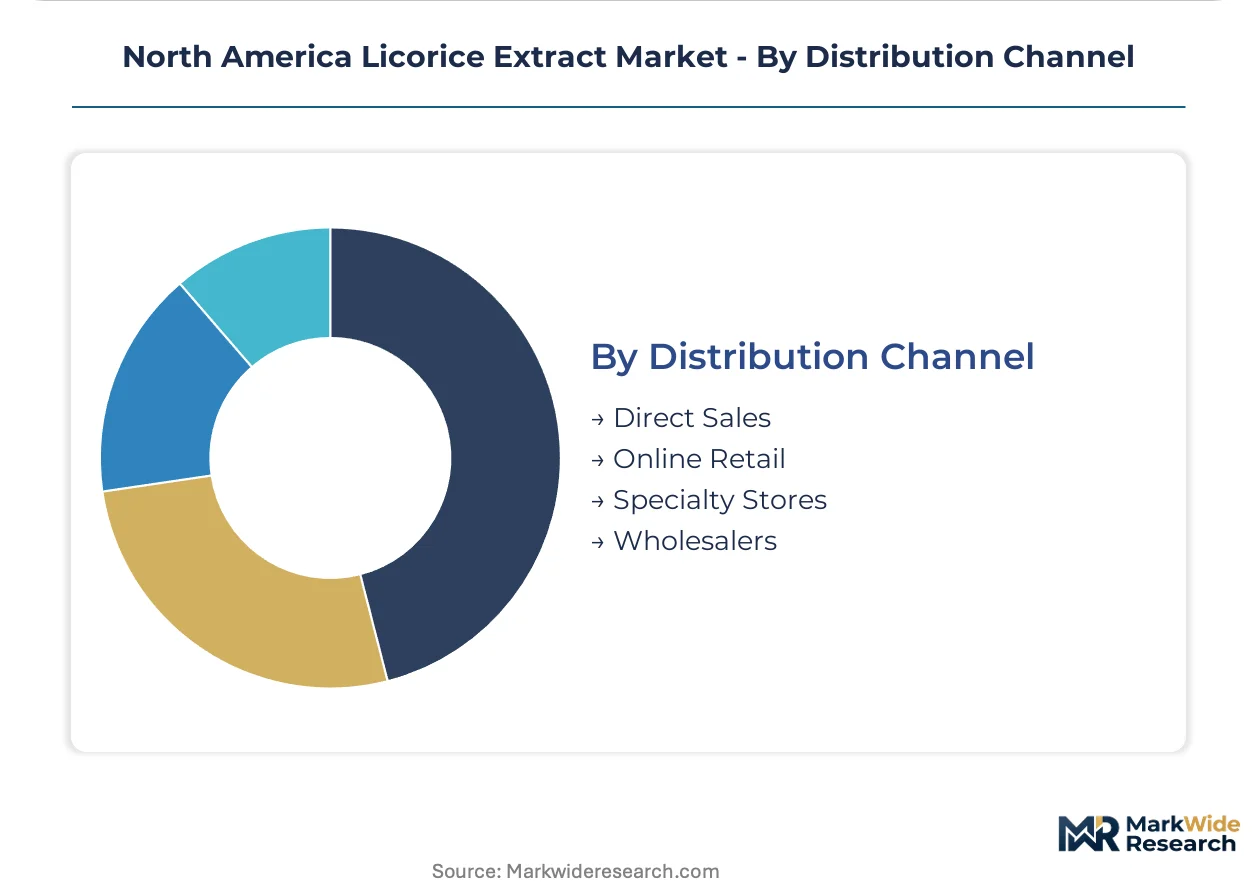
Channel selection reflects order size predictability and technical support requirements, with direct sales capturing strategic accounts and digital channels penetrating smaller formulators.
- Direct Sales:Multi-year offtake agreements between Arizona and Nevada processing facilities and California natural products manufacturers, securing volume commitments with full batch record transparency.
- Online Retail:E-commerce platforms serving small-batch artisanal producers and research institutions requiring gram-scale quantities with rapid fulfillment.
- Specialty Stores:Regional distributors catering to independent apothecaries and traditional medicine practitioners in Pacific Northwest and Appalachian markets.
- Wholesalers:Broadline ingredient distributors maintaining inventory positions for mid-tier food and beverage manufacturers with irregular procurement patterns.
Direct sales dominate value; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's natural products corridor anchors procurement intensity for premium botanical extracts. The FDA's NDI notification pathway and Health Canada's site licensing regime are reshaping cross-border supplier economics.
United States
California-based natural products manufacturers and Midwestern flavor houses in Illinois and Ohio drive differentiated demand streams. The FDA's evolving USP monograph standards for botanical extracts are elevating compliance costs for suppliers seeking ANDA submission readiness. New Jersey and Massachusetts pharmaceutical API clusters are adopting supercritical CO2 extraction systems to bypass residual solvent concerns in parenteral preparations.
Canada
Contract manufacturers serving aging-population supplement demand are expanding granule extract procurement for direct-compression tableting compatibility. Health Canada's Natural and Non-prescription Health Products Directorate mandates on-site audits for foreign suppliers seeking Canadian product licenses. Ontario-based nutraceutical brands with existing Health Canada approvals are consolidating supplier relationships to reduce requalification exposure.
Mexico
Cross-border processing facilities in northern states are positioning as toll manufacturers for US brands seeking tariff-advantaged production. The country's national pharmaceutical regulator maintains parallel import licensing requirements for botanical derivatives entering formal distribution channels. Baja California and Chihuahua extraction operations are scaling aqueous processing capacity to serve cost-sensitive confectionery accounts.
North America Licorice Extract Market Competitive Landscape
Backward integration into raw licorice root sourcing dominates the current landscape among conventional extract suppliers. The vendor base concentrates around three operational archetypes: vertically integrated root-to-extract operators, certified organic specialists, and mass-market cGMP manufacturers. Tiered competitive positioning separates premium nutraceutical-grade suppliers from commodity flavor houses. M&A activity and direct-procurement contracting are the primary vectors for market share capture.
Within the vertically integrated tier, Mafco Worldwide LLC anchors conventional supply chain control through captive sourcing infrastructure. Biomatrix International LLC and NOW Foods occupy distinct positioning vectors—Biomatrix exemplifies certified organic and non-GMO protocol specialization for premium nutraceutical clients, while NOW Foods represents manufacturing scale through cGMP-compliant facilities serving private-label and branded mass-market channels. These three entities collectively illustrate the segmentation between upstream control, certification-driven differentiation, and operational scale.
| Leading Market Players |
|---|
| Mafco Worldwide LLC |
| Biomatrix International LLC |
| Bio-Botanica Inc. |
| NOW Foods |
| Norevo GmbH |
| Maruzen Pharmaceuticals Co. Ltd. |
| F&C Licorice Ltd. |
| Swanson |
| Nature's Sunshine Products |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements from California natural products manufacturers are forcing Arizona and Nevada processing facilities to absorb cultivation batch transparency costs, compressing margins on conventional glycyrrhizin-standardized grades while amplifying premiums for certified organic supply.
Pricing Analysis
Input-cost pass-through from Central Asian licorice root sourcing dominates pricing dynamics. Three-tier pricing structure across premium organic, standard conventional, and economy solvent-extracted levels separates Biomatrix International LLC's certified protocols from Mafco Worldwide LLC's integrated conventional supply and toll-processed commodity grades. Cost compression in the economy tier is intensifying because high-purity stevia glycosides capture confectionery substitution. Food manufacturers exhibit highest price sensitivity; pharmaceutical API buyers accept premiums for USP monograph compliance and residual solvent documentation.
Supply Chain Analysis
Single-source vulnerability sits with Central Asian cultivation belts supplying over seventy percent of conventional Glycyrrhiza glabra root. Arizona, Nevada, and California processing facilities draw from this upstream concentration, with secondary sourcing from Appalachian and Pacific Northwest domestic growers for organic-certified segments. Tariff exposure on cross-border Mexican toll manufacturing creates structural risk for US brands seeking cost-advantaged production. Distribution runs through direct-procurement contracting displacing traditional ingredient distributors, with Arizona and Nevada facilities serving California manufacturers via transparent batch record protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America licorice extract market functions as a regulatory compounder, with Health Canada's tightening site licensing requirements for foreign suppliers accelerating consolidation among cross-border capable processors.
For Market Incumbents: To counter synthetic sweetener substitution in cost-sensitive confectionery accounts, Mafco Worldwide LLC and NOW Foods should deepen backward integration into captive root sourcing infrastructure while accelerating USDA organic certification coverage across Pacific Northwest grower networks. Certification investment represents the critical defensive lever against premium-tier erosion. For New Entrants and Emerging Players: Capture white space in Canadian contract manufacturing for aging-population supplement demand by engineering granule extract formats compatible with high-speed direct-compression tableting equipment. The most penetrable segment sits with Ontario-based nutraceutical brands consolidating supplier relationships to reduce Health Canada requalification exposure. A go-to-market angle emphasizing batch record transparency and on-site audit readiness differentiates against mid-tier US suppliers diverting toward third-party arrangements. For Investors and Strategic Acquirers: Asymmetric upside sits with certified organic specialists possessing Health Canada site licenses and supercritical CO2 extraction capacity. Long-term viability hinges on regulatory moat sustainability across the 5-10 year FDA NDI pathway maturation window. The signal to watch is USP monograph revision timing forcing HPLC method revalidation costs that disproportionately burden artisanal suppliers lacking dedicated quality infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Root Sourcing | Mafco Worldwide LLC's captive Central Asian cultivation infrastructure secures supply continuity against climate volatility. |
| USDA Organic Certification Acceleration | Streamlined group protocols lower entry barriers for Appalachian growers seeking premium nutraceutical positioning. |
| Supercritical CO2 Extraction Scale-Up | New Jersey and Massachusetts API manufacturers bypass residual solvent concerns in parenteral preparations. |
| Health Canada Site Licensing Compliance | On-site audit mandates divert US mid-tier suppliers toward third-party contract manufacturing arrangements. |
| Direct-Procurement Contracting Expansion | California manufacturers negotiate multi-year offtake agreements securing volume with full batch record transparency. |
Research Methodology
Multiple input streams — primary interviews with extraction facility plant managers, nutraceutical procurement leads, and regulatory affairs directors at FDA-registered botanical suppliers; secondary validation through USP monograph documentation, Health Canada site licensing records, and EPA pesticide residue monitoring data; and customs trade flows for licorice root imports — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across product format segmentation by powder, liquid, granule, and block extract types, application segmentation spanning food and beverage, pharmaceutical, cosmetics, and nutraceutical end uses, and geographic clustering by US state-level regulatory exposure and Canadian provincial manufacturing concentration informed the analytical framework over the projection horizon. CAGRs were derived from elasticity modeling against glycyrrhizin-standardized ingredient demand curves and supercritical CO2 extraction capacity expansion timelines.
Climate volatility in Central Asian cultivation belts, Health Canada site licensing policy revisions, and USP monograph alignment timelines for botanical identity testing protocols are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Food Grade Menthol Crystal Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
Natural Berry Flavor Market
Flavorings and Food Additives
Farnesol Market
Flavorings and Food Additives
Mandarin Oil Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
Quillaia Extracts Market