
 Asia-Pacific Grape Seed Extract Market | 2026-2036
Asia-Pacific Grape Seed Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Grape Seed Extract Market Outlook
Supercritical CO₂ extraction is reconfiguring how grape seed extract achieves standardized proanthocyanidin content without solvent residues. Hunan NutraMax Inc. leverages this technology to supply pharmaceutical-grade material to Japanese nutraceutical buyers. BENEPURE Corporation anchors its position through backward integration into raw grape seed sourcing across Central China. Alpspure Lifesciences Private Limited differentiates via kosher and halal certifications that unlock Middle East re-export channels from India.
Grape seed extract is a polyphenolic concentrate derived from Vitis vinifera seeds, typically standardized to 95% oligomeric proanthocyanidins and manufactured through aqueous ethanol or supercritical fluid extraction for antioxidant, anti-inflammatory, and collagen-stabilizing applications. Powder formulations dominate bulk ingredient trade due to stability in ambient storage and compatibility with encapsulation lines, while liquid extracts gain traction in functional beverage premixes where rapid dispersion matters. The nutraceutical end-user channel leads volume offtake as Japanese and South Korean brands reformulate joint-health and cardiovascular portfolios around polyphenol complexes.
China's SAMR and NMPA enforce health food blue-hat registration requirements that filter out substandard extract suppliers, while Japan's Ministry of Health, Labour and Welfare sets purity benchmarks for food-with-health-claims labeling. India's FSSAI recently tightened contaminant limits for imported botanical extracts, redirecting some procurement toward domestic GMP-certified facilities. Stakeholders must monitor how Australia's TGA evolves complementary medicine listing rules, as this shapes export eligibility for Australian brands sourcing Asian extract.
Market Dynamics
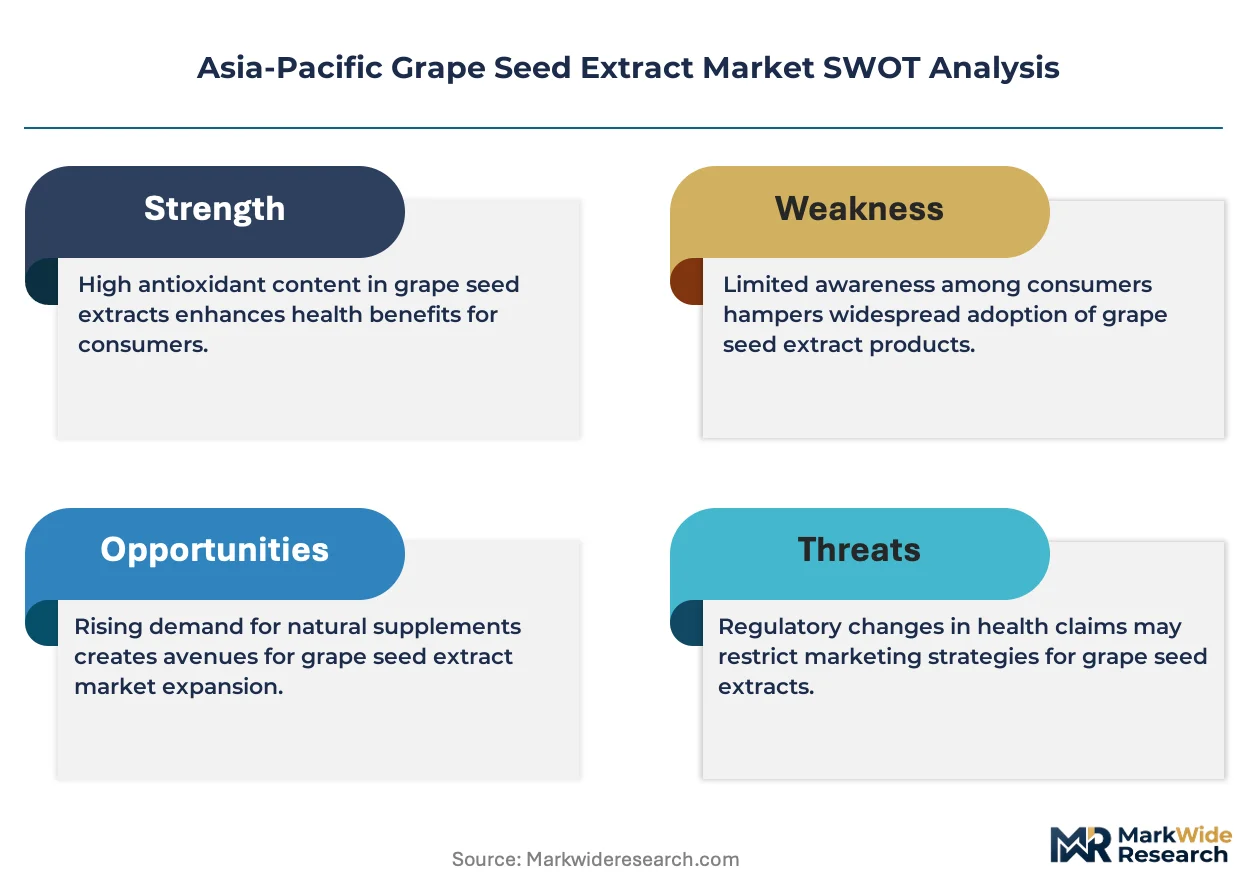
Supercritical CO₂ extraction technology is compressing solvent-based production margins while China's NMPA blue-hat registration requirements filter supplier bases. Japanese nutraceutical brands now demand pharmaceutical-grade proanthocyanidin standardization, forcing extraction facilities to upgrade certification tiers or exit premium supply tiers entirely.
Growth Catalysts
- NMPA Registration Streamlining:China's SAMR reduced health food approval timelines, accelerating ingredient access for domestic antioxidant formulators.
- Joint-Health Portfolio Reformulation:South Korean nutraceutical brands are rebuilding cardiovascular and collagen-support lines around polyphenol complexes.
- Coastal Extraction Clustering:Shandong and Zhejiang provinces concentrate domestic capacity near export corridors, shortening lead times to Japanese buyers.
Market Restraints
- Raw Seed Supply Volatility:Wine industry grape crush volumes fluctuate seasonally, constraining seed feedstock availability for extraction facilities.
- Import Contaminant Limits:India's FSSAI tightened botanical extract purity thresholds, redirecting procurement toward domestic GMP-certified plants.
- Ethanol Solvent Residue Constraints:Aqueous ethanol extraction faces displacement pressure as buyers specify residue-free supercritical CO₂ grades.
Strategic Opportunities
- Southeast Asia Penetration:Vietnam and Thailand functional beverage markets remain underdeveloped for grape seed polyphenol premixes.
- Kosher-Halal Certification Arbitrage:Indian extractors with dual certifications capture Middle East re-export demand that Chinese suppliers cannot serve.
- Backward Integration:Captive control over raw grape seed sourcing across Central China secures feedstock priority during crush season.
Industry Challenges
- Supercritical Equipment Capex Burden:Pharmaceutical-grade CO₂ extraction systems require substantial capital deployment, squeezing mid-scale processors.
- Blue-Hat Compliance Timelines:China's health food registration dossier preparation extends 18-24 months, freezing product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Grape Seed Extract Market |
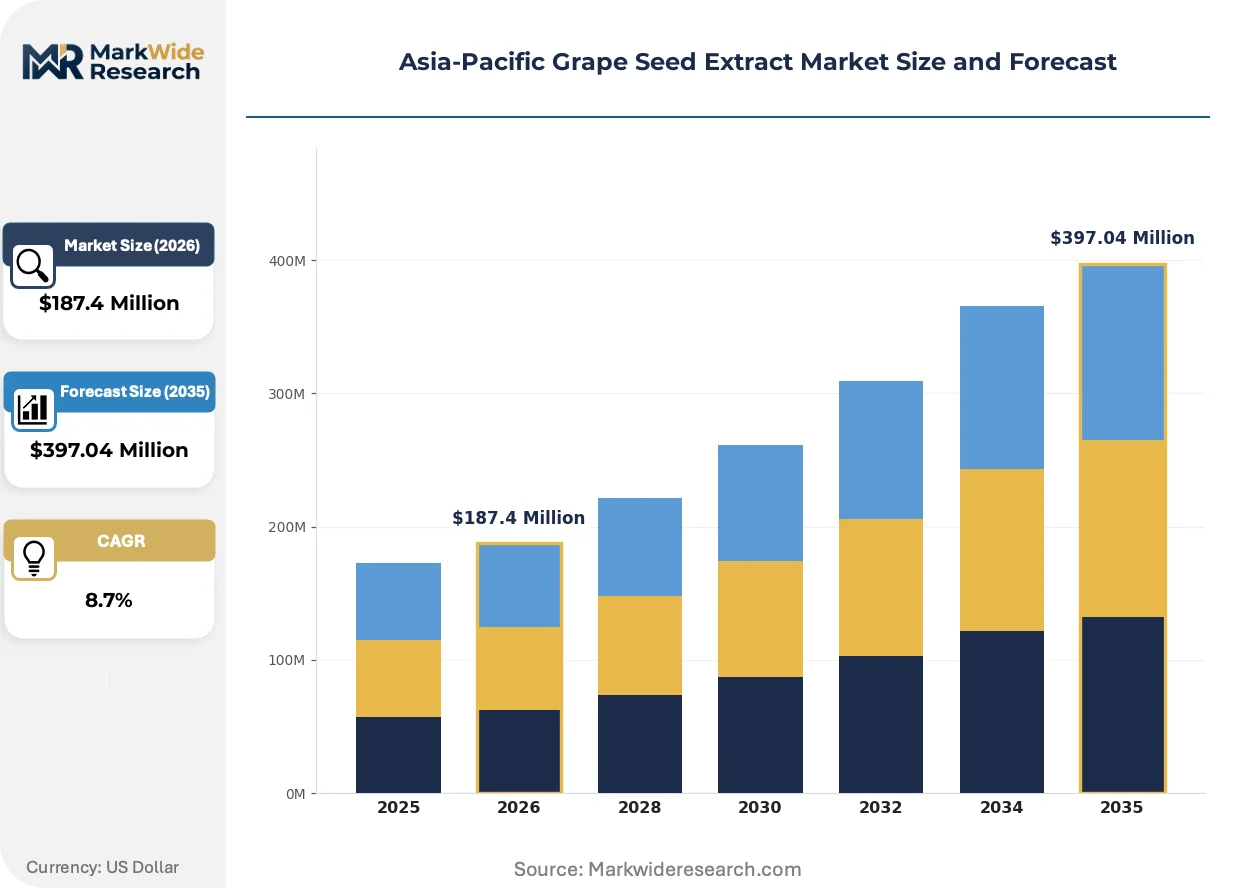
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Food & Beverages Application: Oral Supplements, Anti-Aging, Antioxidants, Functional Foods Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | Botanic Innovations LLC, BENEPURE Corporation, Naturex, Bhooratna Agri Processors, Alpspure Lifesciences Private Limited, Nexira, Hunan NutraMax Inc., Shijiazhuang Jianhe Biotech Co., Ltd., Polyphenolics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Grape Seed Extract Market Strategic Shifts
Extraction technology and regulatory labeling frameworks are compressing legacy supplier positions while buyer procurement criteria harden around certification tiers. Three developments are restructuring competitive access.
Supercritical CO₂ extraction is virtualizing solvent-based production economics. This technology achieves 95% oligomeric proanthocyanidin standardization without ethanol residue. Japanese pharmaceutical and nutraceutical buyers now specify CO₂ grades exclusively, marginalizing aqueous ethanol facilities. The shift is virtualizing mid-tier extraction capacity across Shandong processing zones.
Japan's Ministry of Health, Labour and Welfare tightened food-with-health-claims purity benchmarks. This regulatory compression forces extractors to upgrade analytical testing protocols and batch documentation. South Korean MFDS-aligned brands are mirroring these standards, creating a harmonized premium tier that locks out uncertified Chinese suppliers.
Buyer specification sheets now weight kosher-halal certification equivalence alongside proanthocyanidin content. Middle East distribution channels reject ethanol-extracted material regardless of purity metrics. Indian Alpspure and comparable certified facilities are capturing re-export flows that previously routed through Chinese coastal ports, rotating procurement gravity toward certified supply nodes.
Asia-Pacific Grape Seed Extract Market Segmentation
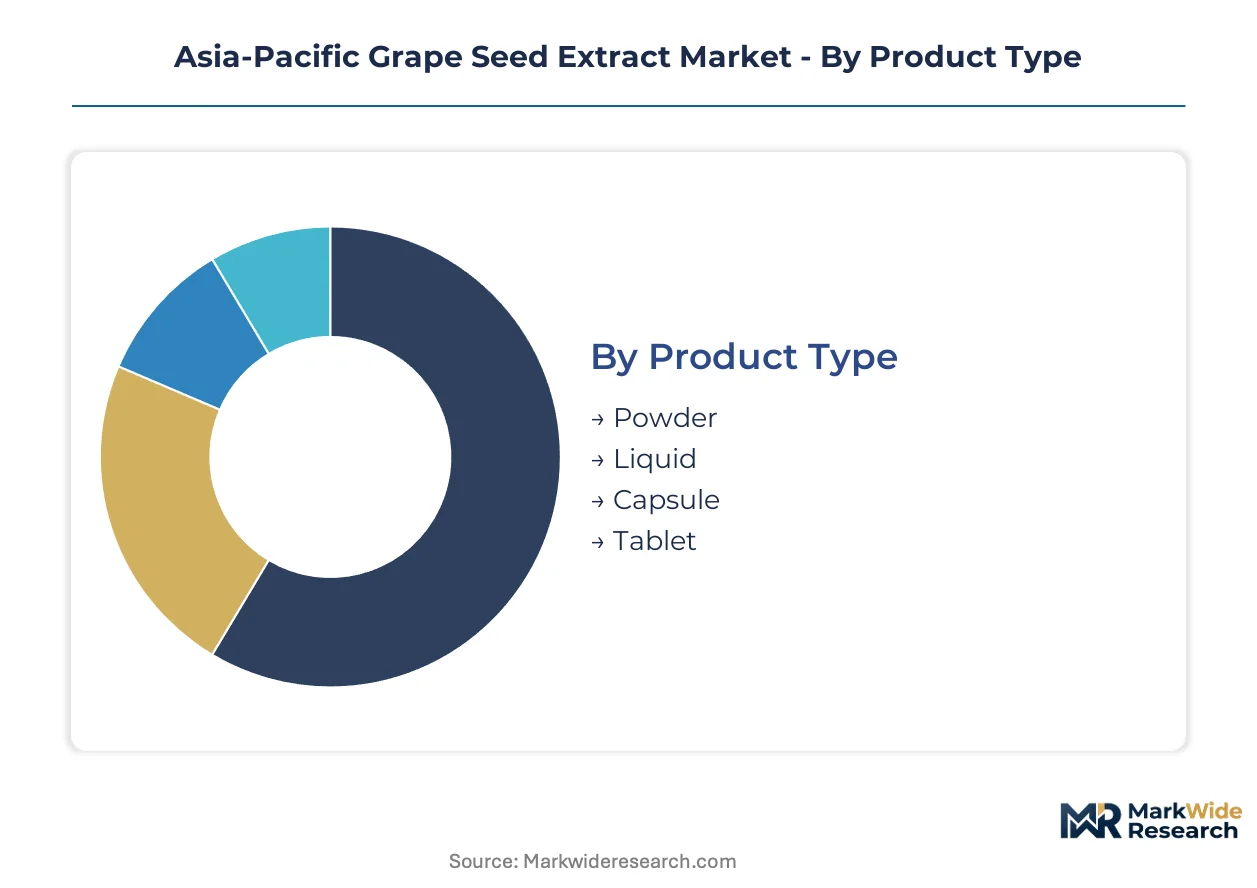
Segmentation in the Asia-Pacific Grape Seed Extract Market reveals how extraction technology and regulatory certification tiers split procurement flows across Japanese pharmaceutical buyers, South Korean nutraceutical brands, and Chinese domestic formulators. Each dimension—product format, end-use channel, application focus, and distribution pathway—carries distinct margin structures and compliance burdens that reshape supplier competitive positioning.
Product Type:
Powder formulations anchor bulk ingredient procurement from Shandong extraction clusters, while liquid grades serve functional beverage premix lines demanding rapid dispersion.
- Powder:Standardized to 95% oligomeric proanthocyanidins through supercritical CO₂ or aqueous ethanol extraction. Ambient stability and encapsulation compatibility drive volume concentration in Japanese nutraceutical capsule manufacturing and Chinese domestic supplement lines.
- Liquid:Rapid-dispersion extracts formulated for functional beverage premixes. South Korean collagen-support drink brands and Thailand functional beverage startups are expanding procurement of liquid grades for ready-to-drink antioxidant formulations.
- Capsule:Pre-formulated dosage units bypassing secondary encapsulation steps. Demand concentrates among Australian TGA-listed complementary medicine brands seeking streamlined manufacturing.
- Tablet:Compressed delivery formats with binders for extended-release profiles. Indian FSSAI-registered domestic brands favor tablet formats for cardiovascular health positioning in pharmacy channels.
Established volume favors Powder; emerging adoption favors Liquid.
End User:
Margin concentration tracks regulatory certification intensity, with pharmaceutical-grade proanthocyanidin standardization commanding premium pricing over food-grade material.
- Pharmaceuticals:PMDA-registered and MFDS-aligned manufacturers demand batch-level purity documentation and residual solvent testing. Japanese buyers specify CO₂-extracted material exclusively, marginalizing ethanol-based suppliers from premium procurement tiers.
- Nutraceuticals:South Korean brands reformulate joint-health and cardiovascular portfolios around polyphenol complexes. China's NMPA blue-hat registration requirements filter supplier bases to GMP-certified extraction facilities.
- Cosmetics:Topical antioxidant and collagen-stabilizing applications in anti-aging serums. Australian and Japanese dermocosmetic brands drive specification tightening around heavy metal limits.
- Food & Beverages:Functional food fortification with polyphenol premixes. Vietnam and Thailand beverage markets remain underdeveloped penetration targets for grape seed polyphenol integration.
Certification intensity peaks in Pharmaceuticals; volume expansion runs fastest in Nutraceuticals.
Application:
Application segmentation maps directly to health claim authorization pathways, with oral supplements dominating where NMPA and MFDS registration infrastructure exists.
- Oral Supplements:Capsule and tablet delivery systems for daily antioxidant intake. Chinese domestic brands leverage streamlined SAMR registration timelines to accelerate product launches in Shandong and Zhejiang distribution corridors.
- Anti-Aging:Collagen stabilization and skin elasticity support claims. South Korean beauty-from-within positioning and Japanese food-with-health-claims labeling drive specification convergence around low-molecular-weight proanthocyanidin fractions.
- Antioxidants:Cardiovascular and cellular protection positioning. Australian TGA complementary medicine listings require evidence-backed dosing claims that favor standardized extract procurement.
- Functional Foods:Beverage, dairy, and bakery fortification. India's FSSAI tightened contaminant limits redirect procurement toward domestic GMP-certified facilities for food-grade material.
Regulatory infrastructure concentrates Oral Supplements; functional claim expansion favors Anti-Aging.
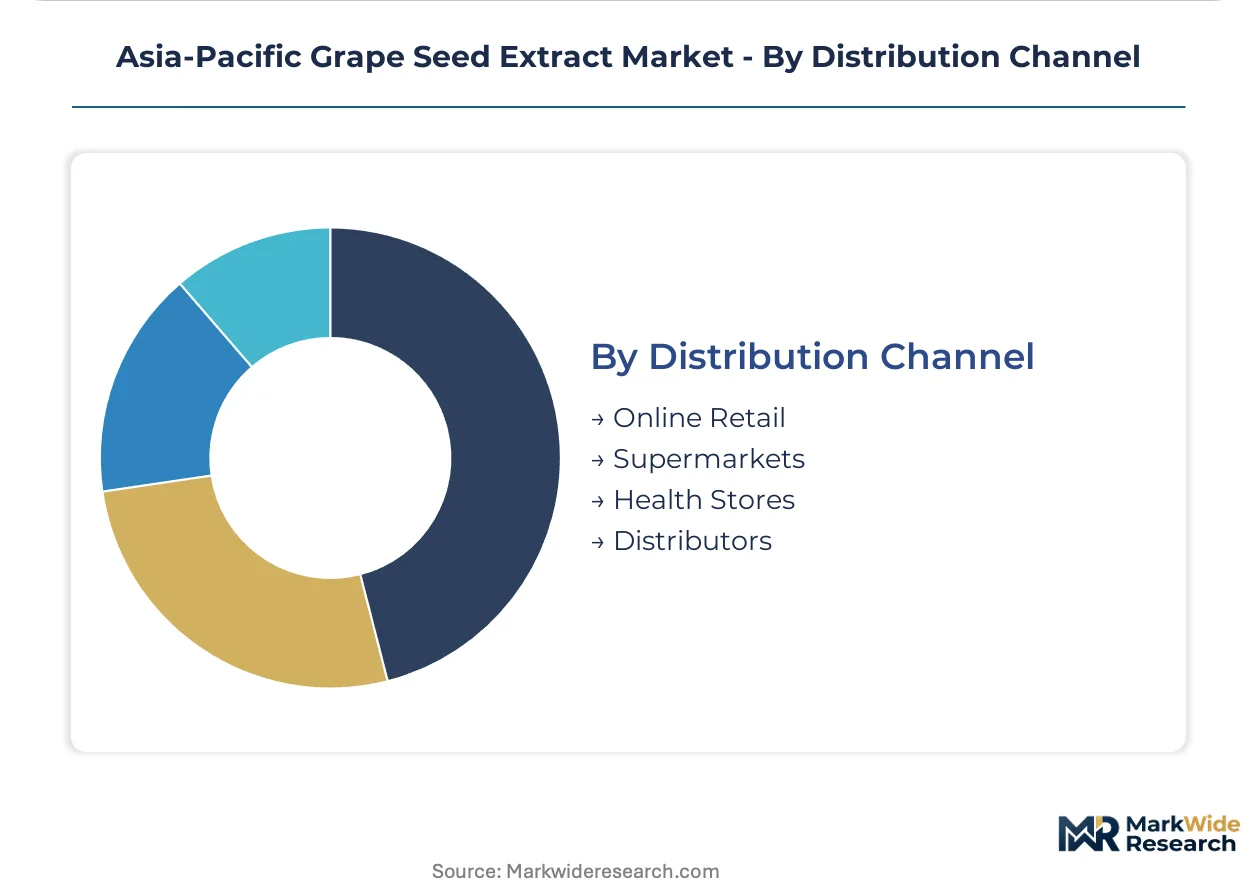
Distribution Channel:
Channel segmentation reflects buyer procurement scale and certification verification requirements, with direct distributor relationships dominating pharmaceutical-grade volume.
- Online Retail:Direct-to-consumer supplement sales bypassing pharmacy markup. Australian and Japanese e-commerce platforms enable niche brand entry with lower certification barriers than brick-and-mortar channels.
- Supermarkets:Mass-market functional food and beverage placement. Thailand and Vietnam modern trade expansion creates shelf-space competition for polyphenol-fortified products.
- Health Stores:Specialty retailer channels with trained staff consultation. South Korean and Japanese pharmacy-adjacent health food shops emphasize food-with-health-claims verification.
- Distributors:Bulk ingredient procurement by contract manufacturers and brand owners. Shandong and Zhejiang extraction facilities ship containerized powder through coastal export corridors to Japanese distributor warehouses.
Scale concentration sits with Distributors; channel diversification favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese nutraceutical brands and South Korean beauty-from-within formulators drive premium-tier procurement, while Chinese domestic brands exploit streamlined registration timelines to accelerate product launches. Coastal extraction clusters in Shandong and Zhejiang provinces anchor supply-side capacity, shortening lead times to regional buyers.
China
Domestic antioxidant formulators in Shandong and Zhejiang provinces are expanding procurement of supercritical CO₂-extracted material for NMPA blue-hat registered products. SAMR streamlined health food approval timelines, compressing ingredient access cycles from 24 months toward 18 months. Shandong's coastal extraction facilities cluster near Qingdao export corridors, containerizing pharmaceutical-grade powder for Japanese distributor warehouses.
Japan
PMDA-registered manufacturers and food-with-health-claims brands specify residue-free extraction grades exclusively, marginalizing ethanol-based suppliers. The Ministry of Health, Labour and Welfare tightened purity benchmarks for proanthocyanidin standardization, forcing batch-level documentation upgrades. Kanto region nutraceutical capsule manufacturers concentrate demand for 95% oligomeric proanthocyanidin grades, importing through Yokohama port channels.
South Korea
MFDS-aligned nutraceutical brands are reformulating joint-health and cardiovascular portfolios around polyphenol complexes, driving specification convergence with Japanese standards. Seoul Capital Area contract manufacturers demand pharmaceutical-grade certification tiers that filter uncertified Chinese suppliers. Busan-Ulsan corridor distributors handle containerized powder imports from Shandong facilities, with Gwangju-Honam region beverage startups testing liquid extract premixes.
India
FSSAI tightened contaminant limits for imported botanical extracts, redirecting procurement toward domestic GMP-certified facilities in Maharashtra and Gujarat. Alpspure Lifesciences and comparable certified extractors capture Middle East re-export demand through kosher-halal certification arbitrage. Mumbai and Ahmedabad processing zones concentrate food-grade material production for pharmacy channel tablet formulations.
Australia
TGA-listed complementary medicine brands drive evidence-backed dosing claims that favor standardized extract procurement from certified Asian suppliers. Sydney and Melbourne-based contract manufacturers specify heavy metal testing protocols that exceed baseline import requirements. Victorian distributor networks channel bulk powder into pharmacy-adjacent health food retail, with online retail platforms enabling niche brand entry at lower certification barriers.
Asia-Pacific Grape Seed Extract Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where certification intensity separates premium procurement tiers from commodity bulk trade. Supercritical CO₂ extraction capability and dual kosher-halal certification function as threshold qualifications for Japanese pharmaceutical and Middle East re-export channels. Three archetypes dominate: vertically integrated seed-to-extract operators, technology-specialized supercritical processors, and certification-focused re-export facilitators. Dominant competitive moves include backward integration into raw grape seed sourcing and geographic expansion into underpenetrated Southeast Asian beverage markets.
Within the technology-specialized tier, Hunan NutraMax Inc. exemplifies supercritical CO₂ extraction positioning for pharmaceutical-grade supply to Japanese buyers. BENEPURE Corporation anchors the vertically integrated archetype through upstream control over raw grape seed procurement across Central China. Alpspure Lifesciences Private Limited occupies the certification-arbitrage position, leveraging dual kosher-halal credentials to capture Middle East re-export flows that ethanol-extracted Chinese material cannot serve. These three entities represent distinct competitive vectors—technical capability, supply chain control, and regulatory access—that structure procurement gravity across the region.
| Leading Market Players |
|---|
| Botanic Innovations LLC |
| BENEPURE Corporation |
| Naturex |
| Bhooratna Agri Processors |
| Alpspure Lifesciences Private Limited |
| Nexira |
| Hunan NutraMax Inc. |
| Shijiazhuang Jianhe Biotech Co., Ltd. |
| Polyphenolics |
| Others |
Value Chain & Pricing Dynamics
Shandong and Zhejiang extraction clusters anchor upstream supply for Japanese pharmaceutical buyers, concentrating margin capture in CO₂-certified grades while ethanol-based processors face price compression. Coastal clustering near Qingdao and Ningbo export corridors shortens lead times but locks in logistics-cost sensitivity for inland feedstock sourcing.
Pricing Analysis
Cost-plus contracts with grape crush volume indexation dominate raw material procurement, passing wine industry seasonality through to extract pricing. Pharmaceutical-grade CO₂-extracted material commands premium-mid-economy pricing differentiation against food-grade ethanol extracts, with certification tier and proanthocyanidin standardization as primary price drivers. Pricing pressure stems from supercritical equipment capex burdens squeezing mid-scale processors. Chinese domestic formulators show highest price sensitivity; Japanese PMDA-registered manufacturers exhibit lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Raw grape seed feedstock draws from wine production clusters across China, India, and Australia, with crush volume seasonality constraining year-round extraction capacity utilization. Supercritical CO₂ systems, pharmaceutical-grade testing protocols, and kosher-halal certification infrastructure represent critical component dependencies. Single-source vulnerability runs through Shandong's coastal processing concentration, where typhoon-disrupted port operations can freeze containerized exports to Japanese distributors. Distribution runs through distributor warehouses in Yokohama, Busan, and Mumbai, with direct manufacturer relationships dominating pharmaceutical-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of supercritical CO₂ extraction capability combined with dual kosher-halal certification infrastructure defines competitive access in this market. Pharmaceutical-grade standardization expertise and NMPA blue-hat registration navigation represent the critical asset gaps separating premium-tier suppliers from commodity processors.
For Market Incumbents: Build certification moats through simultaneous NMPA, MFDS, and TGA registration holdings to lock out uncertified competitors. Secure backward integration into Central China grape seed sourcing to guarantee crush-season feedstock priority. Defend against supercritical technology displacement by upgrading aqueous ethanol facilities or exiting premium tiers entirely. Channel control through exclusive distributor relationships in Yokohama and Busan reinforces pricing power. For New Entrants and Emerging Players: Vietnam and Thailand functional beverage markets offer the most penetrable white-space for liquid extract premixes, with minimal incumbent certification saturation. Target South Korean collagen-support drink startups seeking rapid-dispersion grades for ready-to-drink formulations. Leverage India's FSSAI-compliant GMP facilities as a regulatory-compliant entry point for food-grade material. Partner with established extractors for toll manufacturing rather than greenfield capex deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Chinese extraction facilities holding coastal real estate but lacking supercritical upgrade capital. Five-to-ten-year viability hinges on technology transition completion and certification tier migration. Acquisition targets should display captive raw seed sourcing or established pharmaceutical-grade customer relationships. Watch NMPA approval timeline compression as the inflection signal for domestic Chinese brand launch acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO₂ Technology Upgrade | Pharmaceutical-grade standardization unlocks Japanese PMDA-registered buyer contracts. |
| Backward Integration into Raw Seed Sourcing | Captive supply from Central China wine regions secures crush-season feedstock priority. |
| Dual Kosher-Halal Certification Investment | Alpspure's certification arbitrage model opens Middle East re-export channels. |
| NMPA Blue-Hat Registration Acceleration | SAMR streamlined timelines compress 18-month product launch cycles for domestic formulators. |
| Southeast Asia Beverage Market Entry | Vietnam and Thailand functional drink sectors remain underdeveloped for polyphenol premixes. |
Study Parameters
Operator-level perspectives from extraction facility managers, nutraceutical brand formulators, pharmaceutical procurement leads, and regulatory affairs directors anchored the qualitative base. Secondary validation drew from NMPA registration databases, MFDS approval filings, FSSAI contaminant limit notifications, and customs trade flow records. Bottom-up capacity modeling across Shandong and Zhejiang processing zones triangulated against top-down demand estimates from Japanese distributor import data.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation dimensions spanning extraction technology type, certification tier, end-use channel, and geographic demand cluster. CAGRs derived from capacity expansion announcements, registration pipeline tracking, and buyer procurement intention surveys. Wine industry crush forecasts and supercritical equipment installation pipelines served as industry-specific demand and supply-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed consolidation platforms or state-sponsored Chinese extraction capacity expansions would shift outcomes. Cross-checking against Japanese Ministry of Health, Labour and Welfare import inspection data and PMDA pharmaceutical-grade material approvals is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Flax Seed Meal Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Almond Butter Market
Nuts and Seeds
Europe Tahini Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Hazelnut Market