
 Sugarcane Fiber Market | 2026-2036
Sugarcane Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Sugarcane Fiber Market Analytics
ASTM D6400 compostability certification is unwinding competitive access for suppliers lacking industrial composting validation. Sonoco leverages its integrated fiber supply chain to secure raw material consistency across North American operations. Huhtamaki sustains technical leadership through advanced molded fiber forming capabilities. Biopak anchors its position in Australian and UK foodservice channels with certified home-compostable product lines.
Sugarcane fiber consists of lignocellulosic residue from bagasse processing, containing approximately 40-50% cellulose by dry weight, which undergoes mechanical pulping and thermoforming to produce rigid or flexible articles. The material serves primarily as a structural substitute for petroleum-based plastics in single-use and short-cycle durable applications. Disposable plates within the product type dimension lead volume shipments due to direct replacement of polystyrene in foodservice, while compostable bags represent the fastest-growing category as retail chains adopt certified checkout and produce formats. Packaging applications command the largest share of value given premium pricing for moisture-resistant barrier formulations in chilled and hot-food segments.
FDA food contact substance regulations in the United States, EU MDR and REACH frameworks for material migration limits, and BIS compostability standards in India collectively define product eligibility and cross-border market access for sugarcane fiber articles. These standards increasingly incorporate end-of-life performance criteria rather than solely front-of-pipe material safety, shifting investment toward integrated composting infrastructure partnerships. Stakeholders must monitor evolving extended producer responsibility schemes that transfer collection and processing liability upstream to manufacturers and brand owners.
Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing polystyrene serviceware margins while redirecting foodservice procurement toward ASTM D6400-certified bagasse alternatives. This regulatory pressure is reshaping supplier qualification criteria across North American and European institutional channels.
Growth Catalysts
- California and New York state bans:State-level prohibitions on expanded polystyrene food containers are forcing quick-service restaurant chains to validate bagasse plate and bowl specifications for systemwide rollout.
- Industrial composting infrastructure:Municipalities across Germany and the Netherlands are expanding anaerobic digestion capacity, creating offtake certainty for certified compostable packaging generators.
- Quick-service restaurant pledges:Major burger and coffee chains have committed to 100% renewable or recyclable packaging by 2025, specifying molded fiber as the primary structural replacement for plastic lids and clamshells.
Market Restraints
- Bagasse supply concentration:Raw material availability clusters in Brazilian and Indian sugarcane processing regions, exposing converters to harvest-season volatility and freight cost spikes.
- Barrier coating limitations:Current PLA and bio-PBS laminate formulations for hot-food applications exhibit moisture resistance inferior to polyethylene, restricting penetration in soup and sauce segments.
- EU MDR migration testing:Extended laboratory validation timelines for food-contact substance notifications are delaying product launches by 12-18 months for non-European suppliers.
Strategic Opportunities
- Home-compostable certification gap:Australian and UK retail channels are prioritizing AS 5810 and EN 13432 home-compostable grades over industrial-only alternatives, rewarding early certifiers with shelf-space commitments.
- Chilled ready-meal trays:European supermarket private-label programs are specifying high-barrier bagasse trays for microwaveable curry and pasta formats, opening a premium price tier above standard foodservice disposables.
- Digital print integration:Direct-to-mold inkjet decoration technology is enabling short-run customized branding for regional restaurant chains, collapsing minimum order quantities from 50,000 to 5,000 units.
Industry Challenges
- ASTM D6400 audit backlog:Third-party laboratory capacity constraints are extending certification timelines, forcing converters to delay customer qualification samples.
- Thermoforming tooling capex:Precision aluminum mold fabrication for complex geometries requires capital commitments exceeding standard pulp molding equipment by 40%, straining mid-scale producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugarcane Fiber Market |
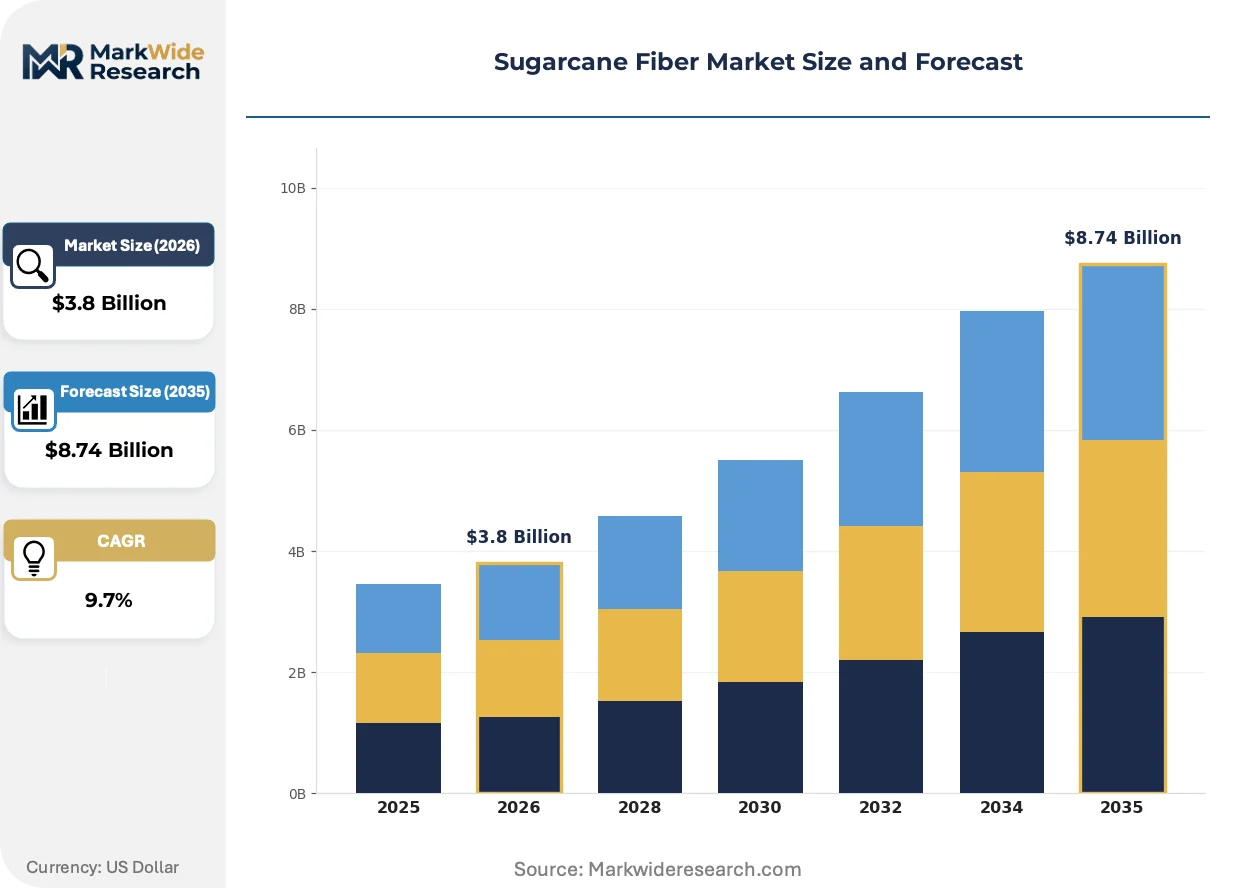
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compostable Bags, Disposable Plates, Fiberboard, Textiles Application: Packaging, Agriculture, Foodservice, Construction End User: Consumer Goods, Food and Beverage, Retail, Textile Manufacturers Form: Sheet, Granule, Web, Film |
| Companies Covered | Sonoco, Dart Container, Biopak, Huhtamaki, Pactiv Evergreen, Berry Global, Detmold Group, Vegware, Good Start Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugarcane Fiber Market Evolving Landscape
Active R&D investment is compressing the performance gap between bagasse articles and petroleum-based alternatives. Three converging developments are redefining technical specifications and procurement criteria across foodservice and retail channels.
Barrier coating technology is miniaturizing. Nanocellulose and bio-wax laminate formulations are replacing conventional PLA films in hot-food clamshell applications. Quick-service chains in California and New York are validating these grades for fried chicken and rice bowl formats. The technology is miniaturizing the thickness requirements for grease resistance, reducing material weights by 15-20% versus first-generation bagasse products.
REACH framework amendments are tightening food-contact migration limits for mineral oil saturated hydrocarbons. ECHA guidance documents issued in 2024 are requiring additional testing for recycled fiber content in molded articles. Chilled dairy and deli packaging segments serving German and French retail channels are reformulating away from post-consumer pulp blends to virgin bagasse fiber to ensure compliance.
Centralized procurement teams at institutional catering operators are consolidating supplier panels from twelve vendors to three approved partners. Technical audits now weight compostability certification, integrated mold design capability, and geographic production proximity equally. This consolidation is most visible in UK hospital and university foodservice contracts, where Sodexo and Compass Group have issued single-source bagasse mandates for 2025-2028 periods.
Sugarcane Fiber Market Segmentation
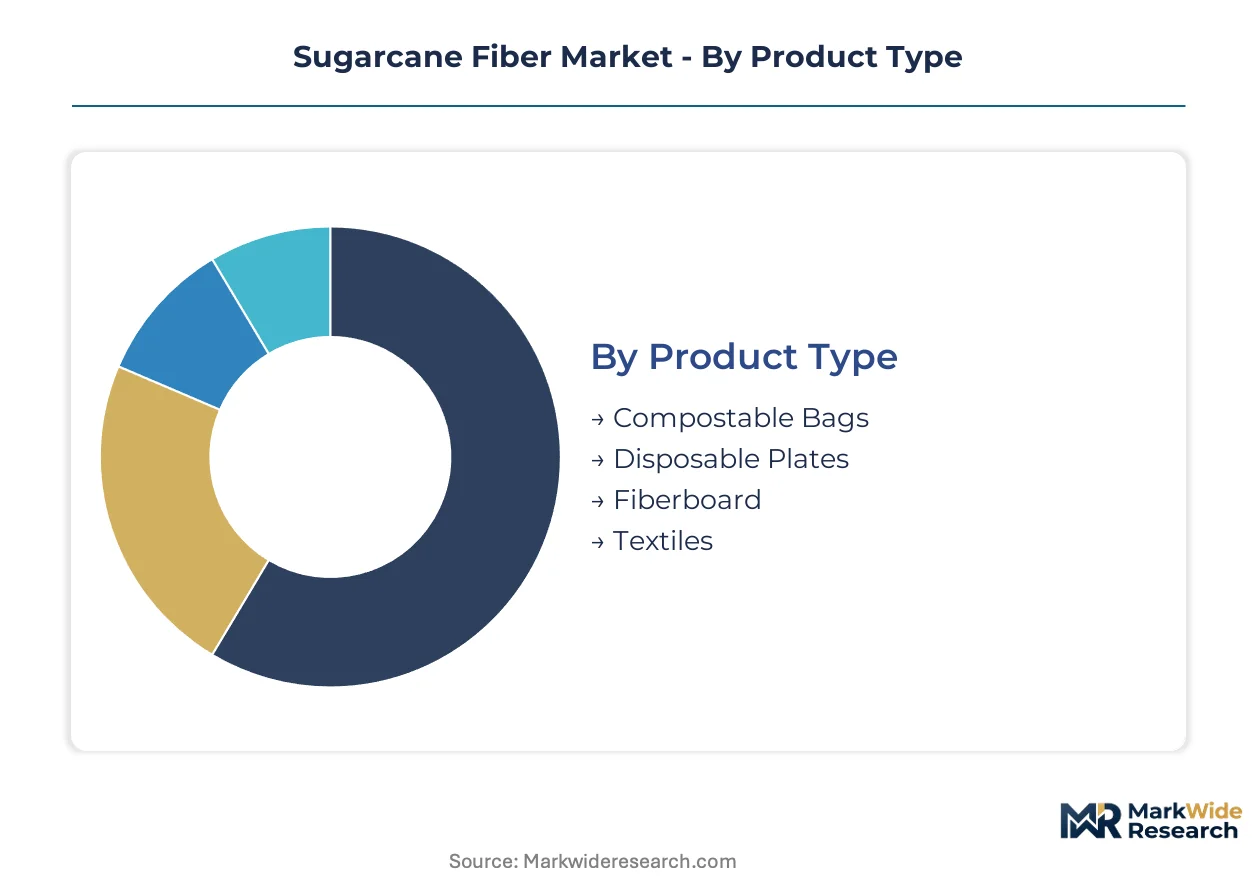
Channel differentiation in sugarcane fiber markets determines specification requirements and certification burdens. Foodservice procurement teams prioritize ASTM D6400 validation, while retail buyers demand home-compostable grades. Understanding segment-channel alignment exposes where margin concentrates and where commoditization threatens.
Product Type:
Channel mix varies sharply by product form: foodservice distributors dominate rigid molded articles, while retail chains control flexible packaging flows. Industrial buyers source fiberboard through direct mill relationships, bypassing distribution markups.
- Disposable Plates:Thermoformed bagasse articles with pressed-rim construction for structural rigidity under hot-food loads. Quick-service restaurant chains in California and New York validate these specifications for systemwide polystyrene replacement programs. ASTM D6400 certification is non-negotiable for institutional contract eligibility.
- Compostable Bags:Flexible films and pouches extruded from bagasse pulp blends with PLA laminate barriers for moisture resistance. UK and Australian supermarket chains prioritize AS 5810 and EN 13432 home-compostable grades for produce and checkout applications. Retail shelf-space commitments flow to early certifiers.
- Fiberboard:High-density pressed panels for protective packaging and display applications.
- Textiles:Non-woven webs for disposable medical and hygiene applications.
By volume, disposable plates lead. By growth pace, compostable bags are climbing the fastest.
Application:
Cost tier segmentation separates premium barrier formulations from commodity molded articles. Chilled ready-meal applications command 40% price premiums over standard foodservice disposables due to microwaveable performance requirements.
- Packaging:Moisture-resistant barrier formulations for chilled and hot-food segments. European supermarket private-label programs specify high-barrier bagasse trays for microwaveable curry and pasta formats. REACH framework amendments on mineral oil migration limits are pushing reformulation toward virgin fiber.
- Foodservice:Single-use serviceware for quick-service restaurants and institutional catering. Sodexo and Compass Group have issued single-source bagasse mandates for UK hospital and university contracts. Centralized procurement consolidation from twelve vendors to three approved partners is reshaping supplier access.
- Agriculture:Biodegradable mulch films and plantable pots for commercial farming operations.
- Construction:Fiber-reinforced panels and insulation substrates for green building projects.
Packaging captures the largest value share. Foodservice is expanding most quickly as state-level plastic bans accelerate.
End User:
Customer type determines order scale and customization depth. Food and beverage buyers run 500,000-unit annual contracts, while textile manufacturers experiment with 5,000-unit pilot orders.
- Food and Beverage:Brand owners specifying molded fiber for primary and secondary packaging. Major burger and coffee chains have committed to renewable packaging targets, driving volume concentration. Direct-to-mold inkjet decoration is enabling short-run regional customization.
- Retail:Supermarket and convenience store operators adopting certified compostable formats for private-label programs. Home-compostable certification gaps in Australian and UK channels are rewarding early movers with exclusive supply agreements.
- Consumer Goods:Household product companies evaluating bagasse for secondary packaging applications.
- Textile Manufacturers:Apparel and hygiene producers testing non-woven bagasse blends for disposable applications.
Food and beverage leads by contract value. Retail is gaining share fastest through home-compostable certification differentiation.
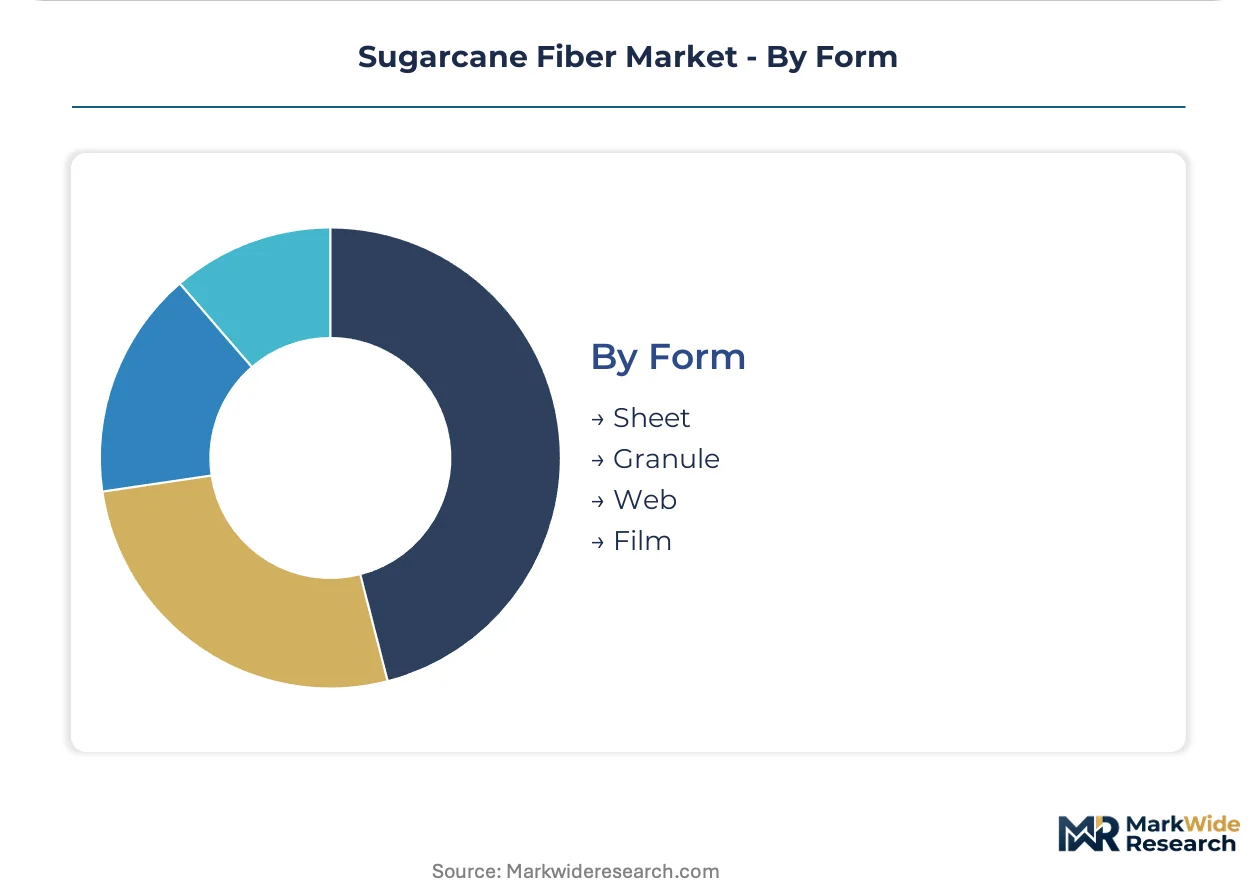
Form:
Supply concentration clusters in sheet and web formats where thermoforming infrastructure already exists. Granule and film segments require extrusion capacity that remains limited outside Brazilian and Indian processing regions.
- Sheet:Pressed pulp sheets for thermoforming into rigid containers and trays. Precision aluminum mold fabrication for complex geometries requires capital commitments exceeding standard pulp molding equipment. Mid-scale producers face balance sheet strain.
- Web:Continuous non-woven mats for textile and filtration applications. German and Dutch industrial composting infrastructure expansion creates offtake certainty for certified generators serving these formats.
- Granule:Densified fiber particles for injection molding and composite blending.
- Film:Cast or blown flexible substrates for bag and pouch conversion.
Sheet dominates current volume shipments. Web formats show the steepest expansion trajectory as barrier coating technology miniaturizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant procurement teams in California and New York are validating bagasse specifications for systemwide rollout. Institutional catering operators in the United Kingdom and Germany are consolidating supplier panels to three approved partners. Brazilian and Indian sugarcane processing regions anchor raw material flows for global converters.
United States
California and New York state bans on expanded polystyrene containers are forcing quick-service chains to validate bagasse plate and bowl specifications. FDA food contact substance regulations define product eligibility for interstate commerce. Los Angeles and New York City foodservice clusters are driving ASTM D6400 certification requirements for institutional contracts.
Germany
Municipalities across Bavaria and North Rhine-Westphalia are expanding anaerobic digestion capacity for certified compostable packaging offtake. ECHA guidance documents issued under REACH framework amendments are tightening mineral oil migration limits for food-contact articles. The Rhine-Ruhr industrial corridor is reformulating chilled dairy packaging toward virgin bagasse fiber to ensure compliance.
United Kingdom
Sodexo and Compass Group have issued single-source bagasse mandates for hospital and university foodservice contracts covering 2025-2028 periods. EN 13432 home-compostable standards are prioritizing AS 5810-certified grades for retail shelf-space commitments. London and Southeast England procurement hubs are consolidating vendor panels from twelve suppliers to three approved partners.
Brazil
Sugarcane processing concentration in São Paulo and Minas Gerais states exposes converters to harvest-season volatility and freight cost spikes. The country's national standards body sets compostability benchmarks for export-bound fiber articles. The Campinas industrial cluster hosts thermoforming operations serving North American quick-service restaurant chains.
India
BIS compostability standards are defining cross-border market access for sugarcane fiber articles targeting European and North American channels. Maharashtra and Gujarat sugarcane belt processing regions supply lignocellulosic residue for mechanical pulping operations. The Pune-Ahmedabad manufacturing corridor is expanding molded fiber forming capacity for foodservice export contracts.
Sugarcane Fiber Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive fiber supply chains and specialized molded fiber converters. The supplier base concentrates around three strategic archetypes: multinational diversified packaging groups with thermoforming scale, regional compostable serviceware specialists with certification depth, and integrated sugarcane processors with backward control over raw material. Competitive moves center on capacity expansion in industrial composting corridor proximity and portfolio diversification into home-compostable certified grades.
Among integrated packaging groups, Sonoco and Huhtamaki exemplify archetypes with supply chain integration and advanced forming capabilities respectively. Biopak occupies a position within the regional specialist tier, anchoring Australian and UK foodservice channels with certified product lines. Dart Container and Pactiv Evergreen sit within the scale-driven segment, representing North American foodservice supply consolidation. Detmold Group and Vegware exemplify certification-focused specialists targeting premium retail and institutional segments with validated compostable grades.
| Leading Market Players |
|---|
| Sonoco |
| Dart Container |
| Biopak |
| Huhtamaki |
| Pactiv Evergreen |
| Berry Global |
| Detmold Group |
| Vegware |
| Good Start Packaging |
| Others |
Value Network & Pricing Analysis
Ninety-day raw material inventory cycles at Brazilian bagasse processors compress converter margins during harvest-season volatility while amplifying pricing power for integrated suppliers with captive fiber supply. This inventory-to-pricing linkage rewards backward integration into São Paulo and Minas Gerais processing regions where freight cost spikes concentrate.
Pricing Analysis
Cost-plus contracts indexed to Brazilian sugarcane futures dominate converter-processor agreements, with ASTM D6400 certification premiums separating industrial-grade from home-compostable tiers. Price differentiation hinges on barrier coating performance and geographic delivery cost, with California and New York foodservice buyers showing highest sensitivity due to state mandate compliance deadlines. Cost compression in standard foodservice disposables is intensifying as quick-service restaurant procurement consolidates vendor panels, while premium chilled ready-meal trays retain margin through microwaveable barrier formulations.
Supply Chain Analysis
Santos port congestion and trans-Pacific container availability function as chokepoints that expose North American converters to 15-20 day shipping variability. Raw material flows draw from Brazilian and Indian sugarcane belt processing regions, with mechanical pulping operations concentrated in the Pune-Ahmedabad and Campinas corridors. Single-source vulnerability in bagasse supply clusters amplifies harvest-season disruption risk. Distribution runs through foodservice distributors for rigid molded articles and direct mill relationships for fiberboard industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against petroleum-based plastic serviceware, where incumbents must navigate polystyrene displacement accelerated by EU Single-Use Plastics Directive enforcement and converging state-level bans.
For Market Incumbents: Secure ASTM D6400 and home-compostable dual certification to defend institutional contract eligibility against regional specialists. Anchor capacity expansion in German and Dutch industrial composting corridor proximity to capture offtake certainty from municipal anaerobic digestion expansion. Certification depth serves as the primary defensive lever against mid-scale converters with barrier coating limitations.
For New Entrants and Emerging Players: Anchor in UK and Australian retail channels where EN 13432 and AS 5810 home-compostable certification gaps reward early movers with exclusive supply agreements. Target chilled ready-meal tray specifications for European supermarket private-label programs, where microwaveable barrier requirements sustain 40% price premiums above commodity foodservice grades. Digital print integration for short-run regional branding collapses minimum order thresholds and opens fragmented restaurant chain access.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-tethered materials play because extended producer responsibility schemes are transferring collection and processing liability upstream to manufacturers. Acquisition targets should display integrated mold design capability paired with geographic production proximity to institutional catering hubs. Watch industrial composting infrastructure buildout rates as the inflection signal for certified packaging offtake certainty.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bagasse Supply | São Paulo and Minas Gerais fiber capture insulates against harvest-season freight volatility and raw material cost spikes. |
| Dual Certification Investment | ASTM D6400 plus EN 13432/AS 5810 home-compostable validation unlocks UK hospital contracts and Australian retail shelf-space commitments. |
| Barrier Coating R&D Partnership | Nanocellulose and bio-wax laminate development closes performance gaps against polyethylene in hot-food soup and sauce segments. |
| Industrial Composting Corridor Proximity | Bavaria and North Rhine-Westphalia anaerobic digestion expansion creates offtake certainty for certified packaging generators. |
| Digital Print Capability Acquisition | Direct-to-mold inkjet decoration enables 5,000-unit minimum orders for regional restaurant chain customization. |
Research Methodology
A spread of perspectives from thermoforming operations managers, quick-service restaurant procurement directors, industrial composting facility operators, and EU regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA food contact substance filings, ECHA REACH guidance documents, BIS compostability standards, and customs trade flow records. Bottom-up volume modeling across product type and application segments triangulated against top-down macroeconomic drivers.
Segmentation dimensions modeled include product form, application end-use, certification grade tier, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating quick-service restaurant renewable packaging pledge timelines and state-level mandate implementation schedules. Forecast inputs weight industrial composting infrastructure buildout rates and barrier coating technology maturation curves.
Material uncertainties — harvest-season bagasse availability shocks, ECHA migration limit amendments, and extended producer responsibility scheme adoption timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as these factors evolve. Practitioners should keep alternative scenarios live as municipal composting capacity and retail certification requirements shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Eco Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Acacia Fiber Powder Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Cellulose Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Jute Bags Market
Natural Fibers
Gum Fiber Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market