
 Eco Fibers Market | 2026-2036
Eco Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Eco Fibers Market Analysis
Subscription-based fiber traceability software is consolidating how mills sell certified eco fibers to brands. Lenzing AG leverages its blockchain-verified fiber provenance platform to command premium positioning across European apparel supply chains. Grasim Industries anchors its competitive stance through backward integration into sustainable wood pulp sourcing. Teijin Limited specializes in closed-loop chemical recycling systems for industrial-grade regenerated cellulose.
Eco fibers comprise cellulosic and protein-based textile materials engineered from renewable, biodegradable feedstocks such as bamboo pulp, hemp bast, or lyocell solvent-spun cellulose, typically processed through closed-loop systems achieving over 99% solvent recovery rates. These materials primarily serve industries requiring reduced petrochemical dependency and verified lifecycle environmental credentials. Organic cotton and Tencel currently occupy the largest volume positions within material type segmentation, while hemp registers the fastest expansion due to regulatory relaxation of cultivation controls across multiple jurisdictions. Within end use industry categories, automotive applications generate disproportionate margin pools as seat and panel manufacturers face OEM mandates for interior material recyclability.
The EU Green Deal and ECHA REACH frameworks enforce strict chemical disclosure thresholds on textile imports entering European markets, compelling Asian manufacturers to reformulate dye and finishing chemistries. The US EPA and USDA BioPreferred program jointly steer federal procurement toward certified biobased fiber content in institutional textiles. India's BIS and CDSCO standards increasingly govern pharmaceutical-grade bamboo fiber purity for wound dressing applications. Stakeholders must monitor evolving certification fragmentation between OEKO-TEX, GOTS, and emerging national eco-labels when allocating compliance investment across export destinations.
Market Dynamics
OEM mandates for interior material recyclability are compressing decision cycles across automotive upholstery supply chains, forcing fiber suppliers to certify closed-loop credentials before contract eligibility.
Growth Catalysts
- EU Green Deal enforcement:ECHA REACH chemical disclosure thresholds compel Asian manufacturers to reformulate dye and finishing chemistries, creating certified fiber demand from European importers.
- Automotive recyclability mandates:Seat and panel manufacturers face binding OEM requirements for interior material circularity, directing procurement toward bamboo and hemp blends.
- Hemp cultivation liberalization:Regulatory relaxation across multiple jurisdictions unlocks bast fiber supply previously constrained by controlled-substance classification.
Market Restraints
- Wood pulp input volatility:Sustainable pulp feedstock pricing fluctuates with forestry certification bottlenecks and climate-related harvest disruptions.
- Austrian supply concentration:Premium lyocell capacity clusters around Lenzing manufacturing sites, creating geographic single-point vulnerability for fashion house supply security.
- Lyocell solvent recovery capex:Closed-loop systems achieving over 99% N-Methylmorpholine-N-oxide recovery require substantial upfront investment, excluding smaller mill entrants.
Strategic Opportunities
- Pharmaceutical-grade bamboo fiber:India's BIS and CDSCO standards for wound dressing purity create a high-margin medical textile segment with limited incumbent competition.
- Blockchain-verified provenance:Subscription-based traceability platforms enable mills to capture premium positioning through immutable certification documentation.
- US federal procurement:The EPA and USDA BioPreferred program steers institutional textile contracts toward certified biobased fiber content, opening public-sector volume.
Industry Challenges
- Certification fragmentation:Divergence between OEKO-TEX, GOTS, and emerging national eco-labels forces suppliers to maintain parallel compliance systems across export destinations.
- Chemical recycling integration:Teijin-style closed-loop systems for industrial-grade regenerated cellulose require reconfiguration of legacy viscose production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eco Fibers Market |
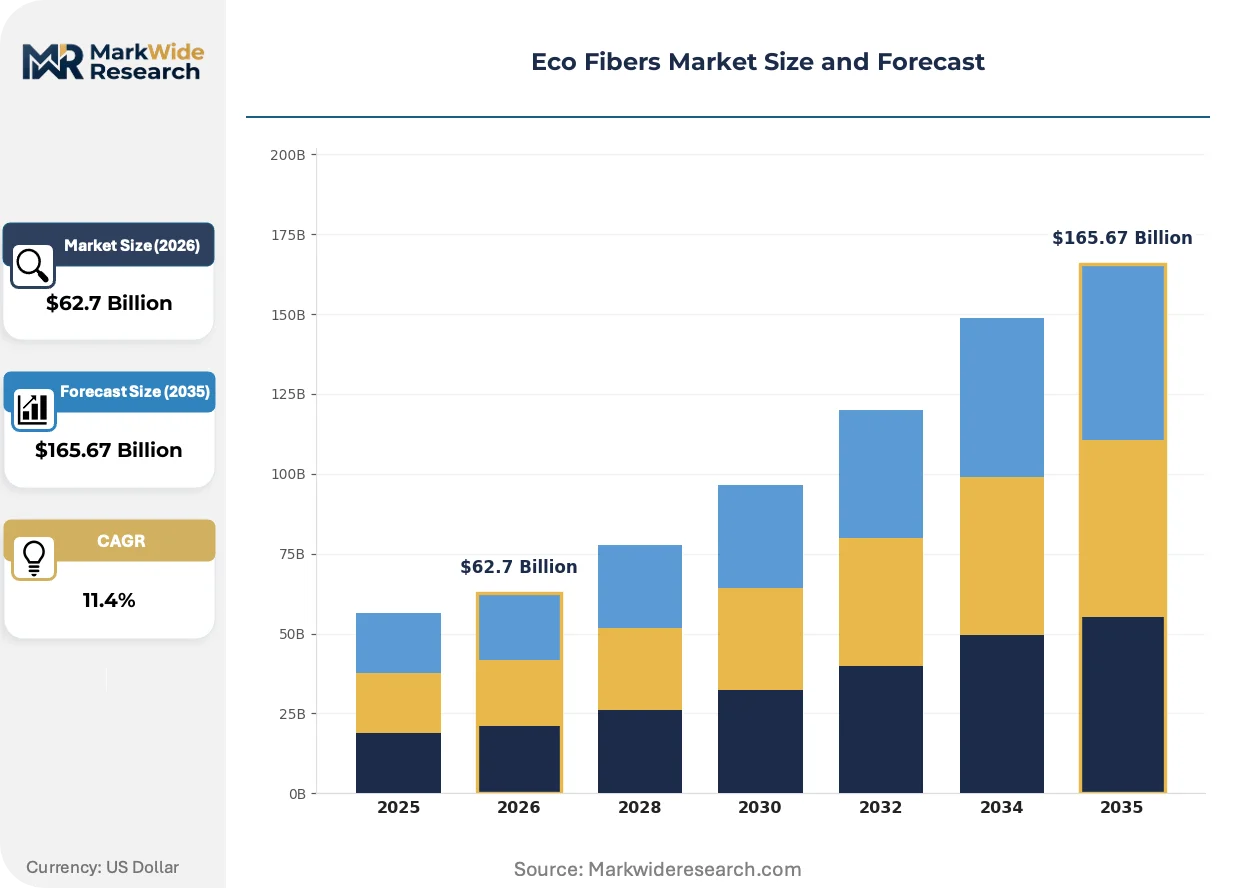
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $165.67 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Organic Cotton, Hemp, Bamboo, Tencel Application: Apparel, Home Textiles, Industrial, Upholstery End Use Industry: Fashion, Interior Design, Automotive, Healthcare Distribution Channel: Online Retail, Specialty Stores, Wholesale, Supermarkets |
| Companies Covered | Lenzing AG, Grasim Industries Ltd., US Fibers, Polyfibre Industries, Sateri, Teijin Limited, Shanghai Tenbro Bamboo Textile Co. Ltd., China Bambro Textile (Group) Co., Ltd., Pilipinas Ecofiber Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eco Fibers Market Emerging Trajectories
Digital traceability infrastructure and solvent recovery automation are compressing the gap between certification promise and verified supply chain execution across fiber manufacturing.
Closed-loop lyocell production is automating solvent recovery monitoring through integrated sensor networks that track N-Methylmorpholine-N-oxide concentration in real time. Austrian manufacturing clusters deploy these systems to maintain the 99%-plus recovery rates required for premium fashion house contracts. This automation is compressing compliance documentation timelines from quarterly audits to continuous verification streams.
REACH chemical disclosure expansion is tightening textile import thresholds across European markets, forcing Asian dye houses to substitute petrochemical finishing agents with bio-based alternatives. The regulation most severely affects polyester-cotton blends entering Germany and France, where customs authorities now require third-party testing documentation at port of entry.
Subscription-based fiber provenance platforms are displacing traditional certificate-based verification as brands demand real-time supply chain visibility. European apparel manufacturers now require blockchain-anchored documentation for every lot of certified eco fiber, replacing the static annual audits that previously sufficed. This behavioral shift concentrates procurement power with mills that have invested in digitized traceability infrastructure.
Eco Fibers Market Segmentation
Eco fiber procurement strategies diverge sharply between standalone material sales and embedded system integrations, with automotive and healthcare buyers demanding pre-certified fiber assemblies while fashion houses source raw inputs for in-house finishing. Understanding these integration patterns clarifies where suppliers can command premium positioning versus commodity volume plays.
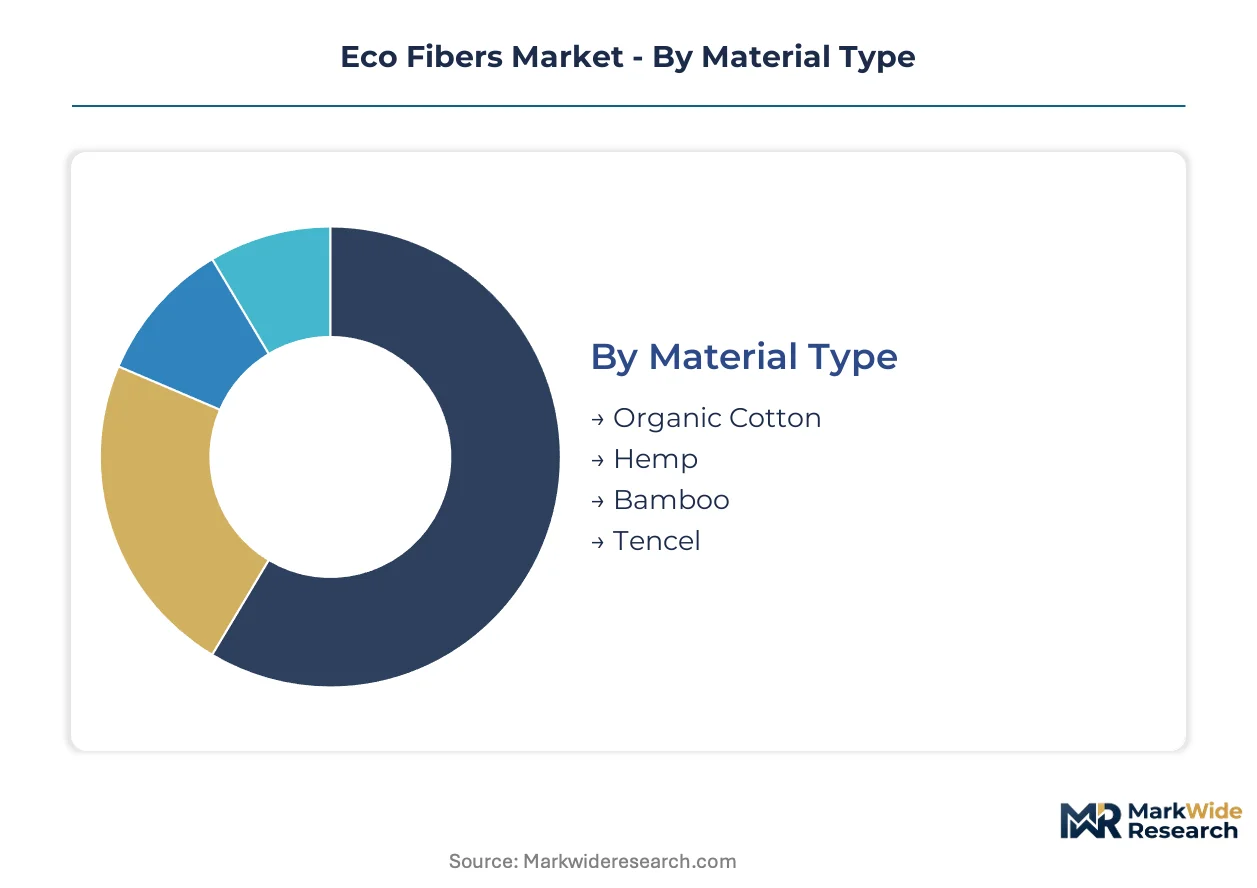
Material Type:
Integration depth varies substantially across fiber categories, with solvent-spun cellulosics demanding tight manufacturing partnerships while bast fibers circulate through more arm's-length trading relationships.
- Organic Cotton:Grown without synthetic pesticides or fertilizers and certified through third-party audit chains, this fiber dominates apparel applications where brands require farm-to-gin traceability documentation. Demand concentrates in Indian and Turkish spinning clusters serving European fashion houses facing ECHA REACH chemical disclosure mandates.
- Tencel:Lyocell produced via closed-loop N-Methylmorpholine-N-oxide solvent systems achieves over 99% chemical recovery rates, embedding directly into Austrian manufacturing clusters that supply premium fashion houses with blockchain-verified provenance. The solvent recovery capex requirements create high barriers to entry, concentrating supply among vertically integrated producers.
- Hemp:Bast fiber from cannabis sativa stalks offers superior tensile strength for industrial composites and automotive panels. Regulatory relaxation across multiple jurisdictions is unlocking cultivation previously constrained by controlled-substance classification.
- Bamboo:Regenerated cellulose from bamboo pulp serves both textile and pharmaceutical-grade applications, with Indian BIS standards now governing wound dressing purity requirements for medical textile segments.
Volume placements concentrate in organic cotton and Tencel; the faster expansion belongs to hemp as cultivation controls ease across North America and Europe.
Application:
Cost tier stratification separates premium positioning in technical upholstery from commodity plays in mass-market home textiles.
- Apparel:Direct-to-garment fiber sales dominate this segment, with brands requiring OEKO-TEX or GOTS certification for consumer-facing sustainability claims. European and Japanese fashion houses drive specification tightening.
- Automotive Upholstery:Seat and panel manufacturers face binding OEM mandates for interior material recyclability, directing procurement toward pre-certified bamboo and hemp blends that meet German and Japanese automotive specifications. This application generates disproportionate margin pools due to technical qualification requirements.
- Home Textiles:Bedding and furnishing applications emphasize cost-competitive certified fiber sourcing, with volume flowing through wholesale and private-label channels.
- Industrial:Nonwoven and composite applications absorb lower-grade fiber outputs, with demand tied to construction and filtration end-uses.
Margin concentration sits with automotive upholstery; home textiles capture the largest absolute volume.
End Use Industry:
Customer type differentiation separates specification-driven buyers with dedicated compliance teams from price-sensitive purchasers relying on trader certification.
- Fashion:Luxury and premium apparel brands mandate blockchain-verified fiber provenance, with Austrian and Italian manufacturing clusters serving as primary supply nodes. Subscription-based traceability platforms are consolidating procurement power among digitized mills.
- Automotive:Tier-1 seat and panel manufacturers face binding circularity requirements from German and Japanese OEMs, compressing decision cycles and forcing fiber suppliers to certify closed-loop credentials before contract eligibility.
- Healthcare:Pharmaceutical-grade bamboo fiber for wound dressings operates under India's BIS and CDSCO purity standards, creating a high-margin segment with limited incumbent competition.
- Interior Design:Commercial and residential furnishing applications emphasize aesthetic performance alongside sustainability credentials, with specification influence residing with design firms and hospitality procurement.
Procurement sophistication peaks in fashion and automotive; healthcare represents the steepest expansion trajectory as regulatory standards proliferate.
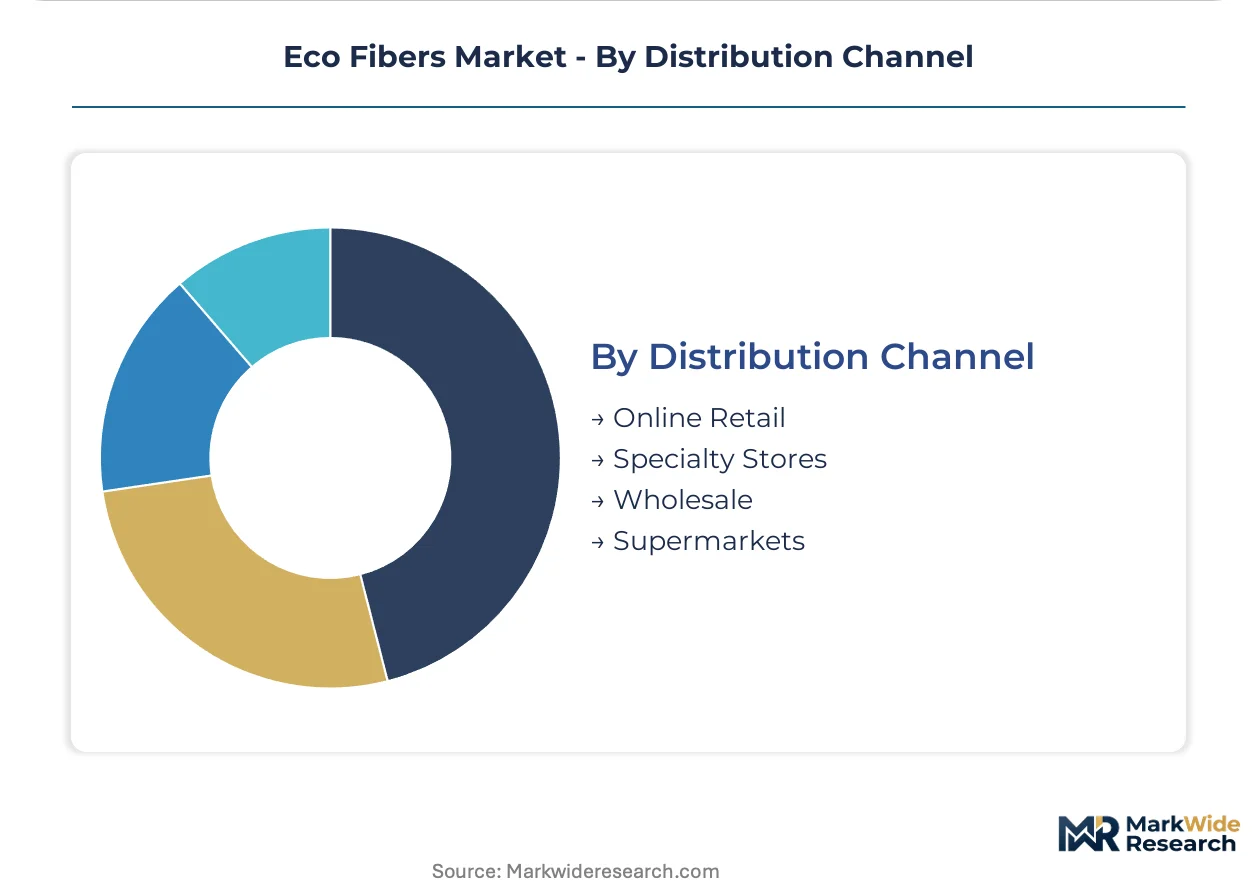
Distribution Channel:
Supply concentration in digital infrastructure separates channel strategies, with traceability-enabled platforms capturing premium positioning.
- Specialty Stores:Dedicated eco-textile retailers serve small-batch designers and craft producers, emphasizing certification transparency and fiber education.
- Wholesale:Volume fiber trading through agent networks dominates industrial and home textile applications, with price competition intensifying as Asian mills expand certified capacity.
- Online Retail:Direct-to-brand digital platforms are displacing traditional certificate-based verification, with European apparel manufacturers now requiring real-time supply chain visibility.
- Supermarkets:Mass-market retail channels emphasize price-competitive certified basics, with private-label programs driving standardization.
Channel investment concentrates in online retail infrastructure; specialty stores retain the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eco fiber production clusters in Austria and India supply consumption centers in Germany and Japan where automotive and fashion end-users enforce strict certification requirements. This geographic split between manufacturing concentration and demand pull shapes investment flows across the value chain.
Germany
Automotive upholstery programs specify bamboo and hemp blends to satisfy ECHA REACH chemical disclosure thresholds for interior materials. The KBA enforces recyclability documentation for seat and panel components entering German assembly plants. Stuttgart manufacturing clusters source pre-certified fiber assemblies from Austrian lyocell producers to meet OEM circularity mandates.
Japan
Tier-1 seat manufacturers face binding requirements from domestic OEMs for interior material traceability and closed-loop credentials. METI guidelines steer procurement toward blockchain-verified fiber provenance platforms. Nagoya industrial corridors concentrate specification authority for automotive textile qualification.
India
Pharmaceutical-grade bamboo fiber for wound dressings operates under BIS and CDSCO purity standards that create high-margin medical textile opportunities. CDSCO oversight of medical device materials compels fiber mills to maintain parallel certification systems for export and domestic pharmaceutical applications. Gujarat spinning clusters serve European fashion houses facing ECHA REACH reformulation pressures.
United States
Federal procurement through the EPA and USDA BioPreferred program directs institutional textile contracts toward certified biobased fiber content. USDA certification requirements for BioPreferred labeling influence supplier qualification for government and university purchasing systems. Southeast textile corridors adapt dye and finishing chemistries to meet disclosure thresholds for European re-export markets.
Austria
Premium lyocell capacity concentrates around Lenzing manufacturing sites serving fashion houses with blockchain-verified fiber provenance. EU Green Deal enforcement through ECHA REACH frameworks sustains demand for closed-loop solvent recovery systems achieving over 99% N-Methylmorpholine-N-oxide recovery. Local production clusters face geographic single-point vulnerability concerns from brands seeking supply security diversification.
Eco Fibers Market Vendor Landscape
Top-tier vendors anchor premium lyocell and solvent-spun cellulosic supply, while mid-scale bast fiber processors and regional viscose producers occupy commodity tiers. Market structure reflects high barriers to entry from solvent recovery capital requirements alongside regulatory fragmentation between OEKO-TEX, GOTS, and national eco-labels. Strategic archetypes include vertically integrated pulp-to-fiber operators, subscription-based traceability platform providers, and specialized pharmaceutical-grade bamboo refiners. Competitive moves concentrate on backward integration into sustainable wood pulp sourcing and digitized certification infrastructure deployment.
Among European and Asian fiber producers, Lenzing AG, Grasim Industries Ltd., and Teijin Limited occupy positions across distinct archetype tiers. Lenzing exemplifies the vertically integrated premium lyocell model with Austrian manufacturing concentration. Grasim Industries represents large-scale pulp-to-fiber integration through backward control over sustainable wood feedstocks. Teijin Limited sits within the industrial-grade regenerated cellulose specialization, particularly around closed-loop chemical recycling systems. These three anchors illustrate how geographic and technological positioning separates premium-provenance suppliers from commodity-grade competitors.
| Leading Market Players |
|---|
| Lenzing AG |
| Grasim Industries Ltd. |
| US Fibers |
| Polyfibre Industries |
| Sateri |
| Teijin Limited |
| Shanghai Tenbro Bamboo Textile Co. Ltd. |
| China Bambro Textile (Group) Co., Ltd. |
| Pilipinas Ecofiber Corporation |
| Others |
Supply Flow & Price Mechanics
ECHA REACH chemical disclosure thresholds gate qualified supply for European automotive and fashion buyers, compressing premium-tier pricing access to mills with certified closed-loop systems and blockchain-verified provenance documentation. This regulatory filter concentrates pricing power among Austrian lyocell producers and Indian organic cotton clusters while excluding smaller dye houses lacking reformulation capacity.
Pricing Analysis
Margin tightening in standard-grade viscose reflects Asian mill expansion and certification oversupply as OEKO-TEX and GOTS audit capacity outpaces brand procurement growth. Three-tier pricing structure across pharmaceutical-grade bamboo, blockchain-verified lyocell, and commodity organic cotton separates buyers by documentation burden and end-use qualification requirements. Cost-down pressure on home textile fibers accelerates because wholesale channel consolidation concentrates volume leverage with large private-label programs. Fashion houses show least price sensitivity for Austrian Tencel with real-time traceability, while industrial nonwoven buyers drive hardest bargain on hemp bast fiber.
Supply Chain Analysis
Sustainable wood pulp supply rests on FSC-certified forestry operations in Austria, Sweden, and Brazil where climate-related harvest disruptions and certification bottlenecks create input volatility. N-Methylmorpholine-N-oxide solvent, organic cotton ginned in India and Turkey, and hemp bast from North American and European cultivation zones constitute critical feedstock dependencies. Single-source vulnerability concentrates around Lenzing manufacturing sites for premium lyocell, exposing fashion house supply security to geographic concentration risk. Distribution runs through subscription-based traceability platforms for certified fiber sales to European brands, with wholesale agent networks handling industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solvent-spun lyocell production is displacing legacy viscose manufacturing as closed-loop chemical recovery systems achieve regulatory compliance and brand preference simultaneously. This technology transition rewards early movers with certification infrastructure and penalizes stranded viscose capacity.
For Market Incumbents: Extend blockchain-verified provenance platforms into pharmaceutical-grade bamboo fiber segments before CDSCO standards harden compliance barriers for wound dressing applications. Defend lyocell margin position by locking long-term offtake with Stuttgart automotive clusters facing KBA recyclability mandates, while accelerating solvent recovery automation to exclude smaller mill entrants from premium fashion house contracts. For New Entrants and Emerging Players: Tier-2 automotive seat manufacturers in Nagoya industrial corridors represent an underserved buyer archetype seeking pre-certified hemp-bamboo blends without minimum volume thresholds imposed by Austrian suppliers. Capture this segment through flexible batch sizing and Japanese-language compliance documentation, then leverage METI guideline alignment to expand into Tier-1 qualification pipelines. For Investors and Strategic Acquirers: USDA BioPreferred program contract awards to institutional textile suppliers are the leading indicator that federal procurement volume will concentrate among certified biobased fiber producers with established government sales channels. Position for five-to-ten year horizon consolidation by targeting mid-scale organic cotton spinners with existing BIS audit relationships and underinvested traceability infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Wood Pulp | Captive FSC-certified feedstock secures margin against Austrian supply concentration and climate harvest disruption. |
| Blockchain-Verified Provenance Platform Deployment | Real-time certification documentation meets European fashion house procurement mandates and displaces static annual audits. |
| Pharmaceutical-Grade Bamboo Fiber Refinement | CDSCO and BIS wound dressing purity compliance opens high-margin medical textile segment with limited incumbent competition. |
| Closed-Loop Solvent Recovery Automation | Integrated sensor networks maintaining 99%-plus N-Methylmorpholine-N-oxide recovery compress compliance timelines to continuous verification. |
| Long-Term Automotive Supply Agreement | Binding OEM circularity mandates from German and Japanese manufacturers create multi-year offtake security for certified fiber assemblies. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fiber mill technical directors, automotive Tier 1 procurement managers, fashion house sustainability leads, and pharmaceutical textile quality officers. ECHA REACH enforcement documentation, USDA BioPreferred certification databases, and Indian CDSCO medical device material standards provided regulatory validation. Bottom-up fiber production estimates from Austrian, Indian, and Southeast Asian manufacturing clusters were triangulated against top-down apparel and automotive consumption forecasts.
Data-stream reconciliation across material type volumes, end-use industry demand patterns, and distribution channel flows shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include fiber category, application tier, customer procurement sophistication, and regional regulatory cluster. CAGRs were derived from regression analysis of historical capacity expansion and brand certification adoption curves, with specific adjustment for hemp cultivation liberalization timelines and lyocell solvent recovery capex cycles.
Revisions become necessary when ECHA REACH chemical disclosure thresholds tighten beyond current dye house reformulation capacity, when Austrian supply concentration triggers forced geographic diversification by major brands, or when CDSCO pharmaceutical-grade standards extend beyond wound dressings into broader medical textile categories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Global Cotton Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Down and Feather Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Green Fibers Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
North America Textile Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Silk Mask Market
Natural Fibers
Acoustic Cotton Market