
 North America Textile Market | 2026-2036
North America Textile Market Size, Share, and Industry Trends Forecast 2026-2036
North America Textile Market Analytics
Subscription-based fabric care and maintenance programs is pivoting how textile suppliers monetize long-term customer relationships. Milliken & Company leverages its chemical technology heritage to dominate performance fabric coatings. Mohawk Industries anchors North American carpet and flooring textile production through extensive manufacturing scale. DuPont de Nemours Inc. specializes in advanced fiber polymers that differentiate industrial and protective textile grades.
Textiles encompass flexible materials constructed from interlaced yarns or fibers, with specifications typically measuring tenacity in grams per denier and abrasion resistance in Martindale cycles, serving functions from moisture management to ballistic protection across commercial and industrial applications. Technical textiles now lead product type expansion as automotive airbag substrates and medical implant meshes command premium positioning. Cotton and polyester material segments occupy divergent margin pools, with organic cotton drawing sustainability premiums while recycled polyester feeds circular economy mandates in apparel and home textiles. Wholesale distribution channels sustain volume throughput for industrial buyers, though direct sales to contract furniture manufacturers concentrate higher-margin upholstery fabric transactions.
The U.S. Environmental Protection Agency enforces wastewater discharge standards under the Clean Water Act that constrain dyeing and finishing operations, while OSHA mandates permissible exposure limits for formaldehyde and other textile chemicals in manufacturing facilities. The Federal Trade Commission's Textile Fiber Products Identification Act shapes labeling requirements that influence consumer transparency and market access for imported goods. Stakeholders must monitor how state-level extended producer responsibility legislation evolves, as California and New York policy experiments could redefine cost allocation across apparel supply chains.
Market Dynamics
The U.S. Inflation Reduction Act's domestic manufacturing incentives are accelerating capital redeployment toward southeastern spinning and weaving clusters, compressing lead times for automotive and medical textile buyers while reshaping supplier geography.
Growth Catalysts
- Automotive airbag substrate demand:Technical textile specifications for lighter-weight, higher-tenacity fabrics are pulling advanced weaving capacity toward Detroit-area Tier 1 suppliers.
- EPA Clean Water Act enforcement:Stricter wastewater discharge standards for dyeing operations are filtering out smaller finishers and concentrating volume among compliant integrated mills.
- Medical implant mesh adoption:Biocompatible synthetic fiber requirements from surgical device manufacturers are expanding North American clean-room textile production.
Market Restraints
- Cotton price volatility:Weather-driven supply fluctuations from Texas High Plains growers compress margin predictability for ring-spun yarn producers.
- Caustic soda and petroleum-based feedstock concentration:Input cost spikes from Gulf Coast chemical producers transmit directly to polyester and cellulosic fiber pricing.
- Formaldehyde permissible exposure limits:OSHA-mandated workplace reductions constrain resin-finishing throughput and extend compliance timelines for smaller cut-and-sew operations.
Strategic Opportunities
- Extended producer responsibility legislation:California and New York policy experiments on apparel end-of-life cost allocation create first-mover advantage for closed-loop fiber recovery infrastructure.
- Digital textile printing convergence:Integration of reactive ink chemistry with on-demand production platforms enables micro-batch customization for contract furniture specifiers.
- Subscription-based fabric care programs:Commercial laundries and hospitality operators are piloting performance-guarantee contracts that shift supplier revenue from unit sales to service outcomes.
Industry Challenges
- Technical textile engineering talent scarcity:Polymer science and advanced weaving process expertise concentrates among aging workforces in North Carolina and South Carolina mill towns.
- FTC Textile Fiber Products Identification Act compliance:Labeling verification for imported component fabrics extends quality-assurance timelines and raises working-capital requirements for upholstery distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Textile Market |
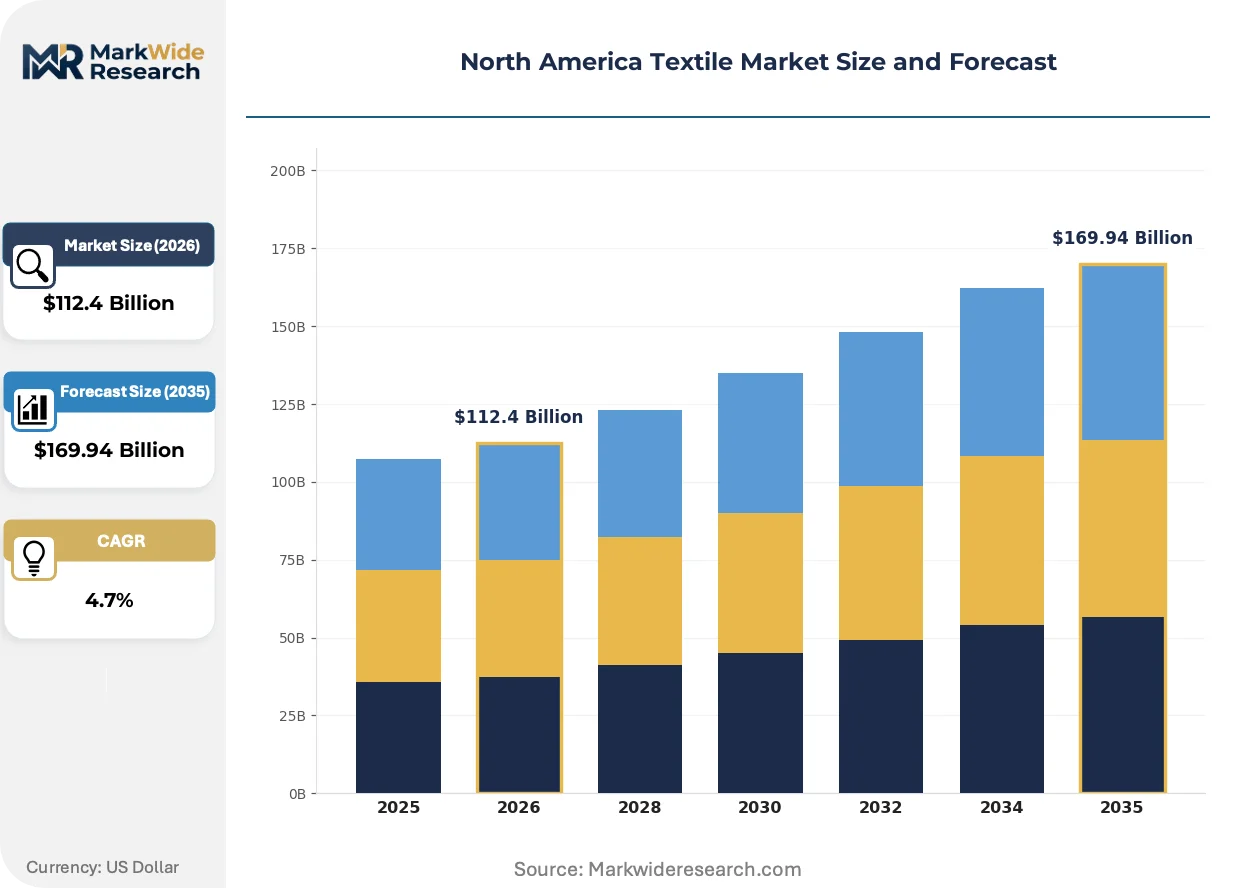
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Fabrics, Non-Woven Fabrics, Knitted Fabrics, Technical Textiles End User: Apparel, Home Textiles, Upholstery, Industrial Applications Distribution Channel: Wholesale, Retail, Online, Direct Sales Material: Cotton, Polyester, Wool, Nylon |
| Companies Covered | Milliken & Company, Mohawk Industries, Parkdale Mills, Shaw Industries Group, Glen Raven, Inc., Elevate Textiles, Inc., Hanesbrands, Inc., Levi Strauss & Co., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Textile Market Evolving Landscape
Digital production technologies and regulatory transparency mandates are converging to compress batch sizes, localize supply chains, and shift buyer value assessment from fiber origin to lifecycle accountability.
Computer-vision-guided loom control systems are automating defect detection and pattern adjustment in real-time weaving operations. Automotive seating manufacturers in Michigan and Ohio are adopting these platforms to reduce airbag fabric rejection rates. The technology is automating quality-assurance labor out of high-speed production lines while enabling single-setup runs for mixed-material technical textiles.
The U.S. Federal Trade Commission's Textile Fiber Products Identification Act enforcement has intensified around recycled-content claims and bamboo-derived fiber labeling. This regulatory pressure is forcing importers to revalidate supply-chain documentation and third-party certifications. Upholstery fabric distributors serving contract furniture manufacturers in the southeastern United States are absorbing the highest compliance costs and extending supplier qualification cycles.
Buyer concentration among large-format commercial laundries and healthcare linen services is consolidating procurement decisions into fewer hands with stricter performance specifications. Direct supplier relationships are replacing wholesale distribution layers for high-volume accounts. This pattern is most pronounced in the upper Midwest, where hospital systems and hospitality chains are centralizing textile sourcing through integrated service contracts rather than spot purchasing.
North America Textile Market Segmentation
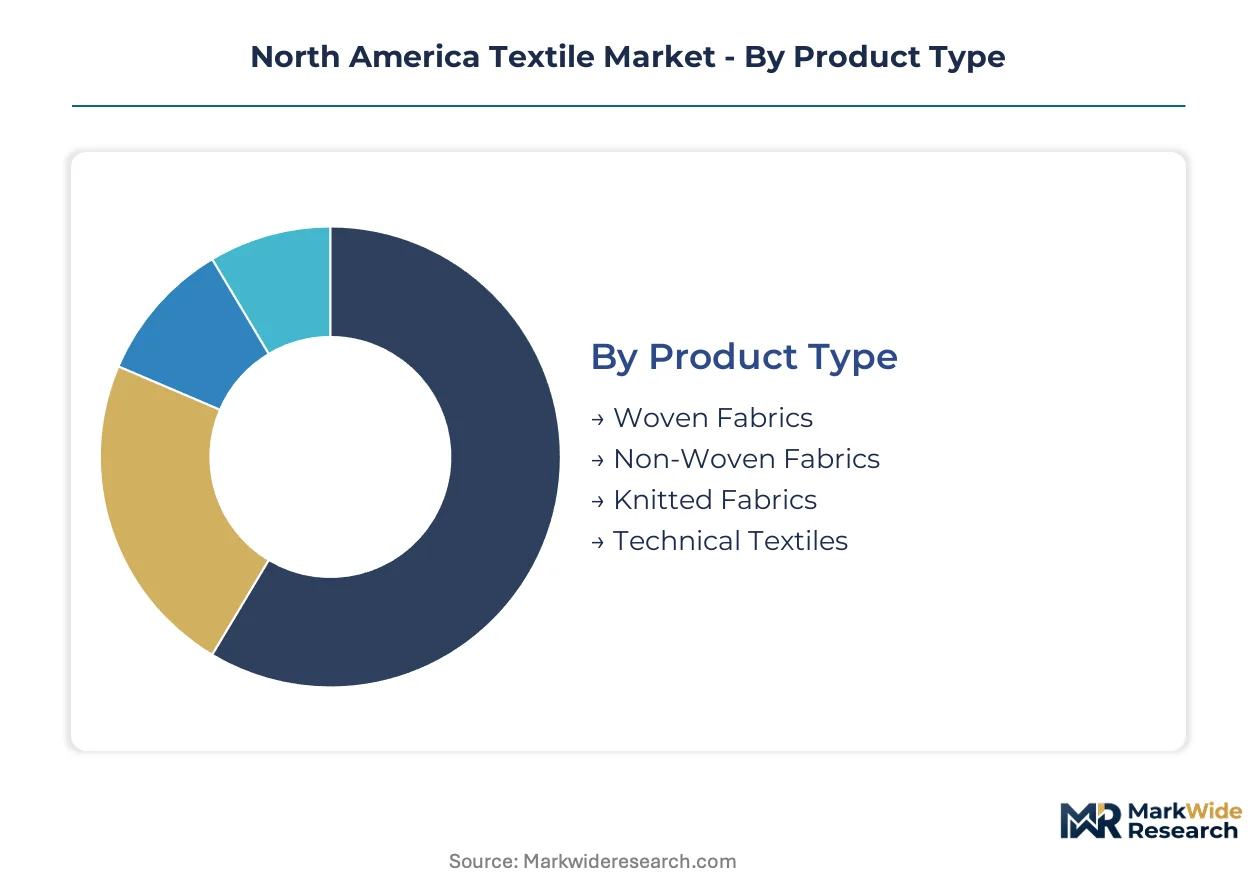
Segmentation in North American textiles separates commodity volume plays from engineered premium positions. Buyers sort procurement strategies by material chemistry, manufacturing process, and end-use performance requirements. Each axis reveals different margin pools and capital intensity profiles.
Product Type:
Woven and non-woven fabrics dominate tonnage, while technical textiles command premium positioning through specialized engineering.
- Technical Textiles:Engineered fabrics with specified tenacity, thermal stability, or biocompatibility for automotive airbag substrates and medical implant meshes. Demand concentrates in Detroit-area Tier 1 automotive suppliers and North Carolina clean-room surgical device manufacturers, pulled by lighter-weight safety mandates and minimally invasive surgical adoption.
- Woven Fabrics:Interlaced yarn constructions measured in picks per inch, serving apparel basics and upholstery foundations. Ring-spun cotton weaving clusters in Georgia and South Carolina supply southeastern furniture manufacturers seeking compressed lead times under IRA domestic manufacturing incentives.
- Non-Woven Fabrics:Fiber webs bonded mechanically or chemically, deployed in filtration media and disposable medical textiles.
- Knitted Fabrics:Loop-structured constructions offering stretch recovery for activewear and compression medical garments.
Today's leader: Woven fabrics. Tomorrow's challenger: Technical textiles.
End User:
Industrial and upholstery applications concentrate procurement scale, while apparel fragments across dispersed brand networks.
- Industrial Applications:Conveyor belting, geotextiles, and protective barriers requiring abrasion resistance above 50,000 Martindale cycles. Demand concentrates in Gulf Coast petrochemical facilities and Great Lakes automotive assembly plants, driven by OSHA-mandated workplace safety upgrades and infrastructure replacement cycles.
- Upholstery:Performance fabrics for contract furniture and hospitality seating with stain-resistant and flame-retardant specifications. North Carolina and Mississippi manufacturers supply commercial laundries and hotel chains through direct service contracts rather than wholesale layers.
- Apparel:Garment construction spanning fast fashion to technical outerwear.
- Home Textiles:Bedding, bath, and decorative fabrics for residential consumers.
Industrial buyers consolidate procurement into fewer hands with stricter performance specifications. Apparel remains fragmented across dispersed brand networks with shorter product cycles.
Distribution Channel:
Wholesale sustains volume throughput for commodity grades, while direct sales capture margin in specification-driven segments.
- Direct Sales:Supplier relationships with contract furniture manufacturers and commercial laundries eliminating intermediary markups. Upper Midwest hospital systems and hospitality chains centralize textile sourcing through integrated service contracts with outcome-based performance guarantees.
- Wholesale:Distributor networks moving commodity volumes to smaller cut-and-sew operations and independent retailers.
- Retail:Branded storefronts and big-box channels for consumer home textiles and apparel basics.
- Online:E-commerce platforms enabling micro-batch customization and rapid replenishment for direct-to-consumer brands.
Direct sales expand fastest as procurement centralizes. Wholesale faces compression from distributor consolidation and working capital pressures.
Material:
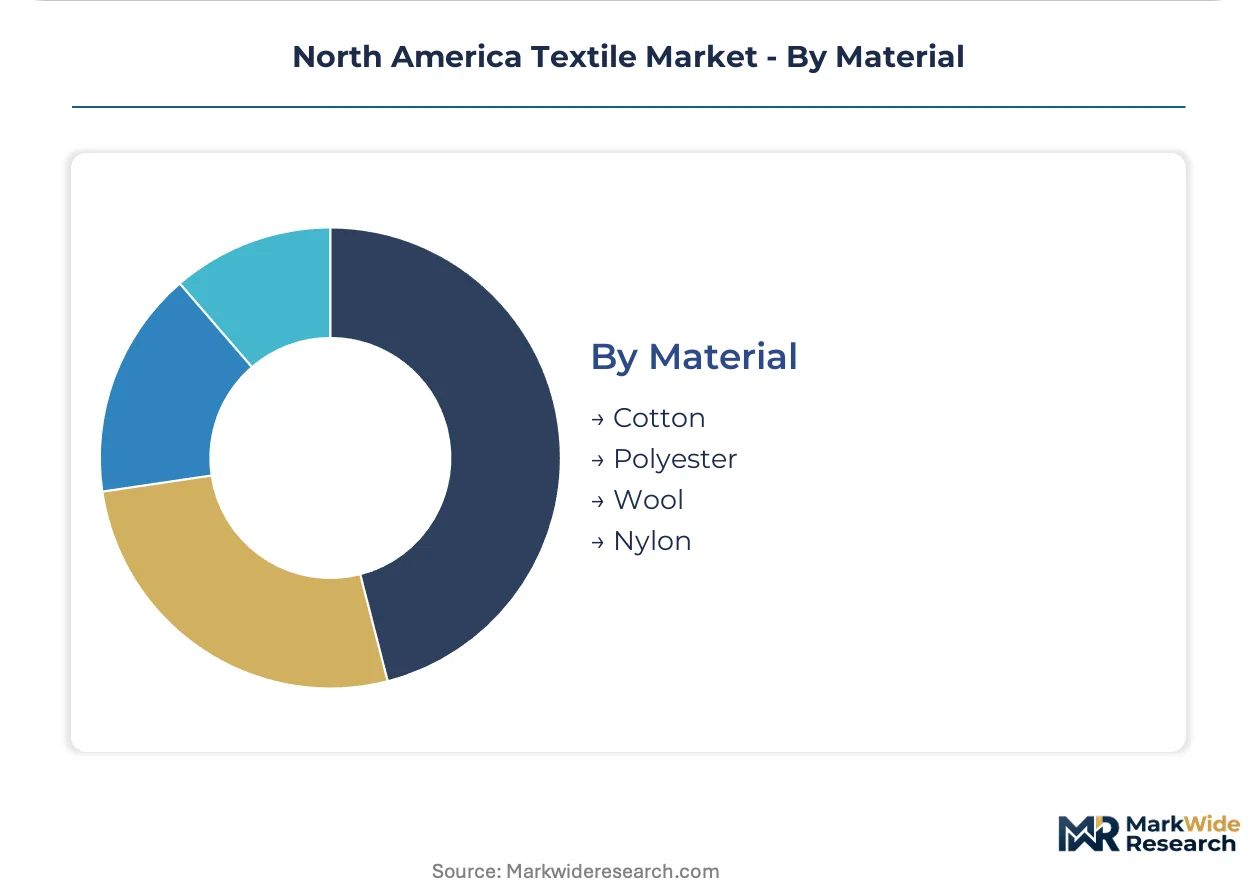
Polyester and cotton split the market by cost position and sustainability positioning, with nylon and wool occupying specialized niches.
- Polyester:Petroleum-derived polymer fibers dominating volume production through melt-spinning efficiency. Recycled PET feedstocks from Gulf Coast chemical producers feed circular economy mandates in apparel and home textiles, though caustic soda price volatility transmits directly to margin predictability.
- Cotton:Cellulosic staple fiber from Texas High Plains and Delta growers, with organic varieties drawing sustainability premiums. Weather-driven supply fluctuations compress margin predictability for ring-spun yarn producers dependent on consistent fiber length and micronaire.
- Nylon:Polyamide engineering for high-tenacity industrial and automotive applications.
- Wool:Protein fiber for premium apparel and acoustic insulation in architectural textiles.
Polyester holds volume dominance. Cotton faces pressure from climate volatility and water-intensive cultivation scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within North America follows regulatory-arbitrage logic, as manufacturers relocate finishing operations to jurisdictions with lower compliance burdens while preserving proximity to major consumer markets.
United States
Automotive airbag substrate demand from Detroit-area Tier 1 suppliers pulls advanced weaving capacity toward Michigan and Ohio. The U.S. Inflation Reduction Act's domestic manufacturing incentives accelerate capital redeployment into southeastern spinning clusters. Georgia and North Carolina mill towns concentrate technical textile engineering expertise for medical implant mesh production.
Canada
Ontario-based automotive seating manufacturers adopt computer-vision-guided loom control systems to reduce fabric rejection rates. Health Canada enforces biocompatibility standards for surgical device textiles that align with U.S. FDA requirements, easing cross-border supply chain integration. Toronto-area clean-room textile producers serve hospital systems across the Great Lakes region.
Mexico
Nuevo León and Chihuahua assembly plants consume industrial textiles for conveyor belting and protective barriers serving Gulf Coast petrochemical facilities. Mexico's proximity to Texas cotton supply chains compresses raw material lead times for ring-spun yarn operations. Border-state finishing plants benefit from lower wastewater compliance costs under less stringent discharge regulations.
North America Textile Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated mills dominating technical textile grades while cut-and-sew contractors handle commodity apparel assembly. The vendor base organizes into three tiers: multinational chemical conglomerates controlling fiber polymer supply, regional weaving specialists capturing automotive and medical specifications, and distributed job shops serving fragmented apparel brands. Competitive moves concentrate on backward integration into fiber production and strategic partnerships with automotive Tier 1 suppliers.
Within the chemical-fiber tier, DuPont de Nemours Inc. anchors advanced polymer positioning for industrial and protective textile grades. Milliken & Company and Mohawk Industries exemplify divergent scale strategies—specialized performance coatings versus carpet and flooring manufacturing breadth. These three entities represent distinct archetypes: materials science origin, chemical technology heritage, and vertical manufacturing scale.
| Leading Market Players |
|---|
| Milliken & Company |
| Mohawk Industries |
| Parkdale Mills |
| Shaw Industries Group |
| Glen Raven, Inc. |
| Elevate Textiles, Inc. |
| Hanesbrands, Inc. |
| Levi Strauss & Co. |
| DuPont de Nemours Inc. |
| Others |
Value Network & Pricing Analysis
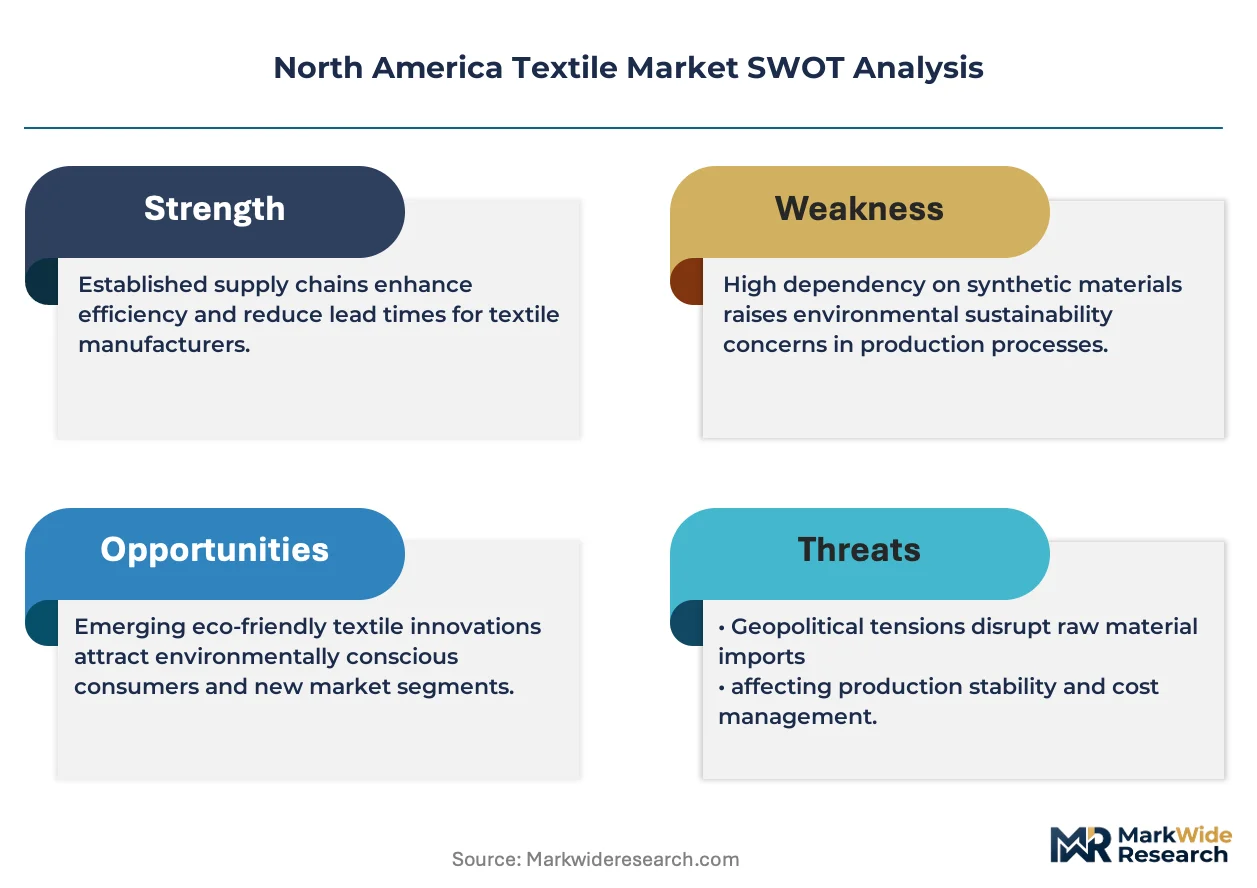
EPA Clean Water Act wastewater discharge standards gate qualified supply for premium-tier technical textile producers, compressing compliant mill capacity while elevating pricing power for integrated operations that absorbed environmental compliance costs. Buyers seeking automotive airbag substrates and medical implant meshes face supply qualification timelines that stratify procurement into specification-validated premium tiers versus commodity spot markets.
Pricing Analysis
Capacity additions in Georgia and North Carolina are reshaping price floors for ring-spun cotton yarns as IRA domestic manufacturing incentives accelerate southeastern spinning cluster expansion. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with organic cotton sustainability premiums widening spreads. Price differentiation stems from formaldehyde-free finishing compliance costs that smaller cut-and-sew operations cannot absorb. Industrial buyers consolidate procurement into direct service contracts with outcome-based performance guarantees, rendering them least price-sensitive, while fragmented apparel brands remain most exposed to cotton price volatility.
Supply Chain Analysis
Reverse-logistics flows for commercial laundry and hospitality linen services are piloting subscription-based fabric care programs that shift supplier revenue from unit sales to lifecycle accountability. Raw material supply concentrates in the United States, Mexico, and Canada, with Texas High Plains cotton and Gulf Coast petrochemical feedstocks anchoring fiber production. Polyester and cellulosic fiber pricing rests on caustic soda and petroleum derivative costs vulnerable to Gulf Coast chemical producer concentration. Single-source vulnerability runs through Detroit-area Tier 1 automotive suppliers for airbag substrate specifications. Distribution runs through direct sales channels for contract furniture manufacturers and commercial laundries, compressing wholesale intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American textile markets present margin-expansion potential as EPA enforcement filters out non-compliant finishers and technical textile specifications command premium positioning. Digital textile printing convergence and closed-loop fiber recovery infrastructure offer cost-down pathways and sustainability premium capture.
For Market Incumbents: Extend performance-guarantee contract structures into hospitality and healthcare linen services, locking in multi-year revenue streams that smaller competitors cannot underwrite. Deepen backward integration into Gulf Coast chemical feedstocks to buffer caustic soda price volatility that compresses polyester margin predictability. Anchor southeastern spinning capacity under IRA incentives before compliance timelines harden for smaller rivals. For New Entrants and Emerging Players: Digital textile printing platforms offer a technology-first wedge into contract furniture micro-batch customization, where reactive ink chemistry integration enables specification-driven positioning without capital-intensive weaving scale. Target North Carolina and Mississippi upholstery manufacturers seeking compressed lead times for stain-resistant hospitality seating. Pursue direct sales relationships with Upper Midwest hospital systems centralizing procurement through integrated service contracts. For Investors and Strategic Acquirers: Roll-up economics work for regional weaving specialists with automotive Tier 1 supplier qualifications because technical textile engineering talent scarcity concentrates among aging workforces in Georgia and South Carolina mill towns. Platform consolidation around clean-room surgical device textile production and automotive airbag substrate specifications offers defensive positioning across a multi-year viability window. Watch California and New York extended producer responsibility legislation implementation as the inflection signal for closed-loop fiber recovery infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Polymers | DuPont de Nemours anchors industrial textile grades through captive polymer supply control. |
| Clean-Room Capacity Expansion | North Carolina surgical device manufacturers pull biocompatible synthetic fiber production toward FDA-aligned standards. |
| Digital Printing Platform Integration | Reactive ink chemistry convergence enables micro-batch upholstery customization for contract furniture specifiers. |
| Direct Service Contract Structuring | Commercial laundries and hospitality operators shift supplier revenue from unit sales to performance outcomes. |
| Closed-Loop Recovery Infrastructure | California and New York EPR experiments create first-mover advantage for fiber-to-fiber recycling operations. |
Research Methodology
Direct dialogue with textile mill operations managers, Tier 1 automotive supplier procurement leads, contract furniture manufacturer specification engineers, and commercial laundry service directors grounded qualitative assessment in operational reality. Secondary validation drew from EPA enforcement records, FTC Textile Fiber Products Identification Act filings, U.S. Customs and Border Protection trade data, and SEC 10-K disclosures from listed textile and chemical producers. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from automotive production forecasts and healthcare linen service procurement patterns.
Segmentation outputs across material chemistry, product construction, end-use application, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from regression analysis against historical capacity deployment, regulatory compliance cost absorption rates, and buyer procurement centralization trends. Automotive airbag substrate specifications and medical implant mesh biocompatibility requirements served as industry-specific demand anchors in the forecast model.
The model holds under sustained IRA domestic manufacturing incentive structures and stable EPA enforcement intensity; deviation in state-level extended producer responsibility legislation rollout or Gulf Coast petrochemical supply disruptions would shift capacity deployment timelines and margin pool distribution. Periodic stress-testing of base assumptions against OSHA formaldehyde exposure limit revisions and cotton yield volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Organic Cotton Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Indonesia Textiles Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Textile Staples Market
Natural Fibers
Down and Feather Market
Natural Fibers
Jute Market
Natural Fibers
Sugarcane Fiber Bowls Market
Natural Fibers
Cellulose Market
Natural Fibers
North America Lyocell Fiber Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Cellulose Fiber Market