
 Woolen Textiles Market | 2026-2036
Woolen Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Woolen Textiles Market Analytics
Modular fabric systems that separate base layers from insulating shells is repositioning how outdoor brands and fashion houses specify wool textiles. Südwolle Group leverages its vertical spinning-to-yarn infrastructure to serve European technical apparel brands. Loro Piana anchors ultra-fine Merino supply for luxury suiting through direct ranch partnerships in Australia and New Zealand. American Woolen Company specializes in heritage-weight blankets and coating fabrics, occupying a defensible niche in domestic US manufacturing.
Woolen textiles are woven or knitted fabrics composed primarily of sheep wool fibers, typically ranging from 15 to 40 microns in diameter, with worsted and woolen-spun yarns differing by fiber alignment and twist density; these materials provide thermal insulation, moisture wicking, and natural flame resistance for apparel, upholstery, and technical applications. Merino-grade wool commands the strongest margin pool in premium apparel due to fineness standards below 19 microns, while the Home Furnishings end-user segment shows structural expansion as interior designers specify wool upholstery for commercial hospitality projects. Blended grades incorporating alpaca or cashmere are gaining share in luxury accessories, though pure Merino retains volume leadership across the analysis window.
REACH in Europe and EPA guidelines in the United States restrict azo dyes and perfluorinated compounds in wool processing, forcing mills to certify water treatment and chemical substitution protocols. The Woolmark Company operates its own fiber certification scheme, which functions as a de facto market access standard for Australian and New Zealand exports into premium channels. Stakeholders must track how emerging ESG disclosure rules in the EU and California reshape traceability requirements from farm to finished fabric.
Market Dynamics
REACH compliance in Europe is compressing chemical processing margins while simultaneously advantaging certified Italian and Portuguese mills that have pre-invested in closed-loop dyeing infrastructure.
Growth Catalysts
- Technical apparel specification:Outdoor brands are integrating wool base layers into modular layering systems for alpine and urban commuting segments. This specification pull is displacing synthetic alternatives in mid-weight insulation categories.
- EU Green Deal procurement mandates:Public sector uniform contracts across Germany, France, and the Netherlands now require biodegradability certifications that wool satisfies inherently.
- Biella cluster concentration:Artisan mills in Italy's Piedmont region supply direct-to-brand programs for Paris and Milan fashion houses, shortening lead times for custom suiting fabrics.
Market Restraints
- Merino fiber cost volatility:Australian wool auction prices swing with drought cycles in New South Wales and Victoria, compressing spinner margins during moisture-deficit seasons.
- Dyehouse concentration risk:Water-intensive finishing operations cluster in northern Italy and Portugal, creating single-point vulnerability for European luxury supply chains.
- Synthetic microfiber substitution:Recycled polyester fleece alternatives capture price-sensitive outdoor and workwear segments where thermal performance outweighs biodegradability preferences.
Strategic Opportunities
- Carbon farming protocols:Australian and New Zealand ranchers are accessing soil carbon credits through verified rotational grazing, offsetting premium fiber premiums for climate-conscious brands.
- Commercial hospitality specification:Interior designers in Dubai, Singapore, and London are specifying wool upholstery for hotel lobbies and co-working lounges, expanding volume beyond traditional residential markets.
- Blockchain traceability convergence:Farm-to-fabric digital verification is unifying with existing Woolmark certification to create dual-layer provenance guarantees for luxury channels.
Industry Challenges
- Master finisher attrition:Europe's pool of skilled mordant dyers and fulling specialists is contracting as generational transitions fail to replenish technical expertise in traditional wool processing.
- Capex intensity for ZDHC compliance:Zero Discharge of Hazardous Chemicals certification requires effluent treatment investments that smaller Portuguese and Romanian mills struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woolen Textiles Market |
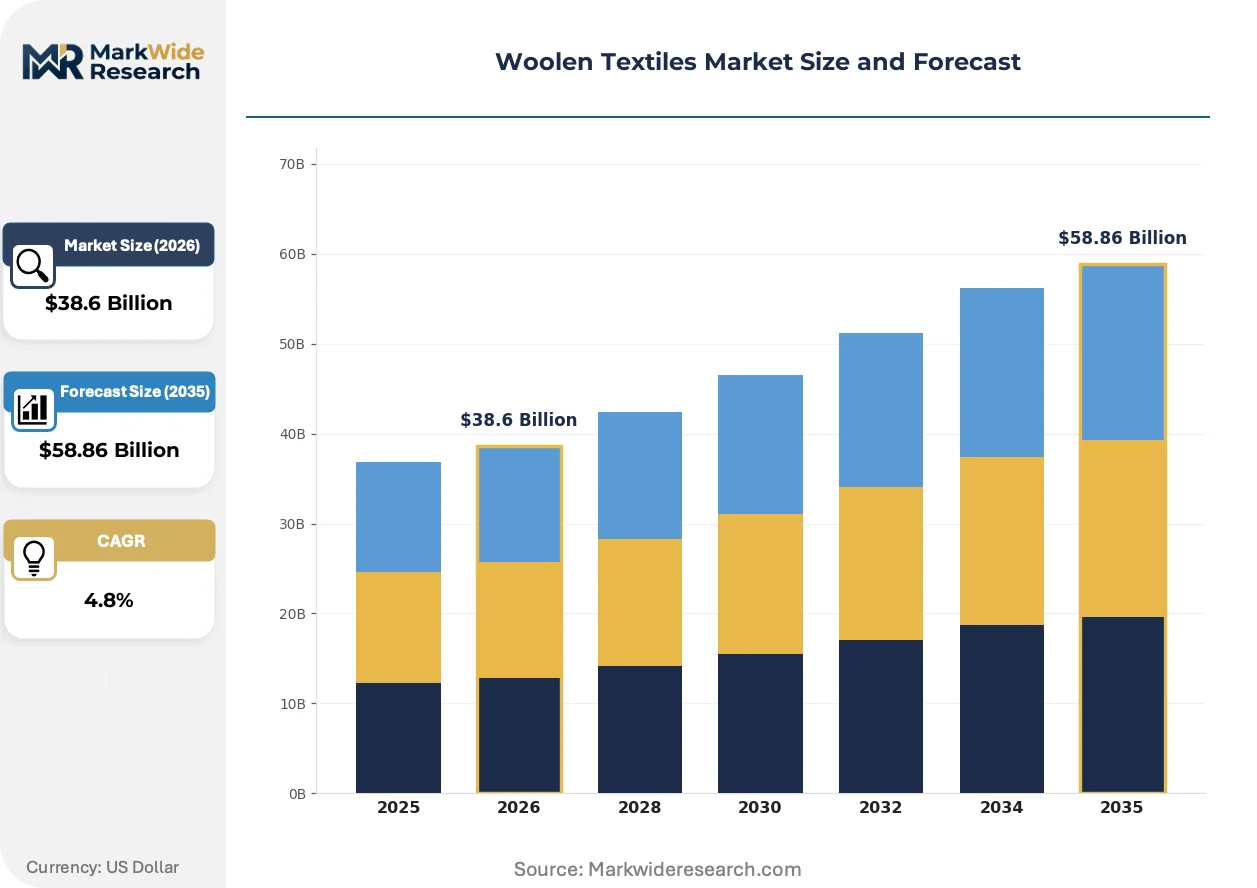
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wool Fabric, Yarn, Blankets, Garments End User: Fashion Industry, Home Furnishings, Automotive Interiors, Outdoor Gear Grade: Merino, Cashmere, Alpaca, Blended Application: Apparel, Upholstery, Insulation, Carpets |
| Companies Covered | The Woolmark Company, Südwolle Group, American Woolen Company, Geetanjali Woolens, Milan Fabric Srl, Loro Piana, Reda, Dormeuil, Ferney Spinning Mills Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woolen Textiles Market Evolving Landscape
Wool processing is bifurcating between heritage craft preservation and precision-engineered technical specifications, with digital tools bridging both pathways.
Plasma surface treatment is unifying hydrophilic performance with retained hand-feel for next-to-skin applications. Athletic apparel brands in Germany and Switzerland are adopting these treated Merino knits for marathon and cycling collections. The technology is compressing the traditional scour-carbonize-dye sequence into fewer wet processing stages.
REACH Annex XVII restrictions on perfluorinated compounds are forcing mills to reformulate durable water repellent finishes. Portuguese and Italian finishers are piloting bio-based alternatives derived from plant waxes and silicones. Luxury outerwear brands are absorbing higher unit costs to maintain European manufacturing claims.
Brand direct sourcing is consolidating procurement relationships with top-tier Australian and New Zealand wool brokers. Fashion houses in Milan and Paris are bypassing traditional trader intermediaries to secure clip-specific lots with documented micron profiles. This disintermediation is most visible in ultra-fine Merino categories where fiber diameter consistency commands measurable price premiums.
Woolen Textiles Market Segmentation
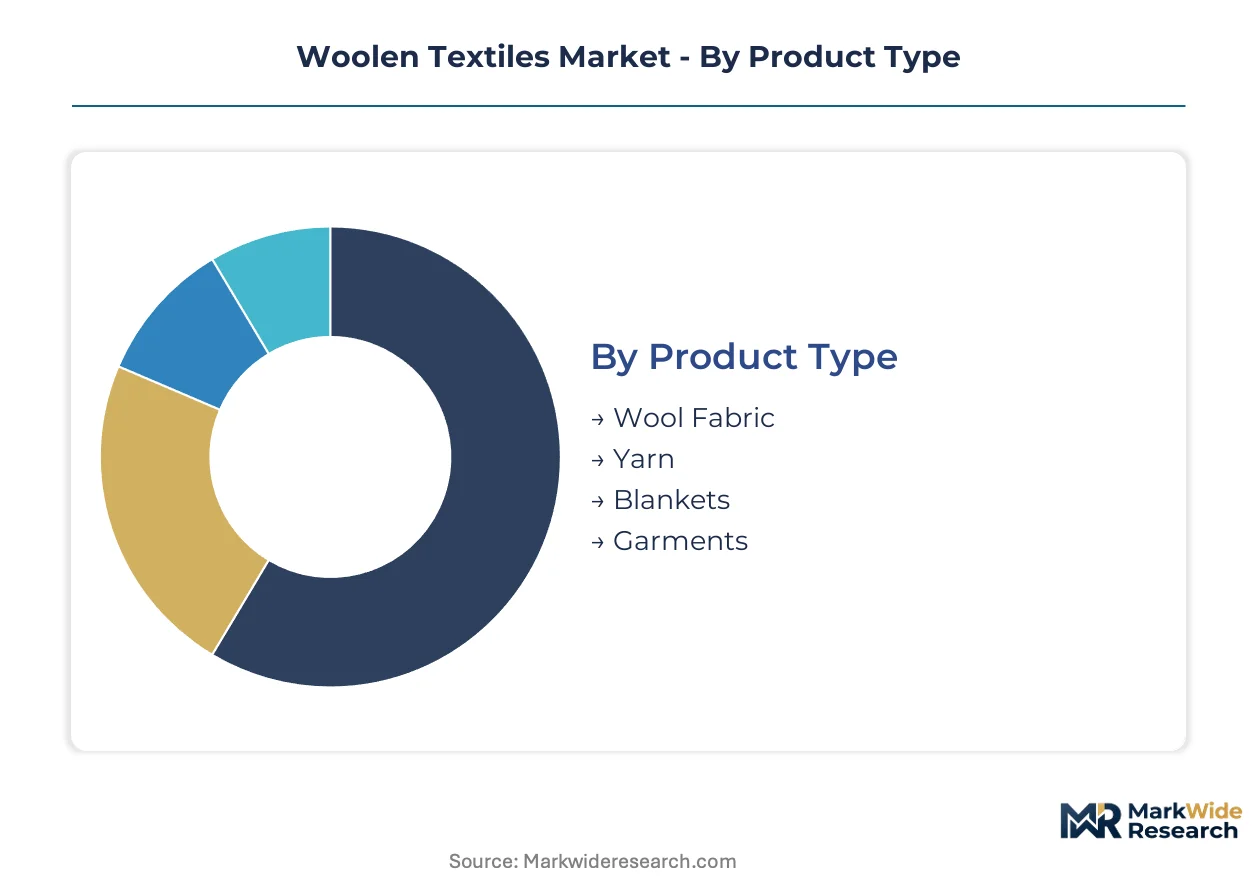
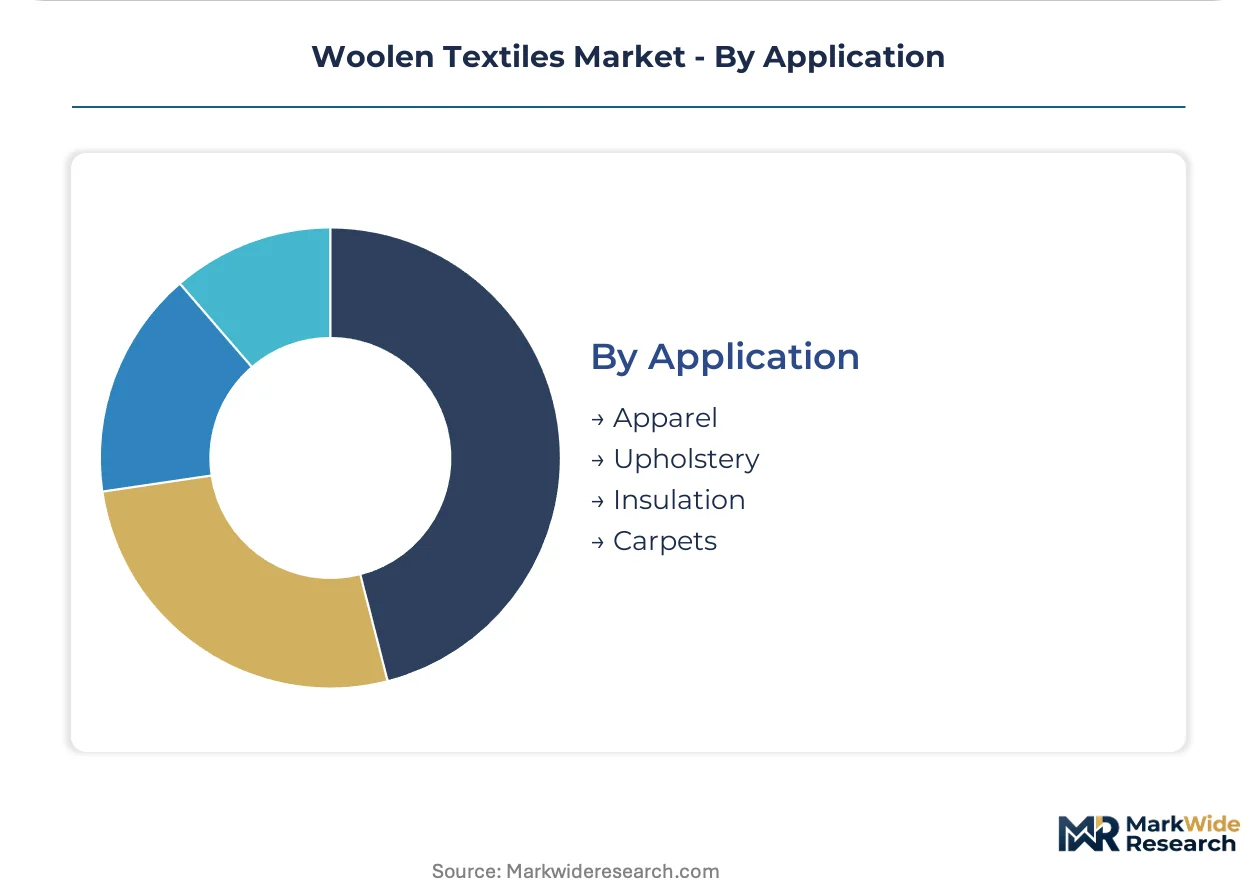
Woolen textiles fragment across four distinct classification axes, each reflecting divergent margin structures and sourcing requirements. Product type and grade classifications determine fiber procurement protocols, while end-user and application segments dictate finishing specifications and certification burdens.
Product Type:
Supply concentration in Biella, Italy and Guimarães, Portugal shapes competitive dynamics across woolen textile formats, with vertical integration determining access to premium channels.
- Wool Fabric:Woven and knitted constructions ranging from 150 to 600 grams per square meter serve suiting, coating, and technical apparel specifications. Italian mills in the Biella cluster supply direct-to-brand programs for Paris and Milan fashion houses, compressing lead times for custom production runs.
- Yarn:Worsted and woolen-spun varieties differ by fiber alignment and twist density, with counts from Nm 10 to Nm 80 covering hand-knitting through machine weaving applications. Südwolle Group's vertical spinning infrastructure anchors European technical apparel supply, serving German and Swiss outdoor brands with certified Merino counts.
- Blankets:Heritage-weight woolen blankets and throws occupy a defensible niche in domestic US manufacturing, with American Woolen Company specializing in military-specification and hospitality-grade production.
- Garments:Finished knitwear and woven outerwear command the highest value-added capture in the supply chain, though production concentrates with cut-make-trim contractors in Romania and Bulgaria.
Today's leader: Wool Fabric. Tomorrow's challenger: Yarn.
End User:
Customer-type fragmentation creates distinct specification regimes, with luxury fashion imposing the most stringent fiber traceability requirements.
- Fashion Industry:Paris and Milan fashion houses specify ultra-fine Merino below 19 microns for suiting and knitwear, with direct ranch partnerships in Australia and New Zealand displacing traditional broker intermediaries.
- Home Furnishings:Interior designers in Dubai, Singapore, and London specify wool upholstery for hotel lobbies and co-working lounges, expanding volume beyond traditional residential markets. This segment is expanding most quickly across the analysis window.
- Automotive Interiors:OEM specifications for seat fabrics and headliners emphasize flame resistance and low VOC emissions, with German and Italian Tier 1 suppliers qualifying mills through extended durability testing protocols.
- Outdoor Gear:Alpine and urban commuting brands integrate wool base layers into modular layering systems, with plasma-treated Merino knits displacing synthetic alternatives in mid-weight insulation categories.
Fashion Industry commands absolute margin premiums. Home Furnishings posts the steepest expansion trajectory.
Grade:
Fiber fineness and provenance stratify pricing across three orders of magnitude, with micron diameter functioning as the primary sorting mechanism.
- Merino:Fine wool below 24 microns dominates volume leadership, with ultra-fine grades below 19 microns commanding measurable price premiums for consistency in diameter profiles. Loro Piana anchors supply through direct ranch partnerships.
- Cashmere:Downy undercoat fibers from Capra hircus goats, typically 15 microns or finer, supply luxury accessories and knitwear through Mongolian and Chinese sourcing corridors.
- Alpaca:Huacaya and Suri varieties from Peruvian and Bolivian highlands offer hypoallergenic alternatives to sheep wool, gaining share in luxury accessories.
- Blended:Wool-synthetic and wool-cotton combinations reduce raw material cost exposure while modifying hand-feel and care properties for mass-market apparel.
Merino retains volume dominance. Cashmere maintains price leadership per kilogram.
Application:
Functional end-use determines finishing chemistry and performance certification requirements, with technical specifications diverging sharply from aesthetic applications.
- Apparel:Next-to-skin and outerwear applications drive plasma surface treatment adoption, with German and Swiss athletic brands specifying hydrophilic performance in marathon and cycling collections.
- Upholstery:Commercial hospitality projects in London, Dubai, and Singapore specify wool for durability and natural flame resistance, with REACH-compliant dyeing protocols mandatory for EU-specified installations.
- Insulation:Batts and loose-fill wool compete with synthetic alternatives in residential and commercial building envelopes, with biodegradability certifications satisfying EU Green Deal procurement mandates.
- Carpets:Axminster and tufted wool carpets serve residential and contract installations, though volume faces pressure from nylon and polypropylene alternatives in price-sensitive segments.
Apparel captures the deepest value per square meter. Insulation is gaining share fastest among building material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Britain's mechanized woolen mills birthed modern textile manufacturing during the Industrial Revolution, establishing quality benchmarks that Italian and Australian producers later refined. This historical foundation continues shaping where premium wool processing concentrates today.
Italy
Luxury fashion houses in Milan and Paris source ultra-fine Merino through direct partnerships with Biella-based mills. ECHA's REACH Annex XVII restrictions on perfluorinated compounds force Piedmont finishers to reformulate water-repellent treatments using plant-based alternatives. The Biella textile cluster anchors European supply for custom suiting fabrics, compressing lead times through vertical spinning-to-weaving integration.
Australia
Drought cycles in New South Wales and Victoria drive Merino fiber auction volatility, compressing spinner margins during moisture-deficit seasons. The country's national agricultural regulator oversees wool export certification protocols that align with EU biodegradability mandates. Direct ranch partnerships with Italian and French fashion houses are displacing traditional broker intermediaries for ultra-fine clip-specific lots.
United States
Military and hospitality procurement sustains domestic demand for heritage-weight blankets and coating fabrics. EPA guidelines restrict azo dyes in wool processing, forcing mills to certify water treatment protocols. The American Woolen Company specializes in military-specification production from New England facilities, occupying a defensible niche against import competition.
China
Mass-market apparel brands specify wool-synthetic blends for cost-sensitive outerwear and knitwear applications. The Ministry of Ecology and Environment enforces wastewater discharge standards at textile finishing facilities in coastal provinces. Yangtze River Delta processors supply volume-positioned European and American retailers with standardized yarn counts.
Portugal
Technical apparel brands in Germany and Switzerland source plasma-treated Merino knits from northern Portuguese finishers. Zero Discharge of Hazardous Chemicals certification requirements strain capital reserves at smaller Guimarães mills. The region's dyehouse concentration creates single-point vulnerability for European luxury supply chains during regulatory enforcement periods.
Woolen Textiles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fiber fineness and certification tiers, with ultra-fine Merino specialists commanding measurable price premiums for diameter consistency. The vendor base stratifies into three archetypes: vertically integrated Italian mills with direct ranch partnerships, regional spinners serving technical apparel specifications, and heritage manufacturers defending domestic production niches. Dominant competitive moves include backward integration into fiber procurement and geographic consolidation of finishing capacity to satisfy REACH compliance.
Within the premium-tier segment, Loro Piana and Reda exemplify direct-sourcing archetypes through Australian and New Zealand ranch partnerships. Südwolle Group occupies a position among European technical suppliers, serving German and Swiss outdoor brands with certified Merino yarn counts. American Woolen Company represents heritage domestic manufacturing, specializing in military and hospitality specifications from New England facilities.
| Leading Market Players |
|---|
| The Woolmark Company |
| Südwolle Group |
| American Woolen Company |
| Geetanjali Woolens |
| Milan Fabric Srl |
| Loro Piana |
| Reda |
| Dormeuil |
| Ferney Spinning Mills Limited |
| Others |
Value Network & Pricing Analysis
Paris and Milan fashion houses concentrate procurement of ultra-fine Merino through direct ranch partnerships, anchoring a contract-based long-term offtake model that insulates premium tiers from auction volatility while exposing mid-grade spinners to spot-market pressure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates woolen textiles, with differentiation driven by micron diameter consistency and Woolmark certification status. Price differentiation separates clip-specific ultra-fine Merino below 19 microns from blended grades and mass-market woolen-spun varieties. Cost compression in standard-tier yarn is intensifying because REACH-compliant dyeing investments concentrate finishing capacity among fewer Portuguese and Italian mills. Mass-market apparel brands exhibit highest price sensitivity, while luxury outerwear houses absorb premium fiber costs to maintain European manufacturing claims.
Supply Chain Analysis
Merino fiber supply rests on Australian and New Zealand ranch outputs, with secondary dependencies on Peruvian alpaca and Mongolian cashmere for luxury blends. Raw material inputs include scoured wool top, mordant dyes, and bio-based water-repellent finishes reformulated under REACH Annex XVII. Single-source vulnerability concentrates in northern Italian dyehouses, where generational attrition of mordant specialists threatens capacity. Distribution runs through direct-to-brand programs for luxury tiers and trader intermediaries for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Australian ranch-level carbon farming protocols and EU Green Deal procurement mandates, with cost differentials emerging from soil credit verification against biodegradability certification burdens.
For Market Incumbents: Anchor backward integration into Australian and New Zealand ranch partnerships to secure clip-specific ultra-fine Merino lots, insulating margin pools from auction volatility driven by New South Wales drought cycles. Invest in closed-loop dyeing infrastructure ahead of ZDHC enforcement waves to capture finishing capacity that smaller Portuguese competitors cannot finance. Defend against synthetic microfiber substitution in outdoor segments by accelerating plasma surface treatment adoption.
For New Entrants and Emerging Players: Launch via blockchain-enabled traceability platforms targeting commercial hospitality specification in Dubai, Singapore, and London co-working lounges, where interior designers seek documented provenance for wool upholstery. Penetrate the insulation segment fastest among building material applications, where EU Green Deal biodegradability mandates create procurement pull with lower certification barriers than luxury apparel channels. Pursue direct ranch partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Luxury fashion conglomerates are the most active acquirer in this space, consolidating Biella-based mills with established Woolmark certification and direct fiber relationships. Long-term viability over the coming decade hinges on carbon farming protocol adoption and traceability technology integration. Watch Australian soil carbon credit verification rates as the inflection signal for premium fiber premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ranch Partnerships | Direct clip access secures micron consistency for ultra-fine Merino supply to Milan and Paris houses. |
| Closed-Loop Dyeing Infrastructure Investment | REACH and ZDHC compliance concentrates finishing capacity among pre-invested Italian and Portuguese mills. |
| Blockchain Traceability Platform Launch | Farm-to-fabric verification unifies with Woolmark certification for dual-layer provenance in luxury channels. |
| Plasma Surface Treatment Scale-Up | German and Swiss athletic brands adopt hydrophilic Merino knits for marathon and cycling collections. |
| Carbon Farming Protocol Adoption | Australian and New Zealand ranchers access soil credits offsetting premium fiber costs for climate-conscious brands. |
Research Methodology
Direct dialogue with spinning mill technical directors, luxury fashion house procurement leads, Italian dyehouse operators, and Australian wool broker executives grounded qualitative findings. Secondary validation drew from AWEX auction data, ECHA REACH substance restrictions, Woolmark certification records, and EU Green Deal procurement guidelines. Bottom-up fiber volume modeling triangulated against top-down end-use demand estimates across apparel, upholstery, and insulation applications.
Segment-level outputs across the projection horizon reflect disaggregated modeling by product type, end-user vertical, fiber grade, and application function. CAGRs were derived from fiber auction price trajectories, capacity utilization at Biella and Guimarães mills, and specification pull from outdoor gear and commercial hospitality channels. Forecast inputs incorporated drought cycle frequency in Australian wool-growing regions and generational transition rates among European mordant dyers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended moisture-deficit seasons in New South Wales or accelerated ZDHC enforcement shuttering smaller Portuguese finishers. Forecasts reflect documented assumptions regarding fiber substitution elasticities and regulatory compliance timelines. A small set of named triggers warrants ongoing watch: Australian soil carbon credit pricing, REACH Annex XVII expansion to additional chemical classes, and synthetic microfiber recycling cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Green Fibers Market
Natural Fibers
Down and Feather Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Fenugreek Fiber Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Jute Market
Natural Fibers
North America Cotton Market
Natural Fibers
Wood-Based Fibers Market
Natural Fibers
Lignocellulosic Fibers Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
North America Textile Market