
 Jute Market | 2026-2036
Jute Market Size, Share, and Industry Trends Forecast 2026-2036
Jute Market Insights
Food and beverage packaging is broadening the end-use vertical mix for jute as brands phase out synthetic alternatives. Gloster Limited leverages its integrated manufacturing footprint across West Bengal to sustain cost leadership in jute yarn. Howrah Mills Co. Ltd. anchors premium-grade supply through specialized retting infrastructure near the Hooghly basin. Cheviot Company Limited differentiates via diversified textile exports that compete across European and Middle Eastern channels.
Jute comprises lignocellulosic bast fibers extracted from Corchorus species, with cellulose content ranging from 58% to 63% and staple lengths of 150–300 cm, processed through retting, stripping, and spinning for packaging, textile, and geotextile applications. Raw jute commands the largest volume share as upstream feedstock for downstream yarn and bag production, though jute bags represent the fastest-expanding margin pool as branded retail packaging gains traction. Grade A material concentrates among export-oriented spinners serving EU and Japanese buyers, while Grade B and C volumes flow predominantly into domestic construction and agricultural netting.
BIS grading protocols and the Indian government's mandatory jute packaging norms for food grains shape domestic demand structure and quality thresholds. Bangladesh's Jute Policy framework and export facilitation mechanisms govern cross-border trade flows and processing investment incentives. Stakeholders must monitor evolving EU Green Deal textile sustainability criteria and shifting South Asian government procurement mandates to align capacity planning with regulatory-driven demand inflections.
Market Dynamics
EU Green Deal textile sustainability criteria are compressing synthetic packaging demand while concentrating jute sourcing authority in certified Bangladeshi and Indian processing clusters.
Growth Catalysts
- EU Green Deal packaging mandates:European food retailers face binding sustainability disclosure requirements that elevate biodegradable fiber specifications above polypropylene alternatives.
- Bangladesh Jute Policy export facilitation:Dhaka-based processing zones receive duty drawback incentives that compress landed costs for EU-bound containerized shipments.
- Retting mechanization:Automated ribbon retting systems reduce fiber degradation rates and enable Grade A output consistency for Japanese technical textile buyers.
Market Restraints
- Monsoon-dependent raw fiber supply:Bangladeshi and Indian crop cycles concentrate annual volume availability within narrow harvest windows, amplifying price volatility.
- Polypropylene woven bag substitution:Synthetic alternatives command 40-60% lower unit costs in bulk agricultural grain storage applications.
- BIS certification timeline friction:Indian Bureau of Standards laboratory testing queues extend batch approval cycles by 8-12 weeks for export-oriented spinners.
Strategic Opportunities
- German automotive interior panels:BMW and Mercedes-Benz supplier programs specify natural fiber composites for door trim substrates, opening technical-grade jute demand outside traditional packaging.
- Carbon-negative construction geotextiles:Soil stabilization applications in Dutch and Belgian infrastructure projects valorize jute's biodegradation profile over synthetic geogrids.
- Indian PLI scheme extension:Production-linked incentives for technical textiles could subsidize capital equipment for value-added yarn and composite manufacturing.
Industry Challenges
- Skilled retting workforce attrition:Traditional water-retting expertise concentrates among aging labor pools in West Bengal's Hooghly basin, constraining quality fiber output scaling.
- Legacy spinning equipment integration:Semi-automatic looms in Bangladesh's Khulna zone require retrofitting to meet EU REACH chemical compliance for finished bag exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jute Market |
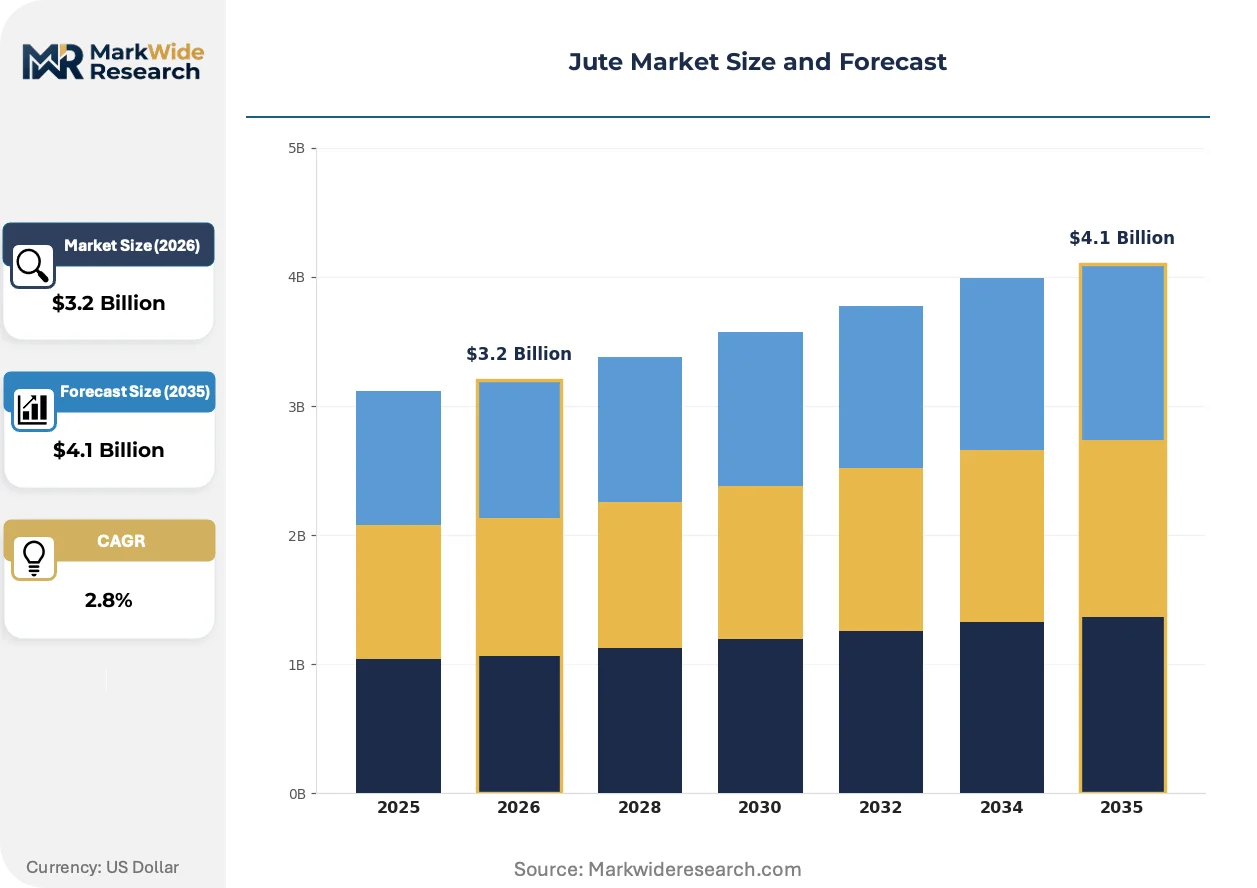
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $4.1 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Jute, Jute Yarn, Jute Bags, Jute Carpets End Use Industry: Textile, Packaging, Construction, Agriculture Grade: Grade A, Grade B, Grade C, Grade D Distribution Channel: Direct Sales, Online Retail, Wholesale, Exports |
| Companies Covered | Premchand Jute & Industries Pvt. Ltd., Budge Budge Company Limited, Gloster Limited, Howrah Mills Co. Ltd., Aarbur, Cheviot Company Limited, Bangalore Fort Farms Ltd., AI Champdany Industries Ltd., Ludlow Jute & Specialities Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jute Market Trends and Innovations
Mechanized fiber processing and blockchain traceability systems are compressing quality variance while enabling premium-grade segmentation for sustainability-certified buyers.
Decentralized ribbon retting units are displacing centralized water-retting ponds across Bangladesh's northern districts. Smallholder cooperatives adopt solar-powered mechanical strippers that reduce fiber degradation from 15% to 4%. This diffusion pattern is decentralizing quality control authority from Dhaka-based exporters toward farm-gate collection points.
REACH chemical compliance documentation now mandates full supply chain substance disclosure for EU-bound jute bags. ECHA enforcement actions against non-compliant South Asian exporters have triggered third-party laboratory certification investments. German and Dutch food retailers now require batch-level traceability that extends from retting pond to finished bag stitching.
Direct mill-to-brand procurement contracts are compressing traditional trader intermediation in European coffee and cocoa packaging. Specialty roasters in Hamburg and Amsterdam negotiate annual volume agreements with Bangladeshi spinners, bypassing Rotterdam commodity brokers. This channel restructuring concentrates margin capture among integrated manufacturers with in-house retting and spinning capabilities.
Jute Market Segmentation
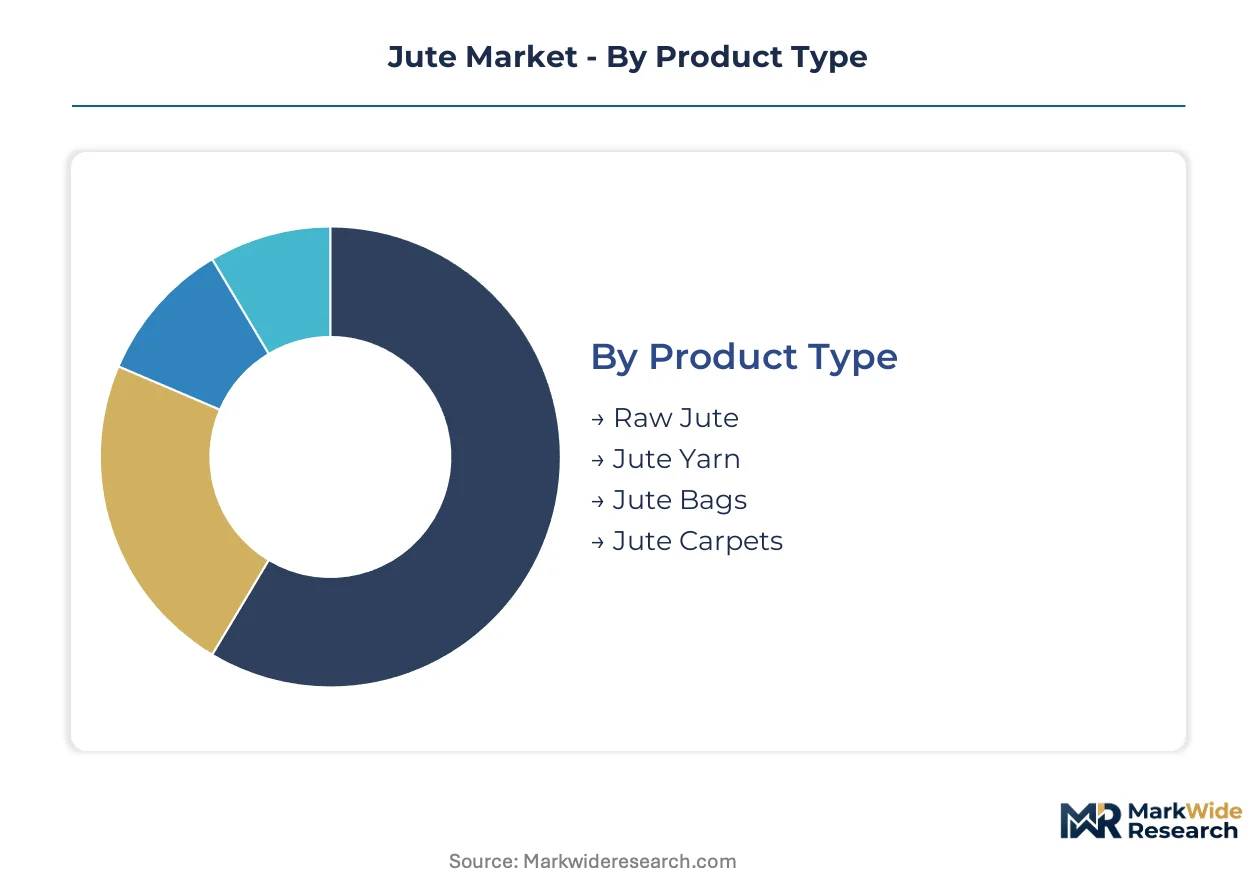
Jute's lignocellulosic fiber characteristics create distinct value pools across processing stages and quality grades. Segmentation reveals how supply chain positioning determines margin capture and regulatory exposure for producers.
Product Type:
Processing depth determines upgrade economics, with raw fiber commanding commodity returns while finished goods capture sustainability premiums from branded buyers.
- Raw Jute:Bast fibers extracted from Corchorus species with 58-63% cellulose content and 150-300 cm staple lengths serve as upstream feedstock. Bangladesh's northern districts and India's West Bengal concentrate harvest volumes, though monsoon-dependent supply creates 8-12 week price volatility windows.
- Jute Yarn:Spun fiber processed through retting, stripping, and spinning operations enables downstream textile and packaging applications. Dhaka and Khulna export processing zones anchor Grade A yarn production for EU and Japanese technical textile buyers seeking REACH-compliant supply chains.
- Jute Bags:Woven and stitched finished goods target food and beverage packaging substitution for synthetic alternatives. Hamburg and Amsterdam specialty roasters negotiate direct mill-to-brand procurement contracts, bypassing traditional trader intermediation.
- Jute Carpets:Tufted and woven floor coverings serve residential and commercial interior applications. Middle Eastern channels absorb premium-grade volumes with specialized dyeing requirements.
Raw Jute sits at the top of the volume ranking, with Jute Bags climbing the fastest.
End Use Industry:
Application diversity spreads demand risk across cyclical and defensive sectors, with construction and agriculture providing baseline offtake during packaging demand fluctuations.
- Textile:Apparel, home furnishings, and technical fabric applications consume Grade A and B fiber. BMW and Mercedes-Benz supplier programs specify natural fiber composites for automotive interior door trim substrates, opening technical-grade demand outside traditional packaging.
- Packaging:Food grain sacks, coffee and cocoa bags, and retail carry bags drive biodegradable fiber substitution. EU Green Deal packaging mandates elevate specifications above polypropylene alternatives for European food retailers facing binding sustainability disclosure requirements.
- Construction:Geotextiles for soil stabilization and erosion control valorize jute's biodegradation profile. Dutch and Belgian infrastructure projects specify carbon-negative construction geotextiles over synthetic geogrids.
- Agriculture:Nursery pots, plant mats, and crop protection netting absorb Grade C and D volumes. Indian government procurement mandates for food grain packaging sustain domestic agricultural sack demand.
Packaging commands the largest value share, with Textile applications expanding most quickly through automotive and technical fabric diversification.
Grade:
Quality tiering aligns fiber characteristics with end-use performance requirements and regulatory compliance thresholds.
- Grade A:Premium bast fibers with minimal lignin content and uniform coloration meet technical textile specifications. Export-oriented spinners serving EU and Japanese buyers concentrate production in certified Bangladeshi and Indian processing clusters with BIS and laboratory certification investments.
- Grade B:Standard commercial fiber with moderate color variation suits general packaging and construction applications. Domestic Indian construction and agricultural netting markets absorb regional volumes from West Bengal's Hooghly basin.
- Grade C:Coarser fiber with higher lignin retention serves low-specification agricultural and industrial uses. Price-sensitive buyers in bulk grain storage applications balance unit costs against polypropylene woven bag substitution pressure.
- Grade D:Short staple and damaged fiber directed to pulp, composite filler, and non-woven applications. Limited premium capture constrains producer margins at this tier.
Grade A fiber captures the steepest expansion trajectory through sustainability-certified buyer programs, while Grade B maintains volume dominance in domestic South Asian markets.
Distribution Channel:
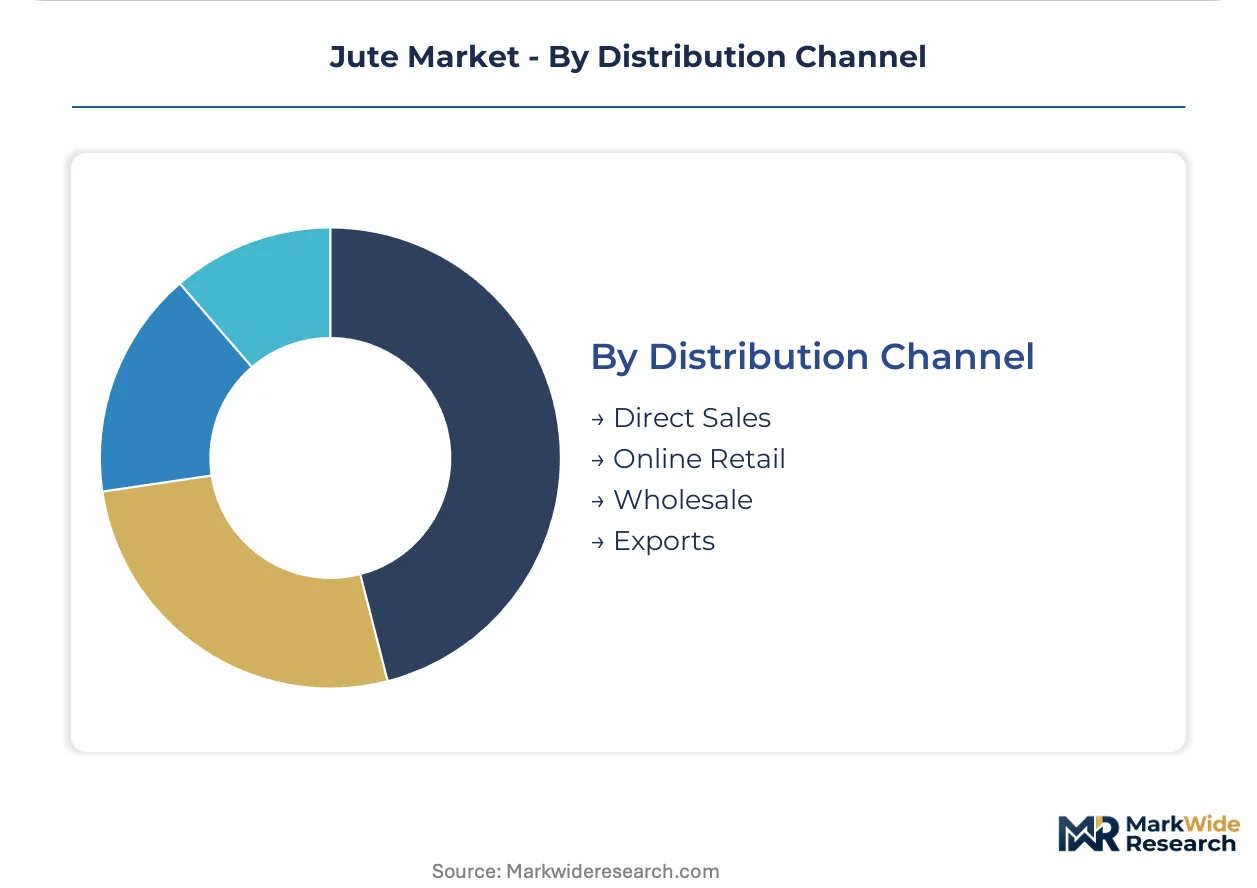
Channel structure determines margin distribution between integrated manufacturers and trader intermediaries, with traceability requirements reshaping procurement patterns.
- Direct Sales:Mill-to-brand contracts eliminate intermediary margins and enable batch-level traceability from retting pond to finished bag stitching. German and Dutch food retailers mandate full supply chain substance disclosure under ECHA enforcement protocols.
- Online Retail:E-commerce platforms serve small-lot specialty buyers and artisan craft segments with customized jute products. Limited penetration in bulk industrial offtake constrains channel scale.
- Wholesale:Traditional trader networks aggregate fragmented smallholder production for standardized grade sorting. Rotterdam commodity brokers face compression as direct procurement contracts displace conventional intermediation.
- Exports:Containerized shipments to EU, Middle Eastern, and Japanese markets require REACH compliance documentation and third-party laboratory certification. Bangladesh's Jute Policy duty drawback incentives compress landed costs for Dhaka-based processing zones.
Wholesale retains volume leadership in smallholder supply aggregation, with Direct Sales gaining share fastest through sustainability-traceable procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as compliance-cost gaps between South Asian origins and European destination markets concentrate processing investment in certified Bangladeshi and Indian clusters. Manufacturers migrate toward zones with pre-approved laboratory infrastructure and streamlined customs protocols.
Bangladesh
EU-bound food packaging demand from German and Dutch retailers drives Dhaka and Khulna export processing zone expansion. The national Jute Policy framework delivers duty drawback incentives that compress landed costs for containerized shipments. Northern district ribbon retting cooperatives adopt solar-powered mechanical strippers, decentralizing quality control from capital-based exporters toward farm-gate collection points.
India
Domestic food grain procurement mandates under government packaging norms sustain baseline agricultural sack volume. BIS certification requirements for jute goods extend laboratory testing queues by 8-12 weeks, creating compliance friction for export-oriented spinners. West Bengal's Hooghly basin retains traditional water-retting expertise, though aging labor pools constrain quality fiber output scaling.
Germany
BMW and Mercedes-Benz supplier programs specify natural fiber composites for automotive interior door trim substrates, opening technical-grade jute demand outside traditional packaging. ECHA enforcement actions against non-compliant South Asian exporters drive third-party laboratory certification investments by sourcing partners. Hamburg specialty coffee roasters negotiate direct mill-to-brand procurement contracts, bypassing Rotterdam commodity broker intermediation.
Netherlands
Dutch infrastructure projects specify carbon-negative construction geotextiles for soil stabilization, valorizing jute's biodegradation profile over synthetic geogrids. Amsterdam-based food retailers mandate batch-level traceability extending from retting pond to finished bag stitching under REACH chemical compliance documentation. The country's national sustainable construction regulator evaluates natural fiber specifications for public works tender eligibility.
Japan
Technical textile buyers source Grade A yarn with minimal lignin content and uniform coloration for high-performance fabric applications. METI standards alignment requires consistent fiber output from automated ribbon retting systems. Japanese trading houses concentrate procurement authority through long-term supply agreements with certified Bangladeshi processing clusters.
Jute Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated manufacturers retrofit legacy equipment to meet EU REACH chemical compliance for finished bag exports. The vendor base organizes around three strategic archetypes: diversified conglomerates with captive fiber supply, specialized spinning houses serving technical textile channels, and regional packaging converters. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding automotive composite and geotextile lines to offset agricultural sack commoditization.
Among India-based integrated producers, Gloster Limited and Howrah Mills Co. Ltd. occupy positions within the premium-grade supply tier, while Cheviot Company Limited exemplifies the diversified textile export archetype competing across European and Middle Eastern channels. These entities represent contrasting strategic postures: West Bengal-anchored manufacturing footprints versus multi-market revenue diversification. The competitive terrain rewards backward integration into retting infrastructure and in-house spinning capability as direct procurement contracts displace traditional trader intermediation.
| Leading Market Players |
|---|
| Premchand Jute & Industries Pvt. Ltd. |
| Budge Budge Company Limited |
| Gloster Limited |
| Howrah Mills Co. Ltd. |
| Aarbur |
| Cheviot Company Limited |
| Bangalore Fort Farms Ltd. |
| AI Champdany Industries Ltd. |
| Ludlow Jute & Specialities Ltd. |
| Others |
Pricing and Supply Chain Analysis
Grade A-to-C fiber bifurcation separates REACH-certified export yarn from domestic agricultural sack feedstock, compressing margin capture toward integrated Dhaka-based spinners while fragmenting pricing power among Hooghly basin commodity traders. This tier divergence concentrates supply chain authority in mechanized retting clusters and disperses it across monsoon-dependent smallholder networks.
Pricing Analysis
Distributor margins on Rotterdam-channeled commodity jute run 12-18% above direct mill-to-brand contracts for EU food retailers. Three-tier pricing structure across premium, standard, and economy levels aligns with BIS certification tiers and batch-level traceability investments. Pricing pressure stems from polypropylene substitution in Indian government grain procurement, where synthetic alternatives undercut jute sacks on unit economics. Agricultural buyers exhibit highest price sensitivity, while German automotive OEMs accept technical-grade premiums for natural fiber composite specifications.
Supply Chain Analysis
Direct-to-OEM channels handle BMW and Mercedes-Benz technical fiber demand, while wholesale networks aggregate fragmented Bangladeshi smallholder production. Raw jute supply concentrates in Bangladesh's northern districts and India's West Bengal, with retting infrastructure dependencies on seasonal water availability and solar-powered mechanical stripper diffusion. The chain draws from Corchorus olitorius and Corchorus capsularis cultivars, with chemical compliance documentation and ECHA enforcement actions creating regulatory chokepoints. Distribution runs through Dhaka and Khulna export processing zones for EU-bound containerized shipments, bypassing traditional trader intermediation where batch traceability is mandated.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in technical-grade fiber substitution for automotive composites and carbon-negative geotextiles, as mechanized retting compresses quality variance and EU sustainability disclosure requirements elevate certified yarn premiums.
For Market Incumbents: Deepen backward integration into northern Bangladesh ribbon retting cooperatives to secure Grade A fiber consistency against polypropylene substitution pressure in bulk grain applications. Invest in automated fiber processing equipment to meet ECHA chemical compliance timelines and capture direct procurement contracts from Hamburg and Amsterdam specialty roasters. Channel control through in-house spinning capability defends margin position against trader margin compression. For New Entrants and Emerging Players: Begin with carbon-negative construction geotextiles for Dutch and Belgian infrastructure projects, where biodegradation specifications create penetrable demand outside established packaging incumbents. Target technical textile applications for Japanese buyers seeking METI-aligned Grade A yarn with minimal lignin content. A farm-gate collection point go-to-market model leverages decentralized solar-powered stripping adoption in Bangladesh's northern districts. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS certification queues and REACH compliance investments fragment export-oriented spinning capacity among sub-scale West Bengal operators. Long-term viability favors integrated manufacturers with captive retting infrastructure and in-house yarn production serving sustainability-certified buyer programs. Watch for Indian PLI scheme technical textile extensions as inflection signal for value-added composite manufacturing subsidies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Retting Infrastructure | Captive fiber supply secures Grade A consistency for EU REACH-compliant yarn exports. |
| Mechanized Ribbon Retting Adoption | Solar-powered strippers reduce fiber degradation from 15% to 4% for Japanese technical textile buyers. |
| Direct Mill-to-Brand Procurement Contracts | Bypassing Rotterdam commodity brokers concentrates margin capture among integrated Dhaka spinners. |
| REACH Chemical Compliance Certification | ECHA enforcement actions mandate third-party laboratory investments for EU-bound bag exports. |
| Technical Textile Diversification | BMW and Mercedes-Benz automotive interior programs open premium-grade demand outside packaging commoditization. |
Research Methodology
Multiple input streams — primary interviews with jute mill operations directors, export processing zone managers, and EU food retailer procurement leads; secondary validation through Bangladesh Jute Policy documentation, Indian BIS certification records, and ECHA REACH enforcement databases; plus customs trade data from Dhaka and Khulna container terminals — were reconciled through bottom-up fiber volume aggregation and top-down end-use demand estimation.
Historical export volume trajectories from Bangladesh's Export Promotion Bureau were cross-referenced against panel input from Japanese trading houses and German automotive Tier 1 suppliers to construct the analytical framework across the analysis window. Segmentation dimensions modeled include processing depth (raw fiber, yarn, finished goods), quality grade tier, end-use industry vertical, and distribution channel structure. CAGRs were derived from regression analysis of monsoon-adjusted harvest volumes and sustainability-certified buyer program expansion rates.
Several conditions sit outside the modeled scope, including extreme weather disruption to Ganges-Brahmaputra delta crop cycles, abrupt shifts in Indian government food grain packaging mandates, and synthetic fiber price volatility from petrochemical feedstock fluctuations. Forecasts reflect assumptions regarding EU Green Deal implementation timelines and Bangladesh Jute Policy duty drawback continuity. Periodic stress-testing of base assumptions is recommended against evolving ECHA enforcement patterns and South Asian labor pool demographics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Jute Bags Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Silk Market
Natural Fibers
North America Textile Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Global Cotton Market
Natural Fibers
Cellulose Market
Natural Fibers
Green Fibers Market
Natural Fibers
Acoustic Cotton Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Modal Fiber Market
Natural Fibers
Silk Fabric Market
Natural Fibers
Silk Mask Market
Natural Fibers
Organic Cotton Market