
 Wood-Based Fibers Market | 2026-2036
Wood-Based Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Wood-Based Fibers Market Analytics
The EU Deforestation Regulation is consolidating supply-chain compliance costs around wood-origin documentation and geolocation data. Lenzing leverages its CanopyStyle green-shirt status to secure preferential access to certified dissolving pulp. Sappi anchors its competitiveness through backward integration into South African and North American pulp assets. Aditya Birla Group dominates Indian viscose staple fiber output with captive chemical plants and plantation partnerships.
Wood-based fibers comprise cellulose strands extracted from lignocellulosic biomass through mechanical, chemical, or thermo-mechanical processing, typically yielding 92-98% alpha-cellulose content for textile-grade dissolving pulp. These fibers serve as renewable feedstocks for textiles, nonwovens, and engineered materials seeking alternatives to synthetic polymers. Engineered wood applications sustain the deepest margin pools where moisture-resistant binders and structural grades command specification premiums from architects. Chemical processing technology leads volume throughput for textile pulp, while bioprocessing represents the fastest-expanding frontier as enzymatic delignification cuts energy intensity and effluent loads. Mechanical processing occupies mature cost positions in packaging and newsprint-adjacent fiberboard markets.
REACH chemical registration in Europe, the EU Green Deal's sustainable product framework, and China's GB standards for formaldehyde emissions in fiberboard collectively reshape product standards and market access thresholds. EPA effluent guidelines in the United States further constrain kraft pulping operations, favoring capital-rich operators with tertiary treatment infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions where carbon-border adjustments and deforestation traceability mandates could fragment sourcing strategies and reward early certification investments.
Market Dynamics
The EU Deforestation Regulation is compressing supply-chain timelines for wood-origin documentation, forcing textile brands to pre-certify dissolving pulp sources before procurement contracts execute.
Growth Catalysts
- EU Green Deal sustainable product framework:Mandatory recycled-content thresholds in apparel are pulling viscose and lyocell into fast-fashion supply chains ahead of synthetic phase-outs.
- Indonesia:Integrated pulp-to-fiber complexes are scaling lyocell output to capture regional textile demand as Chinese viscose faces carbon-border exposure.
- Enzymatic delignification:Bioprocessing advances are cutting kraft pulping energy intensity by half, opening capacity expansion in markets with strict EPA effluent guidelines.
Market Restraints
- Dissolving pulp supply concentration:Brazilian and Indonesian plantation-controlled pulp flows create single-source vulnerability for European spinners.
- Formaldehyde emission standards:China's GB standards for fiberboard are disqualifying conventional adhesive chemistries, forcing reformulation costs on mid-scale producers.
- Recycled PET price compression:Post-consumer polyester flake undercuts viscose staple fiber in non-apparel nonwovens, capping volume growth in wipes and hygiene.
Strategic Opportunities
- Brazil:Eucalyptus plantation expansion around integrated fiber complexes offers captive pulp supply for lyocell investment at sub-Asian carbon intensity.
- Automotive interiors:OEM sustainability scorecards are opening specification slots for wood-based nonwovens in door panels and headliners previously locked in petrochemical textiles.
- REACH chemical registration alignment:Early compliance with ECHA substance dossiers is creating preferential access to EU textile brands ahead of 2025 supply-chain audits.
Industry Challenges
- Dissolving pulp certification timelines:CanopyStyle green-shirt audits require 18-24 month farm-to-fiber traceability builds, delaying contract execution for new entrants.
- Lyocell solvent recovery capex:N-methylmorpholine-N-oxide closed-loop systems demand capital deployment at triple viscose plant levels, constraining independent mill participation.
- Legacy kraft mill retrofit complexity:Converting paper-grade pulp lines to textile-grade alpha-cellulose output requires bleaching sequence overhauls that conflict with existing effluent permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood-Based Fibers Market |
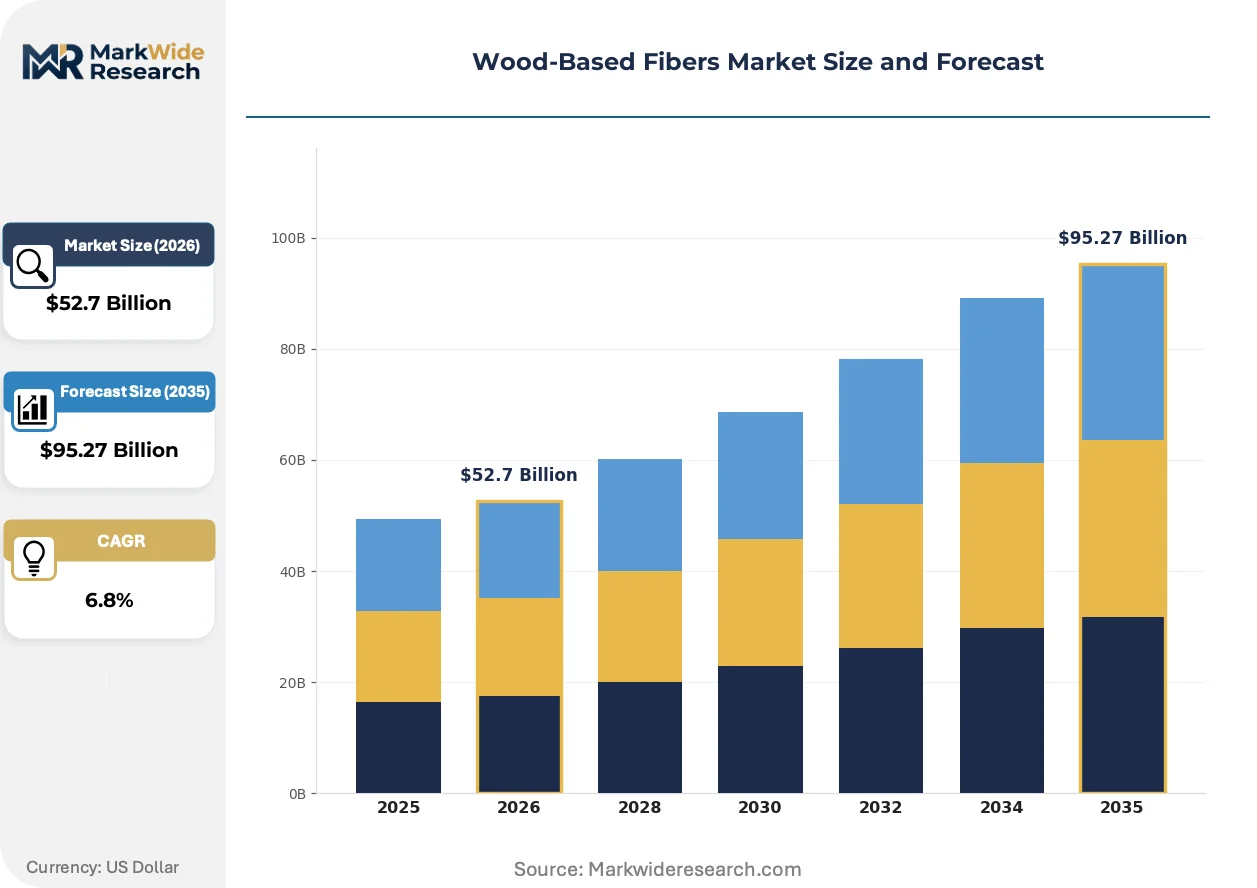
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pulp, Fiberboard, Medium Density Fiberboard, Engineered Wood Application: Construction, Furniture, Packaging, Automotive Interiors End User: Manufacturers, Contractors, Retailers, Wholesalers Technology: Mechanical Processing, Chemical Processing, Thermo-mechanical Processing, Bioprocessing |
| Companies Covered | Lenzing, Sappi, Aditya Birla Group, Bracell, Rayonier Advanced Materials, Aoyang Technology, Asahi Kasei Corporation, International Paper, Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood-Based Fibers Market Evolving Landscape
Wood-based fiber processing is splitting into two technological tracks: closed-loop lyocell systems for premium apparel and mechanically refined lignocellulosic feedstocks for construction composites.
Enzymatic pre-treatment of hardwood chips is rewriting energy economics for dissolving pulp production. Finnish and Swedish mills are retrofitting kraft lines with cellulase-based delignification stages. The structural consequence is a compression of the cost gap between lyocell and conventional viscose, pulling mid-market textile brands toward certified fiber options.
REACH authorization requirements for carbon disulfide are tightening viscose production standards across European member states. The industrial consequence is a migration of staple fiber capacity toward plants with tertiary solvent recovery infrastructure. Italian and Portuguese textile clusters are most affected, with spinners accelerating lyocell blend ratios to preempt supply disruption.
Brand-led fiber preference is rotating procurement specifications toward closed-loop certified inputs. Fast-fashion retailers are inserting CanopyStyle audit requirements into spinning mill contracts, displacing uncertified viscose from tier-one supply tiers. This pattern is most visible in Nordic and German apparel markets where consumer-facing sustainability scoring drives material selection.
Wood-Based Fibers Market Segmentation
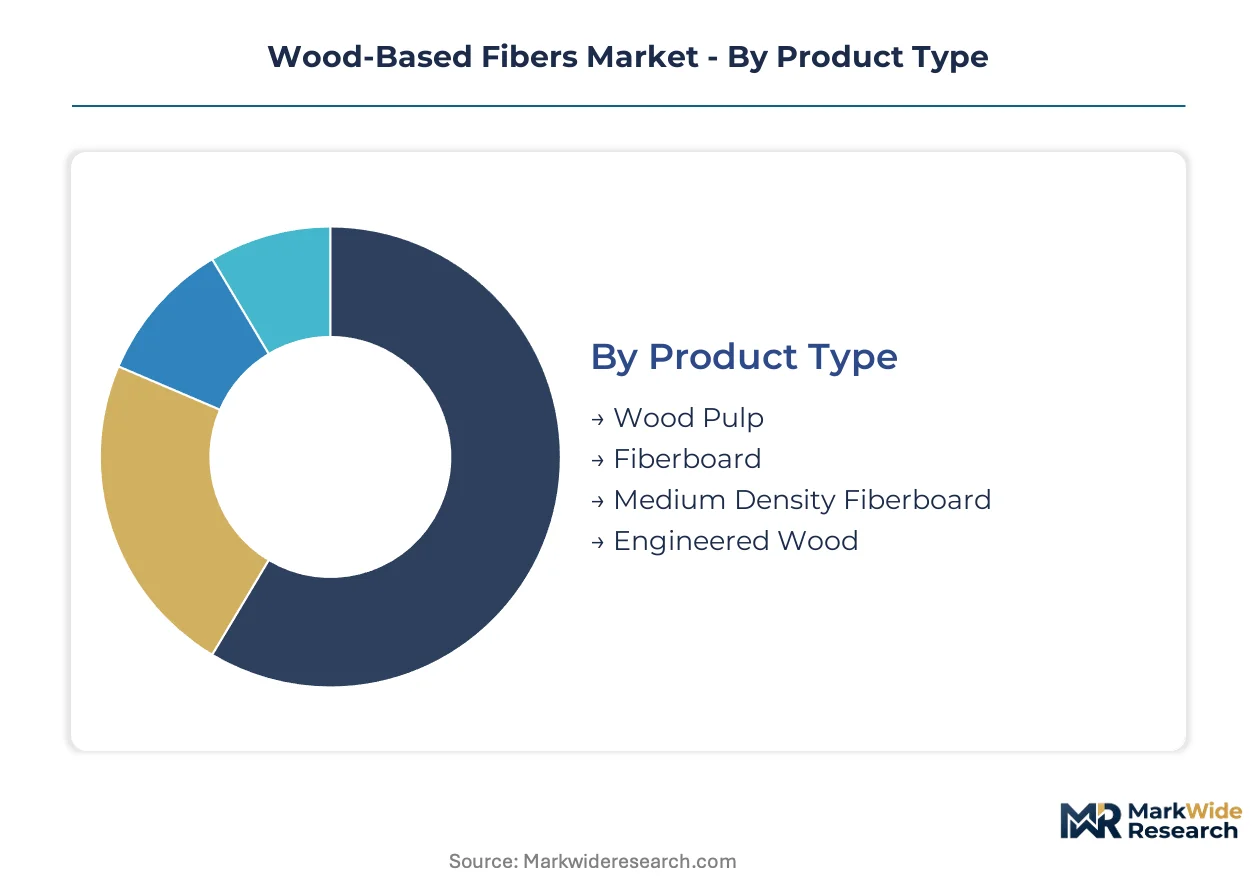
Wood-based fiber markets fragment across processing intensity and end-use durability requirements. Manufacturers configure capacity around either commodity pulp flows or specification-driven engineered products. Segment selection determines exposure to construction cycles, automotive specification windows, and regulatory compliance costs.
Product Type:
Material density and structural performance separate commodity grades from engineered alternatives.
- Wood Pulp:Alpha-cellulose dissolving pulp serves textile-grade viscose and lyocell production. Indonesian and Brazilian integrated complexes are scaling output to capture fast-fashion substitution away from petrochemical fibers.
- Engineered Wood:Cross-laminated timber and laminated veneer lumber deliver structural load-bearing capacity with moisture-resistant binders. Architects in Nordic markets specify these materials for carbon-negative construction credits.
- Fiberboard:Standard-density panels absorb lower mechanical stress in furniture substrates and interior cladding. China's GB formaldehyde emission standards are disqualifying conventional adhesive formulations.
- Medium Density Fiberboard:Uniform fiber distribution enables precision machining for cabinet doors and millwork. Retail furniture manufacturers favor this grade for surface finish consistency.
Wood pulp leads on scale; engineered wood leads on momentum.
Application:
End-use durability requirements pull fiber specifications toward either structural or aesthetic performance tiers.
- Construction:Mass timber and structural panels demand moisture resistance and code-compliant fire ratings. German and Austrian building codes now permit engineered wood for mid-rise residential frames.
- Automotive Interiors:Nonwoven fiber mats for door panels and headliners require low-VOC emissions and compression molding compatibility. OEM sustainability scorecards are opening specification slots previously locked in petrochemical textiles.
- Furniture:Medium-density fiberboard dominates case goods and ready-to-assemble products. Flat-pack retailers specify this grade for weight efficiency in logistics.
- Packaging:Corrugated medium and molded pulp compete with recycled PET for protective applications. E-commerce fulfillment centers drive volume for lightweight cushioning grades.
Construction commands the largest volume commitment; automotive interiors are climbing the fastest.
End User:
Procurement scale and technical specification authority concentrate differently across the value chain.
- Manufacturers:Vertically integrated pulp-to-fiber operators control formulation and certification. Lenzing and Sappi anchor procurement through captive dissolving pulp supply.
- Contractors:Construction firms specify engineered wood for structural applications with architect approval. Nordic contractors lead mass timber adoption for commercial projects.
- Retailers:Fast-fashion brands insert CanopyStyle audit requirements into spinning mill contracts. H&M and Zara parent companies drive certified viscose penetration.
- Wholesalers:Distributors aggregate fragmented demand from smaller furniture and packaging converters. Inventory carrying costs favor standardized fiberboard grades.
Manufacturers lead on scale; retailers lead on momentum.
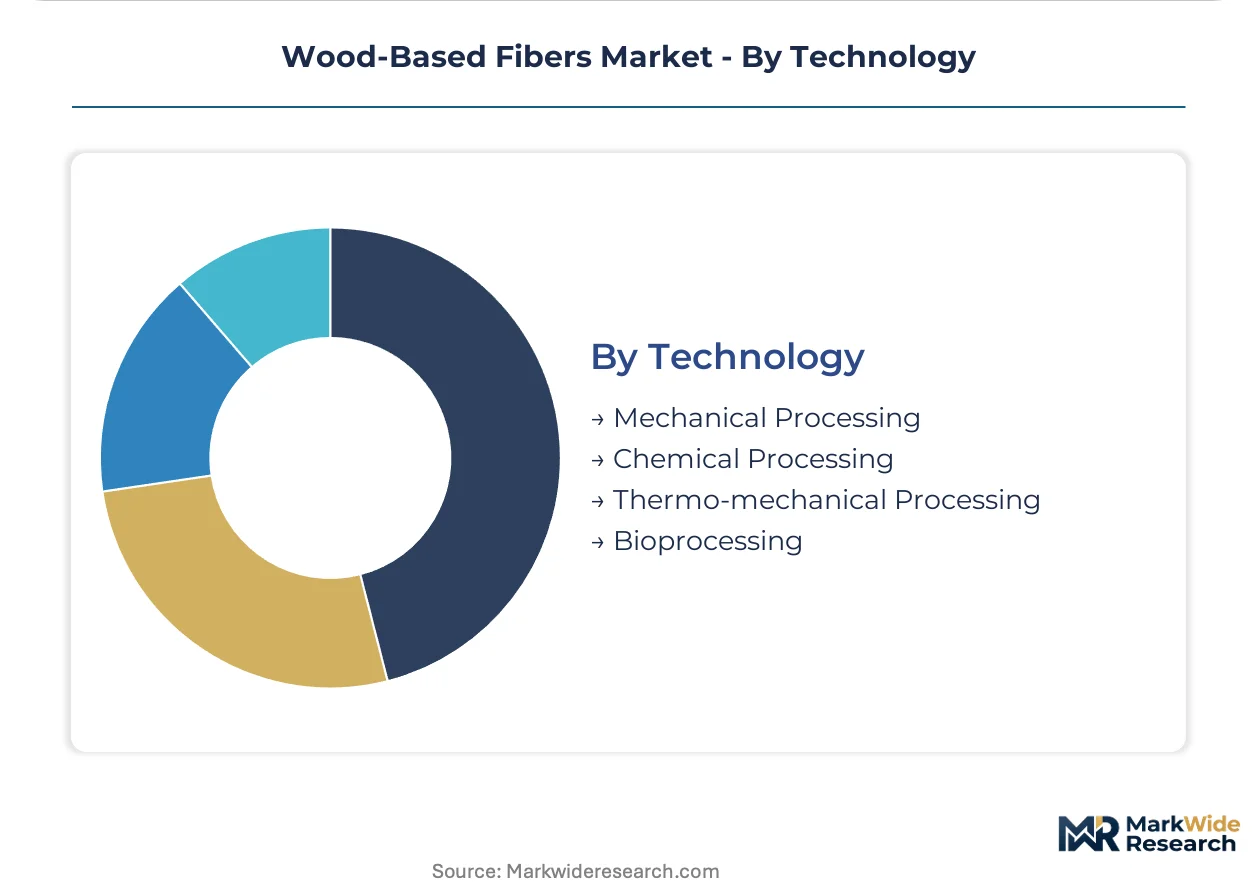
Technology:
Energy intensity and effluent load separate mature chemical processes from emerging bioprocessing platforms.
- Chemical Processing:Kraft and sulfite pulping extract alpha-cellulose through alkaline cooking and multi-stage bleaching. EPA effluent guidelines in the United States favor capital-rich operators with tertiary treatment infrastructure.
- Bioprocessing:Enzymatic delignification with cellulase pre-treatment cuts energy intensity by half. Finnish and Swedish mills are retrofitting kraft lines with these stages to meet strict Nordic environmental permits.
- Mechanical Processing:Stone grinding and refiner mechanical pulping preserve lignin for lower-grade packaging applications. Newsprint-adjacent fiberboard markets occupy mature cost positions.
- Thermo-mechanical Processing:Steam-softened chips refined under pressure yield high-yield pulp for corrugating medium. Energy costs constrain expansion in markets with carbon-border exposure.
Chemical processing leads on scale; bioprocessing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and pulp technicians concentrate in Nordic and Southeast Asian industrial corridors, anchoring capacity expansion for textile-grade dissolving pulp.
Indonesia
Integrated pulp-to-fiber complexes in Sumatra and Kalimantan are scaling lyocell output to capture regional textile demand. The national industrial ministry accelerates downstream chemical plant licensing to reduce import dependence. Riau Province hosts the densest concentration of dissolving pulp capacity, with plantation-controlled supply chains feeding captive fiber production.
Brazil
Eucalyptus plantation expansion around São Paulo state offers captive pulp supply at sub-Asian carbon intensity. IBAMA environmental licensing now mandates geolocation tracking for all plantation fiber entering European supply chains. The Triângulo Mineiro region anchors integrated fiber complex development, linking pulp mills directly to lyocell investment.
China
GB standards for formaldehyde emissions in fiberboard are disqualifying conventional adhesive chemistries, forcing reformulation costs on mid-scale producers. The Ministry of Ecology and Environment tightens effluent discharge permits for kraft pulping operations. Jiangsu Province textile clusters pivot toward lyocell blend ratios to preempt REACH-aligned supply disruption from European buyers.
Germany
Automotive OEM sustainability scorecards open specification slots for wood-based nonwovens in door panels previously locked in petrochemical textiles. ECHA REACH authorization requirements for carbon disulfide tighten viscose production standards. The Saxony-Anhalt chemical corridor hosts specialized solvent recovery infrastructure serving Central European spinning mills.
United States
EPA effluent guidelines constrain kraft pulping operations, favoring capital-rich operators with tertiary treatment infrastructure. The Inflation Reduction Act bioenergy credits pull investment toward enzymatic delignification retrofits. The Pacific Northwest pulp corridor anchors dissolving pulp supply for domestic textile nonwovens, leveraging coastal logistics for Asian export.
Wood-Based Fibers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Integrated pulp-to-fiber operators control captive dissolving pulp supply and certification pipelines. Chemical technology licensors extract rents from solvent recovery system deployments. Regional plantation-backed producers leverage feedstock proximity to undercut transport-heavy competitors. Capacity expansion and backward integration into pulp assets represent the dominant competitive moves.
Among Austrian and South African anchored operators, Lenzing and Sappi exemplify the integrated archetype through captive dissolving pulp supply. Aditya Birla Group occupies a position representing plantation-backed regional scale. These three names anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Lenzing |
| Sappi |
| Aditya Birla Group |
| Bracell |
| Rayonier Advanced Materials |
| Aoyang Technology |
| Asahi Kasei Corporation |
| International Paper |
| Stora Enso Oyj |
| Others |
Value Network & Pricing Analysis
Plantation-controlled integrated producers anchor supply-side discipline through captive eucalyptus feedstock, converting fiber scarcity into pricing power for certified dissolving pulp while squeezing independent spinners dependent on spot-market sourcing. The EU Deforestation Regulation tightens this dynamic by forcing brands to absorb traceability premiums or forfeit European market access.
Pricing Analysis
Contract-based long-term offtage dominates certified dissolving pulp transactions, separating bundled CanopyStyle-audited supply from unbundled spot-market fiber. Price differentiation centers on certification grade and volume scale, with green-shirt status commanding substantial premiums over conventional viscose-grade pulp. Cost compression in standard viscose staple fiber is intensifying because recycled PET flake undercuts wood-based alternatives in nonwoven applications. Small-scale Indonesian and Indian spinners exhibit the highest price sensitivity, while integrated European lyocell producers demonstrate the least due to captive pulp supply and brand-locked contracts.
Supply Chain Analysis
Dissolving pulp supply rests on Brazilian, Indonesian, and South African plantation-controlled flows, with hardwood chips, sulfur chemicals, and N-methylmorpholine-N-oxide solvent forming critical input dependencies. Single-source vulnerability concentrates around Riau Province and São Paulo state complexes, where any environmental licensing suspension would cascade through European spinning mills. Distribution runs through vertically integrated pulp-to-fiber complexes serving captive downstream operations, supplemented by spot-market traders for uncertified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Deforestation Regulation operates as a regulatory compounder, tightening traceability mandates that pull certified fiber demand ahead of supply response and rewarding early compliance investments with preferential brand access.
For Market Incumbents: Extend certification pipelines through accelerated CanopyStyle audit completion to preempt competitor entry, while deepening backward integration into plantation assets in Brazil and Indonesia to secure sub-Asian carbon intensity positioning against emerging lyocell rivals. For New Entrants and Emerging Players: Capture automotive interior nonwoven specifications as OEM sustainability scorecards displace petrochemical textiles from door panel and headliner applications, leveraging low-VOC emissions credentials and direct mill-to-OEM contracting to bypass established textile distribution channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mechanical processing specialists with stranded packaging-grade assets capable of lyocell retrofit, framing long-term viability around enzymatic delignification technology adoption and the inflection signal to monitor is EPA effluent guideline enforcement intensity in the Pacific Northwest pulp corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive eucalyptus supply in Brazil cuts carbon intensity below Indonesian competitors for EU market access. |
| Enzymatic Delignification Retrofit | Finnish and Swedish mills slash kraft pulping energy intensity to meet strict Nordic environmental permits. |
| CanopyStyle Certification Acceleration | Green-shirt status secures preferential contracting with H&M and Zara parent companies ahead of supply-chain audits. |
| Automotive Nonwoven Specification Push | OEM sustainability scorecards open door panel slots previously locked in petrochemical textile supply chains. |
| Lyocell Solvent Recovery Infrastructure | N-methylmorpholine-N-oxide closed-loop systems enable premium fiber production at triple viscose capital efficiency. |
Research Methodology
Bottom-up textile application modeling reconciled against top-down dissolving pulp capacity tracking forms the analytical core, combining primary interviews with spinning mill procurement directors, dissolving pulp plant managers, automotive Tier 1 supplier sustainability officers, and fast-fashion brand material strategists with secondary validation from customs trade data, CanopyStyle audit disclosures, EPA effluent permit filings, and EU Timber Regulation enforcement records.
Historical trendline analysis across dissolving pulp production volumes, lyocell capacity additions, and viscose staple fiber trade flows informs the projection framework, with segmentation dimensions spanning processing technology, certification tier, end-use durability requirements, and regional regulatory clusters. CAGRs derive from capacity-expansion pipelines weighted against substitution elasticity estimates for synthetic fiber displacement, incorporating enzymatic delignification adoption curves and carbon-border adjustment exposure differentials throughout the forecast period.
EU Deforestation Regulation enforcement delays, Indonesian environmental licensing suspensions, and breakthroughs in recycled PET chemical depolymerization are the dominant revision risks, with forecasts reflecting assumptions around plantation expansion rates and solvent recovery technology maturation. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Silk Fabric Market
Natural Fibers
North America Textile Market
Natural Fibers
Hessian Sacks Market
Natural Fibers
Silk Textiles Market
Natural Fibers
Green Fibers Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Down and Feather Market
Natural Fibers
Eco Fibers Market
Natural Fibers
Textile Staples Market
Natural Fibers
Silk Mask Market
Natural Fibers
Woolen Textiles Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Jute Market