
 North America Lyocell Fiber Market | 2026-2036
North America Lyocell Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lyocell Fiber Market Intelligence
Apparel brands seeking biodegradable alternatives are unwinding legacy polyester commitments faster than home textile buyers. Lenzing AG anchors North American supply through its Alabama production complex, while Grasim Industries Limited leverages overseas filament capacity to serve automotive upholstery tiers. Smartfiber AG differentiates through medical-grade lyocell certification, a niche that commands premium positioning in wound-care non-wovens.
North America lyocell fiber denotes regenerated cellulose produced via direct dissolution of wood pulp in N-methylmorpholine N-oxide (NMMO), yielding filaments with tenacity exceeding 4.0 cN/dtex and moisture regain near 13 percent, primarily serving markets that require breathable, biodegradable textiles. Apparel commands the dominant share of value, though industrial non-wovens represent the fastest-expanding margin pool as filtration and wipe manufacturers substitute petroleum-based synthetics. Staple fiber occupies the volume lead across all end-use industries, while filament fiber concentrates in premium fashion and technical textile applications where surface luster and continuous-yarn integrity matter.
The EPA enforces wastewater discharge limits under the Clean Water Act that directly affect NMMO solvent recovery economics, while OSHA standards govern dimethyl sulfoxide exposure in fiber processing facilities, and the FTC's Green Guides constrain how manufacturers label biodegradability claims. State-level extended producer responsibility laws in California and New York are adding compliance layers that favor domestic over imported fiber. Stakeholders must monitor how pending revisions to the FTC textile labeling rules alter competitive positioning between lyocell and competing regenerated fibers.
Market Dynamics
Closed-loop NMMO solvent recovery systems are compressing unit economics for North American lyocell producers, while EPA wastewater discharge limits under the Clean Water Act force capital allocation toward compliance infrastructure rather than capacity expansion.
Growth Catalysts
- California Extended Producer Responsibility Law:Mandates textile waste diversion targets that favor biodegradable regenerated cellulose over synthetic alternatives in apparel supply chains.
- Automotive Upholstery Tiers:Tier-1 seating manufacturers are qualifying lyocell filament for luxury vehicle interiors, creating pull-through demand for high-tenacity fiber grades.
- Southeastern US Mill Clustering:Spun-yarn producers concentrated in Georgia and the Carolinas are shortening logistics loops to Alabama-based pulp dissolution facilities.
Market Restraints
- Dissolving Pulp Supply Concentration:Hardwood pulp suitable for NMMO processing sources from a narrow supplier base in the southeastern United States and Canada.
- Capital Intensity of Solvent Recovery:Closed-loop NMMO purification systems require eight-figure capex commitments that freeze out mid-scale entrants.
- Polyester Price Anchoring:Virgin PET staple fiber from shale-advantaged US petrochemical complexes sets a ceiling on lyocell pricing power in mass-market apparel.
Strategic Opportunities
- Medical-Grade Non-Wovens:Wound-care applications requiring USP Class VI biocompatibility certification command premium positioning underserved by commodity fiber producers.
- New York State Textile EPR Mandate:Pending regulations would extend producer responsibility to home textiles, accelerating substitution of petroleum-based wipes and filtration media.
- Filament-to-Staple Hybrid Processing:Equipment capable of switching between continuous yarn and cut staple outputs enables rapid pivoting between fashion and technical textile demand cycles.
Industry Challenges
- Specialized Process Engineering Talent:NMMO solvent handling and lyocell spinning expertise concentrates among veterans of Lenzing's Alabama operations and a handful of European-trained specialists.
- FTC Green Guides Compliance:Biodegradability labeling claims require substantiation documentation that extends product launch timelines by 6-12 months.
- Legacy Dye House Compatibility:Conventional reactive dye systems optimized for cotton require recalibration for lyocell's higher moisture regain, forcing textile finishers into costly process revalidation.
Report Scope
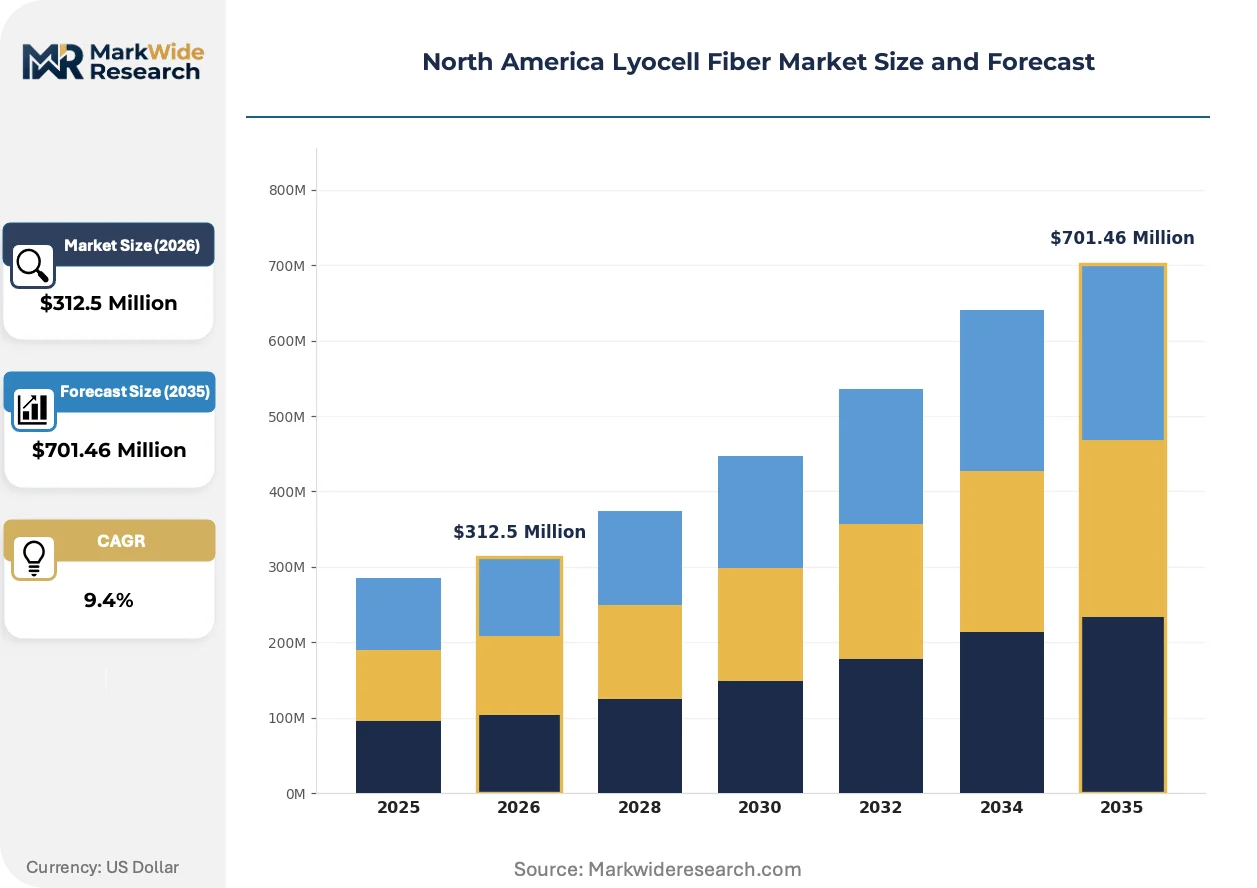
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lyocell Fiber Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Home Textiles, Industrial, Non-wovens End Use Industry: Fashion, Automotive, Healthcare, Upholstery Form: Staple Fiber, Filament Fiber, Blends, Sheets Manufacturing Stage: Raw Material Production, Fiber Processing, Dyeing, Finishing |
| Companies Covered | Smartfiber AG, Baoding Swan Fiber Co., Ltd., Lenzing AG, Weiqiao Textile Company Limited, Acegreen Eco-Material Technology Co., Ltd., Aditya Birla Group, Chonbang Co., Ltd., Aceton Chemicals & Fiber Corporation, Grasim Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lyocell Fiber Market Strategic Shifts & Innovations
Technology and regulatory vectors are splitting the North American lyocell market into premium-certified and commodity-grade tiers, with innovation concentrating in solvent efficiency and end-use-specific fiber engineering.
Closed-loop NMMO recovery technology is bifurcating the competitive landscape between integrated producers with captive solvent regeneration and toll processors dependent on merchant chemical supply. Apparel brands with science-based targets for Scope 3 emissions are prioritizing fiber from facilities with verified solvent capture rates above 99 percent. This technical specification is compressing margins for non-integrated converters while enabling premium pricing for producers with demonstrated closed-loop performance.
The EPA's pending revisions to effluent limitation guidelines for cellulosic fiber manufacturing are tightening total dissolved solids discharge thresholds for facilities discharging to southeastern watersheds. Mills operating near the Chattahoochee and Savannah river basins face accelerated capital schedules for zero-liquid-discharge upgrades. Home textile producers sourcing from these facilities are demanding third-party verification of compliance to preempt supply disruption risk from enforcement actions.
Brand-led fiber provenance requirements are displacing commodity spot purchasing with multi-year offtake agreements tied to specific production facilities. Direct relationships between California-based apparel labels and Alabama spinning operations are bypassing traditional merchant converter networks. This channel compression is most visible in premium denim and activewear verticals, where batch-level traceability supports marketing claims around domestic manufacturing and closed-loop chemistry.
North America Lyocell Fiber Market Segmentation
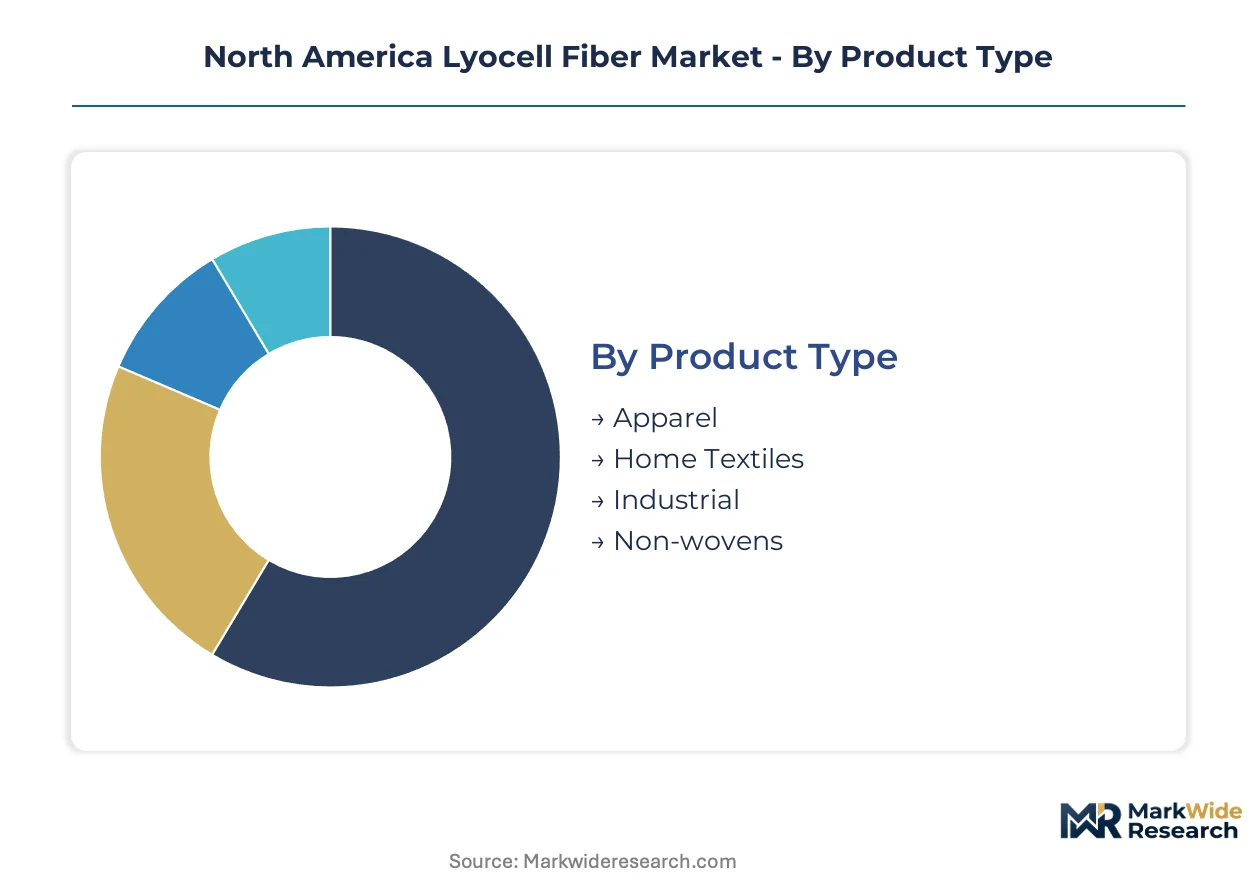
Segmentation in the North America lyocell fiber market reveals how regulatory pressure and end-use specifications fragment demand across incompatible technical tiers. Each dimension carries distinct compliance obligations and margin structures that reshape procurement strategies.
Product Type:
EPA effluent guidelines and state-level EPR mandates create divergent compliance burdens across product categories, with industrial applications facing the most stringent discharge monitoring.
- Apparel:Breathable woven and knitted fabrics for activewear, denim, and casual garments dominate current procurement volumes. California-based labels are unwinding polyester commitments fastest in this segment, sourcing Alabama-spun lyocell staple for domestic manufacturing claims.
- Home Textiles:Bedding and towel applications exploit lyocell's 13% moisture regain for cooling performance. New York State's pending textile EPR mandate is accelerating substitution of petroleum-based sheets in this category, though dye house recalibration costs slow adoption.
- Industrial:Filtration media and technical textiles requiring high tenacity above 4.0 cN/dtex.
- Non-wovens:Wipes and hygiene products where biodegradability supports disposal compliance.
Established volume favors apparel; emerging adoption favors home textiles.
End Use Industry:
Customer technical specifications determine fiber grade requirements, with automotive and healthcare demanding certified traceability that commodity fashion buyers bypass.
- Fashion:Premium denim and activewear brands specify batch-level provenance for marketing claims. Direct offtake agreements with Alabama spinning operations are displacing traditional merchant converter networks in this segment.
- Automotive:Tier-1 seating manufacturers qualify lyocell filament for luxury vehicle interiors, requiring high-tenacity grades with verified closed-loop solvent capture above 99 percent. This specification compresses margins for non-integrated suppliers.
- Healthcare:Wound-care non-wovens requiring USP Class VI biocompatibility certification command premium positioning.
- Upholstery:Residential and contract furniture applications where durability testing exceeds apparel standards.
Fashion commands current procurement scale; automotive represents the steepest expansion trajectory.
Form:
Processing equipment capabilities and end-use surface requirements split demand between continuous and cut fiber formats.
- Staple Fiber:Cut-length fibers spun into yarn for woven and knitted textiles. Georgia and Carolina mills cluster near Alabama dissolution facilities, shortening logistics loops for this volume-dominant format.
- Filament Fiber:Continuous yarn preserving surface luster and structural integrity for premium fashion and technical textiles. Equipment capable of switching between filament and staple outputs enables rapid pivoting between demand cycles.
- Blends:Lyocell-cotton and lyocell-wool combinations optimizing cost and performance.
- Sheets:Non-woven mat formats for industrial applications.
Staple fiber anchors volume leadership; filament fiber captures premium positioning.
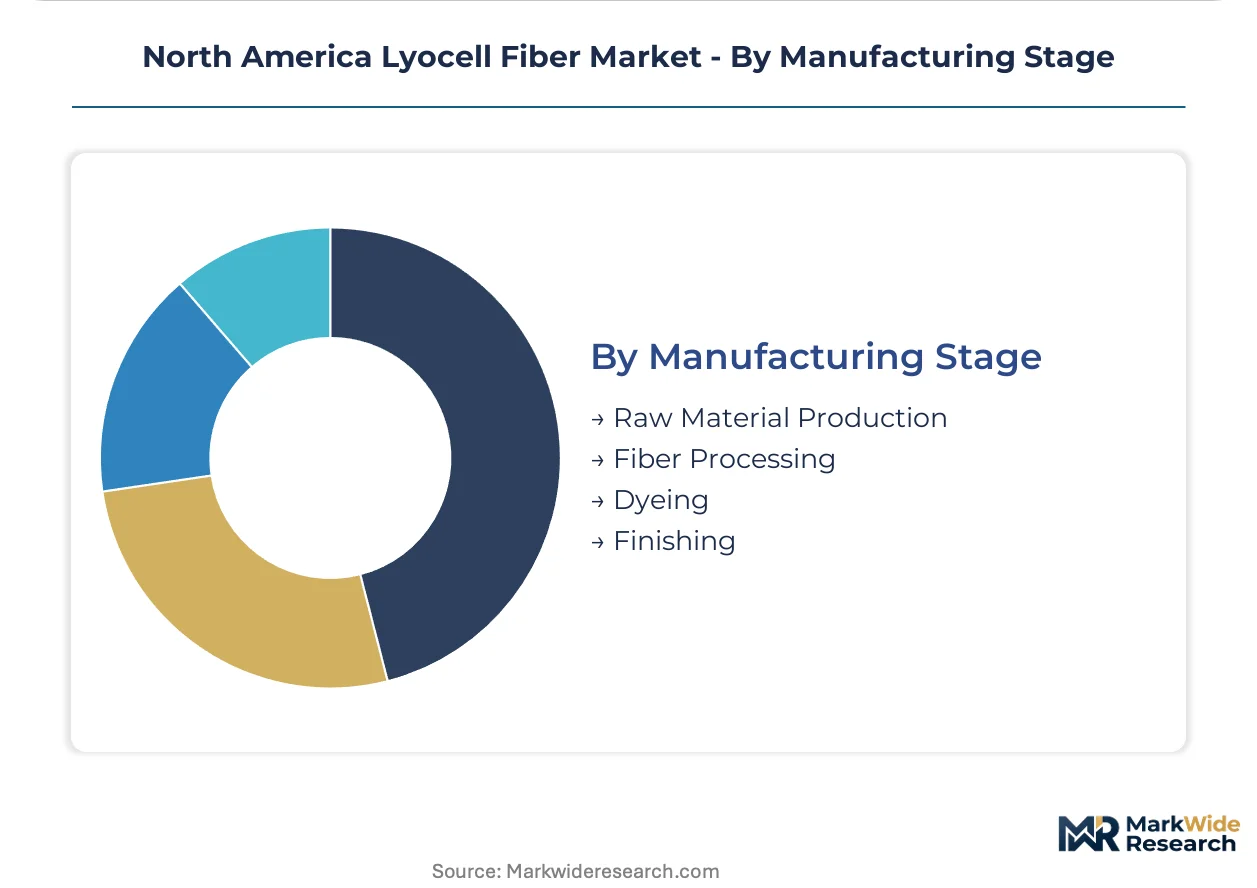
Manufacturing Stage:
Capital intensity and regulatory exposure concentrate at specific process nodes, with solvent recovery economics determining competitive viability.
- Raw Material Production:Hardwood dissolving pulp sourcing from southeastern US and Canadian suppliers faces concentration risk. NMMO solvent handling expertise concentrates among veterans of established Alabama operations.
- Fiber Processing:Direct dissolution and spinning operations where closed-loop recovery systems require eight-figure capex commitments. Mills near Chattahoochee and Savannah river basins face accelerated zero-liquid-discharge upgrade schedules.
- Dyeing:Conventional reactive systems optimized for cotton require recalibration for lyocell's higher moisture regain.
- Finishing:Final textile treatments where FTC Green Guides compliance extends launch timelines.
Raw material and fiber processing stages concentrate investment; finishing stages face compliance delays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian dissolving pulp producers supply hardwood feedstock to Alabama-based fiber mills, creating a cross-border trade corridor that anchors North American lyocell manufacturing. This upstream-downstream linkage concentrates investment around southeastern US processing clusters.
United States
California apparel brands drive procurement of biodegradable staple fiber under the state's Extended Producer Responsibility law. EPA effluent guidelines under the Clean Water Act force zero-liquid-discharge upgrades at mills near the Chattahoochee River basin. Georgia and Carolina spun-yarn mills cluster within trucking distance of Alabama dissolution facilities.
Canada
Quebec and British Columbia hardwood forests supply dissolving pulp to US lyocell producers. Health Canada's environmental assessment protocols align with EPA standards, smoothing cross-border raw material flows. Ontario chemical traders coordinate NMMO solvent logistics for toll processors serving the US market.
Mexico
Nuevo León automotive seating manufacturers qualify imported lyocell filament for luxury vehicle export programs. Mexico's environmental regulator SEMARNAT enforces wastewater standards that favor fiber from US facilities with verified closed-loop systems. Mexico City Metro apparel assemblers blend imported staple with domestic cotton for North American fast-fashion supply chains.
North America Lyocell Fiber Market Key Industry Players
Player mix skews toward integrated pulp-to-fiber conglomerates with captive solvent recovery infrastructure. Three distinct archetypes populate the landscape: European-headquartered multinationals with Alabama production bases, Asian conglomerates leveraging overseas filament capacity, and specialty-certified producers targeting medical-grade niches. Competitive moves concentrate on backward integration into dissolving pulp supply and technology licensing partnerships that transfer NMMO process expertise.
Among European-headquartered operators, Lenzing AG anchors the integrated producer archetype through its Alabama complex, while Smartfiber AG occupies the premium-certified tier with medical-grade fiber positioning. Grasim Industries Limited represents the Asian conglomerate model, drawing on overseas filament capacity to serve automotive upholstery tiers. These three exemplify how geographic origin and certification strategy stratify competitive positioning.
| Leading Market Players |
|---|
| Smartfiber AG |
| Baoding Swan Fiber Co., Ltd. |
| Lenzing AG |
| Weiqiao Textile Company Limited |
| Acegreen Eco-Material Technology Co., Ltd. |
| Aditya Birla Group |
| Chonbang Co., Ltd. |
| Aceton Chemicals & Fiber Corporation |
| Grasim Industries Limited |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between California apparel brands and Alabama spinning operations lock in both supply access and price visibility, insulating buyers from NMMO solvent cost volatility while compressing spot-market liquidity for non-integrated converters. These contracts typically embed volume commitments against fixed-price escalators tied to dissolving pulp indices, creating a dual-track market where integrated producers capture margin stability and merchant-dependent processors absorb feedstock risk.
Pricing Analysis
Closed-loop NMMO recovery technology creates a pronounced pricing gap between first-generation solvent-dependent processors and next-generation integrated facilities with verified capture rates above 99 percent. Contract-based long-term offtake dominates premium tiers, while commodity spot purchasing persists in mass-market apparel where polyester price anchoring from shale-advantaged US petrochemical complexes limits lyocell pricing power. Price differentiation hinges on certification grade—USP Class VI biocompatibility commands substantial premiums—and vertical integration into captive pulp supply. Pricing pressure stems from capital intensity of zero-liquid-discharge upgrades forced by EPA effluent guidelines, with home textile buyers exhibiting greatest price sensitivity due to dye house recalibration costs and automotive tiers showing least sensitivity given performance specifications.
Supply Chain Analysis
Inventory lead times for hardwood dissolving pulp have compressed to 6-8 weeks as southeastern US and Canadian suppliers align production schedules with Alabama dissolution facility runs. Geographic supply concentrates in the United States—specifically Georgia and Carolina mill clusters—Canada through Quebec and British Columbia pulp forests, and Mexico via Nuevo León automotive seating integration. Raw material dependencies center on NMMO solvent chemistry, specialized hardwood pulp grades, and reactive dye systems requiring recalibration. Single-source vulnerability concentrates in NMMO process engineering talent pools anchored to Lenzing's Alabama operations. Distribution runs through direct mill-to-brand channels for premium fashion, bypassing traditional merchant converter networks, while technical textiles flow through Tier-1 automotive supplier hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American lyocell fiber is approaching a platform-economics inflection where closed-loop solvent verification becomes the interoperability standard for brand procurement systems, with EPA compliance data serving as the trust anchor for multi-year offtake platforms.
For Market Incumbents: Secure backward integration into southeastern US dissolving pulp supply to defend against Grasim Industries' overseas filament cost advantages, while investing in USP Class VI certification infrastructure to capture medical-grade non-woven premiums before Smartfiber AG consolidates wound-care positioning. Channel control through direct Alabama spinning relationships remains critical as California EPR mandates accelerate spot-market displacement. For New Entrants and Emerging Players: Medical-grade lyocell certification gaps in wound-care non-wovens offer the most penetrable white-space, given incumbent concentration on commodity apparel volumes. Target toll-processing partnerships with automotive upholstery tiers in Nuevo León seeking verified closed-loop documentation for SEMARNAT compliance. A go-to-market angle anchored to batch-level provenance software—enabling California brand marketing claims—circumvents eight-figure solvent recovery capex barriers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale toll processors with existing NMMO handling permits and zero-liquid-discharge infrastructure in Chattahoochee watershed proximity, positioned for EPA guideline acceleration. Long-term viability across the analysis window favors facilities with demonstrated 99-plus percent solvent capture rates and direct brand relationships displacing merchant networks. Watch for FTC textile labeling rule revisions as the inflection signal that revalues biodegradability substantiation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dissolving Pulp | Captive hardwood supply from southeastern US forests insulates against Canadian pulp concentration risk. |
| Closed-Loop NMMO Recovery Scale-Up | Verified 99-plus percent solvent capture unlocks premium pricing from California apparel brands with Scope 3 targets. |
| USP Class VI Certification Investment | Medical-grade biocompatibility positioning commands wound-care non-woven margins underserved by commodity producers. |
| Direct Brand Offtake Platform Development | Bypassing merchant converter networks captures channel margin and locks in multi-year volume commitments. |
| Zero-Liquid-Discharge Infrastructure Upgrade | EPA effluent guideline compliance preempts enforcement risk for mills near Chattahoochee and Savannah basins. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, customs trade records for dissolving pulp flows, and FTC Green Guides litigation outcomes. Primary interviews engaged fiber processing plant managers, California apparel brand sustainability officers, Tier-1 automotive seating procurement leads, and Alabama-based spinning mill operations directors. Secondary validation drew from SEC filings of publicly traded fiber conglomerates, state-level EPR regulatory dockets in California and New York, and wastewater discharge permit records. Bottom-up fiber shipment data triangulates against top-down apparel brand procurement disclosures.
Segmentation dimensions modeled span product type across apparel, home textile, industrial, and non-woven categories; end-use industry including fashion, automotive, healthcare, and upholstery; form factor distinguishing staple from filament; and manufacturing stage from raw material through finishing. CAGRs derive from regression analysis of historical procurement volumes against regulatory implementation timelines and brand commitment acceleration patterns. Industry-specific forecast inputs incorporate NMMO solvent recovery capex cycles and dye house recalibration adoption curves.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement and California EPR implementation; material policy shifts such as federal textile EPR mandates or NMMO reclassification would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Woolen Textiles Market
Natural Fibers
Down and Feather Market
Natural Fibers
Cellulose Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Global Rattan Products Market
Natural Fibers
Jute Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Silk Stocking Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Jute Bags Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Silk Mask Market
Natural Fibers
Global Cotton Market