
 Natural Fibers Market | 2026-2036
Natural Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Fibers Market Analysis
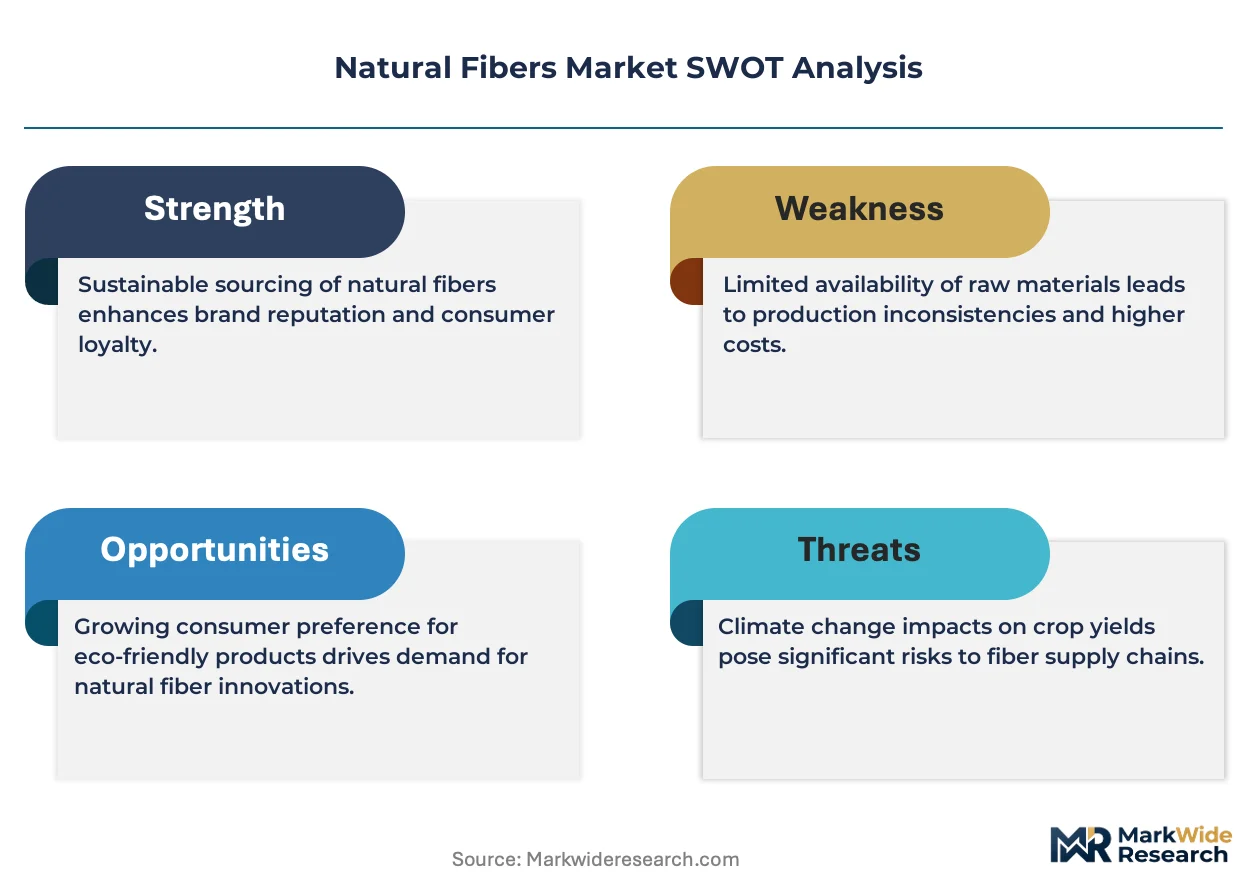
Indian jute mill consolidation is realigning global supply availability for packaging-grade fiber. Lenzing AG leverages its integrated pulp-to-fiber model to dominate regenerated cellulose output for fashion applications. Grasim Industries Ltd. anchors South Asian viscose staple capacity through captive chemical plants and backward integration into wood pulp. Bcomp differentiates by specializing in flax-based composite prepregs for automotive interior panels, competing against glass fiber on weight and recyclability metrics.
Natural fibers comprise plant-derived filaments such as cellulose-based cotton, bast fibers from flax and hemp stems, and lignocellulosic jute, typically measuring 10–50 micrometers in diameter with tensile strengths ranging from 300 to 900 MPa depending on moisture content and retting method. These fibers serve primarily as renewable reinforcement in polymer matrices and as spun yarn feedstock for woven textiles. Cotton holds the largest volume share across the product type dimension, though hemp is gaining traction in composite applications due to its superior stiffness-to-weight ratio. Within the application dimension, automotive interior components represent the fastest-expanding consumption pool as Tier 1 suppliers redesign door panels and seat backs to meet OEM sustainability targets. The grade dimension shows organic certification commanding price premiums in European fashion industry procurement, while conventional grades still dominate construction and packaging end users on cost efficiency.
REACH restrictions on microplastic shedding from synthetic textiles are redirecting European fashion industry sourcing toward certified organic and specialty grades. The EU Green Deal's carbon border adjustments and the F-Gas Regulation's indirect pressure on petrochemical feedstocks are tightening cost competitiveness for conventional synthetics. India's PLI scheme for textiles and BIS quality mandates are reshaping export eligibility for jute and cotton processors. Stakeholders must monitor evolving biodegradability certification standards across multiple jurisdictions to secure preferential market access and avoid stranded inventory in cross-border trade.
Market Dynamics
Automotive OEM sustainability mandates and REACH microplastic restrictions are converging to restructure fiber sourcing priorities across European manufacturing, compressing synthetic alternatives while expanding certified natural fiber procurement specifications.
Growth Catalysts
- EU Green Deal carbon border adjustments:Petrochemical-based synthetic fibers face escalating import costs, redirecting textile and composite procurement toward bast and cellulose alternatives with verified carbon footprints.
- Automotive lightweighting specifications:Door panel and seat back redesigns for electric vehicle range optimization are incorporating flax and hemp fiber composites to replace glass fiber reinforcement.
- India PLI scheme for textiles:Production-linked incentives for jute and organic cotton processing are expanding export-grade capacity and drawing contract manufacturing away from Bangladesh and Vietnam.
Market Restraints
- Seasonal bast fiber supply volatility:Jute and flax harvest yields fluctuate with monsoon patterns across the Ganges Delta and Normandy basin, creating raw material availability gaps for continuous manufacturing.
- Retting process water intensity:Traditional water retting for hemp and flax requires substantial freshwater access, constraining facility siting and raising compliance costs under tightening effluent regulations.
- Polypropylene fiber cost competition:Virgin and recycled polypropylene remains 40-60% cheaper on a per-kilogram basis for non-structural applications, limiting natural fiber penetration in price-sensitive packaging and construction mats.
Strategic Opportunities
- Brazilian cerrado hemp cultivation:Favorable climate and land availability outside traditional fiber belts offer geographic diversification for bast fiber supply chains currently concentrated in Europe and South Asia.
- Construction geotextile applications:Erosion control and soil stabilization specifications are expanding to include biodegradable jute mesh as temporary reinforcement for infrastructure projects.
- Blockchain-enabled fiber provenance:Farm-to-finished-goods traceability systems are unlocking premium pricing for organic and fair-trade certified cotton in fashion industry procurement.
Industry Challenges
- Biodegradability certification fragmentation:Competing standards across ISO, ASTM, and national frameworks create testing redundancy and market access delays for cross-border shipments.
- Composite processing equipment retooling:Automotive Tier 1 suppliers face capital expenditure requirements to modify injection molding lines for higher-moisture natural fiber feedstocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Fibers Market |
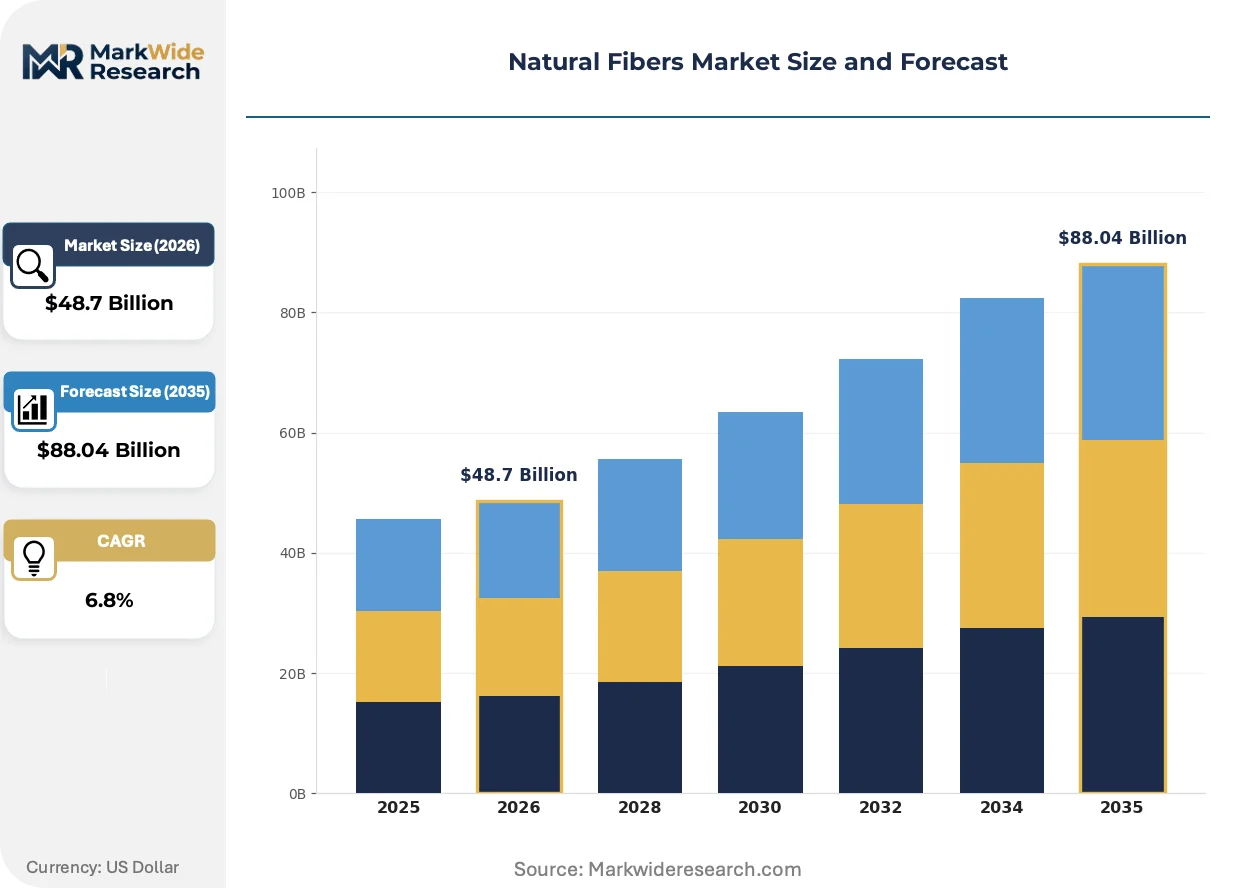
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cotton, Flax, Jute, Hemp Application: Textiles, Composites, Automotive, Insulation End User: Fashion Industry, Construction, Packaging, Furniture Grade: Organic, Conventional, Specialty, Blended |
| Companies Covered | Lenzing AG, Bcomp, Flexform SpA, Trex Company, Inc., Vardhman Textiles Limited, Procotex, Grasim Industries Ltd., Polyfibre Industries, TECNARO GMBH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Fibers Market Emerging Trajectories
Processing technology convergence and regulatory chemistry restrictions are compressing the viable solution set for fiber reinforcement, favoring integrated producers with captive pulp and chemical assets.
Enzymatic retting protocols are consolidating as the dominant bast fiber processing method, replacing water-intensive dew retting and chemical boiling. Automotive composite suppliers in Germany and France are specifying enzyme-processed flax for interior panel prepregs to meet OEM volatile organic compound limits. This consolidation is compressing the supplier base toward vertically integrated processors with in-house biotechnology capabilities.
REACH Annex XVII restrictions on intentionally added microplastics are extending to synthetic textile shedding, accelerating substitution mandates across EU member states. The European Chemicals Agency enforcement timeline is compressing procurement windows for fashion brands, forcing accelerated qualification of GOTS-certified organic cotton and TENCEL alternatives. German and Dutch retailers are responding with binding supplier sustainability scorecards that penalize conventional polyester content.
Direct contracting between automotive OEMs and fiber cooperatives is displacing traditional commodity trading structures for flax and hemp. Tier 1 suppliers in France and Belgium now source specific field lots with traceable lignin content for predictable composite performance. This pattern is most visible in the premium electric vehicle segment, where BMW and Volvo specifications require farm-level documentation for carbon footprint verification.
Natural Fibers Market Segmentation
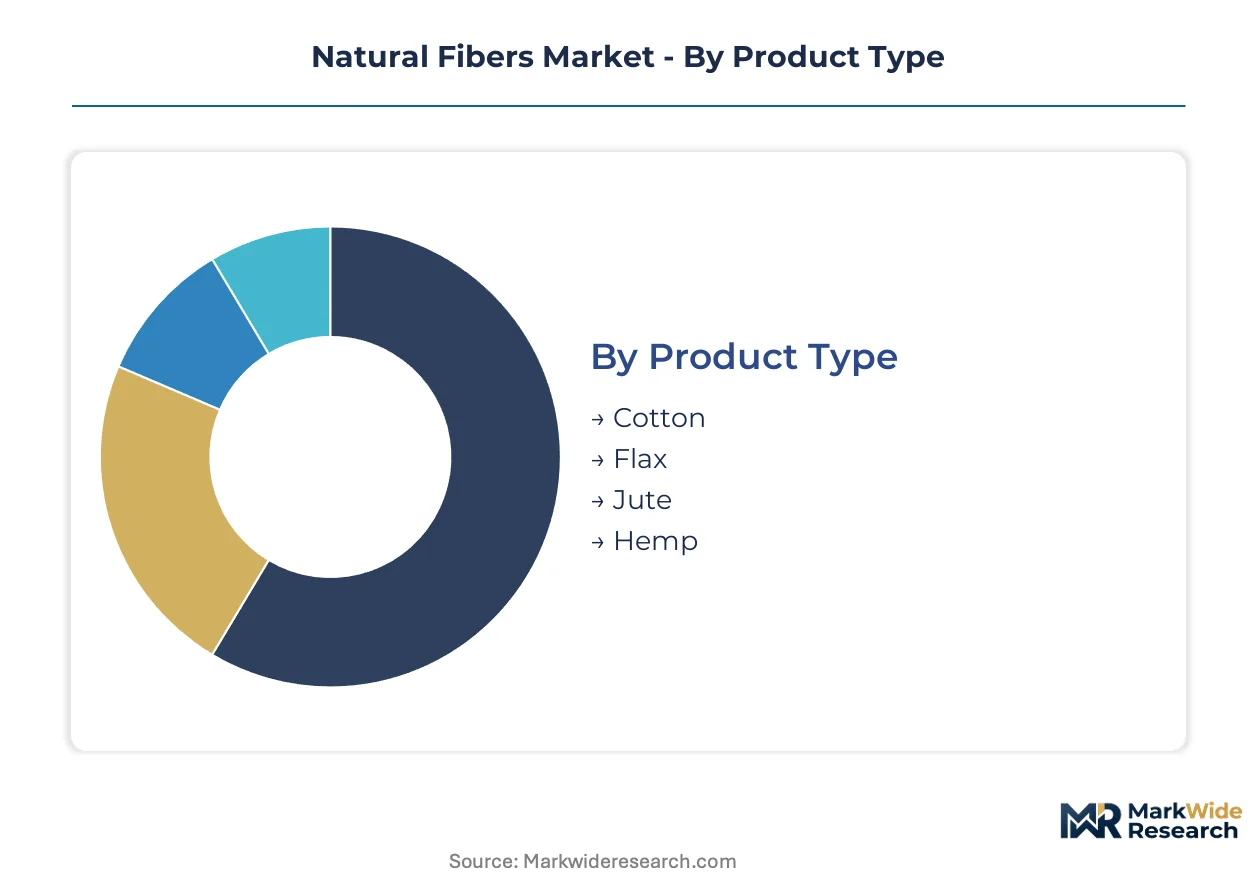
Segmentation in the natural fibers market reveals distinct procurement patterns across standalone textile applications versus embedded composite systems. Understanding these structural divisions enables suppliers to align capacity investments with specific end-use certification requirements and processing specifications.
Product Type:
Integration depth varies sharply across this dimension, with cotton operating primarily as standalone spun yarn while hemp and flax embed predominantly as reinforcement matrices.
- Cotton:Cellulose-based seed hair fibers measuring 10-20 micrometers in diameter serve as the dominant feedstock for woven and knitted textiles. Demand concentrates in Indian spinning clusters under BIS certification mandates, where PLI scheme incentives are expanding organic and extra-long staple processing capacity for export markets.
- Flax:Bast fibers extracted from stem phloem layers deliver superior stiffness-to-weight ratios of 50-70 GPa specific modulus. European automotive interior panel specifications in France and Belgium are absorbing enzyme-retted flax prepregs as glass fiber substitutes to meet OEM volatile organic compound limits.
- Jute:Lignocellulosic fibers from Corchorus species dominate packaging-grade applications and erosion control geotextiles.
- Hemp:Cannabis sativa bast fibers with high cellulose content are gaining composite traction where regulatory frameworks permit cultivation.
Volume placements concentrate in Cotton; the faster expansion belongs to Flax.
Application:
Cost tier differentiation separates commodity-scale textile spinning from precision-engineered automotive composite laminates requiring lot-traceable fiber properties.
- Textiles:Conventional ring spinning and open-end rotor systems process cotton and flax into apparel and home furnishing fabrics. REACH Annex XVII microplastic restrictions are redirecting European fashion procurement toward GOTS-certified organic grades with verified supply chain documentation.
- Composites:Non-woven mats and woven prepregs reinforce thermoset and thermoplastic polymer matrices for structural components. BMW and Volvo specifications in Germany and Sweden now require farm-level carbon footprint verification for flax and hemp interior panels.
- Automotive:Door panels, seat backs, and parcel shelves incorporate natural fiber composites to reduce vehicle mass for electric vehicle range optimization.
- Insulation:Hemp and flax shivs provide thermal and acoustic barrier materials for building envelope applications.
Procurement volumes favor Textiles; Composites are climbing the fastest as automotive lightweighting mandates tighten.
End User:
Customer type stratification creates divergent specification regimes, with fashion brands demanding certification transparency while construction and packaging prioritize unit cost minimization.
- Fashion Industry:Apparel brands and retailers in Germany and the Netherlands enforce binding supplier sustainability scorecards that penalize conventional polyester content. Blockchain-enabled farm-to-finished-goods traceability systems are unlocking premium pricing for organic and fair-trade certified cotton.
- Construction:Geotextile and insulation contractors specify biodegradable jute mesh for temporary soil stabilization in infrastructure projects. Erosion control applications favor conventional grades where project timelines match fiber degradation rates.
- Packaging:Sackcloth and cordage manufacturers consume jute and cotton blends for agricultural commodity transport.
- Furniture:Upholstery and bedding producers utilize cotton and flax for natural aesthetic positioning in residential and hospitality segments.
Order volumes cluster in Fashion Industry; Construction is gaining share fastest on infrastructure biodegradability specifications.
Grade:
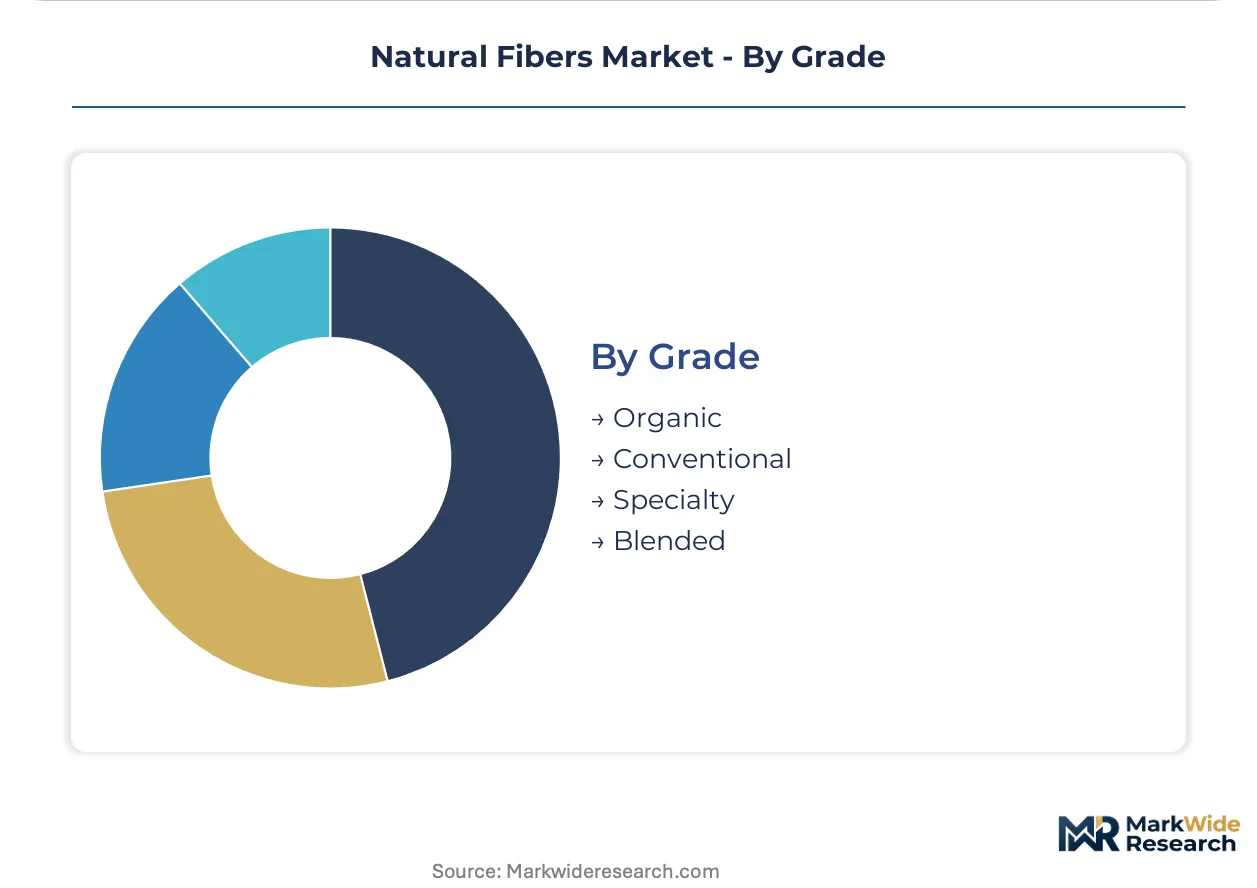
Margin structure separates certified organic premiums from conventional commodity pricing, with specialty grades commanding position in performance-critical composite applications.
- Organic:Third-party certified cultivation excluding synthetic pesticides and fertilizers meets EU Green Deal procurement criteria and carbon border adjustment documentation requirements. European fashion industry sourcing is redirecting toward these grades under accelerated qualification timelines.
- Conventional:Standard agricultural practices deliver cost-competitive fiber for construction mats and packaging where certification premiums are not recoverable.
- Specialty:Enzyme-retted and specific-lignin-content flax lots supply automotive Tier 1 suppliers with predictable composite performance characteristics.
- Blended:Cotton-polyester and natural-synthetic combinations balance cost and performance in mid-market textile applications.
Shipment volumes rest in Conventional; Organic shows the steepest expansion trajectory on regulatory substitution mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ganges Delta anchors raw material availability for jute cultivation, while Normandy's flax fields and the Brazilian cerrado define alternative bast fiber sourcing corridors for composite and textile applications.
India
West Bengal's jute processing clusters supply packaging-grade fiber under BIS certification mandates. The PLI scheme for textiles draws contract manufacturing toward organic cotton spinning in Maharashtra and Gujarat. Kolkata-based mills consolidate operations to meet export-grade specifications for European automotive and fashion procurement.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify enzyme-retted flax prepregs for interior panel applications. REACH Annex XVII enforcement accelerates substitution away from synthetic reinforcement. Stuttgart-area Tier 1 suppliers retool injection molding lines for higher-moisture natural fiber feedstocks.
France
Normandy's flax cooperatives deliver traceable field lots to premium electric vehicle manufacturers. The EU Green Deal's carbon border adjustments tighten documentation requirements for farm-level carbon verification. Lille-Roubaix textile clusters pivot toward GOTS-certified organic processing for Dutch and German retail contracts.
Brazil
The cerrado region offers geographic diversification for hemp cultivation outside traditional European and South Asian supply belts. Favorable climate conditions support year-round bast fiber production. São Paulo-state processors evaluate enzymatic retting protocols for export-grade composite feedstock.
Belgium
Walloon automotive suppliers source specific-lignin-content flax for predictable composite performance in door panel applications. ECHA enforcement timelines compress procurement windows for verified sustainable fiber. Ghent-area biotechnology firms develop captive enzyme processing capabilities for vertical integration.
Natural Fibers Market Vendor Landscape
Global majors compete with regional champions across integrated pulp-to-fiber supply chains and specialized composite prepreg fabrication. The market structure tiers between scale-driven cellulose producers and niche automotive material specialists. Three archetypes dominate: integrated chemical-fiber conglomerates with captive pulp assets, cooperative-based bast fiber processors with farm-level traceability, and biotechnology-enabled retting specialists. Competitive moves concentrate on backward integration into wood pulp cultivation and enzymatic processing technology licensing.
Among European integrated producers, Lenzing AG exemplifies the pulp-to-fiber model with regenerated cellulose dominance for fashion applications. Grasim Industries Ltd. anchors South Asian viscose staple capacity through in-house chemical plant operations. Bcomp occupies a specialist position within flax-based composite prepregs for automotive interior panels, competing against conventional glass fiber on weight and recyclability metrics.
| Leading Market Players |
|---|
| Lenzing AG |
| Bcomp |
| Flexform SpA |
| Trex Company, Inc. |
| Vardhman Textiles Limited |
| Procotex |
| Grasim Industries Ltd. |
| Polyfibre Industries |
| TECNARO GMBH |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustments gate qualified supply and premium-tier pricing access, forcing fiber processors to document farm-level carbon footprints for automotive and fashion procurement eligibility while excluding uncertified competitors from margin-rich contract tiers.
Pricing Analysis
Warranty and traceability documentation are unbundled from base fiber quotes, with certification premiums priced separately. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-retted automotive-grade flax from conventional packaging jute and construction mats. Cost compression in conventional grades is intensifying because polypropylene undercuts natural fiber on per-kilogram economics for non-structural applications. Packaging and construction buyers exhibit highest price sensitivity, while automotive OEMs and European fashion brands absorb certification premiums for verified supply chains.
Supply Chain Analysis
Seasonal labor availability in Normandy, West Bengal, and the Brazilian cerrado constrains retting and decortication throughput during peak harvest windows. Raw material flows draw from Ganges Delta jute cultivation, Normandy flax cooperatives, and cerrado hemp pilot plots. Single-source vulnerability concentrates in enzyme processing biotechnology, where German and Belgian firms dominate captive capabilities. Distribution runs through Rotterdam and Hamburg port hubs for European automotive Tier 1 suppliers, with direct farm-to-mill contracting displacing commodity trading for traceable grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII microplastic restrictions erect a compliance moat that rewards certified organic processors with preferential procurement access while stranding conventional synthetic-dependent competitors.
For Market Incumbents: Hedge against polypropylene cost competition by deepening backward integration into captive pulp assets and enzyme processing biotechnology. Secure long-term offtake agreements with Normandy and West Bengal cooperatives before new entrants lock in traceable supply. Automakers' binding sustainability scorecards threaten margin compression for undifferentiated commodity grades. For New Entrants and Emerging Players: India's PLI scheme for textiles opens a window for export-grade organic cotton spinning capacity in Maharashtra and Gujarat. Target construction geotextile applications where biodegradable jute mesh specifications are expanding fastest. Pursue direct contracting with infrastructure contractors bypassing traditional distribution layers. For Investors and Strategic Acquirers: BMW and Volvo farm-level carbon verification requirements are the leading indicator that traceability infrastructure will separate viable acquisition targets from stranded assets. Five-to-ten-year viability favors biotechnology-enabled retting specialists with in-house enzyme capabilities over commodity traders. Watch for consolidation signals in Kolkata-based jute mill restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood Pulp Cultivation | Lenzing AG and Grasim Industries anchor cost positions through captive pulp supply. |
| Enzymatic Retting Technology Licensing | Ghent-area biotechnology firms monetize processing IP across European automotive supply chains. |
| Blockchain-Enabled Fiber Provenance | German and Dutch retailers pay premiums for farm-to-finished-goods traceability systems. |
| Automotive Composite Prepreg Capacity Expansion | Bcomp and Flexform SpA scale flax-based panel production for BMW and Volvo specifications. |
| Organic Certification Program Investment | Indian PLI scheme recipients capture export eligibility under EU Green Deal procurement criteria. |
Methodological Framework
Trade statistics from Eurostat, customs data from India's DGFT, and automotive production databases from IHS Markit formed the secondary backbone for volume and flow analysis. Primary interviews with jute mill procurement directors, automotive Tier 1 supplier sustainability officers, and European fashion brand sourcing managers validated secondary estimates. Bottom-up fiber consumption modeling triangulated against top-down end-use industry demand projections.
Historical trendline analysis of jute, flax, and cotton pricing against synthetic fiber benchmarks established baseline elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and grade tier. CAGRs were derived from regression analysis of patent filing trajectories, capacity expansion announcements, and regulatory enforcement timelines. Enzymatic retting adoption curves and electric vehicle lightweighting specifications served as industry-specific demand drivers.
The model assumes a particular technology adoption path; alternative pathways for mechanical retting revival would alter the outlook for water-stressed processing regions. Forecasts reflect assumptions about REACH enforcement consistency and PLI scheme renewal. Material deviation in monsoon patterns across the Ganges Delta or ECHA microplastic rule acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Global Rattan Products Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Organic Cotton Market
Natural Fibers
Cellulose Market
Natural Fibers
Cellulose Fiber Market
Natural Fibers
North America Cotton Market
Natural Fibers
Jute Bags Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Natural Cotton Extract Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
North America Alpaca Fiber Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Silk Market