
 Lignocellulosic Fibers Market | 2026-2036
Lignocellulosic Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Lignocellulosic Fibers Market Foresight
Finland is reshaping lignocellulosic fiber supply dynamics through integrated pulp-to-specialty-fiber investments. Stora Enso Oyj leverages its Nordic timber position to anchor high-purity cellulose extraction for textile applications. UPM-Kymmene Corporation competes through backward integration into sustainable forestry, securing certified feedstock for specialty paper and composite grades. Lenzing AG dominates dissolving wood pulp refining, converting hardwood fibers into regenerated cellulosic intermediates for technical textile markets.
Lignocellulosic fibers consist of cellulose, hemicellulose, and lignin bound in a composite matrix, typically extracted through mechanical refining, chemical pulping, or enzymatic hydrolysis to achieve tensile strengths of 300–1000 MPa depending on source and processing intensity. These fibers serve primarily as renewable reinforcement in polymer composites, textile yarns, and engineered building materials where petroleum-based alternatives face carbon-accounting pressure. Wood fibers retain the largest volume share across paper and construction board applications, while hemp fibers command premium positioning in automotive composites where specific strength-to-weight ratios justify higher processing costs. Bamboo fibers are expanding fastest in textile applications, particularly where OEKO-TEX and FSC chain-of-custody certification unlocks access to EU and North American apparel supply chains.
The EU Green Deal and REACH chemical registration requirements in Europe are mandating lifecycle carbon disclosure for construction and automotive materials, directly elevating demand for EPD-certified lignocellulosic inputs. EPA renewable fuel standard pathways and USDA BioPreferred procurement specifications in the United States create parallel compliance incentives for domestically sourced fiber feedstocks. Stakeholders must monitor evolving biogenic carbon accounting methodologies under ISO 14067 and EN 15804, as these standards will determine which fiber sources and processing routes qualify for green procurement tenders and low-carbon building codes.
Market Dynamics
Automotive OEMs in Germany are compressing material qualification cycles for hemp and flax fiber composites, forcing pulp processors to reconfigure extraction protocols for higher tensile consistency. This demand pull from Tier-1 suppliers is restructuring upstream fiber preparation investments across Nordic timber markets.
Growth Catalysts
- EU Green Deal lifecycle mandates:EPD certification requirements for construction materials in France and the Netherlands are redirecting specification budgets toward certified lignocellulosic reinforcement. Building contractors now face carbon disclosure thresholds that synthetic fibers cannot satisfy.
- REACH substitution pressures:Chemical registration restrictions on petroleum-based reinforcements are elevating bio-composite qualification in automotive interior programs. ECHA compliance timelines are accelerating R&D allocation toward hemp and flax fiber matrices.
- Bamboo fiber certification pipelines:OEKO-TEX and FSC chain-of-custody standards are unlocking apparel supply chain access for Southeast Asian textile mills. Spinning houses in Vietnam and Indonesia are retrofitting equipment for bamboo pulp processing.
Market Restraints
- Softwood pulp price volatility:Nordic timber harvest fluctuations and energy cost spikes at Finnish and Swedish mills are compressing margin predictability for specialty cellulose grades. Pulp contract structures lack hedging mechanisms for smaller composite compounders.
- Hemp fiber supply concentration:French and Dutch agricultural cooperatives dominate EU hemp bast fiber production, creating geographic chokepoints for automotive qualification programs. Single-source dependency risks delay OEM approval timelines.
- Enzymatic hydrolysis yield ceilings:Current cellulose extraction protocols max out at 65-70% purity for textile-grade dissolving pulp, leaving 30% residual lignin that degrades spinning performance. Mechanical refining alternatives consume excessive energy per ton.
Strategic Opportunities
- USDA BioPreferred procurement expansion:Federal agency purchasing mandates for domestically sourced bio-based materials are opening specification pathways for US hardwood fiber processors. Composite manufacturers can bypass petroleum-based incumbent lock-in.
- India construction board demand:Low-density fiberboard applications in affordable housing projects represent underpenetrated volume potential for imported softwood pulp. Domestic MDF capacity constraints force reliance on Southeast Asian supply.
- Enzyme-mechanical hybrid processing:Convergent biotech and pulp engineering approaches are reducing lignin contamination below 15% without sulfur-based chemical pulping. Pilot installations in Austria demonstrate 40% energy reduction per ton of textile-grade output.
Industry Challenges
- ISO 14067 biogenic carbon accounting expertise:Fiber processors lack in-house lifecycle assessment capability to document carbon sequestration claims for automotive and construction tenders. Third-party verification costs exceed mid-tier supplier budgets.
- Automotive qualification timeline compression:OEM material approval cycles now demand 18-month durability testing protocols that small-scale fiber compounders cannot resource. Tier-1 supplier consolidation favors vertically integrated pulp-to-composite operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lignocellulosic Fibers Market |
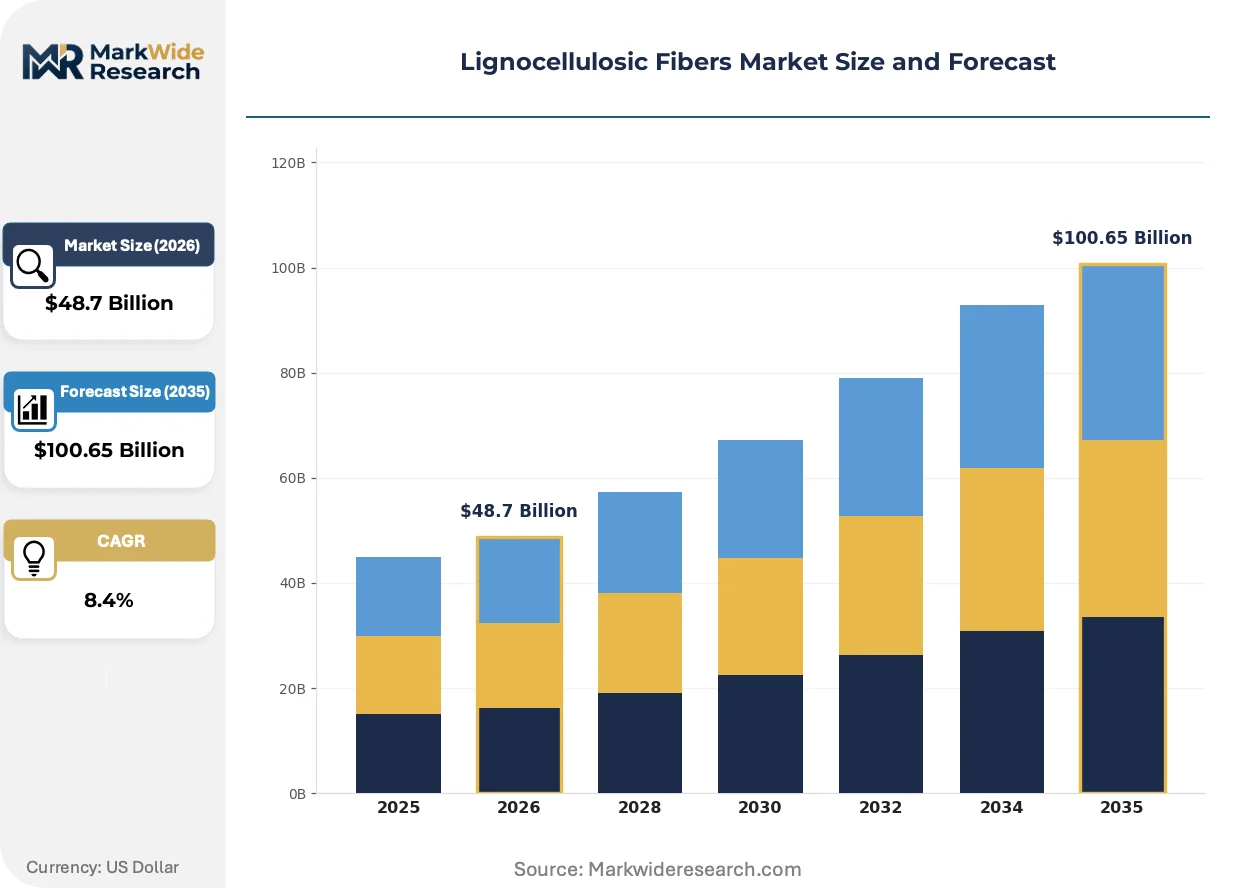
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Fibers, Bamboo Fibers, Wood Fibers, Kenaf Fibers Application: Composites, Textiles, Paper, Construction End User: Automotive, Aerospace, Furniture, Agriculture Form: Raw, Pre-Processed, Processed, Reinforced |
| Companies Covered | BASF SE, DuPont de Nemours Inc, Stora Enso Oyj, Mitsubishi Chemical Corporation, Sappi Limited, UPM-Kymmene Corporation, Lenzing AG, Grasim Industries Limited, JELU-WERK J. Ehrler GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lignocellulosic Fibers Market Shifts & Advancements
Digital twin modeling of fiber-matrix interfaces is compressing R&D iteration cycles for composite compounders. Virtual material testing protocols are displacing physical prototyping in automotive and construction qualification programs.
Enzymatic pre-treatment platforms are virtualizing traditional chemical pulping infrastructure for textile-grade cellulose extraction. Finnish and Austrian engineering firms are deploying AI-controlled enzyme dosing systems that cut water consumption by half. Dissolving wood pulp refiners adopting these platforms are bypassing sulfur recovery investments while meeting Lenzing AG purity benchmarks.
EPA renewable fuel standard pathway expansions are redirecting agricultural residue streams toward fiber extraction rather than ethanol conversion. Corn stover and wheat straw processors in Iowa and Illinois are reconfiguring pretreatment equipment for pulp-grade cellulose output. This regulatory arbitrage is compressing feedstock costs for US-based composite manufacturers below imported Nordic softwood levels.
Buyer concentration among automotive Tier-1 suppliers is forcing fiber processors toward direct mill-to-mold supply contracts. Specifiers at Magna International and Lear Corporation are bypassing traditional pulp merchant networks for certified hemp and flax fiber lots. This channel disintermediation is visible most acutely in German automotive clusters where OEMs mandate supplier consolidation for carbon traceability.
Lignocellulosic Fibers Market Segmentation
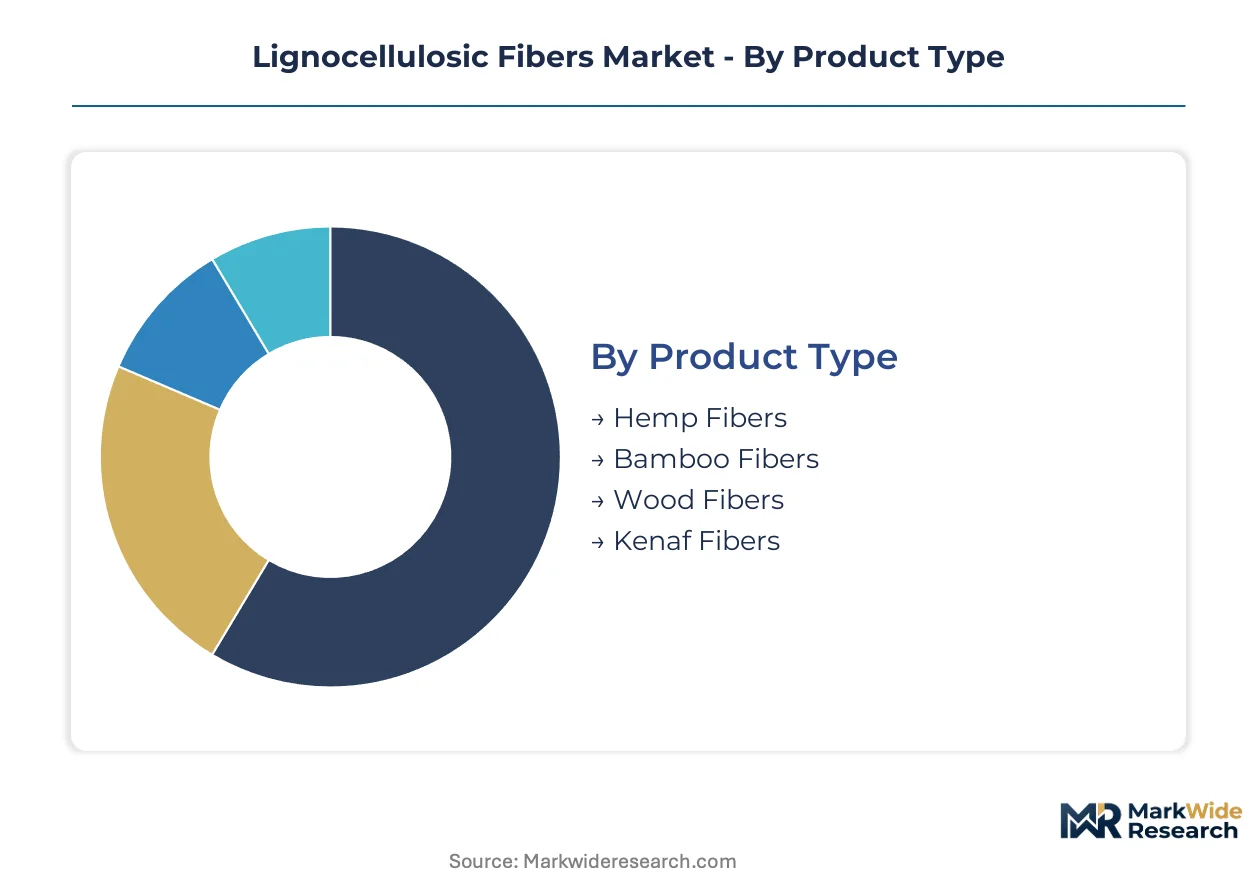
Segmentation in the lignocellulosic fibers market exposes divergent technical requirements across end-use verticals. Automotive qualification protocols demand batch-to-batch tensile consistency that textile spinners tolerate less strictly. Understanding these segment boundaries prevents misallocation of processing investments across incompatible specification tiers.
Product Type:
After-sales service intensity varies sharply by fiber source, with bast fiber processors fielding more technical support calls for composite qualification failures than wood fiber merchants serving commodity paper markets.
- Hemp Fibers:Cellulose-rich bast fibers extracted from Cannabis sativa stalks deliver specific tensile strength of 300-800 MPa with low microfibril angle. German automotive OEMs and Tier-1 suppliers at Magna International specify hemp for interior panel substrates where crashworthiness and carbon accounting converge. REACH substitution pressures and EPD certification mandates elevate hemp positioning despite French and Dutch agricultural supply concentration.
- Bamboo Fibers:Rapid-growth grass species yield regenerated cellulosic filaments through viscose or lyocell processing routes. Southeast Asian spinning houses in Vietnam and Indonesia retrofit equipment for bamboo pulp to capture OEKO-TEX and FSC-certified apparel supply chains. EU Green Deal lifecycle disclosure requirements favor bamboo's documented carbon sequestration profile.
- Wood Fibers:Mechanical or chemical pulping of softwood and hardwood species dominates volume across paper and construction board applications. Nordic mills in Finland and Sweden anchor specialty cellulose extraction for dissolving pulp refiners.
- Kenaf Fibers:Hibiscus cannabinus bast fibers offer intermediate properties between hemp and jute for emerging composite applications. Agricultural residue streams in India and Bangladesh supply nascent automotive trials.
By volume, Wood Fibers leads. By growth pace, Bamboo Fibers is ahead.
Application:
Cost tier stratification separates commodity construction board from premium automotive composites, with textile applications occupying a mid-tier position defined by certification premiums.
- Composites:Fiber-reinforced polymer matrices substitute glass fiber in automotive interior panels, structural components, and furniture frames. German OEM qualification programs compress material approval cycles, forcing pulp processors to reconfigure extraction protocols for tensile consistency. EPA renewable fuel standard pathway expansions redirect US agricultural residues toward fiber extraction for domestic composite manufacturing.
- Textiles:Regenerated cellulosic yarns from dissolving wood pulp serve technical and apparel markets where petroleum-based synthetics face carbon-accounting pressure. Lenzing AG purity benchmarks dominate specification standards.
- Paper:Virgin and recycled wood pulp grades satisfy packaging and printing demand with minimal processing intensity relative to textile or composite routes. Nordic softwood supply anchors global trade flows.
- Construction:Medium-density fiberboard and oriented strand board applications leverage low-cost fiber streams for affordable housing projects in India and Southeast Asia. EPD certification requirements in France and the Netherlands redirect specification budgets toward certified lignocellulosic reinforcement.
Composites command the highest value per ton. Construction absorbs the greatest raw volume.
End User:
Customer type fragmentation concentrates procurement power among consolidated Tier-1 automotive suppliers while furniture and agriculture segments retain dispersed buyer structures.
- Automotive:Interior panels, door modules, and structural reinforcements specify hemp and flax composites for mass reduction and carbon disclosure compliance. KBA type-approval requirements and EU Green Deal mandates compress supplier consolidation timelines.
- Aerospace:Secondary structures and cabin interiors evaluate lignocellulosic alternatives for non-structural weight reduction where flame-retardant certification permits bio-based substitution.
- Furniture:Particleboard and MDF substrates for flat-pack and upholstered furniture absorb softwood fiber volumes with less stringent mechanical specification than automotive or aerospace tiers.
- Agriculture:Erosion control mats, nursery containers, and biodegradable mulch films represent emerging outlets for lower-grade fiber streams with minimal processing investment.
Automotive sets the most demanding specification standards. Agriculture presents the lowest barrier to supplier entry.
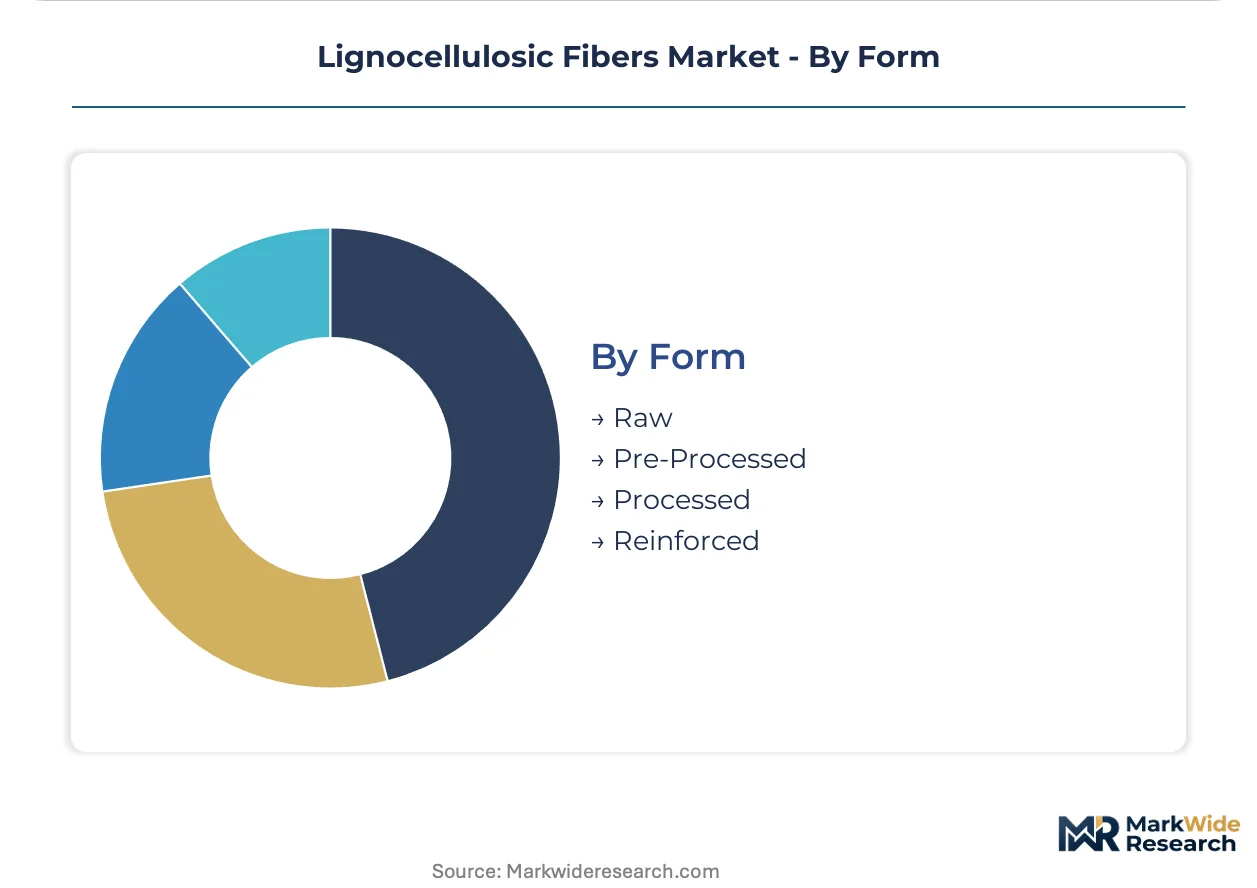
Form:
Supply concentration in pre-processed and processed grades reflects downstream channel disintermediation as automotive Tier-1 suppliers bypass traditional pulp merchant networks.
- Raw:Field-retted or decorticated bast fibers and chipped wood furnish require further mechanical or chemical treatment before specification-grade applications. French and Dutch hemp cooperatives dominate EU raw bast fiber supply.
- Pre-Processed:Cleaned, refined, and partially purified fiber streams reduce downstream capital intensity for composite compounders and textile spinners. Finnish and Austrian engineering firms deploy enzyme-mechanical hybrid platforms at this stage.
- Processed:Bleached or unbleached pulp grades meet dissolving pulp purity thresholds for regenerated cellulose production. Lenzing AG and comparable refiners dictate quality benchmarks.
- Reinforced:Compounded pellets or non-woven mats integrate lignocellulosic fibers with polymer matrices for direct molding operations. Magna International and Lear Corporation specify certified lots through direct mill-to-mold contracts.
Processed forms capture the greatest value addition. Reinforced forms are expanding most quickly as channel disintermediation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance timelines and EU Green Deal mandates anchor European demand leadership. Automotive OEM qualification programs and construction EPD certification requirements concentrate procurement power in specific national clusters.
Germany
KBA type-approval standards compress material qualification cycles for hemp and flax fiber composites. Magna International and Lear Corporation consolidate supplier relationships through direct mill-to-mold contracting. The Stuttgart automotive cluster hosts active Tier-1 material qualification programs for interior panel substrates.
United States
USDA BioPreferred federal procurement mandates open specification pathways for domestic hardwood fiber processors. EPA renewable fuel standard pathway expansions redirect Iowa and Illinois agricultural residues toward pulp-grade cellulose extraction. Corn stover processors in the Midwest reconfigure pretreatment equipment for composite manufacturing feedstock.
Finland
Nordic timber harvest positions anchor specialty cellulose extraction for textile applications. Stora Enso Oyj and UPM-Kymmene Corporation maintain integrated pulp-to-specialty-fiber investments. Finnish engineering firms deploy AI-controlled enzyme dosing systems that cut water consumption in dissolving pulp refining.
France
Agricultural cooperatives dominate EU hemp bast fiber production for automotive composite qualification. EPD certification requirements in construction redirect specification budgets toward certified lignocellulosic reinforcement. The Hauts-de-France region concentrates field-retting and decortication capacity for Tier-1 supplier programs.
India
Domestic MDF capacity constraints force reliance on imported softwood pulp for affordable housing fiberboard. BIS standards and construction procurement specifications create compliance frameworks for imported reinforcement materials. Maharashtra and Gujarat industrial corridors absorb growing volumes of medium-density fiberboard for residential construction.
Lignocellulosic Fibers Market Competitive Landscape
Integrated pulp-to-specialty-fiber conglomerates and dissolving wood pulp refiners split the market structure. Nordic timber-based operators leverage backward integration into certified forestry to anchor supply security. Specialty cellulose refiners compete on purity benchmarks for regenerated cellulosic intermediates. Dominant competitive moves include direct mill-to-mold supply contracting and enzyme-mechanical hybrid processing platform deployment.
Within the integrated forestry tier, Stora Enso Oyj and UPM-Kymmene Corporation represent Nordic supply anchoring through captive timber positions. Among dissolving pulp specialists, Lenzing AG occupies a position defining textile-grade purity benchmarks that competitors must satisfy. These three companies exemplify the geographic and technological concentration shaping procurement relationships with automotive Tier-1 suppliers and apparel supply chains.
| Leading Market Players |
|---|
| BASF SE |
| DuPont de Nemours Inc |
| Stora Enso Oyj |
| Mitsubishi Chemical Corporation |
| Sappi Limited |
| UPM-Kymmene Corporation |
| Lenzing AG |
| Grasim Industries Limited |
| JELU-WERK J. Ehrler GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
French and Dutch hemp bast fiber supply concentration determines both pricing tier spreads and supply chain shape for automotive qualification programs. Single-source dependency in EU agricultural cooperatives elevates premium-grade hemp pricing while compressing margin predictability for compounders lacking direct contracting relationships with field-retting operators.
Pricing Analysis
Nordic softwood pulp trades at substantial premiums to Southeast Asian bamboo fiber grades, reflecting energy cost differentials and certification overhead. Three-tier pricing structure across premium, standard, and economy levels segments by OEKO-TEX certification status, FSC chain-of-custody documentation, and tensile consistency batch testing. Cost compression in standard-grade wood fiber intensifies because of energy price spikes at Finnish and Swedish mills. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to carbon accounting mandates, while Indian construction board importers face acute cost pressure from domestic MDF capacity constraints.
Supply Chain Analysis
Field-retted hemp bast from France, mechanically refined softwood pulp from Finland and Sweden, and viscose-processed bamboo fiber from Vietnam and Indonesia constitute the upstream feedstock base. Automotive qualification programs draw from French agricultural cooperatives, Nordic timber harvests, and Southeast Asian spinning house retrofits. Single-source vulnerability in EU hemp bast production threatens OEM approval timelines when weather disrupts field-retting schedules. Distribution runs through direct mill-to-mold contracts for reinforced composite grades, bypassing traditional pulp merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by EU Green Deal lifecycle mandate implementation across automotive and construction procurement specifications.
For Market Incumbents: Harden supply security through backward integration into certified forestry or direct agricultural contracting with French and Dutch hemp cooperatives. Invest in ISO 14067 biogenic carbon accounting capability to defend specification-grade positioning against emerging enzyme-mechanical hybrid processors. Channel control through direct mill-to-mold relationships with Magna International and Lear Corporation represents the critical defensive lever against Tier-1 supplier consolidation. For New Entrants and Emerging Players: USDA BioPreferred procurement pathways for domestic US hardwood fiber processors represent the most penetrable entry point, bypassing petroleum-based incumbent lock-in in federal agency purchasing. India construction board demand for affordable housing fiberboard offers secondary white-space volume potential where imported softwood pulp fills domestic MDF capacity gaps. Go-to-market execution should anchor on EPA renewable fuel standard pathway arbitrage for corn stover and wheat straw processors in Iowa and Illinois. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated pulp-to-specialty-fiber operators with captive timber positions and enzyme-mechanical hybrid processing platforms. Long-term viability across the five-to-ten-year window rests on biogenic carbon accounting expertise and automotive qualification track records. Acquisition targets should demonstrate direct Tier-1 supplier relationships and EPD certification capabilities. The signal to watch is KBA type-approval timeline compression that favors vertically integrated operators over merchant pulp suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Mechanical Hybrid Processing Deployment | Finnish and Austrian engineering firms cut water consumption by half while meeting Lenzing AG purity benchmarks. |
| Direct Mill-to-Mold Supply Contracting | Magna International and Lear Corporation bypass traditional pulp merchants for certified hemp and flax fiber lots. |
| Backward Integration into Certified Forestry | Stora Enso Oyj and UPM-Kymmene Corporation anchor supply security through Nordic timber positions. |
| ISO 14067 Biogenic Carbon Accounting Investment | EPD certification requirements in France and Netherlands elevate demand for documented carbon sequestration claims. |
| USDA BioPreferred Procurement Qualification | Federal agency purchasing mandates open specification pathways for domestic hardwood fiber processors. |
Research Methodology
Operator-level perspectives from composite compounders, textile spinners, automotive Tier-1 procurement officers, pulp mill technical directors, and agricultural cooperative managers anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, SEC 10-K filings of listed forestry conglomerates, ECHA REACH registration databases, and OEKO-TEX certification registries. Bottom-up fiber volume estimates by source and application triangulated against top-down market sizing from dissolving pulp refinery capacity disclosures.
Scenario-bracketing around EU Green Deal implementation pace, EPA renewable fuel standard pathway expansion timing, and enzymatic hydrolysis yield improvements framed the analytical approach across the projection horizon. Segmentation modeling captured product type, application vertical, end-user industry, and processing form dimensions alongside regional regulatory cluster variations. CAGRs derived from elasticity-adjusted demand curves incorporating substitution rates for glass fiber in automotive composites and petroleum-based synthetics in technical textiles. Forecast inputs included Nordic timber harvest forecasts and automotive OEM lightweighting program announcements.
Practitioners should monitor ECHA REACH substitution timeline acceleration, KBA type-approval protocol changes, and Nordic energy cost volatility for early signals of forecast revision. Cross-checking against IEA industrial bioenergy demand projections and automotive industry association material disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Gum Fiber Market
Natural Fibers
North America Textile Market
Natural Fibers
Natural Fibers Market
Natural Fibers
Global Cotton Market
Natural Fibers
Global Hemp Fiber Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
Textile Staples Market
Natural Fibers
North America Cotton Market
Natural Fibers
Global Alpaca Fiber Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Down and Feather Market
Natural Fibers
Natural Fiber Composite (NFC) Market
Natural Fibers
Apple Fiber Market
Natural Fibers
Natural Fibers and Sisal Market
Natural Fibers
Bamboo Fibers Market
Natural Fibers
Woolen Textiles Market