
 Airport Internet of Things Market | 2026-2036
Airport Internet of Things Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Internet of Things Market Analysis
Sensor manufacturers in Germany and Japan are expanding production capacity for aviation-grade IoT hardware. Cisco Systems, Inc. leverages its networking infrastructure to dominate airport connectivity deployments across North America. Honeywell International Inc. sustains technology leadership through its building automation systems tailored for terminal environments. Siemens AG anchors European market presence with integrated facility management platforms that combine edge computing and smart sensor arrays.
Airport Internet of Things denotes a networked ecosystem of connected devices, sensors, and analytics platforms that collect real-time operational data across terminal, airside, and landside environments. These systems typically operate on low-latency protocols such as LoRaWAN or 5G private networks to enable instantaneous baggage tracking, environmental monitoring, and passenger flow optimization. Smart Sensors and Data Analytics represent the most technically demanding segments, where margin pools concentrate around predictive maintenance algorithms and real-time decision engines. Cloud Computing deployments are gaining traction among mid-sized airports seeking to avoid capital-intensive on-premises infrastructure, while Edge Computing serves security-critical applications requiring sub-millisecond response times.
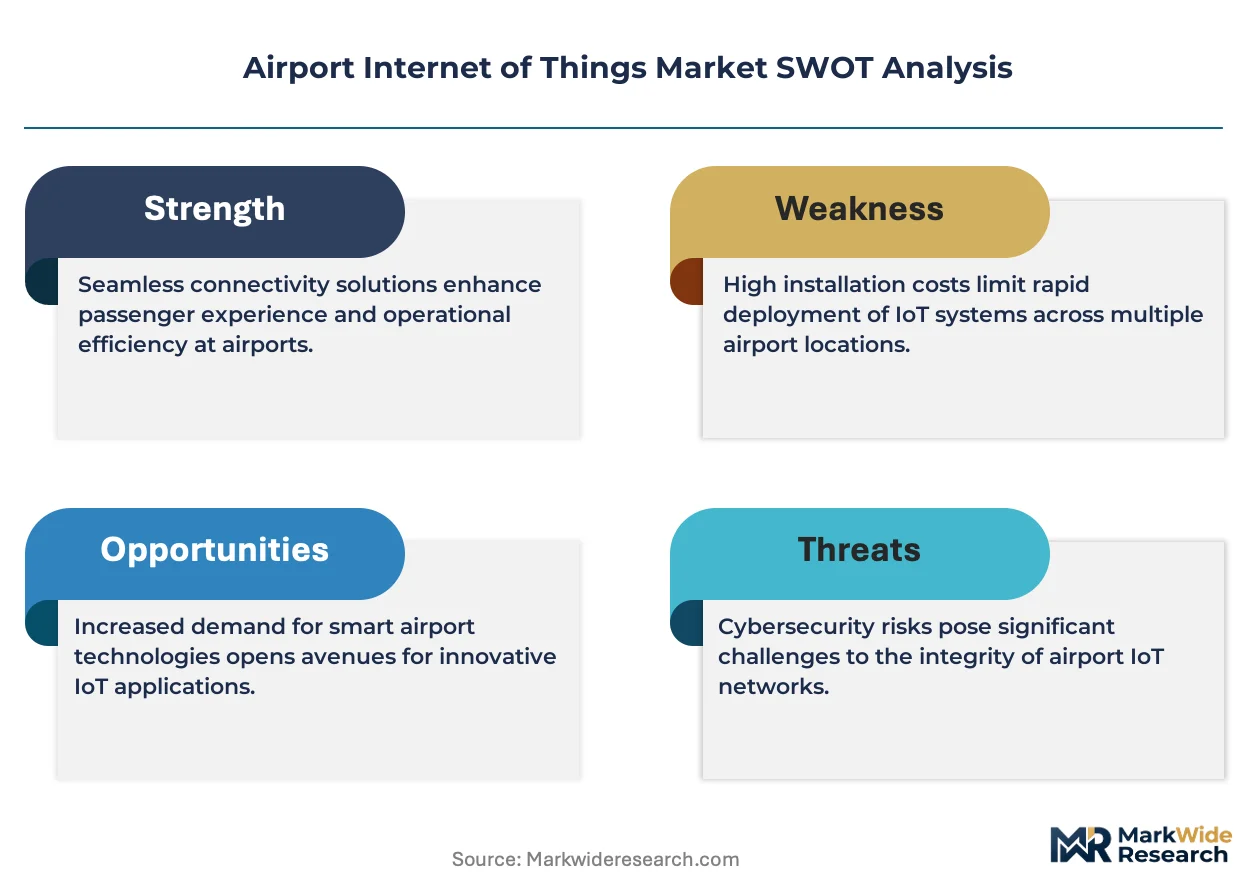
The Federal Aviation Administration mandates cybersecurity frameworks for airport operational networks, pushing operators toward certified IoT architectures. EASA's regulatory guidance on connected airside equipment shapes procurement standards for ground handlers and aeronautical authorities across Europe. ISO/IEC 27001 compliance has become a baseline requirement for cloud-based deployment contracts. Stakeholders must weigh interoperability standards against vendor lock-in risks as hybrid architectures become the default configuration.
Market Dynamics
The EU Green Deal is pressuring European airports to deploy energy-efficient IoT infrastructure, while ground handlers across North America and Asia-Pacific simultaneously expand connected baggage handling systems to reduce operational losses.
Growth Catalysts
- EU Green Deal mandates:European airports must retrofit terminal operations with energy-monitoring sensor networks to meet carbon reduction targets, accelerating procurement cycles for smart building systems.
- Private 5G deployment:Low-latency 5G private networks enable real-time baggage tracking and passenger flow optimization, with major hub airports in the United States leading infrastructure upgrades.
- Mishandled luggage reduction:Ground handlers are investing in connected baggage handling systems to cut loss rates and avoid compensation liabilities.
Market Restraints
- Aviation-grade hardware costs:Sensor manufacturers in Germany and Japan face capacity constraints, creating input cost volatility for certified IoT components.
- Cybersecurity compliance burden:FAA-mandated frameworks for operational networks impose certification timelines that delay deployment schedules.
- Legacy system interoperability:Hybrid architectures required to bridge old and new infrastructure increase integration complexity and total cost of ownership.
Strategic Opportunities
- Mid-sized airport cloud migration:Cloud Computing deployments offer escape from capital-intensive on-premises infrastructure, with mid-tier airports in Spain and Italy showing early adoption.
- Edge Computing security applications:Sub-millisecond response requirements for airside safety systems create demand for localized processing at runway and gate zones.
- Predictive maintenance algorithms:Smart Sensors and Data Analytics segments concentrate margin pools around real-time decision engines for ground support equipment.
Industry Challenges
- ISO/IEC 27001 certification timelines:Cloud-based deployment contracts now require baseline compliance, extending vendor qualification periods by six to twelve months.
- Multi-protocol integration:LoRaWAN and 5G private networks must coexist with legacy Wi-Fi and cellular systems, creating configuration complexity for terminal operators.
- Cybersecurity talent scarcity:Aviation-specific network security expertise remains concentrated among specialized contractors, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Internet of Things Market |
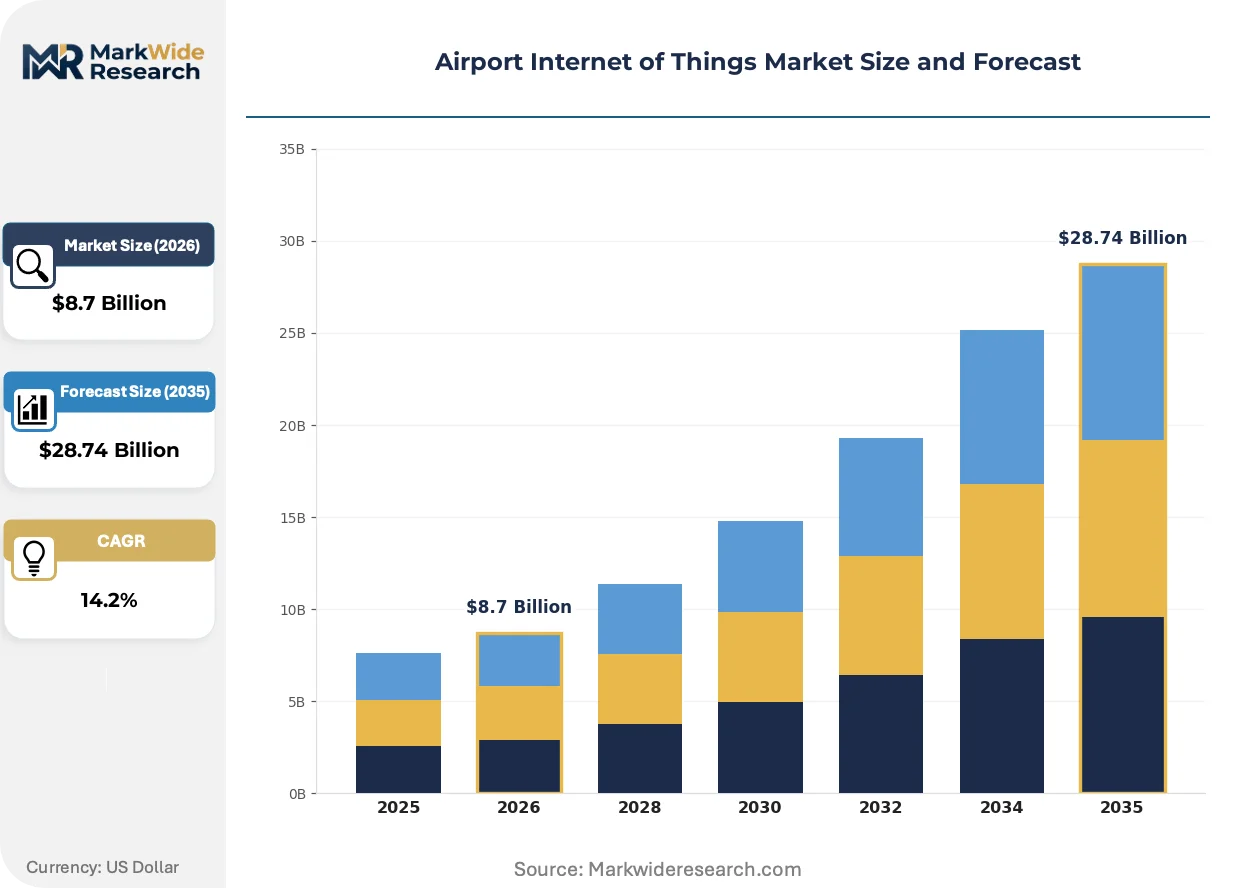
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Sensors, RFID, Data Analytics, Cloud Computing Application: Passenger Experience, Baggage Tracking, Security Management, Facility Management End User: Aeronautical Authorities, Airlines, Ground Handlers, Retail Operators Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, Amadeus IT Group, Honeywell International Inc., SITA, SAP SE, Cisco Systems, Inc., Microsoft Corporation, Siemens AG, Huawei Technologies Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Internet of Things Market Emerging Trajectories
Aviation IoT architectures are pivoting from centralized data lakes toward distributed edge intelligence, with regulatory pressure and latency requirements forcing simultaneous upgrades across hardware, networking, and analytics layers.
Edge Computing is overtaking cloud-centric models for security-critical airport applications. These systems process sensor data locally at terminal gates and runway zones, eliminating round-trip latency to remote servers. Major hub operators in the United States are deploying edge nodes for instantaneous baggage sortation decisions. The shift is compressing vendor competitive advantage toward hardware-software integration capability rather than pure cloud scale.
EASA's regulatory guidance on connected airside equipment is reshaping procurement standards for ground handlers across Europe. The framework mandates cybersecurity hardening and interoperability testing before operational deployment. Ground handling contractors in Germany and France are restructuring supplier qualification processes to meet these requirements. Equipment vendors must now certify against both EASA protocols and national aviation authority supplements.
Buyer procurement patterns are fragmenting as airport authorities unbundle integrated IoT contracts into component-level competitions. Terminal operators in Japan and South Korea are separately sourcing sensors, networking infrastructure, and analytics platforms rather than accepting single-vendor stacks. This disintermediation favors specialized sensor manufacturers and software houses over full-system integrators. The shift is most visible in greenfield terminal projects where legacy vendor relationships carry less weight.
Airport Internet of Things Market Segmentation
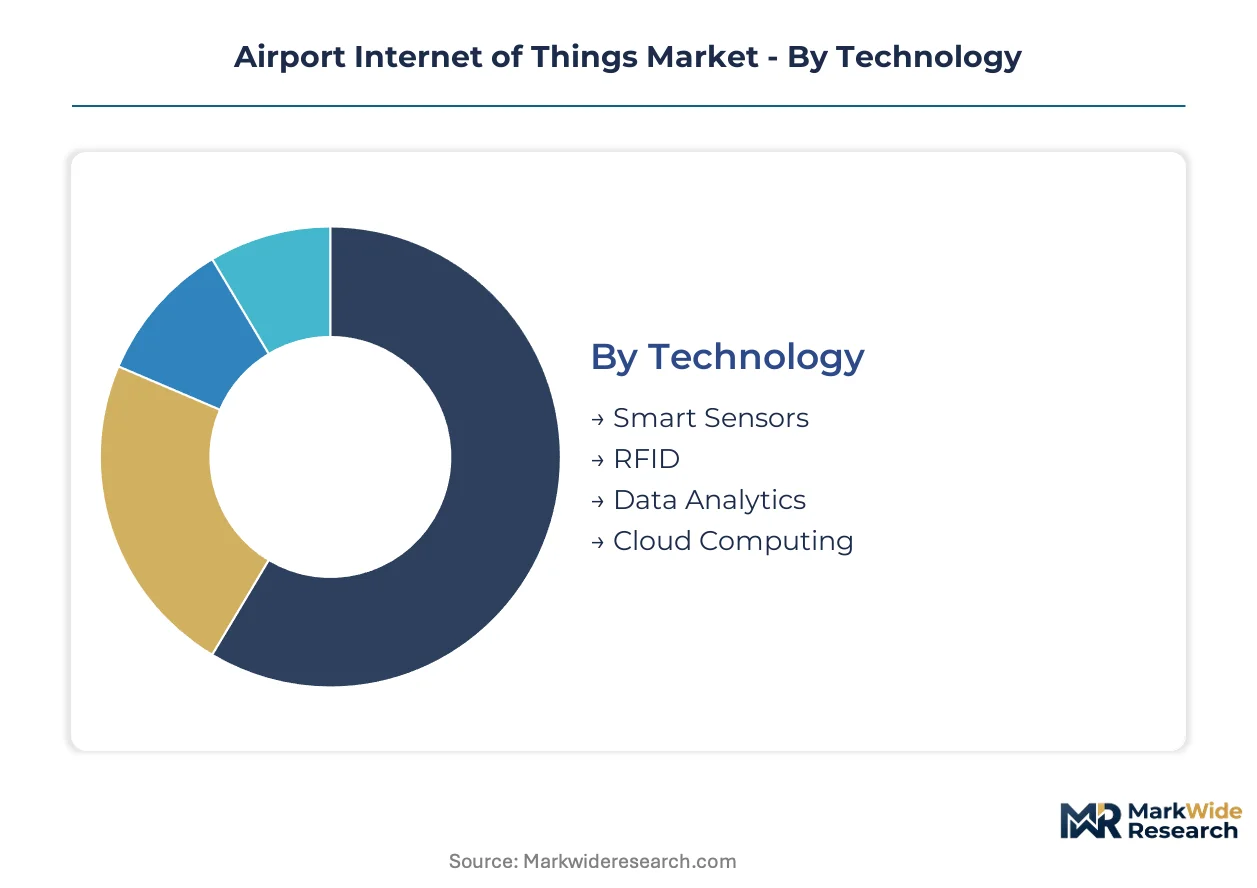
Airport IoT procurement splits sharply between capital-heavy infrastructure overhauls and modular software deployments. Understanding where upfront investment concentrates helps vendors align their go-to-market timing with airport budget cycles and regulatory compliance windows.
Technology:
Smart Sensors and Cloud Computing demand the heaviest capital commitment, with sensor networks requiring extensive physical installation and cloud platforms needing redundant connectivity infrastructure.
- Smart Sensors:Aviation-grade hardware integrates environmental, motion, and proximity detection for real-time terminal monitoring. German and Japanese manufacturers are expanding foundry capacity to serve hub airports in the United States retrofitting aging facilities with integrated arrays.
- RFID:Radio-frequency identification tags and readers enable automated baggage tracking through sortation tunnels and gate zones. Ground handlers across North America are deploying these systems to cut mishandled luggage rates and avoid compensation liabilities.
- Data Analytics:Predictive algorithms process operational streams for maintenance scheduling and passenger flow optimization.
- Cloud Computing:Centralized data storage and processing platforms eliminate on-premises server requirements. Mid-sized airports in Spain and Italy are migrating here to escape capital-intensive infrastructure ownership.
Most installed capacity flows through Smart Sensors. Expansion is steepest in Cloud Computing.
Application:
Facility Management and Security Management absorb the largest share of recurring operational expenditure, as these applications run continuously rather than episodically.
- Passenger Experience:Queue management, wayfinding, and personalized notification systems reduce terminal congestion. Hub operators in the United States are prioritizing these deployments to modernize aging infrastructure and meet traveler expectations.
- Baggage Tracking:End-to-end luggage monitoring from check-in to reclaim cuts loss rates and insurance claims. The EU Green Deal is pressuring European airports to integrate these systems with energy-efficient IoT infrastructure for terminal operations.
- Security Management:Perimeter intrusion detection, access control, and video analytics protect airside zones. Edge Computing serves these applications with sub-millisecond response requirements.
- Facility Management:HVAC, lighting, and energy optimization through building automation. Honeywell International Inc. sustains leadership here with systems tailored for terminal environments.
Facility Management commands the largest current installed base. Baggage Tracking is climbing the fastest as ground handlers restructure operations.
End User:
Aeronautical Authorities and Ground Handlers face the steepest procurement complexity, as both must satisfy multi-layered regulatory certification before operational deployment.
- Aeronautical Authorities:National aviation regulators mandate cybersecurity frameworks and interoperability standards. EASA's guidance on connected airside equipment shapes procurement across Europe, extending vendor qualification timelines.
- Airlines:Carriers invest in passenger-facing IoT for loyalty differentiation and operational efficiency.
- Ground Handlers:Contractors manage baggage, cargo, and aircraft servicing equipment. These operators are expanding adoption of connected handling systems to reduce operational losses and meet airline service level agreements.
- Retail Operators:Duty-free and concession vendors deploy footfall analytics and inventory tracking. Terminal commercial managers in Japan and South Korea are separately sourcing these solutions rather than accepting airport-wide integrated stacks.
Ground Handlers account for the most sensor nodes currently active. Aeronautical Authorities are expanding procurement fastest as regulatory mandates harden.
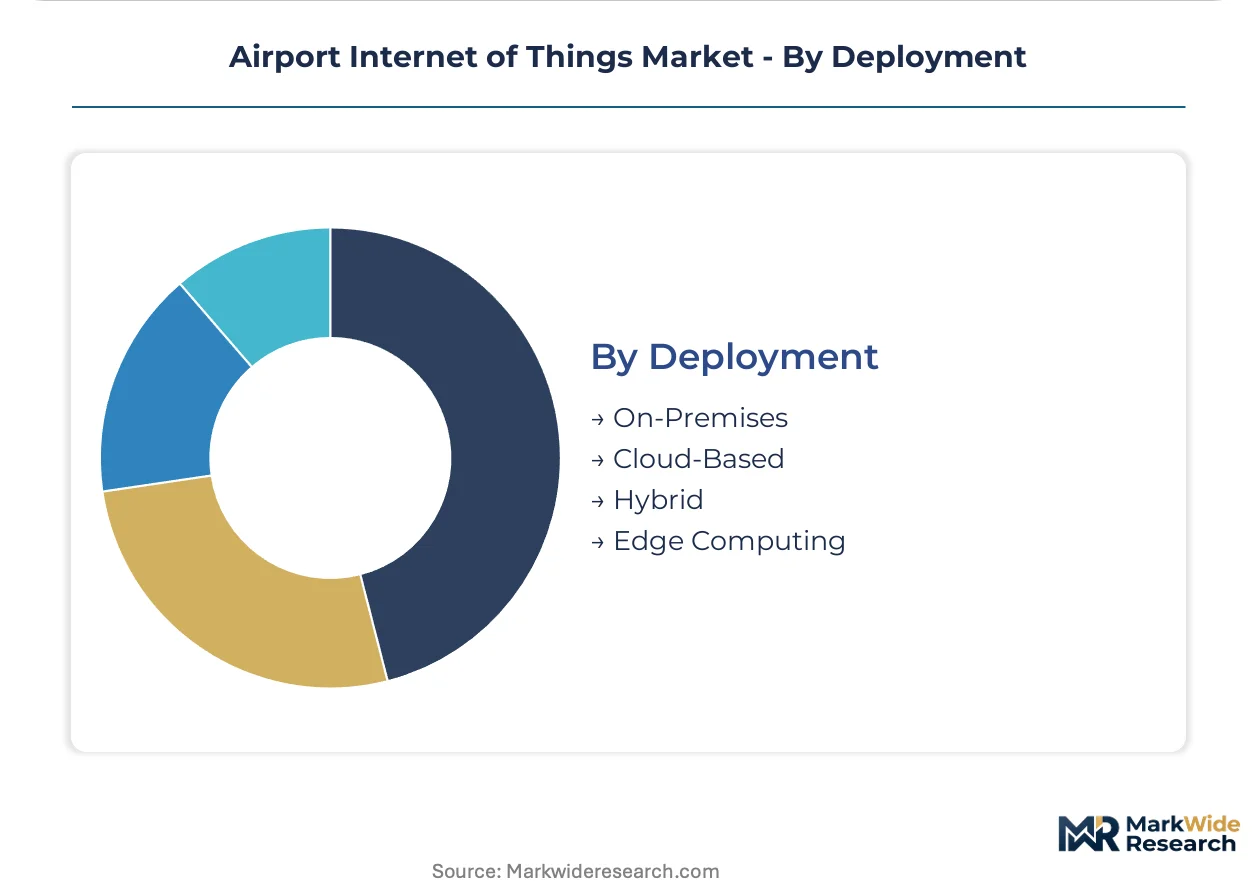
Deployment:
Hybrid and Edge Computing architectures impose the most complex integration burden, requiring simultaneous management of legacy protocols and low-latency local processing.
- On-Premises:Dedicated server infrastructure within airport data centers. Large hub operators with existing IT estates continue maintaining these for sensitive operational systems.
- Cloud-Based:Third-party hosted platforms with subscription pricing. ISO/IEC 27001 compliance has become baseline for contracts here, extending vendor qualification periods.
- Hybrid:Mixed architectures bridging legacy and modern infrastructure. FAA-mandated cybersecurity frameworks for operational networks push operators toward certified hybrid configurations.
- Edge Computing:Localized processing at terminal gates and runway zones eliminates round-trip latency. Major hub operators in the United States are deploying edge nodes for instantaneous baggage sortation and airside safety decisions.
Hybrid deployments dominate current infrastructure. Edge Computing is gaining share fastest as latency requirements harden for security-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting IoT deployment patterns as airports in jurisdictions with lighter certification burdens accelerate procurement ahead of stricter mandates elsewhere. Production of aviation-grade sensors concentrates where compliance costs remain manageable.
United States
Major hub airports in Atlanta, Dallas-Fort Worth, and Chicago are modernizing aging facilities with integrated sensor networks for baggage tracking and passenger flow optimization. The FAA mandates cybersecurity frameworks for operational networks, pushing operators toward certified IoT architectures that extend vendor qualification timelines. Dallas-Fort Worth International Airport anchors domestic deployment activity with edge computing nodes for sub-millisecond safety decisions.
Germany
Sensor manufacturers in Munich and Stuttgart are expanding foundry capacity to serve European retrofit demand driven by EU Green Deal carbon reduction targets. EASA's regulatory guidance on connected airside equipment shapes procurement standards for ground handlers, requiring cybersecurity hardening before operational deployment. Frankfurt Airport exemplifies integrated facility management platforms combining edge computing with smart sensor arrays.
Japan
Terminal operators in Tokyo and Osaka are separately sourcing sensors, networking infrastructure, and analytics platforms rather than accepting single-vendor stacks. METI standards on industrial IoT interoperability influence aviation procurement specifications for domestic deployments. Kansai International Airport leads unbundled contracting approaches in greenfield terminal projects.
United Kingdom
Heathrow and Gatwick are deploying private 5G networks to enable real-time baggage tracking and reduce mishandled luggage compensation liabilities. UK aviation regulators align with EASA protocols while maintaining national supplements for cybersecurity certification. London's terminal cluster represents the densest concentration of cloud migration activity among mid-sized European airports.
South Korea
Incheon International Airport drives demand for predictive maintenance algorithms processing operational streams from ground support equipment. MFDS-equivalent national standards on connected infrastructure shape vendor qualification for airside deployments. Seoul's aviation cluster concentrates procurement for passenger experience systems including queue management and personalized notification platforms.
Airport Internet of Things Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in edge analytics and specialized sensor hardware. The vendor base stratifies between full-system integrators and component specialists as procurement fragmentation accelerates. Three archetypes dominate: networking infrastructure providers, building automation specialists, and enterprise software houses. Competitive moves concentrate on strategic partnerships bridging hardware-software gaps and geographic expansion into mid-sized airport segments.
Within the networking infrastructure tier, Cisco Systems, Inc. and Huawei Technologies Co. Ltd. exemplify scale-driven positioning for connectivity deployments. Honeywell International Inc. and Siemens AG occupy the building automation archetype with integrated facility management platforms. IBM Corporation and Microsoft Corporation represent enterprise software houses anchoring cloud and analytics layers. These six entities collectively illustrate the competitive structure without exhausting participant diversity.
| Leading Market Players |
|---|
| IBM Corporation |
| Amadeus IT Group |
| Honeywell International Inc. |
| SITA |
| SAP SE |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| Siemens AG |
| Huawei Technologies Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal mandates energy-efficiency thresholds for terminal IoT infrastructure, creating a dual gate that restricts qualified supply to certified German and Japanese sensor manufacturers while enabling premium-tier pricing for aviation-grade hardware meeting EASA cybersecurity protocols.
Pricing Analysis
Distributor margins compress pricing realization for component vendors selling through systems integrators, while direct-to-airport contracts command 15-25 point premiums. Three-tier pricing structure across aviation-certified, industrial-grade, and commercial-off-the-shelf levels separates ground handlers with airline SLA exposure from mid-sized airports prioritizing capital avoidance. Pricing pressure stems from capacity constraints at German and Japanese foundries extending lead times for LoRaWAN and 5G-enabled sensor modules. Ground handlers facing mishandled luggage compensation liabilities prove least price-sensitive; mid-sized airports in Spain and Italy migrating to cloud deployments exhibit highest elasticity.
Supply Chain Analysis
Reverse logistics for aviation-grade sensors involves certified refurbishment flows back to Munich and Stuttgart facilities, where EASA-mandated interoperability testing extends remanufacturing cycles. Component supply concentrates in Germany, Japan, and Taiwan, with semiconductor foundries in Hsinchu and Taichung feeding sensor packaging operations in Osaka. Raw material dependencies span gallium arsenide for RF modules, rare earth elements for precision magnetometers, and high-purity silicon substrates. Single-source vulnerability runs through Taiwanese wafer fabrication for edge computing chipsets. Distribution runs through specialized aviation electronics distributors holding FAA and EASA parts supplier certifications rather than broad-line component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Airport Internet of Things Market functions as a regulatory compounder where FAA cybersecurity framework mandates and EU Green Deal carbon thresholds create successive demand waves for certified infrastructure replacement.
For Market Incumbents: Hedge against procurement fragmentation by acquiring specialized sensor software houses in Japan and South Korea where unbundled contracting accelerates. Cisco Systems and Honeywell International should deepen backward integration into aviation-grade edge computing chipsets to offset Taiwanese foundry concentration risk. Certification investment in ISO/IEC 27001 and EASA protocols remains the critical defensive lever as qualification timelines extend vendor lock-in. For New Entrants and Emerging Players: Launch via cloud-native SaaS platforms targeting mid-sized airports in Italy and Spain seeking escape from capital-intensive on-premises infrastructure ownership. The most penetrable white space sits in predictive maintenance algorithms for ground support equipment, where margin pools concentrate around real-time decision engines lacking incumbent dominance. Partner with ground handlers facing airline SLA pressure rather than competing for aeronautical authority procurement directly. For Investors and Strategic Acquirers: Roll-up economics work for specialized edge analytics vendors because EASA and FAA certification requirements create artificial scarcity that protects acquired revenue streams from pure-software competition. Platform consolidation across sensor hardware, networking infrastructure, and analytics layers offers 5-10 year viability as hybrid architectures become default. Monitor private 5G deployment velocity at Dallas-Fort Worth and Heathrow as the inflection signal for infrastructure upgrade cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aviation-Grade Sensor Foundry Expansion | German and Japanese manufacturers are adding capacity to serve EU Green Deal retrofit demand. |
| Private 5G Network Deployment | Major US hub airports are building low-latency infrastructure for real-time baggage tracking. |
| Edge Computing Node Installation | Dallas-Fort Worth anchors domestic deployment for sub-millisecond safety decisions. |
| Cloud Migration Partnership | Mid-sized airports in Spain and Italy are escaping capital-intensive server ownership. |
| Predictive Maintenance Algorithm Development | Ground handlers are restructuring operations around real-time equipment monitoring. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airport CIOs, ground handling operations directors, EASA certification specialists, and aviation electronics procurement managers with secondary validation against FAA regulatory filings, EASA guidance documents, EU Green Deal implementation reports, and customs trade data for aviation-grade sensor imports. Bottom-up sensor deployment counts triangulated against top-down infrastructure spending estimates across the analysis window.
Segment-weighting approaches distributed value projections across technology type, application function, end-user archetype, and deployment architecture dimensions. CAGRs derived from fitted growth curves incorporating private 5G rollout schedules, EU carbon reduction milestone enforcement, and ground handler SLA restructuring timelines. Forecast inputs included baggage mishandling rate trajectories, edge computing latency requirement evolution, and cloud migration adoption curves among mid-tier airports.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or Taiwan semiconductor supply disruption scenarios. Practitioners should monitor EASA protocol amendment cycles and private 5G spectrum allocation decisions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Cellular Internet of Things (IoT) Devices Market
Internet of Things (IoT)
UK IoT Software Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Global Embedded Security for Internet of Things Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
IoT Integration Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
IoT Middleware Market
Internet of Things (IoT)
Edge Computing in IoT Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
North America IoT Node and Gateway Market