
 Diisostearyl Fumarate Market | 2026-2036
Diisostearyl Fumarate Market Size, Share, and Industry Trends Forecast 2026-2036
Diisostearyl Fumarate Market Analytics
ISO 16128 natural origin certification is collapsing the supplier base for premium-grade diisostearyl fumarate, forcing raw material vendors to demonstrate biomass-derived feedstock traceability. Croda International Plc leverages its botanical ester portfolio to sustain leadership in clean-label cosmetic ingredients. BASF SE anchors its position through integrated fumaric acid supply chains that reduce batch-to-batch variability. Evonik Industries AG differentiates via high-purity liquid grades tailored for lipophilic active delivery systems.
Diisostearyl fumarate is a diester synthesized from fumaric acid and isostearyl alcohol, functioning as an emollient, film-former, and pigment dispersant with a molecular weight typically exceeding 600 g/mol and a melting point below 25°C for liquid variants. The compound serves primarily as a texture modifier in anhydrous and water-in-oil formulations where spreadability and wear resistance determine consumer acceptance. Cosmetics applications dominate value contribution due to premium positioning of long-wear makeup and skin-conditioning treatments. The powder and granule forms command higher processing margins as they enable cold-process manufacturing favored by indie formulators seeking energy savings.
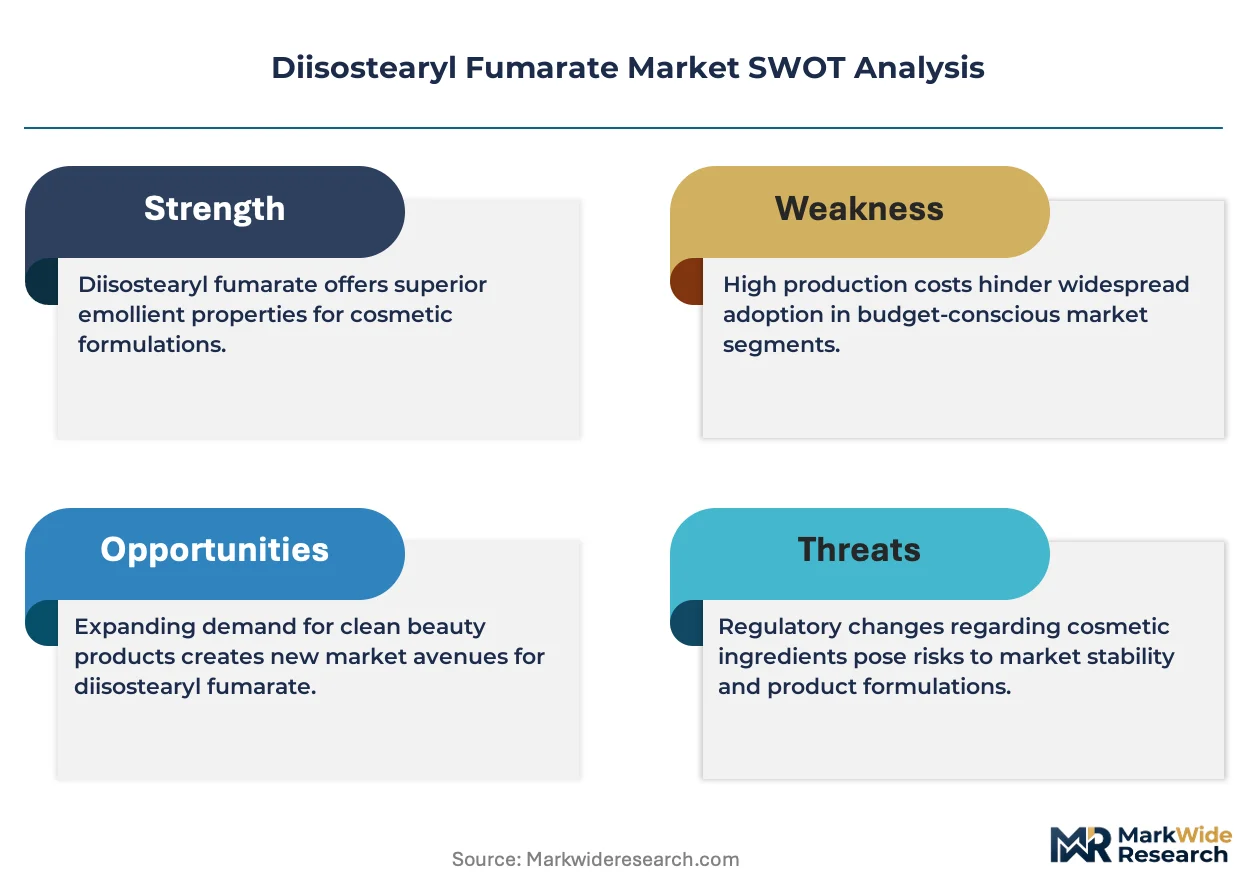
REACH registration requirements in the European Union, FDA cosmetic ingredient oversight in the United States, and China's GB standards for imported cosmetic raw materials collectively elevate compliance costs for cross-border suppliers. These frameworks increasingly mandate safety data dossiers and manufacturing process disclosures that smaller ester producers struggle to assemble. Stakeholders must monitor evolving natural-origin claim definitions across regulatory jurisdictions to anticipate which purity grades will retain premium positioning.
Market Dynamics
ISO 16128 natural origin certification requirements are compressing the supplier base for cosmetic-grade diisostearyl fumarate, forcing raw material vendors to demonstrate biomass-derived feedstock traceability or exit premium segments entirely.
Growth Catalysts
- K-beauty manufacturing corridor:South Korean cosmetics formulators around Seoul are expanding cold-process anhydrous color cosmetic lines that rely on diisostearyl fumarate for pigment dispersion and wear resistance.
- REACH purity benchmarks:ECHA's tightening cosmetic-grade fumarate ester specifications are eliminating low-purity competitors and consolidating demand among certified suppliers capable of sub-ppm impurity control.
- Lipophilic active delivery systems:Pharmaceutical and dermocosmetic developers are adopting high-purity liquid grades as solubilizers for oil-soluble vitamins and UV filters in water-in-oil emulsions.
Market Restraints
- Isostearyl alcohol feedstock volatility:Branched-chain fatty alcohol supply concentrates among Southeast Asian oleochemical processors, exposing formulators to palm kernel oil price swings and biodiesel policy competition for feedstock allocation.
- Fumaric acid supply concentration:Integrated petrochemical producers control the majority of food-grade and polymer-grade fumaric acid, limiting merchant market liquidity for specialty ester manufacturers lacking backward integration.
- Silicone ester substitution threat:Alkyl-modified silicone esters from Dow and Shin-Etsu compete directly in long-wear makeup applications, offering equivalent spreadability with lower surface tension and reduced tack.
Strategic Opportunities
- Indian dermocosmetics expansion:CDSCO's streamlined cosmetic ingredient notification pathway and BIS adoption of ISO 16128 standards are enabling premium-grade diisostearyl fumarate penetration into Ayurveda-inspired skincare formulations targeting domestic and export markets.
- Biomass-derived certification premium:EU Green Deal sustainable chemistry incentives and France's AGEC law on product environmental labeling are creating price premiums for esters with verified renewable carbon content and mass-balance chain of custody.
- Indie formulator channel:Direct-to-brand raw material platforms and small-batch cosmetic manufacturing cooperatives are bypassing traditional distributor markups, enabling specialty ester producers to capture margin previously allocated to regional chemical distributors.
Industry Challenges
- Analytical method standardization:Absence of harmonized ISO or Pharmacopeia test methods for diisostearyl fumarate purity and isomer ratio forces suppliers to maintain multiple analytical protocols for different regulatory jurisdictions, inflating quality control headcount and equipment costs.
- Cold-chain logistics fragility:Liquid-grade variants require temperature-controlled transport below 25°C to prevent oxidative degradation and color drift, complicating last-mile delivery to small-scale formulators lacking refrigerated receiving infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diisostearyl Fumarate Market |
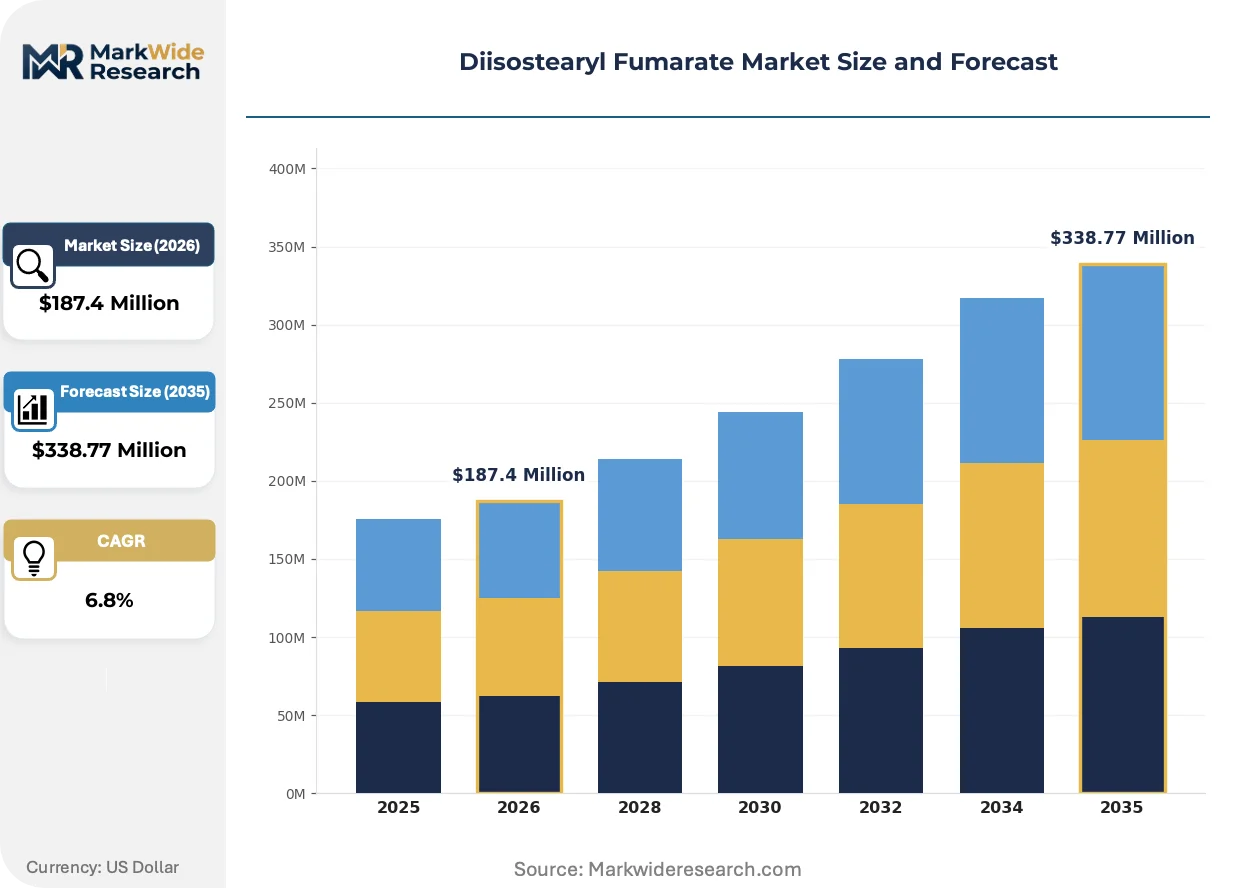
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Personal Care, Pharmaceuticals, Industrial Additives End Use: Skincare, Haircare, Makeup, Formulations Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesale Form: Liquid, Powder, Granule, Paste |
| Companies Covered | Croda International Plc, Lubrizol Corporation, Kobo Products Inc., Ashland Inc., BASF SE, Solvay S.A., Sensient Technologies Corporation, Evonik Industries AG, Alzo International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diisostearyl Fumarate Market Evolving Landscape
Biomass traceability systems and enzymatic esterification processes are converging to redefine competitive advantage in cosmetic-grade specialty esters, separating suppliers with verified renewable supply chains from commodity producers.
Enzymatic esterification using immobilized lipase biocatalysts is supplanting traditional acid-catalyzed processes for high-purity diisostearyl fumarate production. European and Japanese cosmetic ingredient suppliers are scaling these routes to meet ISO 16128 natural origin thresholds. The technology is enabling batch-specific carbon-14 dating certificates that command 15-30% price premiums over petrochemical-derived equivalents.
REACH Annex XVII restrictions on microplastics in rinse-off cosmetics are accelerating demand for biodegradable film-forming alternatives. ECHA's 2023-2024 restriction proposals explicitly exclude certain synthetic esters from microplastic definitions based on biodegradability screening data. German and French formulators are reformulating mascara and lipstick lines to incorporate compliant diesters ahead of enforcement deadlines.
Direct raw material procurement from certified bio-refineries is compressing traditional distributor layers in the value chain. Indie cosmetics brands and contract manufacturers in California and Seoul are establishing preferred supplier agreements with Malaysian and Indonesian oleochemical producers. This disintermediation is most visible in the K-beauty export segment, where lead times from feedstock to finished formulation have compressed from 90 days to under 45 days.
Diisostearyl Fumarate Market Segmentation
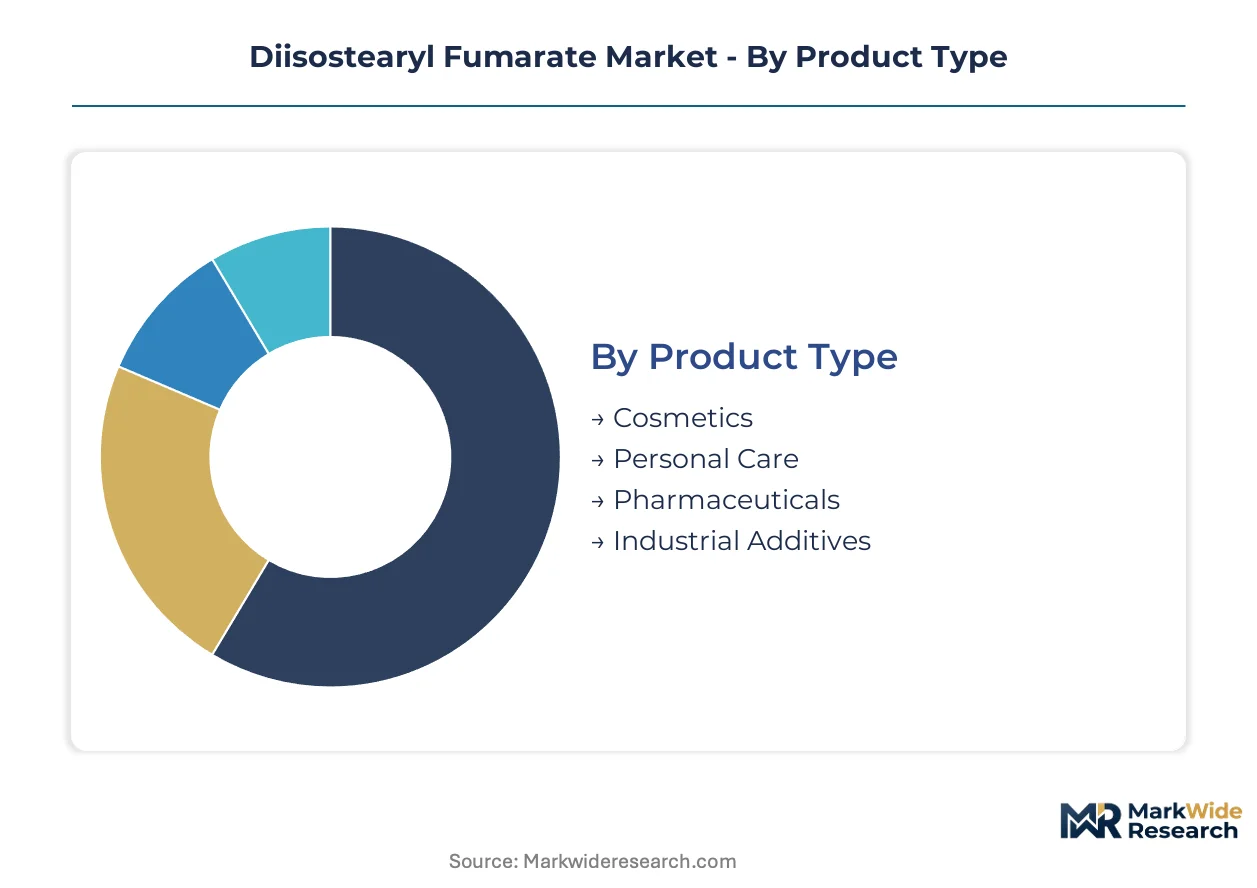
Segmentation in diisostearyl fumarate markets exposes where silicone ester substitutes threaten incumbent positions and where biomass certification creates defensive moats. Understanding these fault lines enables suppliers to prioritize R&D investment and distribution partnerships.
Product Type:
Cosmetics applications face the most acute substitution pressure from alkyl-modified silicone esters in long-wear color formulations, forcing diisostearyl fumarate suppliers to differentiate through ISO 16128 natural origin credentials.
- Cosmetics:Long-wear makeup and anhydrous color cosmetic formulations demand liquid grades with sub-ppm impurity profiles. Seoul-based K-beauty manufacturers are expanding cold-process lines that rely on this ester for pigment dispersion and transfer resistance, though Dow and Shin-Etsu silicone alternatives compete aggressively on surface tension performance.
- Personal Care:Skin-conditioning treatments and water-in-oil emulsions utilize high-purity grades as texture modifiers. Indian dermocosmetic brands adopting Ayurveda-inspired positioning are driving uptake of biomass-certified variants through CDSCO's streamlined notification pathway.
- Pharmaceuticals:Lipophilic active delivery systems for oil-soluble vitamins and UV filters require pharmaceutical-grade liquid esters with documented isomer ratios.
- Industrial Additives:Polymer processing aids and lubricant applications consume standard-grade material with less stringent purity requirements.
Cosmetics retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
End Use:
Cost tier stratification separates premium skincare formulations from mass-market haircare, with makeup applications commanding the widest price spreads based on wear-resistance performance.
- Skincare:Premium facial oils and dermocosmetic treatments specify liquid diisostearyl fumarate for spreadability and skin-feel modulation. French formulators responding to AGEC environmental labeling requirements are reformulating with mass-balance certified esters to capture green chemistry premiums.
- Makeup:Anhydrous foundations, lipsticks, and mascaras depend on this diester for film-forming and transfer resistance. ECHA's REACH Annex XVII microplastic restrictions are accelerating demand for biodegradable alternatives ahead of enforcement deadlines.
- Haircare:Conditioning agents and styling products incorporate lower-cost grades where silicone competitors already dominate.
- Formulations:Contract manufacturers serving multiple end-use categories blend standardized base materials with performance additives.
Makeup dominates value contribution; Skincare is expanding most quickly on natural-origin positioning.
Distribution Channel:
Customer type fragmentation between indie formulators and multinational manufacturers is compressing traditional distributor layers, with direct procurement gaining share fastest among small-batch producers.
- Online Retail:Direct-to-brand raw material platforms enable specialty ester producers to bypass regional chemical distributors and capture margin previously allocated to intermediaries. California-based indie cosmetics brands are establishing preferred supplier agreements through these channels.
- Wholesale:Large-volume contracts with integrated oleochemical producers dominate supply to major cosmetics manufacturers. Malaysian and Indonesian bio-refineries are compressing lead times from feedstock to finished formulation through these relationships.
- Specialty Stores:Regional distributors serving mid-tier formulators maintain inventory of standard purity grades.
- Pharmacies:Dermocosmetic and pharmaceutical-grade materials reach compounding pharmacies through licensed intermediaries with cold-chain capabilities.
Wholesale maintains volume dominance; Online Retail is climbing the fastest on disintermediation trends.
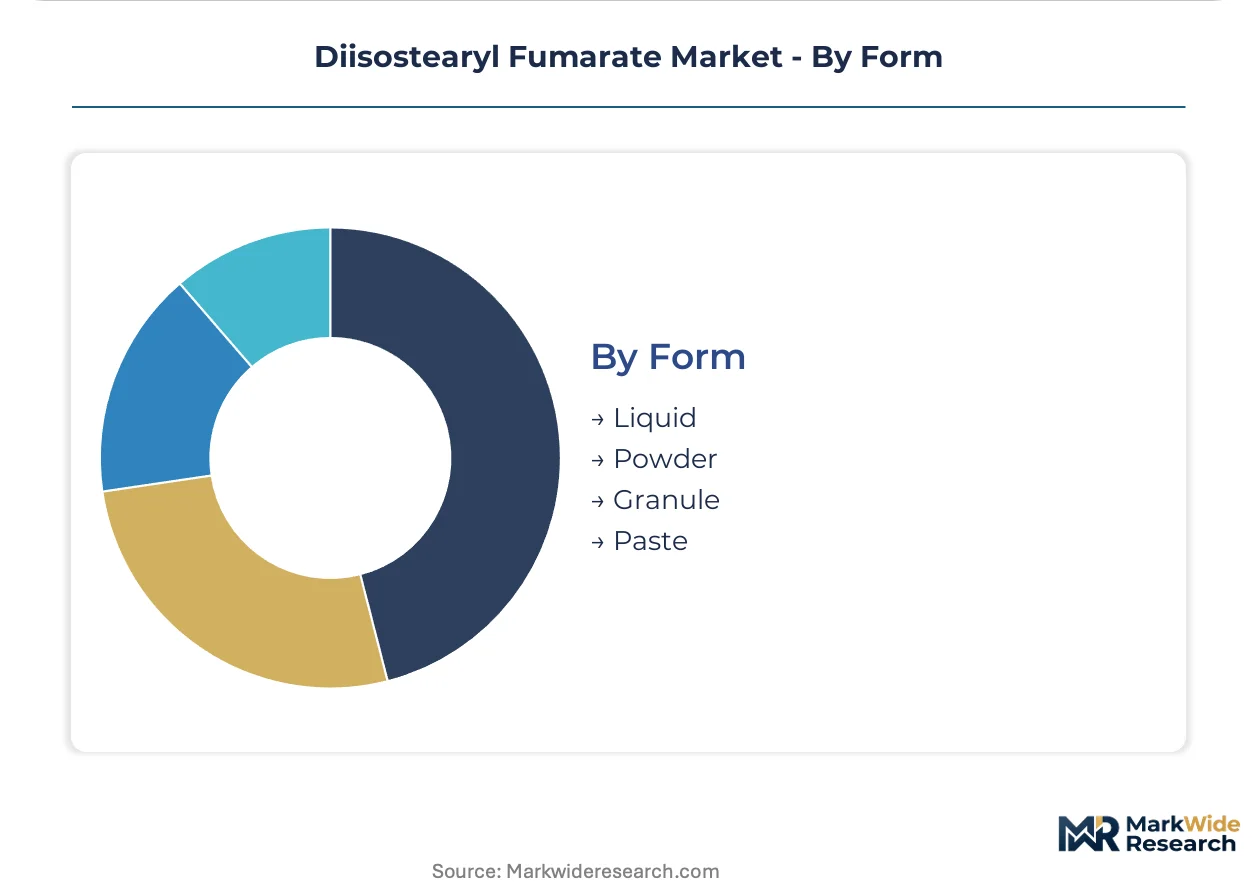
Form:
Supply concentration in liquid-grade production creates margin pressure for powder and granule variants, where cold-process manufacturing demand from energy-conscious formulators sustains premium positioning.
- Liquid:The predominant commercial form for anhydrous and water-in-oil formulations, requiring temperature-controlled transport below 25°C to prevent oxidative degradation. Evonik Industries and BASF SE anchor supply through integrated fumaric acid chains and high-purity processing capabilities.
- Powder:Cold-process manufacturing favored by indie formulators drives demand for solid variants that eliminate heating steps. Energy savings and equipment simplification justify 15-30% price premiums over liquid equivalents in this segment.
- Granule:Free-flowing granules enable precise dosing in automated compounding systems for large-scale manufacturers.
- Paste:Semi-solid concentrates serve niche applications requiring thixotropic behavior.
Liquid retains volume leadership; Powder holds the steepest expansion curve on cold-process adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainable chemistry incentives and France's AGEC law on product environmental labeling are redirecting procurement toward biomass-certified esters. South Korea's K-beauty manufacturing corridor around Seoul is compressing lead times from feedstock to finished formulation. India's CDSCO streamlined notification pathway is enabling premium-grade penetration into Ayurveda-inspired skincare.
South Korea
Seoul-based cosmetics formulators are expanding cold-process anhydrous color cosmetic lines that rely on diisostearyl fumarate for pigment dispersion and transfer resistance. MFDS cosmetic ingredient oversight aligns with ISO 16128 standards for natural origin claims. The Gyeonggi-do province manufacturing belt is attracting direct procurement agreements with Malaysian oleochemical producers.
France
French formulators responding to AGEC environmental labeling requirements are reformulating with mass-balance certified esters to capture green chemistry premiums. ECHA's REACH Annex XVII microplastic restrictions are accelerating demand for biodegradable film-forming alternatives ahead of enforcement deadlines. The Île-de-France region hosts contract manufacturers serving premium skincare brands seeking verified renewable carbon content.
United States
California-based indie cosmetics brands are establishing preferred supplier agreements through direct-to-brand raw material platforms. FDA cosmetic ingredient oversight maintains safety data dossier requirements that favor established suppliers with documented manufacturing process disclosures. The Los Angeles-Orange County metro area concentrates small-batch formulators bypassing traditional distributor markups.
India
Domestic dermocosmetic brands adopting Ayurveda-inspired positioning are driving uptake of biomass-certified variants through CDSCO's streamlined notification pathway. BIS adoption of ISO 16128 standards enables premium-grade penetration into formulations targeting export markets. Maharashtra's Mumbai-Pune industrial corridor anchors contract manufacturing for both domestic consumption and Middle East exports.
Germany
German chemical suppliers are scaling enzymatic esterification routes using immobilized lipase biocatalysts to meet ISO 16128 natural origin thresholds. ECHA's tightening cosmetic-grade fumarate ester specifications are eliminating low-purity competitors and consolidating demand among certified suppliers. The North Rhine-Westphalia region concentrates specialty ester production facilities with integrated quality control laboratories.
Diisostearyl Fumarate Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public companies leveraging integrated supply chains against private firms emphasizing boutique biomass traceability. The supplier base compresses as ISO 16128 natural origin requirements force raw material vendors to demonstrate feedstock traceability or exit premium segments. Three archetypes dominate: integrated petrochemical majors with captive fumaric acid supply, botanical ester specialists with verified renewable chains, and regional oleochemical processors serving price-sensitive industrial grades. Competitive moves center on backward integration into isostearyl alcohol feedstock and enzymatic process licensing to secure natural-origin certification.
Within the integrated petrochemical tier, BASF SE and Evonik Industries AG exemplify players with in-house production of fumaric acid that reduces batch-to-batch variability. Croda International Plc occupies a position among botanical ester specialists leveraging biomass-derived feedstock traceability for clean-label positioning. Lubrizol Corporation sits within the performance additives archetype, representing private specialists with formulation science capabilities. These three anchors illustrate how certification requirements are separating suppliers with verified renewable supply chains from commodity producers.
| Leading Market Players |
|---|
| Croda International Plc |
| Lubrizol Corporation |
| Kobo Products Inc. |
| Ashland Inc. |
| BASF SE |
| Solvay S.A. |
| Sensient Technologies Corporation |
| Evonik Industries AG |
| Alzo International |
| Others |
Value Network & Pricing Analysis
Capacity utilization at integrated fumaric acid producers anchors price floors across all certification tiers, compressing margins for non-integrated specialty ester manufacturers while concentrating supply power among backward-linked suppliers in Germany and China.
Pricing Analysis
Certification level creates the primary spread between premium and standard grades, with ISO 16128 natural-origin verification commanding 15-30% premiums over petrochemical-derived equivalents. Pricing stratifies across biomass-certified, REACH-compliant, and industrial-grade tiers based on impurity thresholds and carbon-14 traceability documentation. Cost compression in standard industrial grades is intensifying because Southeast Asian oleochemical processors compete aggressively on isostearyl alcohol supply contracts. Indie formulators and small-batch cosmetics manufacturers exhibit the highest price sensitivity, while K-beauty exporters and French premium skincare houses prioritize certification integrity over unit cost.
Supply Chain Analysis
Malacca Strait transit routes underpin feedstock flows from Indonesian and Malaysian palm kernel oil refineries to specialty ester producers, creating logistics exposure that amplifies during monsoon shipping disruptions. Manufacturing concentrates in Germany, South Korea, and China, with German facilities specializing in enzymatic high-purity grades and Chinese plants dominating standard industrial volumes. Feedstock supply draws from fumaric acid merchants and isostearyl alcohol oleochemical processors, with limited backward integration outside BASF and Evonik. Single-source vulnerability concentrates in Southeast Asian branched-chain fatty alcohol supply, where biodiesel policy competition constrains cosmetic-grade allocation. Distribution runs through direct procurement agreements with K-beauty manufacturers and wholesale contracts serving European formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among K-beauty contract manufacturers and California indie formulators, fragmenting traditional distributor influence and compressing margin capture for non-certified suppliers.
For Market Incumbents: Shield premium positioning by deepening backward integration into isostearyl alcohol feedstock through Malaysian bio-refinery partnerships, and accelerate enzymatic process licensing to defend against silicone ester substitution from Dow and Shin-Etsu in long-wear makeup applications.
For New Entrants and Emerging Players: Anchor in India's dermocosmetics segment where CDSCO's streamlined notification pathway and Ayurveda-inspired brand positioning create white-space penetration opportunities, leveraging direct-to-brand raw material platforms to bypass established distributor layers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among botanical ester specialists with verified renewable carbon content and mass-balance chain of custody, positioning these assets for long-term viability as EU Green Deal incentives harden. Acquisition focus should target mid-cap producers with enzymatic capability gaps that integrated majors need to fill. The signal to watch is ECHA's REACH Annex XVII enforcement timeline for microplastic restrictions, which will accelerate demand inflection for biodegradable film-forming alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isostearyl Alcohol | Captive feedstock supply from Malaysian bio-refineries insulates against palm kernel oil price volatility and biodiesel policy competition. |
| Enzymatic Esterification Scale-Up | Immobilized lipase biocatalyst routes enable ISO 16128 natural-origin certification that commands premium positioning in EU and K-beauty markets. |
| Direct-to-Brand Platform Expansion | Bypassing regional chemical distributors captures margin previously allocated to intermediaries in California and Seoul indie formulator channels. |
| Mass-Balance Chain of Custody Certification | Verified renewable carbon content documentation satisfies France's AGEC law and EU Green Deal sustainable chemistry incentive requirements. |
| Cold-Chain Logistics Infrastructure | Temperature-controlled transport below 25°C prevents oxidative degradation in liquid-grade variants delivered to small-scale formulators. |
Research Methodology
Cross-validation between primary interviews with cosmetic formulators, oleochemical procurement managers, and regulatory affairs specialists and secondary sources including ECHA REACH registration databases, CDSCO cosmetic ingredient notifications, and SEC filings from listed specialty chemical producers anchors the qualitative findings. Bottom-up volume estimates from end-use consumption patterns triangulate against top-down supply-side capacity assessments across German, South Korean, and Chinese manufacturing facilities.
Sensitivity analysis around isostearyl alcohol feedstock price scenarios and REACH enforcement timelines shapes the analytical framework across the analysis window. Segmentation dimensions modeled include certification grade tier, end-use application, form factor, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand projections incorporating K-beauty export growth rates and Indian dermocosmetics penetration curves. Industry-specific forecast inputs capture enzymatic process adoption rates and biomass certification premium sustainability.
Material uncertainties — palm kernel oil commodity volatility, ECHA microplastic restriction enforcement timing, and silicone ester substitution acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU Green Deal incentive structures and K-beauty manufacturing corridor expansion patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Sodium Stearoyl Lactylate Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Global Emollient Esters Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
Stearyl Tartrate Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Oily Waste Cans Market