
 Fatty Acid Amides Market | 2026-2036
Fatty Acid Amides Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Acid Amides Market Analysis
The EU Green Deal is restructuring procurement criteria across European polymer supply chains, forcing compounders to certify bio-based content in processing aids. Kao Corporation leverages its oleochemical heritage to dominate Asia-Pacific supply routes for erucamide slip agents. BASF sustains R&D intensity in amide derivatives for engineered plastics, while Croda International Plc anchors European demand through certified mass-balance supply chains.
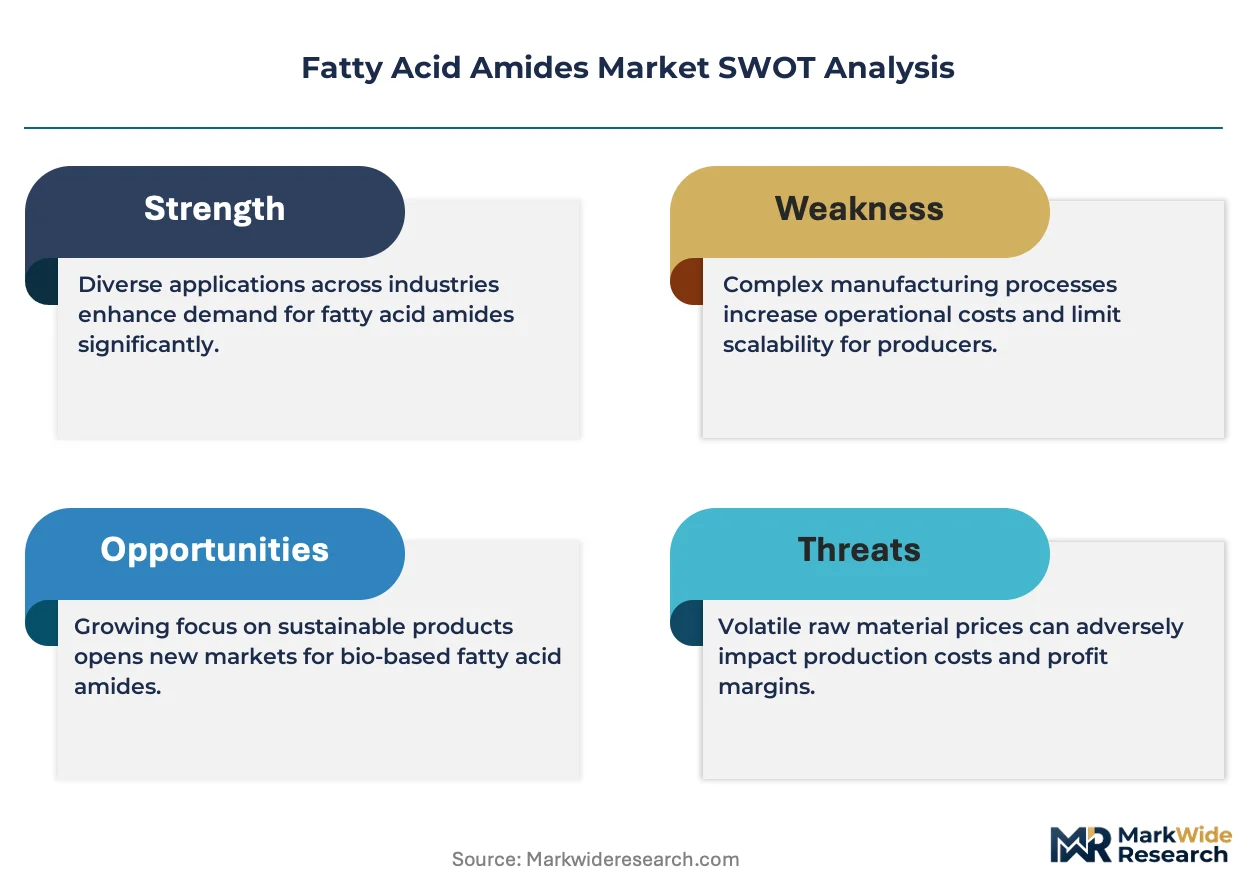
Fatty acid amides comprise long-chain carboxylic acid derivatives reacted with ammonia or primary amines, typically ranging from C12 to C22 chain lengths, functioning primarily as lubricants, slip agents, and anti-block additives in polymer films and molded parts. Monoamides occupy the largest volume share due to their cost-efficiency in polyethylene extrusion, whereas ethanolamides gain ground in personal care emulsification where mildness credentials command premium positioning. Diamides retain niche but high-margin roles in engineering polymer processing where thermal stability requirements exclude simpler chemistries.
REACH registration obligations in Europe, EPA TSCA Section 5 scrutiny in the United States, and China's GB standards for food-contact materials collectively tighten purity and traceability requirements across export-oriented supply chains. ECHA's evolving restrictions on persistent substances are pushing manufacturers toward shorter-chain or fully saturated amide variants with improved environmental fate profiles. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance costs for multi-destination suppliers escalate faster than formulation premiums can absorb.
Market Dynamics
REACH restrictions on synthetic lubricant precursors are redirecting formulation chemistries toward plant-derived amides, restructuring supplier qualification requirements across European polymer compounding. This regulatory pivot is compressing margins for petrochemical routes while creating certification premiums for bio-based alternatives.
Growth Catalysts
- EU Green Deal procurement mandates:Compounders must now certify bio-based content in processing aids, creating compliant demand for mass-balance certified erucamide and oleamide slip agents.
- Polymer film extrusion in China:Compounding facilities cluster around Shanghai and Ningbo, absorbing higher volumes of anti-block additives as flexible packaging output expands.
- Ethanolamide mildness premiums:Personal care formulators command price positioning for C12-C18 diethanolamides in rinse-off applications where dermatological safety credentials differentiate.
Market Restraints
- Erucic acid supply concentration:High-erucic rapeseed oil sourcing concentrates in Canadian prairies and Indian subcontinent, exposing amide producers to agricultural yield volatility and trade friction.
- Diamide thermal stability limitations:Engineering polymer processors require C20-C22 saturated diamides for PEEK and PPS compounding, where simpler monoamide chemistries fail at elevated shear temperatures.
- EPA TSCA Section 5 scrutiny:New chemical notifications for novel amide structures extend approval timelines, freezing innovation pipelines for US-focused formulators.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic amide production incentives attract backward-integrated investments from oleochemical majors seeking to serve South Asian polymer markets.
- Food-contact GB standards compliance:China's SAMR migration limits for polyethylene films create certified-grade demand that Western suppliers can capture through joint-venture manufacturing.
- Mass-balance certification convergence:ISCC PLUS and RSB standards are unifying sustainability verification, enabling premium pricing for amides with traceable vegetable oil feedstocks.
Industry Challenges
- Multi-jurisdiction registration timelines:ECHA REACH dossiers, EPA PMN submissions, and China's NMPA food-contact approvals require parallel regulatory teams, stretching compliance budgets.
- Analytical method standardization gaps:Amide purity testing protocols diverge between ISO 17025 laboratories, creating disputes over anti-block performance specifications in masterbatch supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Acid Amides Market |
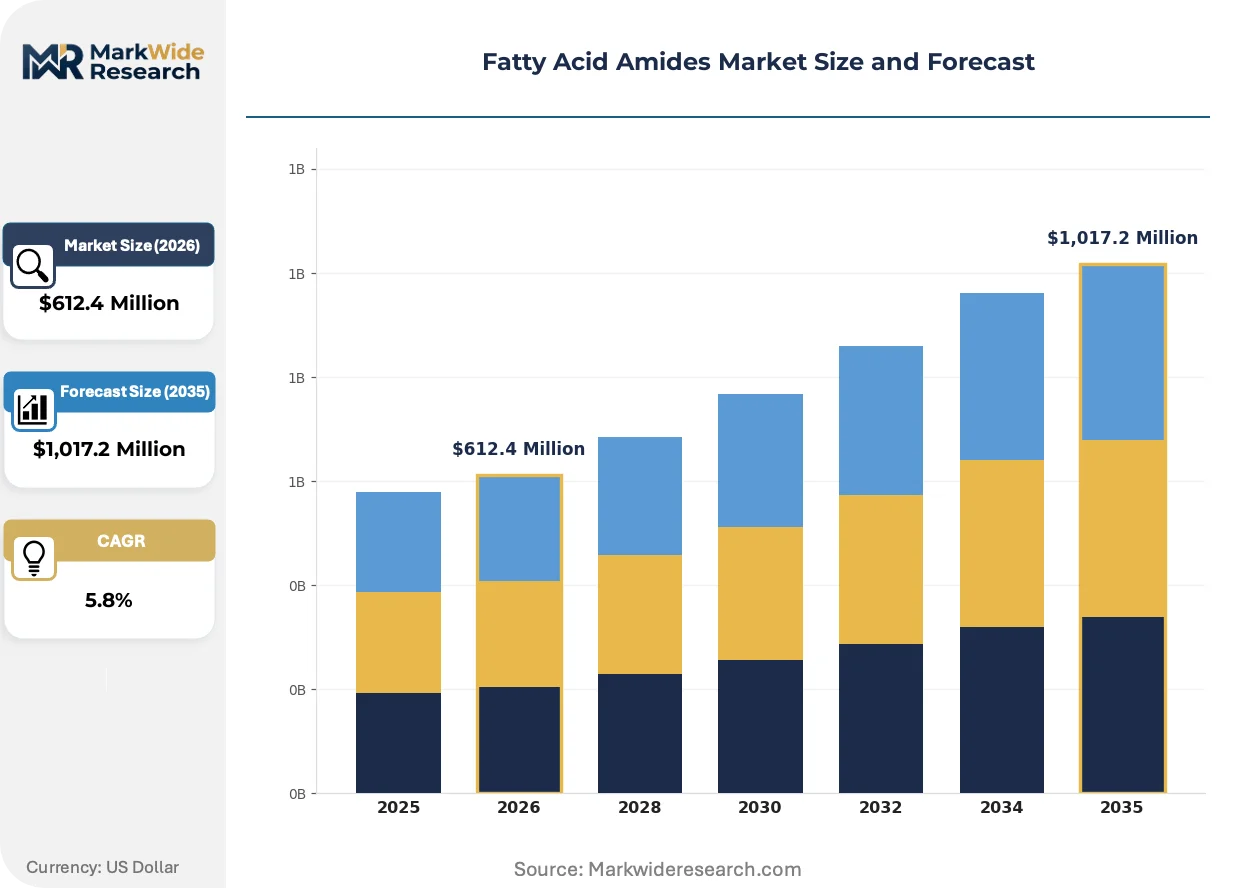
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoamides, Ethanolamides, Diamides, Amine-terminated End Use Industry: Pharmaceuticals, Food Processing, Personal Care, Plastics Functionality: Emulsifier, Stabilizer, Surfactant, Thickening Agent Formulation Type: Liquid, Powder, Granules, Emulsions |
| Companies Covered | Kao Corporation, Nippon Fine Chemical, BASF, PMC Biogenix, Italmatch Chemicals, Mitsubishi Chemical Corporation, KLK OLEO, Fine Organic Industries, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Acid Amides Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based verification systems that embed traceability into polymer processing aid procurement. This shift is compressing the competitive window for conventional petrochemical routes.
Enzymatic amidation processes are unifying sustainability credentials with cost parity. Specialty chemical producers adopt lipase-catalyzed routes for C18 monoethanolamides to bypass high-pressure thermal synthesis. This technology is compressing capital intensity for mid-scale producers while enabling carbon footprint claims that satisfy ESG-linked procurement clauses.
ECHA's evolving restrictions on persistent substances are tightening purity specifications for amide additives in European food-contact applications. Manufacturers reformulate toward shorter-chain saturated variants with improved environmental fate profiles. Polyethylene film extruders in Germany and France absorb compliance costs through specification premiums for certified migration-safe grades.
Buyer concentration among multinational packaging groups is consolidating amide procurement into framework agreements with sustainability riders. Tier-one compounders in North America and Western Europe now mandate ISCC PLUS certification for slip agent supply. This behavior concentrates volume with vertically integrated oleochemical suppliers capable of documenting feedstock origin through polymer film value chains.
Fatty Acid Amides Market Segmentation
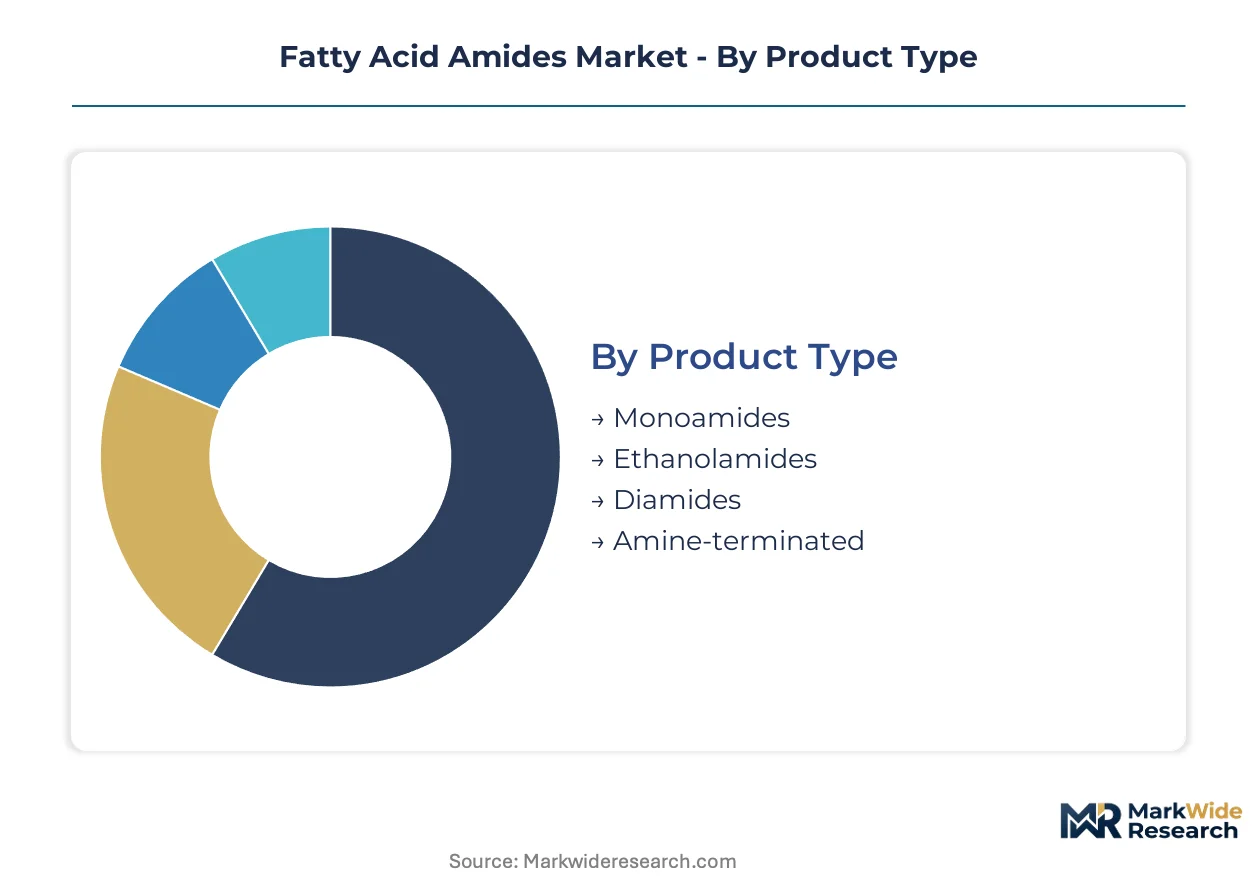
Segmentation in fatty acid amides tracks how molecular architecture dictates margin structure across polymer processing and personal care. Chain length, saturation degree, and terminal functional groups separate commodity volume from specialty premiums.
Product Type:
Monoamides dominate tonnage while ethanolamides and diamides capture margin premiums through performance differentiation.
- Monoamides:Long-chain saturated fatty acids condensed with ammonia yield C18 oleamide and C22 erucamide slip agents. Polyethylene film extruders in China's eastern manufacturing corridor absorb the highest volumes as flexible packaging output expands. REACH restrictions on synthetic lubricant precursors are redirecting formulation chemistries toward plant-derived monoamides with mass-balance certification.
- Ethanolamides:Reaction of fatty acids with monoethanolamine or diethanolamine produces mild surfactants for rinse-off personal care. Personal care formulators in Western Europe command price positioning for C12-C18 diethanolamides where dermatological safety credentials differentiate. Kao Corporation leverages its oleochemical heritage to dominate Asia-Pacific supply routes for these grades.
- Diamides:Bis-amide structures from C20-C22 diacids provide thermal stability in engineering polymer processing.
- Amine-terminated:Reactive amide intermediates for epoxy curing and polyamide modification.
Mature deployment sits with monoamides. Newer deployment is concentrated in ethanolamides.
End Use Industry:
Application concentration separates process-aid commodities from formulated specialties with regulatory compliance burdens.
- Plastics:Slip agents and anti-block additives for polyethylene and polypropylene film extrusion. Compounding facilities cluster around Shanghai and Ningbo, absorbing higher volumes as flexible packaging output expands.
- Personal Care:Mild surfactants and emulsifiers where dermatological safety credentials command premium positioning. BASF sustains R&D intensity in amide derivatives for this segment.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient applications with purity and traceability requirements.
- Food Processing:Food-contact lubricants and release agents subject to migration limits and GB standards compliance.
Volume concentration rests with plastics. Margin expansion is climbing the fastest in personal care.
Functionality:
Functional role determines specification stringency and substitution elasticity across end-use segments.
- Surfactant:Surface-active properties from hydrophilic-lipophilic balance tuning in personal care and industrial cleaning.
- Emulsifier:Stabilization of oil-water interfaces in cosmetics and food applications.
- Stabilizer:Thermal and oxidative stability enhancement in polymer processing.
- Thickening Agent:Rheology modification through network formation in aqueous systems.
Specification breadth is widest for surfactant grades. Regulatory burden is heaviest for emulsifier applications.
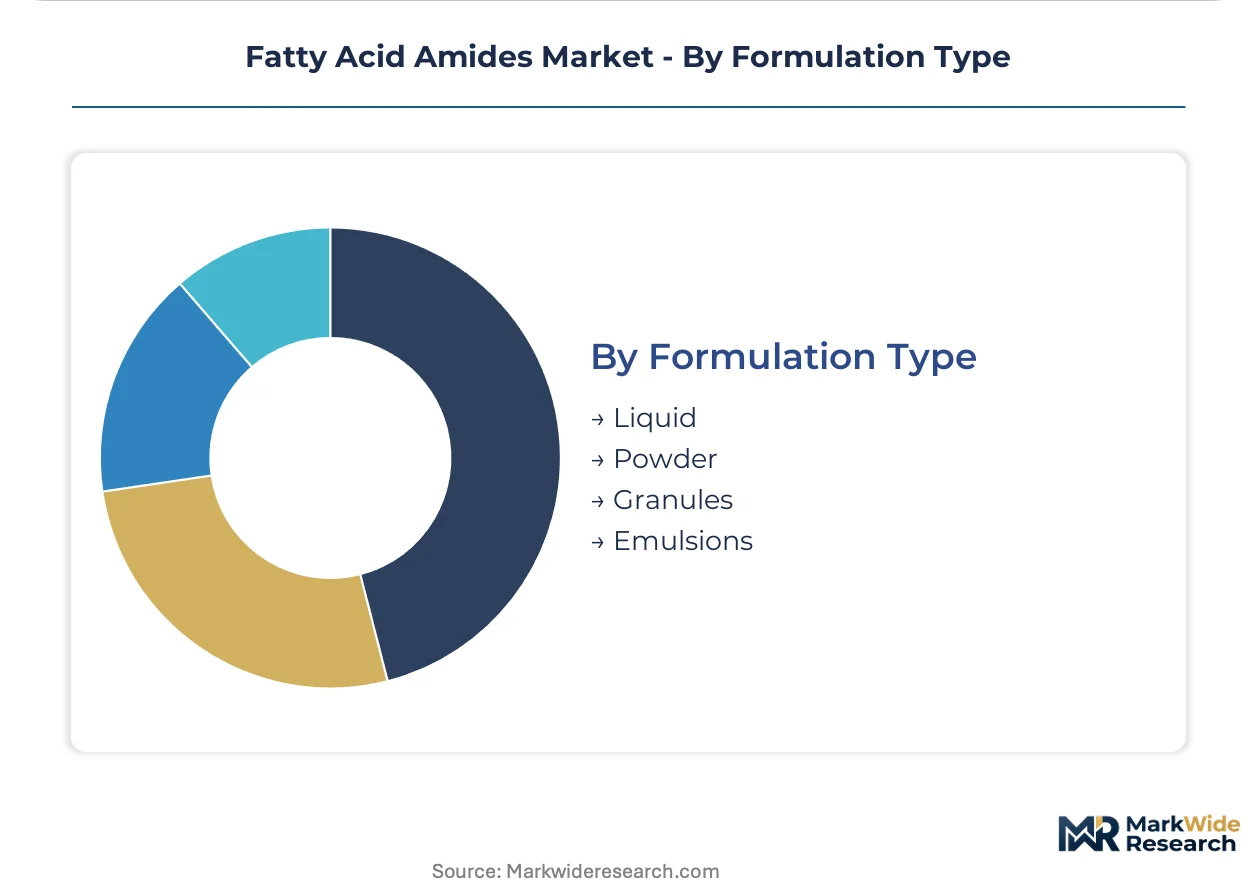
Formulation Type:
Physical form factors align with customer handling infrastructure and dosing precision requirements.
- Powder:Free-flowing amide grades for dry blending in masterbatch compounding.
- Liquid:Molten or solvent-dissolved amides for direct injection into extrusion lines.
- Granules:Dust-reduced forms for automated feeding systems in high-volume polymer processing.
- Emulsions:Aqueous dispersions for water-based coatings and personal care formulations.
Handling efficiency favors granules. Formulation flexibility is expanding most quickly in emulsions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Ningbo anchor polymer compounding demand, absorbing slip agents and anti-block additives as flexible packaging output expands across China's eastern manufacturing corridor.
China
Polyethylene film extruders in the Yangtze River Delta absorb the highest volumes of erucamide slip agents. SAMR migration limits for food-contact materials tighten purity specifications, forcing certified-grade procurement. Compounding facilities cluster around Shanghai and Ningbo, where masterbatch producers scale anti-block additive consumption.
Germany
Engineering polymer processors in the Ruhr region demand C20-C22 saturated diamides for PEEK and PPS compounding. ECHA REACH restrictions on persistent substances redirect formulation toward shorter-chain saturated variants. BASF sustains R&D intensity in amide derivatives from Ludwigshafen, serving automotive and industrial compounders.
United States
Flexible packaging converters in the Midwest and Southeast masterbatch sectors absorb monoamide slip agents. EPA TSCA Section 5 scrutiny extends approval timelines for novel amide structures, freezing innovation pipelines. PMC Biogenix anchors domestic supply from Arkansas, serving polyethylene film extruders with erucamide grades.
India
Polymer processors in Gujarat and Maharashtra expand anti-block additive consumption as flexible packaging output rises. The PLI scheme for specialty chemicals attracts backward-integrated investments from oleochemical majors. Fine Organic Industries leverages Mumbai-based production to serve South Asian compounding markets.
United Kingdom
Personal care formulators in the Southeast command price positioning for C12-C18 diethanolamides where dermatological safety credentials differentiate. Croda International Plc anchors European demand through certified mass-balance supply chains from East Yorkshire. ISCC PLUS certification requirements concentrate procurement with traceable vegetable oil feedstock suppliers.
Fatty Acid Amides Market Vendor Landscape
The competitive structure tilts toward vertically integrated oleochemical specialists with captive vegetable oil supply chains. Tier-one compounders in North America and Western Europe now mandate sustainability certification, concentrating volume with producers capable of documenting feedstock origin. Three archetypes dominate: Asian oleochemical majors with backward integration into palm and rapeseed oil, European mass-balance specialists serving ESG-linked procurement, and regional compounders with formulation chemistry expertise. Competitive moves center on enzymatic amidation technology licensing and ISCC PLUS certification acquisition to secure framework agreements.
Among Asia-Pacific-based producers, Kao Corporation and Mitsubishi Chemical Corporation exemplify the integrated oleochemical archetype, leveraging regional supply routes for erucamide and ethanolamide grades. BASF represents the European R&D-intensive tier, sustaining derivative development for engineered plastics from Ludwigshafen. Croda International Plc anchors the mass-balance certification tier, occupying a position where traceable feedstock documentation commands premium positioning in polymer and personal care supply chains.
| Leading Market Players |
|---|
| Kao Corporation |
| Nippon Fine Chemical |
| BASF |
| PMC Biogenix |
| Italmatch Chemicals |
| Mitsubishi Chemical Corporation |
| KLK OLEO |
| Fine Organic Industries |
| Croda International Plc |
| Others |
Supply Flow & Price Mechanics
Family-owned oleochemical specialists in Malaysia and Indonesia anchor upstream supply, compressing margin capture for non-integrated compounders while enforcing pricing discipline through captive palm and rapeseed oil sourcing. This ownership pattern concentrates bargaining power with processors capable of documenting feedstock origin through ISCC PLUS mass-balance certification.
Pricing Analysis
Yield-based pricing anchors contract structures, with polyethylene film extruders in China's Yangtze River Delta paying premiums for erucamide grades that demonstrably reduce line downtime and scrap rates. Price differentiation separates mass-balance certified bio-based amides from conventional petrochemical routes, with REACH-compliant European procurement absorbing specification premiums. Cost compression in standard-grade monoamides is intensifying because Indian and Southeast Asian producers are expanding ethoxylation capacity. Masterbatch compounders in flexible packaging represent the most price-sensitive buyers, while personal care formulators in Western Europe demonstrate lowest sensitivity due to dermatological safety credential requirements.
Supply Chain Analysis
ISCC PLUS and RSB certification gating concentrates qualified supply with vertically integrated oleochemical majors capable of tracing vegetable oil feedstocks through polymer film value chains. Raw material supply draws from high-erucic rapeseed oil in Canadian prairies and Indian subcontinent, palm kernel derivatives from Malaysia and Indonesia, and coconut oil from Philippines and Indonesia. Single-source vulnerability in erucic acid sourcing exposes amide producers to agricultural yield volatility and trade friction. Distribution runs through framework agreements with tier-one compounders in North America and Western Europe, with spot market liquidity thinning for non-certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic amidation technology is displacing high-pressure thermal synthesis, compressing capital intensity for mid-scale producers while enabling carbon footprint claims that satisfy ESG-linked procurement clauses.
For Market Incumbents: Cement mass-balance certification leadership through ISCC PLUS acquisition and feedstock documentation systems, defending against Southeast Asian entrants with cost-advantaged enzymatic routes. Prioritize backward integration into high-erucic rapeseed crushing or palm fractionation to secure supply continuity against Canadian and Indian agricultural volatility. Capacity addition in Gujarat or Maharashtra captures India's PLI scheme incentives while serving South Asian polymer markets with reduced logistics exposure. For New Entrants and Emerging Players: EU Green Deal procurement mandates in Germany and France open a window for bio-based amide specialists with certified mass-balance supply chains and documented vegetable oil provenance. White-space concentration sits with C20-C22 saturated diamides for PEEK and PPS engineering polymer processing, where thermal stability requirements exclude simpler monoamide chemistries and incumbent supply is thin. SAMR food-contact compliance in China represents a penetrable entry point through joint-venture manufacturing with domestic masterbatch compounders around Shanghai and Ningbo. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European compounders with stranded petrochemical amidation assets and established REACH dossiers but lacking bio-based certification. Long-term viability hinges on enzymatic technology licensing positions and ISCC PLUS accreditation timelines. Watch for inflection in ECHA restrictions on persistent substances, which would accelerate reformulation demand toward shorter-chain saturated amide variants with improved environmental fate profiles.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Amidation Technology Licensing | Lipase-catalyzed routes for C18 monoethanolamides bypass high-pressure thermal synthesis, enabling carbon footprint claims for ESG procurement. |
| ISCC PLUS Certification Acquisition | Mass-balance accreditation secures framework agreements with tier-one compounders mandating traceable vegetable oil feedstock documentation. |
| Backward Integration into High-Erucic Rapeseed | Captive crushing capacity in Canadian prairies or Indian subcontinent insulates against agricultural yield volatility and trade friction. |
| Joint Venture Manufacturing in China | Domestic production around Shanghai and Ningbo captures SAMR food-contact compliance demand while serving Yangtze River Delta masterbatch clusters. |
| Diamide Capacity Expansion for Engineering Polymers | C20-C22 saturated diamide production serves PEEK and PPS compounding in Germany's Ruhr region where thermal stability requirements exclude monoamides. |
Methodological Framework
Trade databases, ECHA REACH registration dossiers, and SEC filings from publicly traded oleochemical majors formed the secondary backbone, supplemented by customs records tracking erucamide and oleamide flows into China's eastern manufacturing corridor. Primary interviews with polymer processing plant managers, procurement leads at flexible packaging OEMs, technical R&D directors at masterbatch compounders, and regulatory affairs specialists at personal care formulators validated supply chain configurations and pricing benchmarks. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Malaysian, Indonesian, and European oleochemical facilities.
Historical trendline analysis of amide consumption in polyethylene film extrusion, engineering polymer compounding, and personal care emulsification established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture (monoamide, ethanolamide, diamide), end-use industry (plastics, personal care, food processing), functionality (slip agent, anti-block, surfactant, emulsifier), and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating polymer film output growth, regulatory compliance cost absorption, and substitution dynamics between petrochemical and bio-based feedstock routes.
The model assumes a particular technology adoption path; alternative pathways for enzymatic amidation scale-up would alter the outlook through accelerated cost parity and compressed capital requirements for mid-scale entrants. Forecasts reflect assumptions regarding ECHA regulatory trajectory, Chinese flexible packaging output sustainability, and Indian PLI scheme implementation pace. A model refresh is warranted upon material change in EU Green Deal procurement mandate enforcement or SAMR food-contact standard revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Triethyl Citrate Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Squalane Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Europe Wax Market
Oleochemicals
Paraffin Market
Oleochemicals
Global Wax Market
Oleochemicals
Iso-Octene Market