
 Global Fatty Amides Market | 2026-2036
Global Fatty Amides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fatty Amides Market Foresight
Asian oleochemical producers is broadening fatty amide output to serve polymer and personal care formulators. Croda International Plc leverages its integrated oleochemistry platform to sustain supply security for erucamide and oleamide grades. BASF SE anchors European production through specialized amide derivatives for engineered plastics. Kao Corporation dominates Asian personal care applications with refined stearamide technologies.
Fatty amides are long-chain carboxylic acid derivatives synthesized via amidation of fatty acids with ammonia or amines, typically containing C12 to C22 carbon chains with melting points between 65°C and 110°C. These compounds function primarily as slip agents, anti-block additives, and lubricity modifiers in polymer processing and industrial formulations. Erucamide commands premium positioning in high-performance film applications where low coefficient of friction is critical. Stearamides occupy mature volume pools in commodity plastic processing across Asia-Pacific polymer corridors. Oleic amides differentiate through broader compatibility with bio-based polymer feedstocks.
REACH registration requirements in Europe, EPA chemical substance rules in the United States, and China's GB standards for plastic food-contact materials collectively elevate purity thresholds and documentation burdens for fatty amide suppliers. ECHA substance evaluations are pushing formulators toward primary amides with lower migratory potential in packaging end uses. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating product portfolios toward amide chemistries that satisfy the strictest forthcoming migration limits.
Market Dynamics
Polymer-grade fatty amide specifications are tightening as food-contact migration limits harden across major regulatory jurisdictions, forcing producers to reconfigure purification trains and documentation systems.
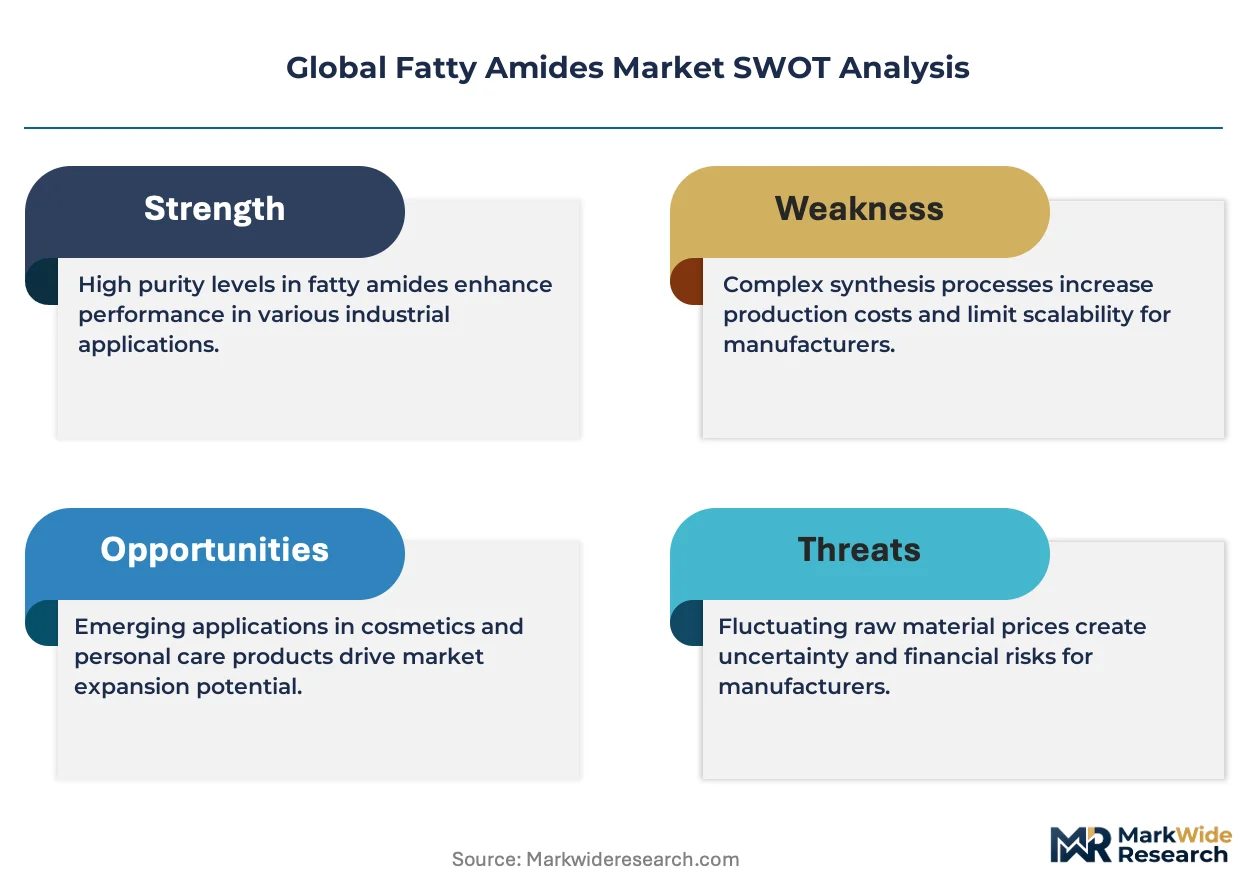
Growth Catalysts
- REACH substance evaluations:ECHA's scrutiny of migratory additives in European packaging channels is accelerating formulator migration toward primary amide chemistries with demonstrably lower extractable profiles.
- Polymer corridor expansion:Integrated oleochemical complexes in China and India are scaling amidation capacity to serve domestic polyethylene film producers seeking localized slip agent supply.
- Erucamide performance premium:High-clarity agricultural and medical film applications are specifying low-coefficient-of-friction erucamide grades over commodity alternatives.
Market Restraints
- Erucic acid supply concentration:Brassica oilseed cultivation for erucic acid feedstock clusters in limited temperate growing regions, exposing erucamide producers to crop yield volatility.
- GB standard compliance costs:China's evolving national standards for plastic food-contact materials impose purity documentation burdens that smaller amidation operators struggle to absorb.
- Silicone slip agent substitution:Perfluorinated and silicone-based alternatives are capturing share in premium film segments where ultra-low friction specifications override cost considerations.
Strategic Opportunities
- Bio-based polymer compatibility:Oleic amide grades demonstrate superior miscibility with polylactic acid and polyhydroxyalkanoate matrices, positioning suppliers for bioplastic packaging growth.
- Personal care formulation demand:Refined stearamide technologies for hair conditioning and emulsion stabilization are penetrating Southeast Asian cosmetic manufacturing clusters.
- EPA chemical substance rules:United States regulatory documentation requirements for new chemical notifications are creating barriers to entry that favor incumbent amide producers with established PMN files.
Industry Challenges
- Amidation process engineering talent:Specialized knowledge of high-pressure ammonia handling and continuous reactor optimization is concentrating among retiring cohorts at legacy European producers.
- Migration testing protocol standardization:Divergent analytical methods between EFSA, FDA, and SAMR jurisdictions force multi-registration of identical amide grades with redundant toxicology packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fatty Amides Market |
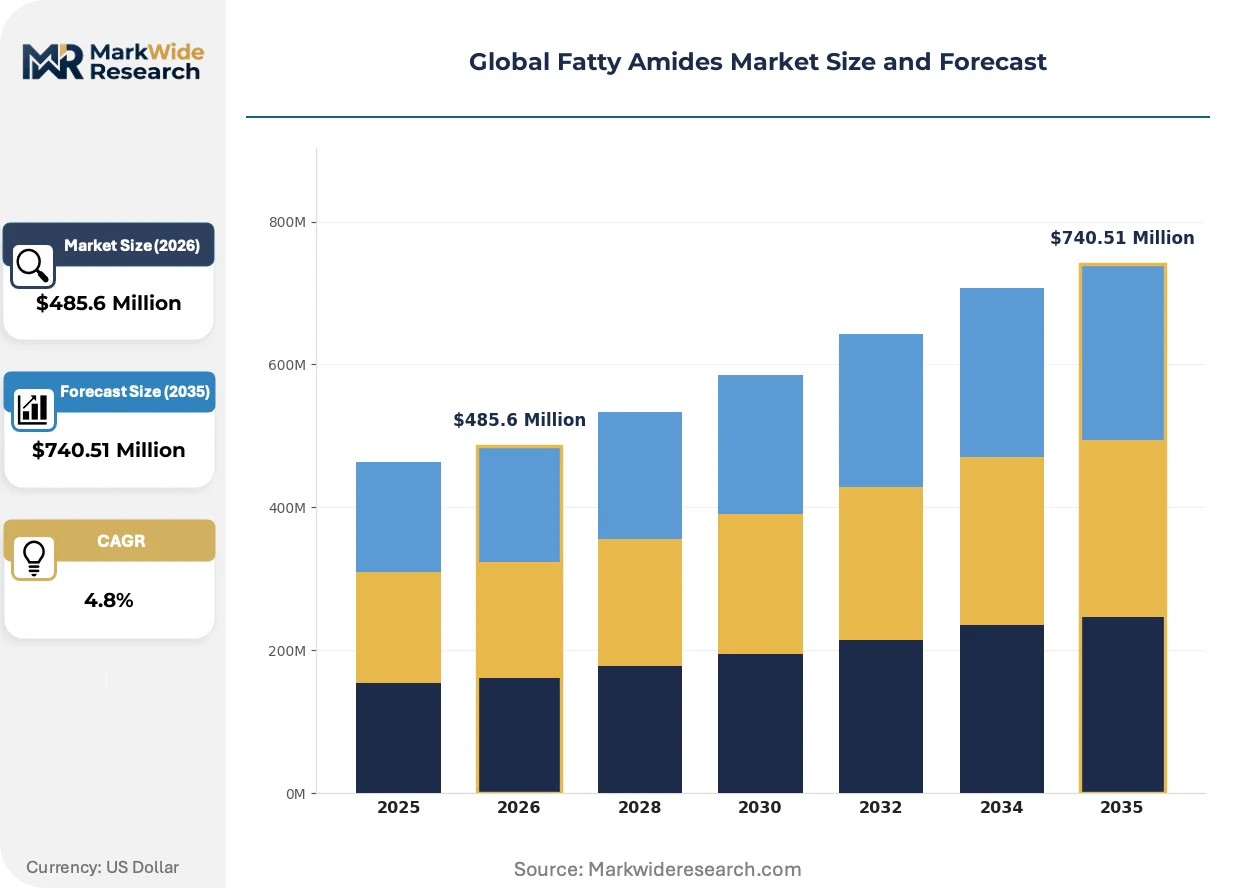
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $740.51 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oleic Amides, Stearamides, Lauramide DEA, Erucamide, Others Application: Personal Care, Agrochemicals, Lubricants, Plastic Processing, Textile Treatment End User Industry: Cosmetics Manufacturers, Pesticide Producers, Automotive Lubricants, Polymer Plants, Apparel Producers Packaging Type: Drums, Bulk Bags, Totes, Intermediate Bulk Containers, Cartons |
| Companies Covered | Croda International Plc, BASF SE, Kao Corporation, PMC Biogenix Inc, Fine Organic Industries Pvt. Ltd., Nippon Fine Chemicals Co., Ltd., Mitsubishi Chemical Corporation, KLK OLEO, Italmatch Chemicals S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fatty Amides Market Shifts & Advancements
Continuous flow reactor technology is displacing batch amidation systems across mid-scale producers, compressing capital recovery timelines while enabling tighter purity control for food-contact specifications.
Modular skid-mounted amidation units are decentralizing fatty amide production by allowing polymer compounders to install captive slip agent capacity at film manufacturing sites. BASF and regional engineering firms are deploying containerized reactor systems for on-demand erucamide generation. This distributed model is compressing logistics costs and lead times for just-in-time polymer additive procurement.
REACH authorization procedures for substances of very high concern are tightening migratory limits on secondary amide impurities in European packaging channels. ECHA's 2024 substance evaluation roadmap prioritizes primary amide chemistries with documented metabolic profiles. Film converters serving EU retail channels are reformulating toward erucamide and oleamide grades with certified low-secondary-amine content.
Compounders are consolidating additive procurement through integrated masterbatch suppliers rather than direct amide purchases. This channel consolidation is compressing spot market volumes while elevating technical service requirements for amide producers. The shift is most visible in German and Italian automotive interior film supply chains, where Tier 1 suppliers now specify complete additive packages from masterbatch houses.
Global Fatty Amides Market Segmentation
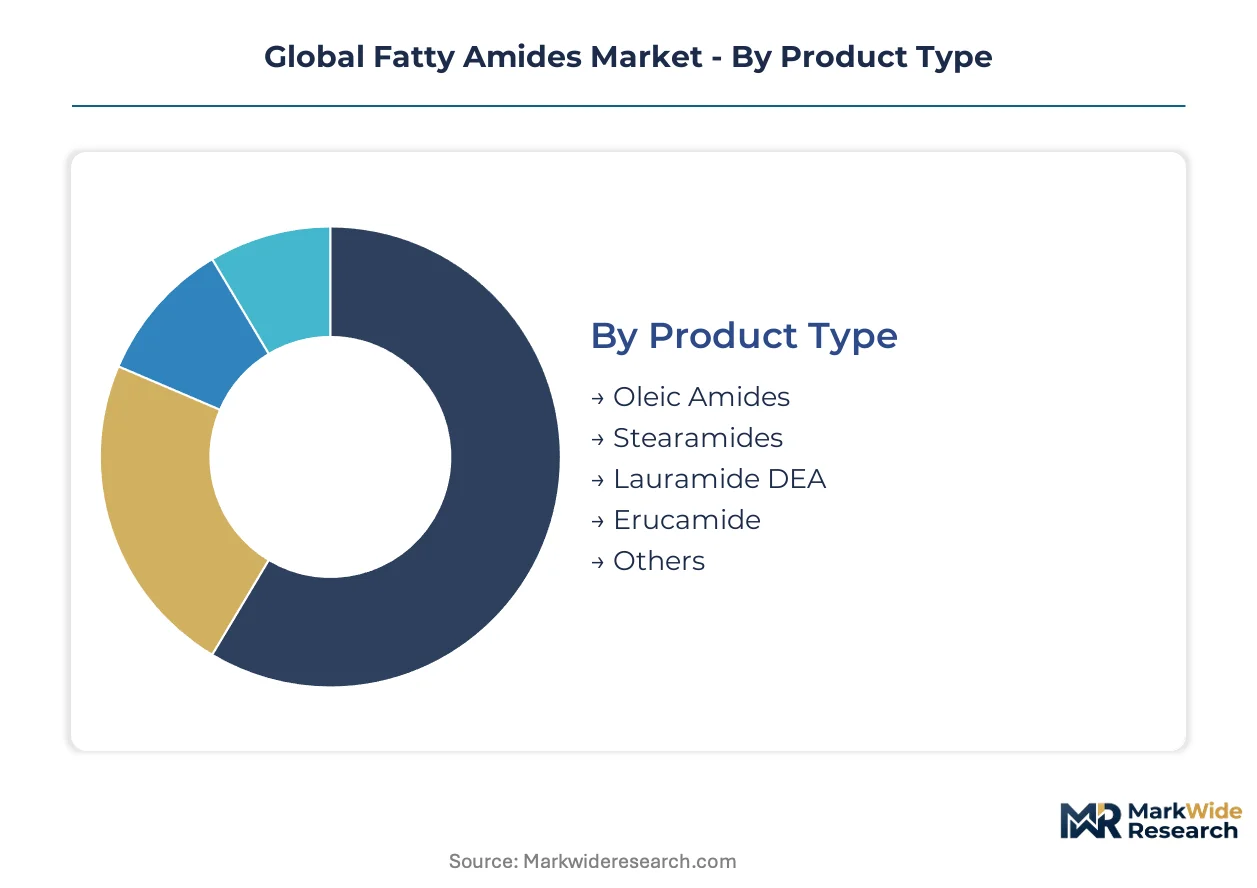
Segmentation in fatty amides tracks how technical specifications and regulatory thresholds fragment procurement across polymer processing, personal care, and industrial lubricant channels. Buyers select grades based on carbon chain length, amidation purity, and migration compliance profiles rather than commodity pricing alone.
Product Type:
Upgrade cycles in polymer additive specifications are forcing compounders to retire legacy stearamide formulations in favor of lower-migratory primary amide alternatives.
- Erucamide:A C22 mono-unsaturated primary amide derived from high-erucic rapeseed oil. Polymer plants in Germany and China specify erucamide for agricultural film and medical packaging where coefficient-of-friction thresholds sit below 0.15. REACH substance evaluations on migratory additives favor this chemistry over secondary amide alternatives.
- Stearamides:Saturated C18 amides produced from tallow or palm stearin feedstocks. Volume concentrates in commodity polyethylene processing across India and Vietnam, where cost-sensitive film producers prioritize unit economics over clarity specifications. GB standard compliance for food-contact materials is tightening purity documentation burdens on this mature grade.
- Oleic Amides:C18 mono-unsaturated amides compatible with polylactic acid and bio-based polymer matrices.
- Lauramide DEA:Diethanolamide derivative for personal care foam stabilization and viscosity modification.
- Others:Specialty branched-chain and behenamide grades for niche lubricant and textile applications.
Stearamides sit at the top of the volume ranking, with erucamide climbing the fastest as food-contact migration limits harden.
Application:
Cost tier stratification separates premium film-grade specifications from commodity plastic processing volumes.
- Plastic Processing:Slip and anti-block functions in polyethylene and polypropylene film extrusion. Demand clusters in China, India, and Germany where integrated polymer corridors source amides through masterbatch intermediaries rather than direct procurement. ECHA's 2024 substance evaluation roadmap is accelerating reformulation toward primary amide chemistries.
- Personal Care:Hair conditioning, emulsion stabilization, and foam boosting in rinse-off and leave-on formulations. Southeast Asian cosmetic manufacturing clusters in Thailand and Indonesia drive specification of refined stearamide and oleamide grades with low secondary-amine residuals.
- Lubricants:Friction modification and corrosion inhibition in metalworking and automotive fluids.
- Agrochemicals:Surfactant and adjuvant functions in pesticide emulsions and dispersible granules.
- Textile Treatment:Softening and anti-static finishing for synthetic fiber processing.
Plastic processing commands the dominant revenue share, while personal care applications are expanding most quickly on Southeast Asian manufacturing growth.
End User Industry:
Customer type fragmentation separates integrated oleochemical consumers from merchant market buyers with divergent technical service requirements.
- Polymer Plants:Integrated polyethylene and polypropylene film producers with captive compounding operations. Procurement concentrates in China, India, and Saudi Arabia where new polymer capacity is scaling amidation demand for localized slip agent supply. Specifications prioritize batch-to-batch consistency and REACH-compliant documentation packages.
- Cosmetics Manufacturers:Formulators of hair care, skin care, and color cosmetic products. Demand localizes in South Korea, Japan, and Singapore where regulatory thresholds for amine residuals in rinse-off products exceed European baselines.
- Automotive Lubricants:Metalworking fluid and engine oil additive packagers.
- Pesticide Producers:Agrochemical formulators requiring emulsifier and dispersant functionalities.
- Apparel Producers:Textile finishers and fiber processors seeking softening agents.
Polymer plants anchor procurement volumes, with cosmetics manufacturers gaining share fastest on Southeast Asian manufacturing migration.
Packaging Type:
Supply chain configuration separates bulk integrated deliveries from packaged merchant sales with divergent logistics economics.
- Bulk Bags:500-1000 kg flexible intermediate bulk containers for polymer plant direct delivery. Dominates procurement in China and India where integrated oleochemical complexes feed downstream amide production with minimal handling stages. Specifications emphasize moisture barriers and UN-certified stacking strength for port-to-plant transfer.
- Drums:200-liter steel or polymer containers for lubricant and personal care formulators. Prevails in European and North American channels where smaller batch sizes and multi-product procurement favor unitized handling. EPA chemical substance documentation requirements attach to each drum lot for US-bound shipments.
- Totes:Intermediate rigid containers for mid-volume polymer compounders.
- Intermediate Bulk Containers:Reusable tank systems for closed-loop supply arrangements.
- Cartons:Retail and sample packaging for specialty laboratory and pilot-scale procurement.
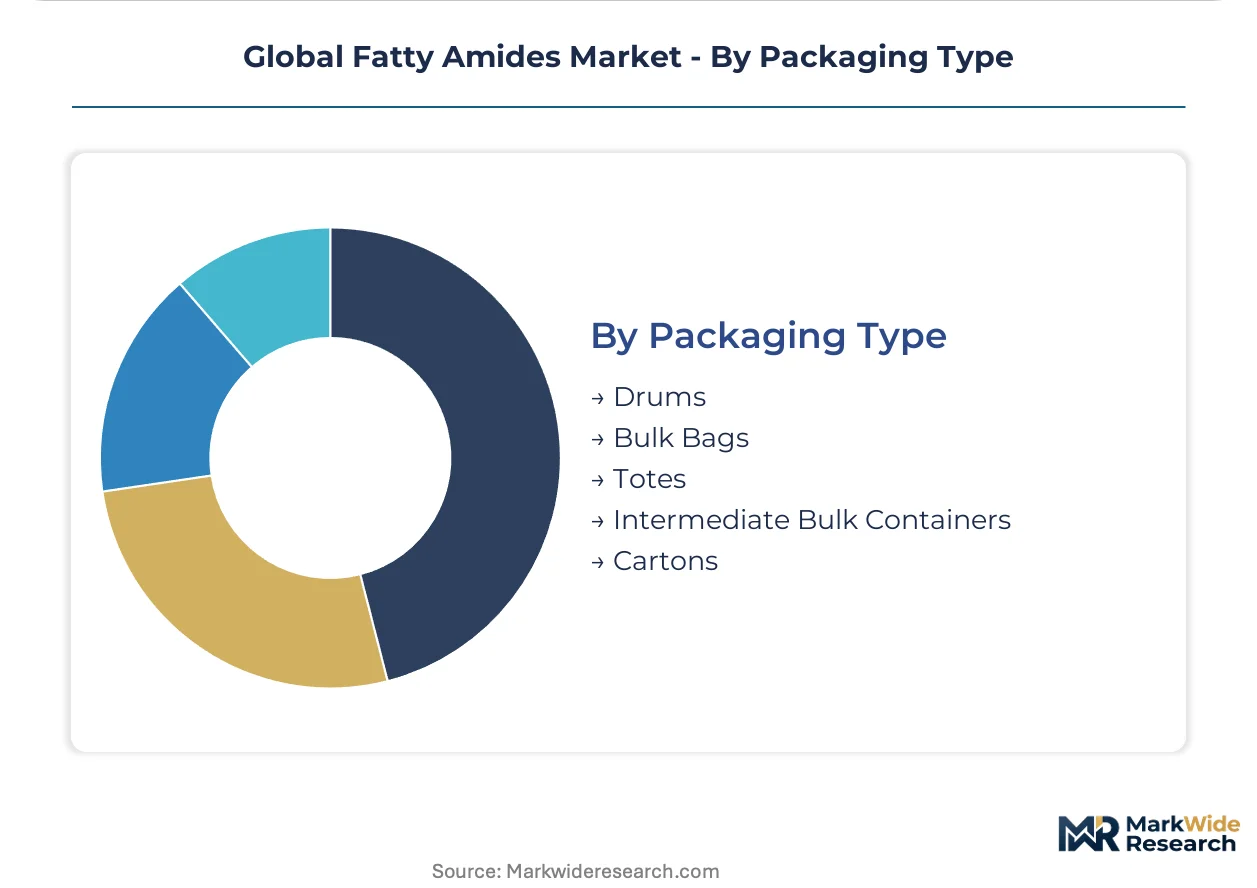
Bulk bags lead procurement volumes by tonnage, with totes gaining share fastest on just-in-time polymer additive sourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's integrated oleochemical corridors outpace India's fragmented amidation capacity, while European REACH enforcement pulls specification standards higher than North American baselines.
China
Polymer plants in Jiangsu and Zhejiang provinces are expanding polyethylene film output, driving localized procurement of erucamide and oleamide slip agents. GB standards for plastic food-contact materials are tightening purity documentation requirements through SAMR enforcement. The Yangtze River Delta concentration of integrated oleochemical complexes feeds downstream amide production with minimal handling stages.
Germany
Automotive interior film supply chains in Bavaria and Baden-Württemberg specify complete additive packages from masterbatch intermediaries rather than direct amide purchases. ECHA substance evaluations on migratory additives are accelerating reformulation toward primary amide chemistries with lower extractable profiles. The Cologne-Düsseldorf industrial corridor hosts specialized amidation capacity serving engineered plastics compounders.
India
Commodity polyethylene processors in Gujarat and Maharashtra prioritize cost-sensitive stearamide grades for unit economics over clarity specifications. BIS compliance documentation for food-contact applications imposes purity thresholds that smaller amidation operators struggle to absorb. The Mundra port cluster enables integrated oleochemical complexes to serve domestic polymer corridors with captive slip agent supply.
United States
EPA chemical substance rules for new chemical notifications are creating documentation barriers that favor incumbent amide producers with established PMN files. Polymer compounders in Texas and Louisiana are consolidating procurement through integrated masterbatch suppliers, compressing spot market volumes. The Gulf Coast petrochemical corridor anchors demand for lubricant-grade fatty amide derivatives.
Japan
Cosmetics manufacturers in Osaka and Tokyo specify refined stearamide technologies with low secondary-amine residuals for rinse-off hair conditioning formulations. METI guidelines on chemical substance safety are elevating technical service requirements for amide suppliers serving personal care channels. The Kansai region's cosmetic manufacturing cluster drives specification of high-purity oleamide grades.
Global Fatty Amides Market Competitive Landscape
European producers anchor the premium documentation tier; Asian specialists hold volume positions in commodity polymer applications. The vendor base splits between integrated oleochemical majors with captive amidation capacity and merchant market specialists serving personal care and lubricant channels. Three archetypes dominate: backward-integrated feedstock controllers, purification-technology specialists, and regional formulation service providers. Competitive moves concentrate on continuous flow reactor licensing and masterbatch partnership structures.
Within the integrated oleochemistry tier, Croda International Plc and BASF SE exemplify producers leveraging captive vegetable oil processing to sustain supply security for high-purity amide grades. Kao Corporation occupies a position representing Asian personal care specialization, with its geographic origin signaling proximity to Southeast Asian cosmetic manufacturing clusters. These three entities illustrate how regulatory documentation capabilities and feedstock integration separate premium positioning from commodity volume competition.
| Leading Market Players |
|---|
| Croda International Plc |
| BASF SE |
| Kao Corporation |
| PMC Biogenix Inc |
| Fine Organic Industries Pvt. Ltd. |
| Nippon Fine Chemicals Co., Ltd. |
| Mitsubishi Chemical Corporation |
| KLK OLEO |
| Italmatch Chemicals S.p.A. |
| Others |
Supply & Pricing Matrix
Specialized amidation process engineers in Germany's Cologne-Düsseldorf corridor command wage premiums that compress margin spreads between premium erucamide and commodity stearamide tiers, with labor-cost differentials between European and Asian production sites driving three-tier pricing stratification across food-contact-certified, industrial-grade, and bulk commodity segments.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for commodity stearamide grades, forcing established European producers to differentiate through REACH-compliant documentation packages and certified low-migration specifications. Three-tier pricing structure across premium, standard, and economy levels reflects divergent purity thresholds: polymer plants in Germany absorb premiums for ECHA-evaluated primary amides, while Indian commodity processors prioritize unit economics. Pricing pressure stems from silicone slip agent substitution in ultra-low-friction film segments. Cost-sensitive buyers in Vietnam and Gujarat represent the most price-sensitive segment; medical film compounders in Bavaria show least sensitivity.
Supply Chain Analysis
Dual-sourcing qualification mandates from polymer plants in China and Germany are fragmenting procurement across integrated oleochemical majors and specialized merchant suppliers. Supply concentrates in China, India, and Germany, with Jiangsu and Zhejiang provinces anchoring integrated amidation capacity. Raw material dependencies rest on high-erucic rapeseed oil from temperate cultivation zones, palm stearin from Southeast Asian estates, and ammonia feedstock from regional petrochemical corridors. Single-source vulnerability in erucic acid supply exposes erucamide producers to crop yield volatility. Distribution runs through masterbatch intermediaries rather than direct amide sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where food-contact migration limits hardening across ECHA, FDA, and SAMR jurisdictions are concentrating procurement among suppliers with certified low-secondary-amine documentation capabilities.
For Market Incumbents: Anchor premium positioning through captive backward integration into high-erucic rapeseed oil processing and continuous flow reactor technology licensing. Defend against silicone slip agent substitution by embedding technical service teams within German automotive interior film supply chains. Prioritize certification investment for ECHA's evolving substance evaluation roadmap. For New Entrants and Emerging Players: REACH authorization procedures in Europe open a window for regional specialists offering primary amide grades with pre-documented metabolic profiles. Target India's fragmented commodity stearamide segment where BIS compliance burdens are forcing smaller operators to exit. Pursue toll-manufacturing arrangements with Chinese integrated oleochemical complexes as the go-to-market angle. For Investors and Strategic Acquirers: Masterbatch compounders are the most active acquirer in this space, consolidating additive procurement channels to capture margin from polymer plants. Over the medium-term horizon, prioritize targets with established PMN files under EPA rules and REACH-compliant dossiers. Watch for ECHA substance evaluation outcomes on secondary amide impurities as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Erucic Feedstock | Croda and BASF secure supply security against Brassica crop volatility in Canadian and Eastern European growing regions. |
| Continuous Flow Reactor Deployment | Modular skid-mounted units enable just-in-time erucamide generation at polymer film manufacturing sites in China. |
| REACH-Compliant Documentation Investment | Primary amide producers capture share from secondary amide suppliers facing ECHA substance evaluation restrictions. |
| Masterbatch Partnership Structures | Channel consolidation in German automotive supply chains compresses spot market volumes while elevating technical service requirements. |
| Bio-Based Polymer Compatibility Development | Oleic amide grades with superior polylactic acid miscibility position suppliers for bioplastic packaging procurement. |
Research Methodology
Direct dialogue with plant managers at integrated oleochemical complexes, procurement leads at polyethylene film producers, technical R&D directors at amide specialists, and distribution channel partners in polymer corridors grounded this analysis. Secondary validation drew from customs and trade data, Cefic sector reports, SEC 10-K filings from listed chemical producers, and ECHA substance evaluation dossiers. Bottom-up capacity assessments and top-down demand modeling were triangulated to ensure consistency.
Top-down macroeconomic drivers were cross-checked against bottom-up segment projections across product type, application, end-user industry, and packaging format dimensions. CAGRs were derived through iterative convergence of historical trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated oleochemical feedstock price dynamics, polymer corridor expansion timelines, and migration limit evolution across jurisdictions.
Revisions become necessary when regulatory divergence between ECHA, FDA, and SAMR jurisdictions accelerates beyond baseline assumptions, or when silicone slip agent cost curves shift substitution economics in premium film segments. Deviation in erucic acid crop yields or REACH authorization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
1-Decene Market
Oleochemicals
Ethylhexyl Palmitate Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Stearic Acid Market
Oleochemicals
Medium-Chain Triglycerides (MCT) Powder Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Aminoethylethanolamine Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Paraffin Wax Market
Oleochemicals
Undecanoyl Chloride Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Neodecanoyl Chloride Market