
 Europe Wax Market | 2026-2036
Europe Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wax Market Insights
Multi-source procurement among European compounders is shifting toward certified sustainable feedstock partnerships. Sasol leverages its Fischer-Tropsch synthetic wax capacity to dominate specialty industrial grades. BASF SE anchors its position through backward integration into petrochemical precursors and custom polymer-modified waxes. Clariant differentiates via bio-based montan wax derivatives targeting cosmetic and pharmaceutical channels.
Wax comprises solid lipophilic substances at ambient temperature, melting between 40°C and 120°C, composed of hydrocarbons, esters, or fatty alcohols that provide barrier, lubrication, or gloss functions across industrial and consumer applications. Paraffin wax maintains volume leadership in candle and packaging applications despite feedstock cost volatility tied to European refinery output. Olefin wax competes in hot-melt adhesives and automotive coatings where thermal stability requirements exceed paraffin performance limits. Microcrystalline wax commands premium positioning in pharmaceutical ointment bases and food-grade coatings due to its higher melting point and adhesive properties.
REACH registration requirements and the EU Green Deal carbon-border adjustments constrain import access for non-compliant Asian wax suppliers while accelerating domestic bio-based certification demand. ECHA substance evaluation protocols force reformulation of certain microcrystalline wax grades containing polycyclic aromatic hydrocarbons above threshold limits. Stakeholders must monitor evolving F-Gas Regulation interactions with wax-based sealing applications and assess whether German automotive OEM sustainability scorecards will exclude petroleum-derived waxes from approved materials lists.
Market Dynamics
REACH registration deadlines and EU Green Deal carbon-border adjustments are forcing reformulation across European wax supply chains, compressing import access for non-compliant Asian suppliers while accelerating certified bio-based feedstock partnerships.
Growth Catalysts
- Automotive OEM sustainability mandates:German manufacturers are expanding wax procurement for electric vehicle battery sealing and lightweight coating applications. Tier-1 suppliers in Stuttgart and Munich industrial clusters now specify certified renewable content in material scorecards.
- REACH compliance deadlines:ECHA substance evaluation protocols are phasing out polycyclic aromatic hydrocarbon-contaminated microcrystalline wax grades. Domestic compounders with pre-registered alternatives capture displaced volume from non-compliant imports.
- Hot-melt adhesive thermal stability requirements:Packaging converters serving e-commerce fulfillment centers specify olefin wax blends exceeding paraffin performance limits. French and Polish converter hubs drive specification upgrades across corrugated board and flexible film sealing.
Market Restraints
- European refinery output volatility:Paraffin wax feedstock costs fluctuate with regional crude processing rates and maintenance schedules at Rotterdam and Antwerp refining complexes.
- Fischer-Tropsch capacity concentration:Synthetic wax supply concentrates at a single large-scale production site in Germany, creating geographic single-source exposure for specialty industrial grades.
- Natural wax substitution pressure:Carnauba and candelilla waxes from South American sources displace petroleum-derived grades in premium cosmetic formulations where label claims emphasize botanical origin.
Strategic Opportunities
- Polish packaging converter expansion:Central European manufacturing hubs near Wrocław and Poznań offer underpenetrated demand for food-grade microcrystalline wax coatings as cold-chain logistics infrastructure scales.
- EU Green Deal bio-based certification:Renewable energy directive incentives and carbon-border adjustment mechanisms reward verified sustainable feedstock sourcing with preferential market access.
- Pharmaceutical ointment base convergence:Combination of microcrystalline wax with polymer-modified rheology agents creates next-generation topical delivery systems for transdermal medication patches.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in polymer-wax compatibilization and regulatory dossier preparation concentrates at aging technical workforces in German and Swiss industrial centers.
- Multi-certification timeline compression:Simultaneous pursuit of REACH registration, EU organic cosmetic certification, and pharmaceutical GMP compliance extends product launch cycles for bio-based entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wax Market |
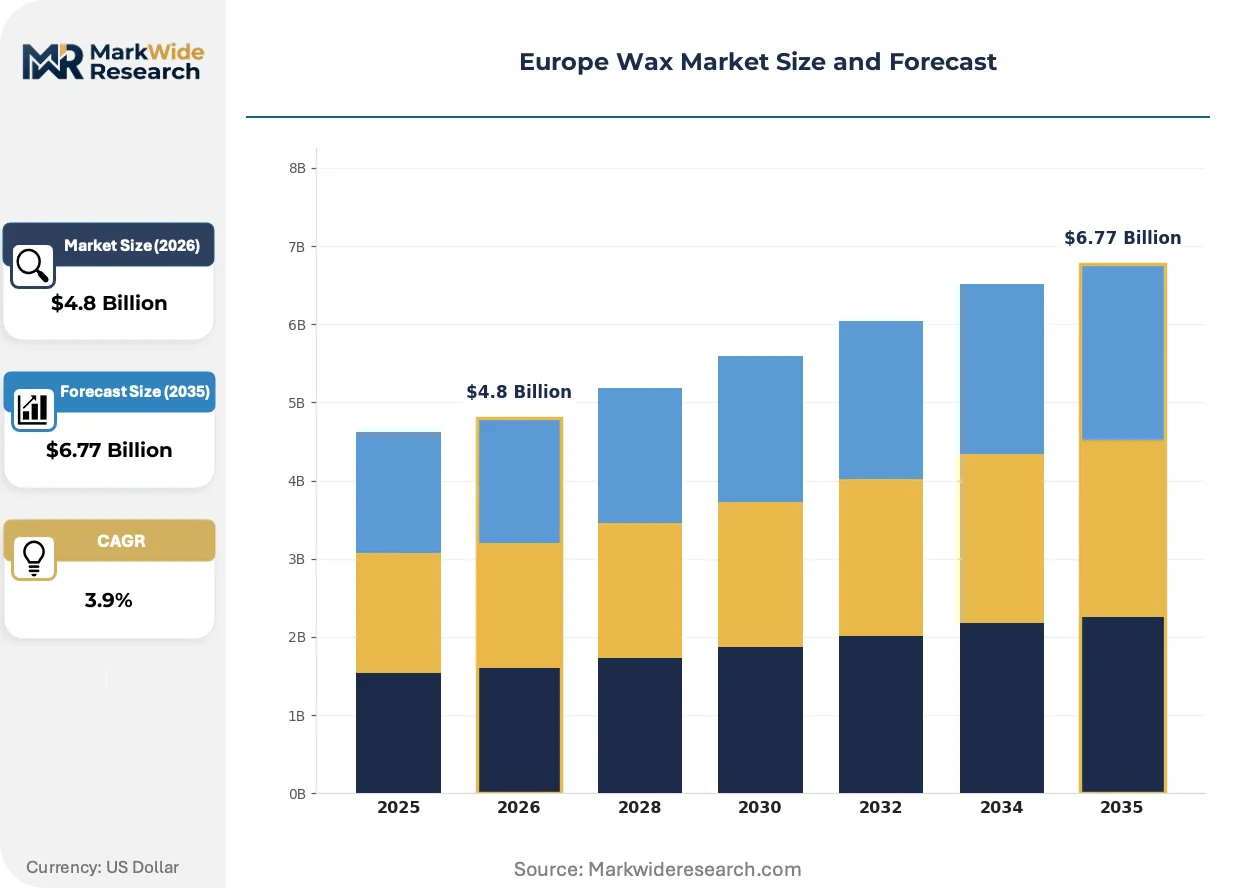
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraffin Wax, Olefin Wax, Microcrystalline Wax, Beeswax Application: Cosmetics, Candles, Packaging, Pharmaceuticals End User: Food Industry, Personal Care, Automotive, Textiles Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Sasol, Honeywell International, BASF SE, The Lubrizol Corporation, Baker Hughes Company, Clariant, Exxon Mobil Corporation, Westlake Corporation, euroceras Sp. z o.o., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wax Market Trends and Innovations
European wax markets are experiencing accelerated specification fragmentation as end-users decouple from commodity paraffin grades toward performance-engineered alternatives with traceable sustainability credentials.
Bio-based montan wax derivatives are consolidating market position in cosmetic and pharmaceutical channels. Clariant and specialty compounders in the Rhine-Ruhr region scale fermentation-derived and botanical-refined grades to serve formulators requiring EU organic certification. This technology is consolidating supplier relationships around certified feedstock partnerships with documented chain-of-custody.
ECHA substance evaluation protocols under REACH are tightening polycyclic aromatic hydrocarbon thresholds for microcrystalline wax grades used in pharmaceutical ointments and food-contact coatings. Compounders with pre-2025 registration dossiers secure continued market access while competitors face reformulation costs or import exclusion. German pharmaceutical packaging converters now audit supplier REACH compliance status as a primary procurement filter.
Direct mill relationships are displacing traditional distributor networks among mid-volume European compounders. French and Italian cosmetic manufacturers now source certified sustainable wax grades through verified supplier platforms rather than regional chemical distributors. This pattern concentrates most visibly in Provence-Alpes-Côte d'Azur and Lombardy cosmetic manufacturing clusters where formulation houses prioritize supply chain transparency for export compliance.
Europe Wax Market Segmentation
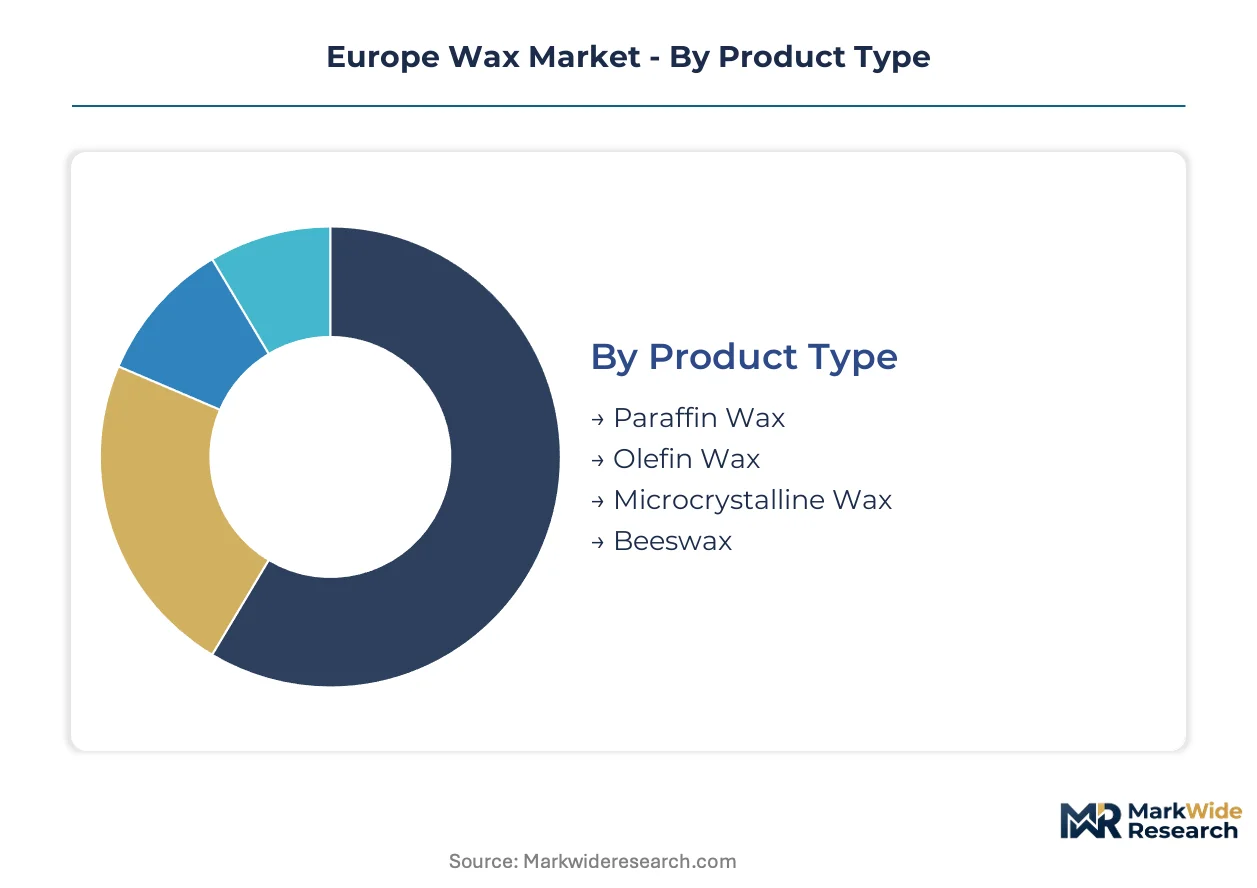
Wax procurement patterns across Europe diverge sharply by end-use performance requirements and regulatory compliance burden. Specification fragmentation forces compounders to maintain parallel inventory positions across multiple grades and certification tiers.
Product Type:
Upgrade cycles in European wax markets accelerate as REACH deadlines force replacement of non-compliant legacy grades with certified alternatives.
- Paraffin Wax:Saturated hydrocarbon mixtures refined from petroleum slack wax dominate candle manufacturing and corrugated board coatings. German packaging converters in the Rhine-Ruhr cluster specify food-grade paraffin for cold-chain logistics applications despite feedstock cost volatility at Rotterdam refining complexes.
- Microcrystalline Wax:Higher molecular weight amorphous waxes with superior adhesive properties command premium positioning in pharmaceutical ointment bases and food-contact coatings. ECHA substance evaluation protocols are phasing out polycyclic aromatic hydrocarbon-contaminated grades, displacing volume toward pre-registered domestic compounders.
- Olefin Wax:Fischer-Tropsch and polymer-derived synthetic waxes deliver thermal stability exceeding paraffin limits for hot-melt adhesives and automotive underbody coatings.
- Beeswax:Natural secretion from Apis mellifera colonies serves niche cosmetic and pharmaceutical formulations requiring EU organic certification.
Paraffin wax sits at the top of the volume ranking, with microcrystalline wax climbing the fastest as pharmaceutical and food-contact specifications tighten.
Application:
Margin structures across application segments correlate with regulatory compliance intensity and formulation complexity.
- Cosmetics:Formulations requiring EU organic certification and REACH registration drive specification toward bio-based montan and botanical wax derivatives. French manufacturers in Provence-Alpes-Côte d'Azur prioritize certified sustainable feedstock partnerships for export compliance.
- Pharmaceuticals:Ointment bases and transdermal delivery systems demand GMP-compliant microcrystalline wax with documented polycyclic aromatic hydrocarbon thresholds below ECHA limits. German packaging converters audit supplier REACH status as a primary procurement filter.
- Candles:Traditional paraffin grades face substitution pressure from natural wax blends in premium scented candle segments.
- Packaging:Corrugated board and flexible film sealing specifications concentrate demand for olefin wax blends with elevated thermal stability.
Cosmetics commands the highest margin tier, with pharmaceuticals expanding most quickly as regulatory barriers exclude non-compliant suppliers.
End User:
Customer concentration patterns reflect geographic clustering of manufacturing activity and sustainability mandate intensity.
- Automotive:German OEM sustainability scorecards now specify certified renewable content in battery sealing and lightweight coating applications. Tier-1 suppliers in Stuttgart and Munich industrial clusters drive procurement toward bio-based and synthetic wax grades with traceable chain-of-custody.
- Personal Care:Formulators across Lombardy and Provence-Alpes-Côte d'Azur cosmetic clusters source certified sustainable wax grades through verified supplier platforms rather than traditional distributor networks.
- Food Industry:Cold-chain logistics infrastructure scaling near Wrocław and Poznań generates underpenetrated demand for food-grade microcrystalline wax coatings.
- Textiles:Fabric finishing and water-repellency applications specify paraffin and microcrystalline wax emulsions with restricted substance compliance.
Automotive sits at the top of the specification intensity ranking, with food industry climbing the fastest as Polish packaging converter capacity expands.
Distribution Channel:
Channel economics shift as mid-volume compounders bypass traditional intermediaries for direct mill relationships.
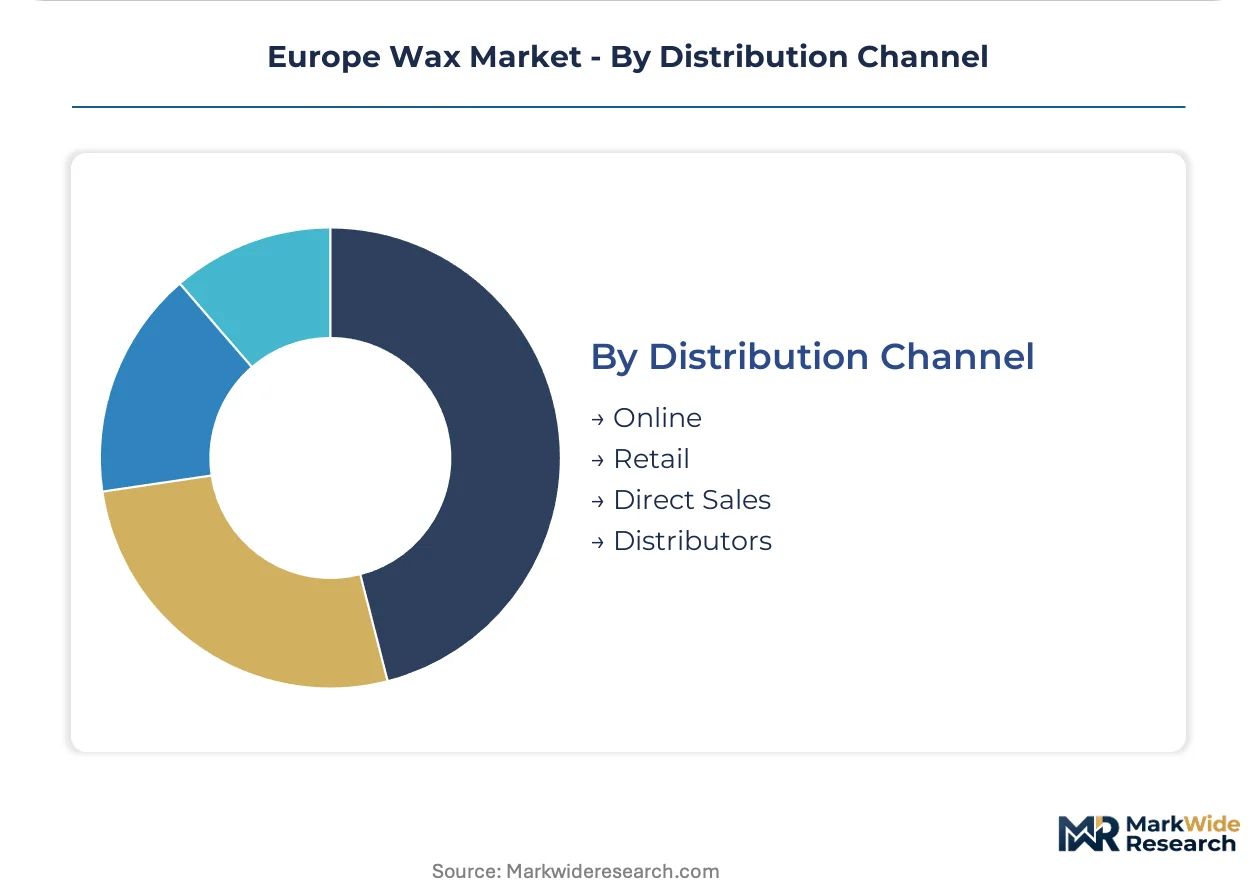
- Direct Sales:Certified sustainable wax grades move through verified supplier platforms connecting compounders to French and Italian cosmetic manufacturers. This pattern concentrates in formulation clusters prioritizing supply chain transparency for export compliance.
- Distributors:Regional chemical distributors retain relevance for smaller compounders requiring technical support and mixed-product logistics.
- Online:Digital procurement platforms serve spot-market purchases and standardized commodity grades with limited technical consultation.
- Retail:Small-volume sales of candle-making and hobbyist wax products through specialty chemical retailers.
Direct sales sits at the top of the growth trajectory ranking, with distributor share contracting fastest as transparency requirements concentrate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Europe tracks divergent REACH enforcement intensity and carbon-border adjustment timelines, with compounders relocating formulation activities toward jurisdictions offering faster regulatory clearance pathways.
Germany
Automotive OEM sustainability scorecards now mandate certified renewable content in battery sealing applications. ECHA substance evaluation protocols under REACH accelerate displacement of non-compliant microcrystalline wax imports. Stuttgart and Munich industrial clusters concentrate Tier-1 supplier procurement relationships for synthetic and bio-based wax grades.
France
Cosmetic manufacturers in Provence-Alpes-Côte d'Azur prioritize EU organic certification for botanical wax derivatives. ANSM cosmetic ingredient oversight converges with REACH registration requirements to elevate compliance costs for petroleum-derived alternatives. Formulation houses near Grasse and Lyon now audit supplier chain-of-custody documentation as a primary procurement filter.
Poland
Packaging converter capacity expansion near Wrocław and Poznań generates underpenetrated demand for food-grade microcrystalline wax coatings. EU Green Deal carbon-border adjustments disadvantage non-compliant Asian suppliers while rewarding domestic compounders with verified sustainable feedstock partnerships. Cold-chain logistics infrastructure scaling drives specification upgrades across corrugated board sealing applications.
Italy
Lombardy cosmetic manufacturing clusters source certified sustainable wax grades through verified supplier platforms rather than traditional distributor networks. ECHA REACH registration deadlines compress product launch timelines for bio-based entrants pursuing simultaneous pharmaceutical GMP compliance. Milan-based formulation houses emphasize supply chain transparency for export compliance with Middle Eastern and Asian markets.
Netherlands
Rotterdam and Antwerp refining complex maintenance schedules introduce paraffin wax feedstock cost volatility for compounders serving candle and packaging applications. EU F-Gas Regulation interactions with wax-based sealing applications create formulation uncertainty for automotive suppliers. Dutch chemical distributors retain relevance for smaller compounders requiring mixed-product logistics and technical support.
Europe Wax Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based certification and specialty pharmaceutical channels. The supplier base concentrates around petrochemical majors with backward integration into feedstock precursors and independent compounders with fermentation-derived capabilities. Three archetypes dominate: integrated petrochemical producers leveraging captive slack wax supply, specialty chemical houses with polymer-modification expertise, and bio-based entrants securing EU organic certification. Capacity expansion and certified feedstock partnerships represent the dominant competitive moves.
Within the integrated producer tier, Sasol and BASF SE anchor positions through synthetic wax capacity and petrochemical precursor control. Among specialty compounders, Clariant occupies a position exemplifying bio-based montan wax differentiation for cosmetic and pharmaceutical channels. These three represent archetypal strategies: Fischer-Tropsch synthesis scale, backward-integrated petrochemical supply, and botanical-refined certification.
| Leading Market Players |
|---|
| Sasol |
| Honeywell International |
| BASF SE |
| The Lubrizol Corporation |
| Baker Hughes Company |
| Clariant |
| Exxon Mobil Corporation |
| Westlake Corporation |
| euroceras Sp. z o.o. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between REACH-registered pharmaceutical waxes and commodity paraffin candles splits the market into parallel pricing architectures. Premium microcrystalline grades for ointment bases command substantial markups through audited supplier relationships, while Rotterdam-refined paraffin moves through spot-market volatility with thinner distributor margins.
Pricing Analysis
Distributor margin compression in the mid-volume tier forces compounders toward direct mill relationships for certified sustainable grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with EU organic cosmetic waxes capturing the widest spreads. Cost compression in paraffin feedstocks intensifies because Rotterdam and Antwerp refining complex maintenance schedules introduce crude processing volatility. Candle manufacturers exhibit highest price sensitivity, while German pharmaceutical packaging converters prioritize compliance documentation over unit cost.
Supply Chain Analysis
Freight cost differentials between German synthetic wax production and South American botanical sourcing reshape procurement geography for cosmetic formulators. Supply concentrates in Germany, Poland, and the Netherlands, with Fischer-Tropsch capacity anchored at a single German site creating single-source exposure. Raw material flows draw from petroleum slack wax, fermentation-derived feedstocks, and imported carnauba. Distribution runs through verified supplier platforms for certified grades and regional chemical distributors for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's wax market functions as a regulatory compounder where ECHA substance evaluation protocols under REACH are forcing wholesale reformulation of legacy microcrystalline grades.
For Market Incumbents: Lock in backward integration into petrochemical precursors or captive bio-based feedstock partnerships before certification timelines compress further. Sasol and BASF SE demonstrate how Fischer-Tropsch scale and polymer-modification expertise create defensive moats against emerging fermentation-derived entrants. Prioritize pre-registration dossiers for pharmaceutical-grade microcrystalline waxes to capture volume displaced by polycyclic aromatic hydrocarbon threshold enforcement. For New Entrants and Emerging Players: Begin with Polish packaging converter hubs near Wrocław and Poznań where cold-chain logistics scaling generates underpenetrated demand for food-grade coatings. EU Green Deal carbon-border adjustments disadvantage non-compliant Asian suppliers, opening procurement relationships for domestic compounders with verified sustainable feedstock documentation. Pursue direct mill relationships through verified supplier platforms rather than traditional distributor networks. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation chemist scarcity concentrates technical expertise in aging German and Swiss industrial workforces. Long-term viability favors compounders with simultaneous REACH registration, pharmaceutical GMP compliance, and EU organic certification capabilities. Watch German automotive OEM sustainability scorecards as the inflection signal—these procurement filters are expanding certified renewable content mandates from battery sealing into broader coating applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Precursors | BASF SE's captive petrochemical supply secures margin control against Rotterdam refining volatility. |
| EU Organic Certification Investment | Clariant's bio-based montan wax derivatives access premium cosmetic channels with documented chain-of-custody. |
| Direct Mill Relationship Platforms | French cosmetic manufacturers bypass distributors for supply chain transparency serving Middle Eastern export markets. |
| Pharmaceutical GMP Compliance Buildout | German packaging converters audit supplier REACH status as primary procurement filter for ointment bases. |
| Polish Converter Hub Proximity | Central European manufacturing expansion near Wrocław captures food-grade microcrystalline wax demand from cold-chain logistics scaling. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at German and Polish compounders, procurement leads at Stuttgart automotive Tier-1 suppliers, technical R&D directors at Rhine-Ruhr specialty chemical houses, and formulation chemists at Lombardy cosmetic manufacturers combined with secondary validation. Sources include ECHA registration databases, EU customs trade data, Cefic sector reports, and SEC filings from integrated petrochemical producers.
Historical trendline analysis across wax grade volume trajectories informed projection frameworks over the analysis window. Segmentation dimensions modeled include product type tier, application regulatory intensity, end-user industry concentration, and distribution channel structure. CAGRs were derived from regression analysis of segment-level demand drivers including REACH compliance deadlines, automotive OEM sustainability mandate adoption curves, and packaging converter capacity expansion patterns. Forecast inputs incorporated ECHA substance evaluation protocol timelines and EU Green Deal carbon-border adjustment implementation phases.
Several conditions sit outside the modeled scope, including unannounced refinery maintenance schedules at Rotterdam and Antwerp complexes, sudden ECHA polycyclic aromatic hydrocarbon threshold revisions, and geopolitical disruptions to South American carnauba supply. Forecasts reflect documented assumptions about regulatory enforcement intensity and feedstock cost transmission mechanisms. Stakeholders should weight assumptions against their own operating context and supplier audit capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Global Oxidized Polyethylene Wax Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Octyl Octanoate Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Alpha Olefin Sulfonates Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Octanoyl Chloride Market