
 Void Pattern Tamper-Evident Tapes Market | 2026-2036
Void Pattern Tamper-Evident Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Void Pattern Tamper-Evident Tapes Market Analytics
Buyer concentration in pharmaceutical contract packaging is recalibrating supplier qualification criteria toward tamper-evident tape vendors with validated cold-chain performance. 3M Company leverages its adhesive science portfolio to sustain dominance in high-security pharmaceutical applications. Avery Dennison anchors North American demand through direct relationships with generic drug distributors. Tesa SE competes on European regulatory compliance breadth.
Void pattern tamper-evident tapes are pressure-sensitive adhesive constructions that fracture or reveal a hidden message upon removal attempt, typically incorporating cross-linked polymer backings with controlled-release coatings to achieve predictable failure modes. These tapes serve primary industrial purposes in pharmaceutical serialization, food integrity assurance, and high-value electronics anti-counterfeiting. Cross-linked formulations command premium positioning due to superior environmental resistance and clean removal characteristics, while hot-melt variants occupy cost-sensitive retail packaging segments where moderate tamper indication suffices. Acrylic adhesives lead pharmaceutical applications for their broad temperature stability, and silicone chemistry extends into electronics protection where ultra-clean release is paramount.
FDA Drug Supply Chain Security Act requirements and EU MDR traceability mandates are compelling pharmaceutical packagers to specify tamper-evident systems with documented authentication protocols. REACH chemical restrictions and ECHA substance evaluations are reshaping adhesive formulation choices across European supply chains. ISO 21978 anti-counterfeiting standards provide voluntary benchmarks that major buyers increasingly embed in procurement specifications. Stakeholders must monitor evolving serialization interoperability requirements between regional regulatory frameworks.
Market Dynamics
Pharmaceutical serialization mandates are compressing procurement cycles and forcing tape vendors to validate cold-chain performance documentation before contract qualification. FDA Drug Supply Chain Security Act and EU MDR traceability requirements have transformed tamper-evident sealing from a packaging accessory into a compliance-critical component.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Mandates unit-level traceability for prescription drugs, compelling pharmaceutical packagers to specify tamper-evident systems with documented authentication protocols.
- Cross-linked polymer formulations:Deliver superior environmental resistance and clean removal characteristics, commanding premium positioning in high-security pharmaceutical applications.
- Germany's pharmaceutical manufacturing corridor:Concentrates demand for EU MDR-compliant tamper-evident solutions, driving volume procurement from contract packaging operations.
Market Restraints
- Acrylic adhesive input volatility:Petroleum-derived monomer costs fluctuate with energy markets, compressing margins for tape converters.
- European supply concentration:REACH chemical restrictions and ECHA substance evaluations limit adhesive formulation choices, creating dependency on approved chemical suppliers.
- Hot-melt substitution ceiling:Moderate tamper indication from lower-cost alternatives caps pricing power in retail packaging segments.
Strategic Opportunities
- India's pharmaceutical export hub:CDSCO traceability requirements are tightening, creating demand for validated cold-chain tamper-evident systems in generic drug distribution.
- Blockchain-converged authentication:Combines physical void pattern tapes with digital verification, enabling serialization interoperability across regional regulatory frameworks.
- Direct-to-pharmacy distribution:Bypasses wholesale intermediaries, requiring tape vendors to establish technical service relationships with hospital procurement.
Industry Challenges
- ISO 21978 certification timelines:Anti-counterfeiting standard validation requires 12-18 month documentation cycles, delaying market entry for new formulations.
- Legacy serialization system integration:Pharmaceutical packagers operate mixed-equipment environments, complicating tape-to-line compatibility verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Void Pattern Tamper-Evident Tapes Market |
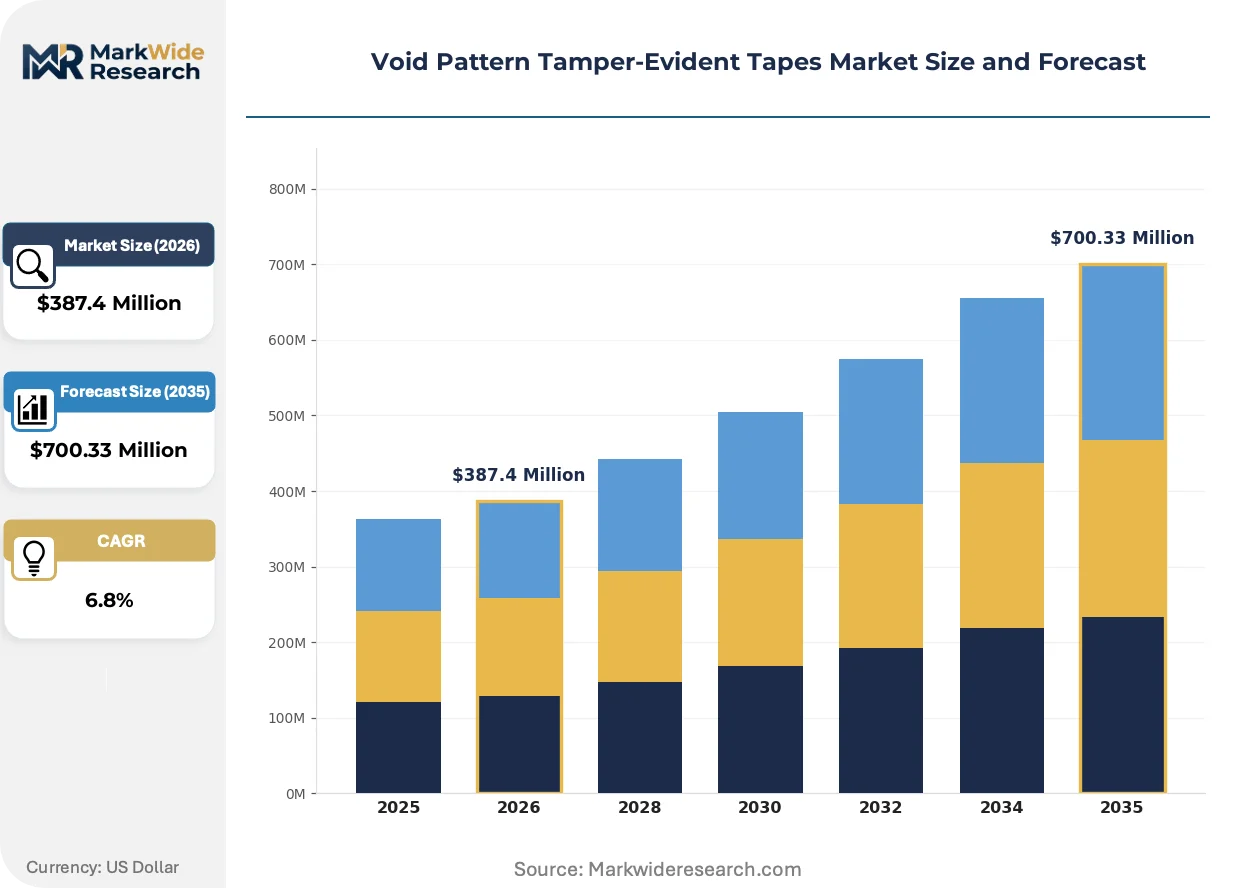
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $700.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-Linked, Hot-Melt, Acrylic, Silicone End User: Food Packaging, Pharmaceutical, Retail Packaging, Electronics Application: Sealing, Security, Branding, Protection Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | 3M Company, Avery Dennison, CCL Industries, Tesa SE, Intertape Polymer, TydenBrooks, Shosky Security, Ruilisibo Technology, Longding New Material Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Void Pattern Tamper-Evident Tapes Market Evolving Landscape
Adhesive chemistry and digital authentication are converging to redefine tamper-evident tape value propositions. Manufacturers are embedding sensor-responsive layers and cloud-linked verification to meet pharmaceutical traceability mandates.
Micro-encapsulated indicator systems are modularizing tamper detection across temperature-sensitive pharmaceutical shipments. Cold-chain logistics operators in Germany and the United States are adopting these constructions to satisfy FDA and EMA documentation requirements. The technology is modularizing supplier qualification criteria, separating vendors with validated thermal performance from commodity tape producers.
EU MDR traceability mandates are forcing pharmaceutical packagers to maintain electronic records linking tamper-evident seals to individual product units. The regulation requires documented authentication protocols for Class IIa and higher medical devices. Generic drug distributors in the United States are responding by embedding procurement specifications with explicit tape performance benchmarks.
Hospital procurement departments are consolidating supplier lists around vendors offering combined physical-digital authentication platforms. Group purchasing organizations are displacing fragmented buying across individual pharmacy departments. This concentration is most visible in the United States, where three major GPOs control pharmaceutical distribution to over half of acute care facilities.
Void Pattern Tamper-Evident Tapes Market Segmentation
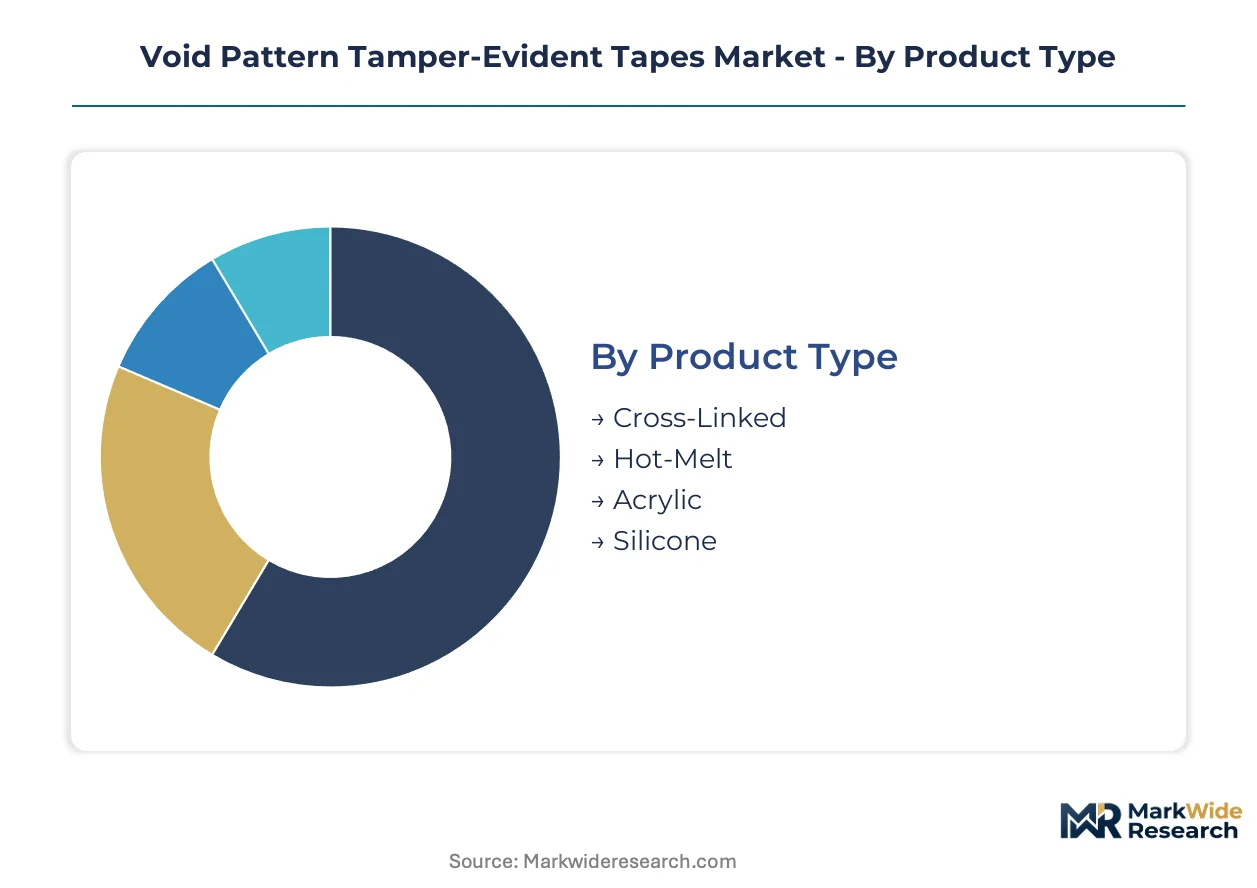
Void pattern tamper-evident tapes fragment across adhesive chemistry, end-use compliance intensity, and channel control. Procurement teams in pharmaceutical and food packaging verticals apply divergent qualification criteria that reshape competitive positioning within each segment cluster.
Product Type:
Cost tier separates commodity converters from premium specification holders.
- Cross-Linked:Cross-linked polymer backings incorporate controlled-release coatings for predictable fracture mechanics. Pharmaceutical contract packagers in Germany specify these constructions for EU MDR-compliant cold-chain documentation, paying premiums for validated thermal performance envelopes.
- Hot-Melt:Hot-melt adhesives rely on thermoplastic elastomer formulations that soften under heat exposure. Retail packaging segments in the United States absorb volume here, where moderate tamper indication suffices and procurement prioritizes unit cost over authentication depth.
- Acrylic:Acrylic pressure-sensitive adhesives deliver broad temperature stability across -40°C to 150°C operational windows.
- Silicone:Silicone chemistry enables ultra-clean release characteristics for electronics protection applications.
Cross-linked formulations lead volumes today; silicone is gaining share fastest in precision electronics.
End User:
Application maturity dictates margin structure and certification burden.
- Pharmaceutical:FDA Drug Supply Chain Security Act mandates unit-level traceability, forcing packagers to document authentication protocols for every seal application. Serialization interoperability requirements compress vendor qualification timelines to 12-18 months.
- Food Packaging:Cold-chain integrity assurance drives specification toward indicator-integrated tapes. Logistics operators in the United States deploy these for FDA Food Safety Modernization Act compliance documentation.
- Retail Packaging:Cost-sensitive segments favor hot-melt constructions with basic void pattern visibility.
- Electronics:Anti-counterfeiting requirements for high-value components demand residue-free removal.
Pharmaceutical leads volumes today; electronics is climbing the fastest on semiconductor supply chain security investments.
Application:
Functional depth determines adhesive specification and pricing tier.
- Security:Multi-layer constructions embed micro-encapsulated indicators that respond to thermal, chemical, or mechanical tampering attempts. Hospital procurement departments in the United States consolidate supplier lists around vendors offering combined physical-digital authentication platforms.
- Sealing:Primary closure functions dominate commodity volume, with generic drug distributors specifying minimum void pattern visibility standards.
- Branding:Custom-printed void patterns integrate corporate identity with tamper indication.
- Protection:Environmental barrier properties complement tamper evidence for sensitive electronics shipments.
Sealing leads volumes today; security is expanding most quickly on pharmaceutical traceability mandates.
Distribution Channel:
Customer scale and technical service requirements fragment channel control.
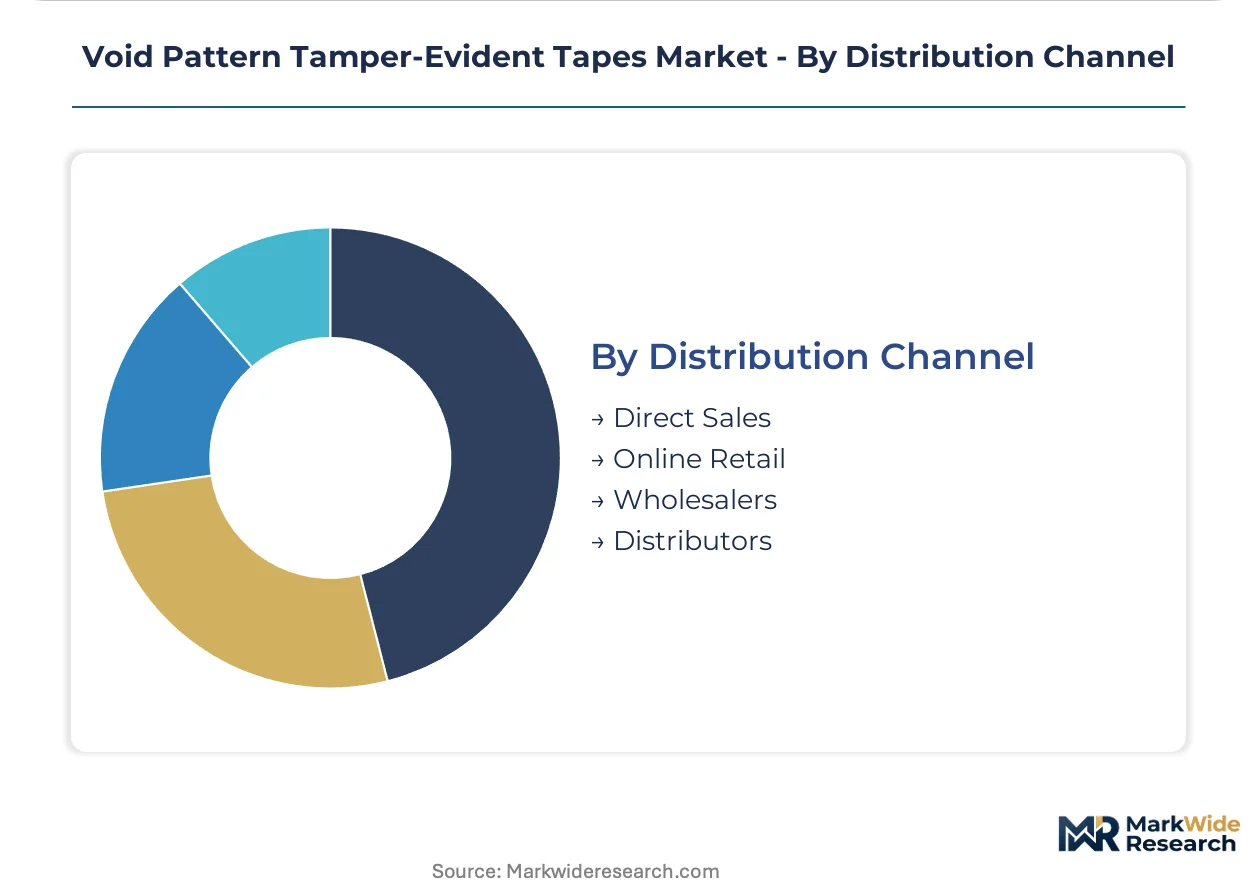
- Direct Sales:Tape vendors maintain technical service relationships with pharmaceutical contract packagers and group purchasing organizations. Three major GPOs in the United States control distribution to over half of acute care facilities, concentrating procurement leverage.
- Distributors:Regional converters stock standard widths and adhesive constructions for immediate availability.
- Wholesalers:Volume aggregation serves mid-tier retail packaging accounts with limited specification complexity.
- Online Retail:E-commerce channels capture small-lot demand from specialty electronics manufacturers and independent pharmacies.
Direct sales leads volumes today; distributors are gaining share fastest on inventory localization strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical manufacturing corridor commands premium tape specifications, while the United States generic drug distribution hub drives volume procurement at differentiated price points. Regulatory divergence between FDA serialization mandates and EU MDR traceability requirements creates distinct qualification barriers across Atlantic markets. Cold-chain logistics operators in both jurisdictions now embed tamper-evident sealing documentation into standard procurement protocols.
United States
Generic drug distributors in the US absorb substantial tape volumes as FDA Drug Supply Chain Security Act deadlines compress vendor qualification timelines. Three major group purchasing organizations control pharmaceutical distribution to over half of acute care facilities, concentrating procurement leverage around vendors with validated authentication platforms. Hospital procurement departments in the Midwest and Southeast are consolidating supplier lists toward combined physical-digital authentication systems.
Germany
Contract packaging operations along the Rhine-Ruhr and Bavarian pharmaceutical corridors specify EU MDR-compliant cold-chain documentation for Class IIa and higher medical devices. ECHA substance evaluations under REACH restrictions limit adhesive formulation choices, creating dependency on approved chemical suppliers with documented environmental resistance data. Frankfurt and Munich logistics hubs are deploying micro-encapsulated indicator systems for temperature-sensitive pharmaceutical shipments.
India
Pharmaceutical export operations in Gujarat and Maharashtra face tightening CDSCO traceability requirements for cold-chain generic drug distribution. Domestic tape converters are qualifying cross-linked polymer constructions to meet documentation standards for European and North American destination markets. Hyderabad and Ahmedabad manufacturing clusters are integrating tamper-evident sealing into serialization workflows ahead of regulatory deadlines.
China
Electronics protection applications in the Yangtze River Delta and Pearl River Delta drive demand for silicone-based ultra-clean release formulations. NMPA pharmaceutical serialization pilots are expanding procurement specifications toward documented authentication protocols in Shanghai and Suzhou contract packaging facilities. Domestic producers are qualifying pressure-sensitive adhesive constructions for semiconductor supply chain security investments.
Switzerland
High-value pharmaceutical manufacturing in Basel and Zurich corridors commands premium positioning for validated thermal performance envelopes. Swissmedic medical device regulations align with EU MDR traceability mandates, requiring electronic records linking tamper-evident seals to individual product units. Precision packaging operations are specifying cross-linked formulations with controlled-release coatings for predictable fracture mechanics.
Void Pattern Tamper-Evident Tapes Market Competitive Landscape
North American adhesive science conglomerates anchor the premium tier; European specialty coating houses hold regulatory compliance breadth. The vendor base separates into three distinct strata: multinational diversified materials groups with pharmaceutical validation histories, regional converters serving cost-sensitive retail segments, and emerging Asian producers capturing electronics protection volumes. Consolidation pressure concentrates among mid-tier distributors as direct technical service relationships displace fragmented wholesale channels. Backward integration into polymer backing production and captive supply of cross-linked formulations represent dominant competitive moves.
Within the multinational diversified tier, 3M Company and Avery Dennison occupy positions exemplifying adhesive science depth and North American channel control respectively. Tesa SE represents European regulatory compliance specialization. These three anchors demonstrate how geographic origin and corporate structure correlate with archetype positioning—diversified materials groups with pharmaceutical validation histories versus regional converters with inventory localization strategies.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison |
| CCL Industries |
| Tesa SE |
| Intertape Polymer |
| TydenBrooks |
| Shosky Security |
| Ruilisibo Technology |
| Longding New Material Technology |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU MDR-validated cross-linked formulations and commodity hot-melt alternatives manifests in both pricing power and supply chain configuration, with pharmaceutical contract packagers in Germany paying substantial premiums for documented cold-chain performance while retail distributors in the United States absorb volume at compressed margins.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for silicone-based ultra-clean release formulations, intensifying cost competition in electronics protection segments. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade constructions with ISO 21978 documentation from basic retail packaging alternatives. Price differentiation hinges on thermal performance envelope breadth and regulatory certification depth. Cost compression in hot-melt segments is intensifying because petroleum-derived monomer costs fluctuate with energy markets. Generic drug distributors in the United States exhibit highest price sensitivity, while Swiss precision packaging operations show least elasticity.
Supply Chain Analysis
Freight cost volatility from Middle East petrochemical feedstocks to European coating facilities is compressing margins for acrylic adhesive converters. Manufacturing concentrates in Germany, the United States, and China, with cross-linked polymer backing production anchored in the Rhine-Ruhr corridor and silicone chemistry development centered in the Yangtze River Delta. Raw material sourcing draws from Saudi Arabian petrochemical complexes, German specialty chemical producers, and Chinese silane monomer manufacturers. Single-source vulnerability around ECHA-approved adhesive formulations under REACH restrictions creates procurement bottlenecks. Distribution runs through direct technical service relationships with pharmaceutical contract packagers and group purchasing organizations, bypassing fragmented wholesale channels for high-specification volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Void pattern tamper-evident tapes represent a late-cycle quality story as pharmaceutical serialization mandates force procurement toward premium specifications with validated authentication protocols, displacing commodity alternatives in high-compliance end uses.
For Market Incumbents: Extend regulatory compliance breadth by qualifying cross-linked formulations for CDSCO traceability requirements in India's pharmaceutical export corridor, while anchoring North American channel control through direct relationships with the three major group purchasing organizations that dominate hospital procurement. Backward integration into polymer backing production defends margin position against acrylic adhesive input volatility. Certification investment in ISO 21978 anti-counterfeiting standards creates switching costs for pharmaceutical contract packagers. For New Entrants and Emerging Players: FDA Drug Supply Chain Security Act implementation in the United States opens a window for specialized converters offering combined physical-digital authentication platforms to hospital procurement departments consolidating supplier lists. India's pharmaceutical manufacturing clusters in Gujarat and Maharashtra present the most penetrable geography, with domestic tape converters still qualifying cross-linked constructions for European and North American destination markets. A technical service partnership model with contract packaging operations offers the strongest go-to-market angle, displacing inventory-heavy distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier distributors lack direct technical service capabilities and pharmaceutical validation histories, creating acquisition opportunities for regional converters with cold-chain documentation expertise. Long-term viability centers on adhesive science depth and regulatory compliance breadth rather than commodity volume scale. Acquisition target archetype: European specialty coating houses with EU MDR-compliant formulation libraries and established relationships with Rhine-Ruhr pharmaceutical corridors. The signal to watch is CDSCO enforcement timelines in India, which will accelerate qualification demands for export-oriented manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Backing Production | Captures margin from petrochemical feedstocks while securing supply continuity for cross-linked formulations. |
| ISO 21978 Certification Investment | Creates 12-18 month qualification barriers for pharmaceutical contract packagers seeking anti-counterfeiting compliance. |
| Direct Technical Service Relationships with GPOs | Concentrates procurement leverage among three major US group purchasing organizations controlling hospital distribution. |
| Blockchain-Converged Authentication Platform Development | Combines physical void pattern tapes with digital verification for serialization interoperability across FDA and EU MDR frameworks. |
| Capacity Expansion in India's Pharmaceutical Export Corridor | Positions converters ahead of CDSCO traceability enforcement for cold-chain generic drug distribution to European markets. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with pharmaceutical contract packaging executives, adhesive R&D directors at tape converters, hospital procurement managers within group purchasing organizations, and cold-chain logistics operators. Secondary validation draws from FDA Drug Supply Chain Security Act guidance documents, EMA serialization implementation reports, ECHA substance evaluation databases, and customs trade data for pressure-sensitive adhesive imports. Bottom-up demand modeling from end-use segments triangulates against top-down supply-side capacity assessments.
Granularity-level framing applies country-specific regulatory cluster modeling for pharmaceutical traceability mandates, with adhesive chemistry segmentation at the formulation level and distribution channel analysis at the account-type tier. CAGRs derive from unit-volume projections calibrated to pharmaceutical serialization deadline phasing and electronics supply chain security investment cycles. Forecast inputs include EU MDR implementation timelines, REACH chemical restriction evolution, and semiconductor fabrication capacity expansion in the Yangtze River Delta.
Revisions become necessary when FDA enforcement discretion shifts, EU MDR traceability mandates expand to additional device classes, or acrylic adhesive feedstock costs experience sustained volatility outside historical bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Industrial Tapes Market
Tapes
Pipe Anti-Corrosion Tape Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Flatback Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Tape Stretching Line Market
Tapes
Paper Masking Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Replica Tapes Market
Tapes
Masking Tape Market
Tapes
Painting Masking Tapes Market
Tapes
Tape Backing Materials Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Unidirectional Tapes Market