
 Gamma-Butyrolactone (GBL) Market | 2026-2036
Gamma-Butyrolactone (GBL) Market Size, Share, and Industry Trends Forecast 2026-2036
Gamma-Butyrolactone (GBL) Market Analytics
Asset-light leasing models for specialty chemical production capacity are reshaping competitive entry in the GBL sector. BASF SE leverages its integrated Ludwigshafen complex to sustain captive butyrolactone supply chains. Balaji Amines anchors South Asian production with amine chemistry adjacencies. Mitsubishi Chemical Corporation differentiates through pharmaceutical-grade certification depth in Japan.
Gamma-butyrolactone is a hygroscopic cyclic ester with a boiling point of 204°C, manufactured via dehydrogenation of 1,4-butanediol over copper catalysts, serving primarily as a polar aprotic solvent and chemical intermediate. Industrial-grade GBL dominates volume throughput in agrochemical and electronics cleaning applications where purity thresholds remain permissive. Pharmaceutical-grade segments command premium positioning due to FDA and EMA precursor documentation requirements. The solvent application category leads absolute consumption, while intermediate usage for pyrrolidone derivatives captures faster growth in battery electrolyte and polymer additive markets.
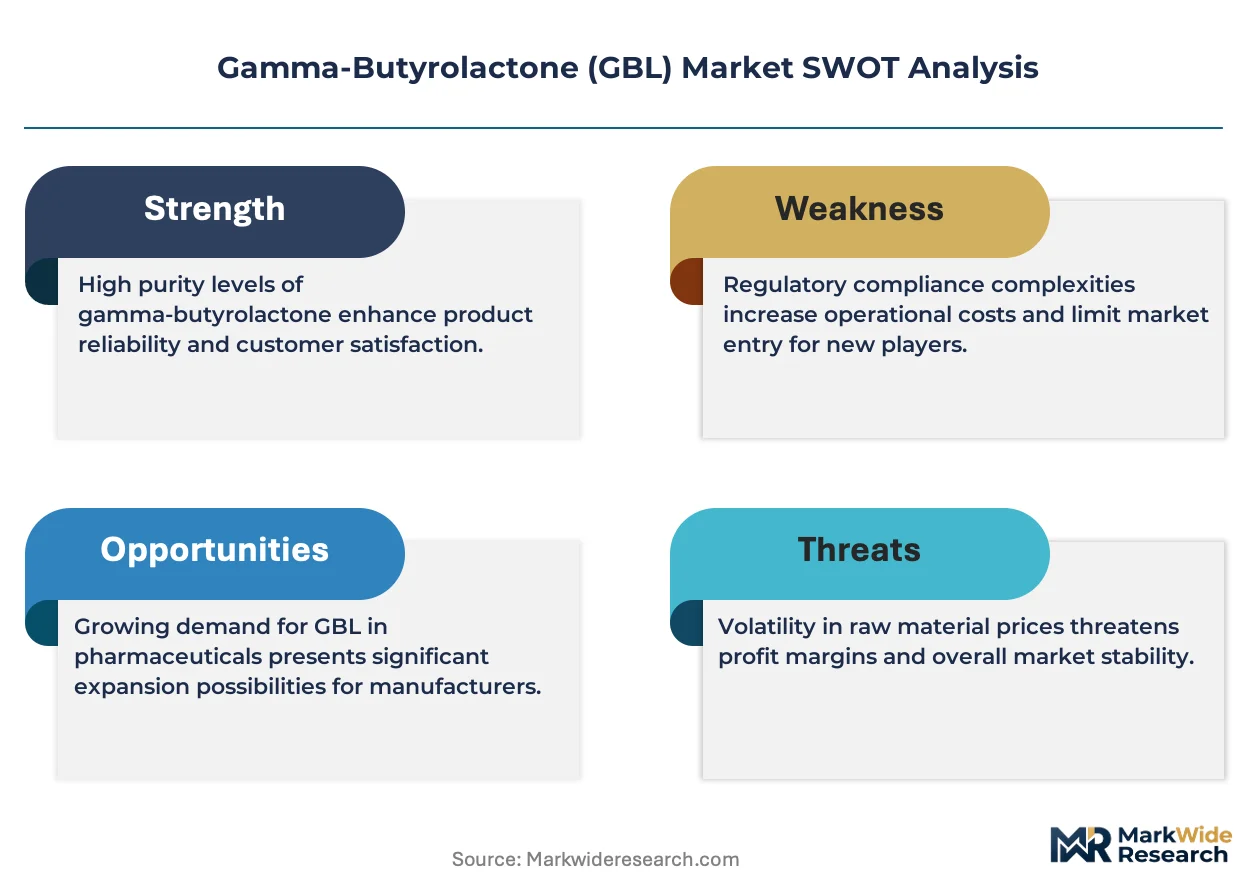
EPA regulates GBL under the Controlled Substances Act as a List I chemical precursor, requiring registration and transaction reporting that constrains US distribution channels. ECHA classifies the substance under REACH with reproductive toxicity restrictions that limit cosmetics-grade formulations in Europe. China's SAMR and MEE enforce dual-use chemical export licensing that shapes cross-border trade patterns. Stakeholders must monitor precursor scheduling expansions and green chemistry substitution mandates that could displace conventional GBL solvent applications before the forecast horizon closes.
Market Dynamics
Pharmaceutical-grade certification requirements and precursor chemical scheduling across multiple jurisdictions are fragmenting supply chains into compliant and non-compliant tiers, forcing manufacturers to choose between premium positioning and volume markets.
Growth Catalysts
- Battery electrolyte demand:Lithium-ion cell manufacturers in South Korea and Japan are expanding pyrrolidone derivative procurement for high-voltage electrolyte formulations, pulling GBL through the intermediate channel.
- REACH reproductive toxicity restrictions:ECHA's classification limits cosmetics-grade applications in Europe but creates captive demand from pharmaceutical and industrial solvent buyers with established compliance infrastructure.
- India's PLI scheme for active pharmaceutical ingredients:Domestic manufacturers are scaling dehydrogenation capacity to serve antibiotic and CNS drug synthesis, reducing import dependency.
Market Restraints
- 1,4-butanediol feedstock volatility:Butane-based BDO pricing fluctuates with natural gas liquid markets, compressing dehydrogenation margins for non-integrated producers.
- EPA List I chemical controls:Registration and transaction reporting requirements constrain distribution channel density in the United States, limiting spot market liquidity.
- Green solvent substitution:Bio-based polar aprotic alternatives from fermentation-derived 2-methyltetrahydrofuran are displacing industrial-grade GBL in electronics cleaning applications.
Strategic Opportunities
- Pharmaceutical-grade arbitrage:FDA and EMA documentation gaps between Indian and Chinese suppliers create margin expansion potential for certified producers serving regulated markets.
- Asset-light production leasing:Specialty chemical toll manufacturers in Germany's chemical processing corridor are offering dehydrogenation capacity to entrants without captive BDO supply.
- Solid-state battery electrolyte precursors:Polymer solid-electrolyte interphase formulations require ultra-high purity GBL derivatives, opening premium pricing tiers for purification technology leaders.
Industry Challenges
- Precursor diversion monitoring systems:Dual-use chemical tracking requirements under China's SAMR and MEE demand real-time supply chain visibility investments that smaller traders cannot fund.
- Pharmaceutical-grade certification timelines:FDA Drug Master File compilation and EMA CEP approval cycles extend 18-24 months, locking working capital before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gamma-Butyrolactone (GBL) Market |
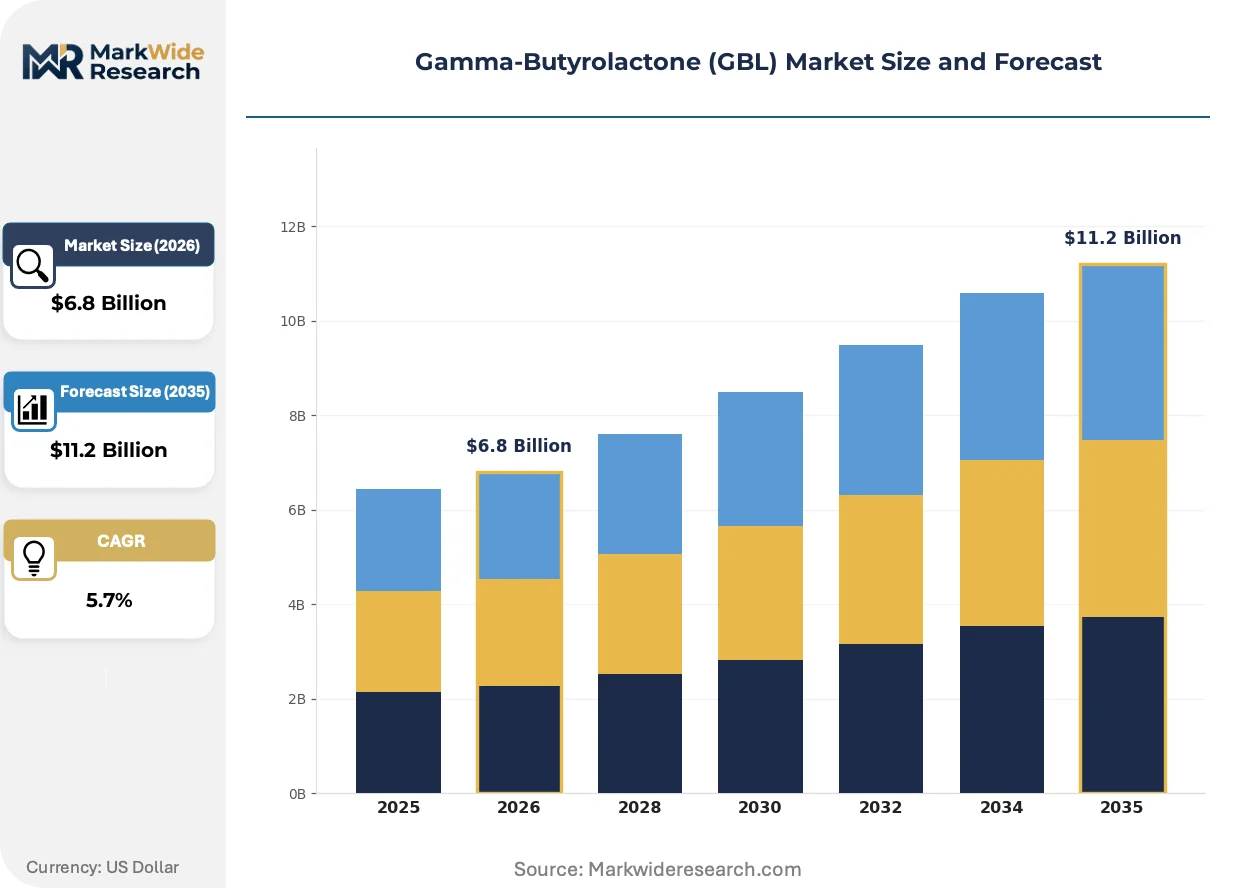
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetics Grade, Food Grade End Use Industry: Pharmaceuticals, Chemicals, Agriculture, Cosmetics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers Application: Solvent, Intermediate, Additive, Cleaner |
| Companies Covered | Dairen Chemical Corporation, Balaji Amines, BASF SE, Chang Chun Group, Zhejiang Realsun Chemical Co., Ltd., Ashland, Sipchem Company, Biosynth, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gamma-Butyrolactone (GBL) Market Evolving Landscape
Process intensification and digital supply chain verification are compressing production economics while regulatory technology investments reshape competitive entry barriers across the value chain.
Continuous flow dehydrogenation reactor technology replaces batch copper-catalyzed systems with microchannel designs that halve residence time and reduce thermal degradation byproducts. Specialty chemical producers in Ludwigshafen and Antwerp are retrofitting pilot lines for pharmaceutical-grade output. This process architecture is virtualizing the traditional scale economies that favored integrated petrochemical complexes.
China's NMPA tightened export licensing for dual-use chemical precursors in 2023, requiring end-user verification and destination country import authorization before shipment clearance. The measure redirected trade flows toward pre-qualified distributors with established compliance documentation. Pharmaceutical manufacturers in India and Southeast Asia now face extended lead times and are qualifying alternative suppliers in the Middle East.
Direct procurement relationships between GBL consumers and BDO-integrated producers are displacing merchant market intermediaries, particularly in battery electrolyte supply chains. Korean cathode material producers are signing offtake agreements with Middle Eastern BDO operators for captive dehydrogenation capacity. This channel consolidation concentrates in high-volume industrial applications where purity specifications remain permissive.
Gamma-Butyrolactone (GBL) Market Segmentation
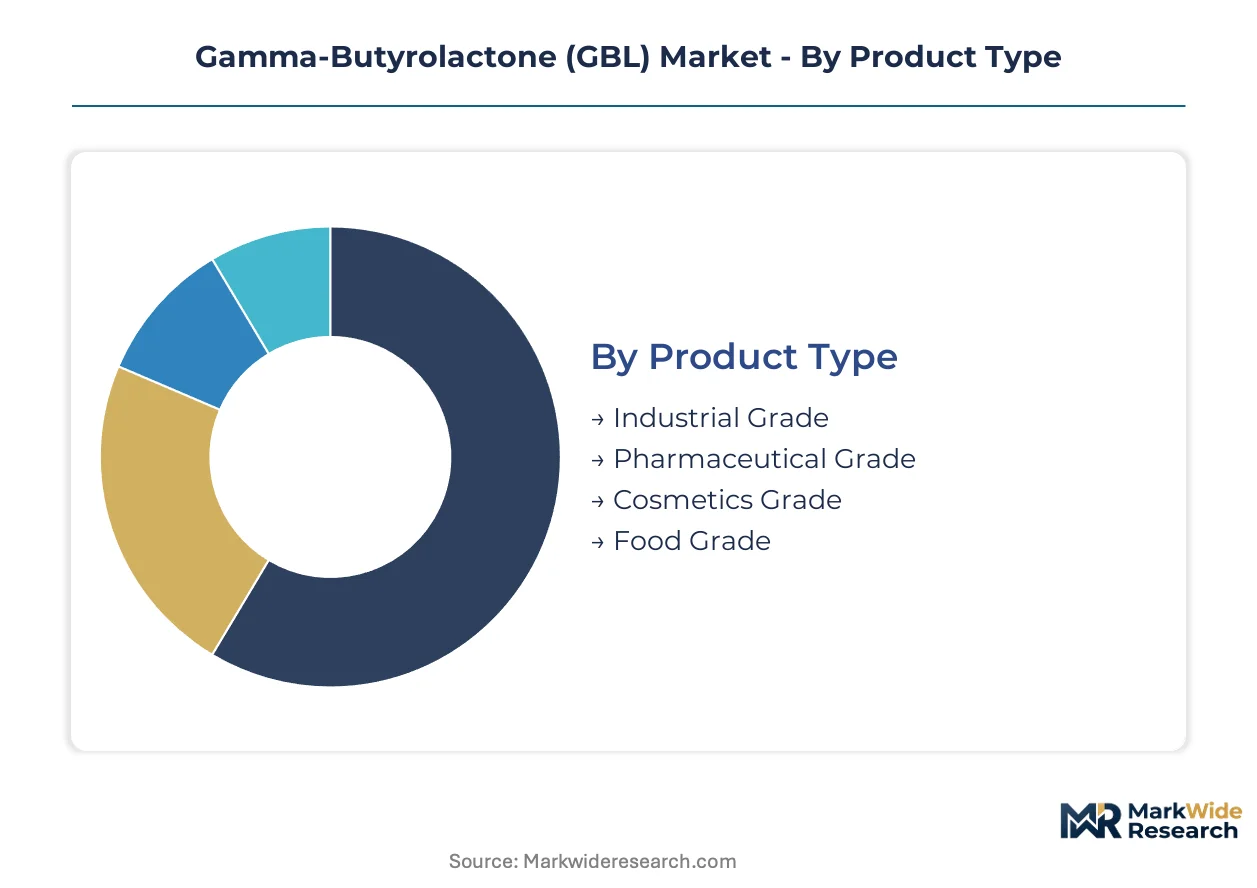
GBL procurement patterns diverge sharply across purity grades and regulatory exposure, with pharmaceutical and industrial buyers operating in parallel supply chains that rarely intersect. Segmentation clarity enables suppliers to align certification investments with margin capture potential.
Product Type:
After-sales service intensity escalates with regulatory documentation burden, as pharmaceutical-grade buyers demand batch-specific certificates of analysis and precursor tracking systems that industrial-grade customers rarely require.
- Industrial Grade:Purity thresholds of 99.0-99.5% serve agrochemical synthesis and electronics cleaning where permissive specifications enable multi-source procurement. German chemical processors along the Ludwigshafen corridor anchor volume consumption for polymer intermediate production.
- Pharmaceutical Grade:Ultra-purity specifications exceeding 99.9% with comprehensive heavy metal and residual solvent documentation. FDA Drug Master File and EMA Certificate of Suitability requirements concentrate demand among CDSCO-registered Indian manufacturers expanding API synthesis capacity under PLI scheme incentives.
- Cosmetics Grade:REACH reproductive toxicity restrictions constrain European formulation use, limiting viable demand to Asian personal care markets with less stringent precursor classifications.
- Food Grade:Minimal commercial traction given GBL's scheduled precursor status; limited to specialized flavor extraction applications with national food safety regulator oversight.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is expanding most quickly.
End Use Industry:
Cost tier differentiation separates commodity chemical buyers from premium pharmaceutical procurement, with the latter absorbing 40-60% price premiums for documentation packages that satisfy DEA and EMA audit requirements.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis for antibiotics and CNS therapeutics drives specification intensity. Indian manufacturers under CDSCO oversight are scaling captive dehydrogenation to reduce import dependency.
- Chemicals:Pyrrolidone derivative production for battery electrolyte formulations pulls GBL through intermediate channels. Korean cathode material producers are signing direct offtake agreements with Middle Eastern BDO-integrated suppliers.
- Agriculture:Agrochemical solvent applications tolerate industrial-grade purity, with procurement concentrating through distributor networks rather than direct manufacturer relationships.
- Cosmetics:ECHA reproductive toxicity classification has collapsed European demand, redirecting residual volume toward Southeast Asian formulation houses with less restrictive precursor controls.
Pharmaceuticals commands the steepest price premiums. Chemicals is gaining share fastest as battery electrolyte demand accelerates.
Distribution Channel:
Volume concentration favors direct procurement in high-throughput chemical and battery material applications, while regulatory fragmentation pushes pharmaceutical buyers toward specialized distributors with established precursor compliance infrastructure.
- Direct Sales:Dominates battery electrolyte and polymer intermediate supply chains where Korean and Japanese cathode producers negotiate multi-year offtake agreements with BDO-integrated GBL manufacturers.
- Distributors:Essential for pharmaceutical-grade procurement in regulated markets, with pre-qualified intermediaries absorbing DEA registration and transaction reporting burdens that spot market traders cannot fund.
- Online Retail:Severely constrained by EPA List I chemical controls and SAMR dual-use licensing requirements; limited to industrial-grade solvent sales with end-user verification protocols.
- Wholesalers:Concentrated in emerging market industrial applications where documentation requirements remain permissive and multi-source aggregation reduces procurement overhead.
Direct Sales captures the largest volume flows. Distributors are climbing the fastest as regulatory documentation demands intensify.
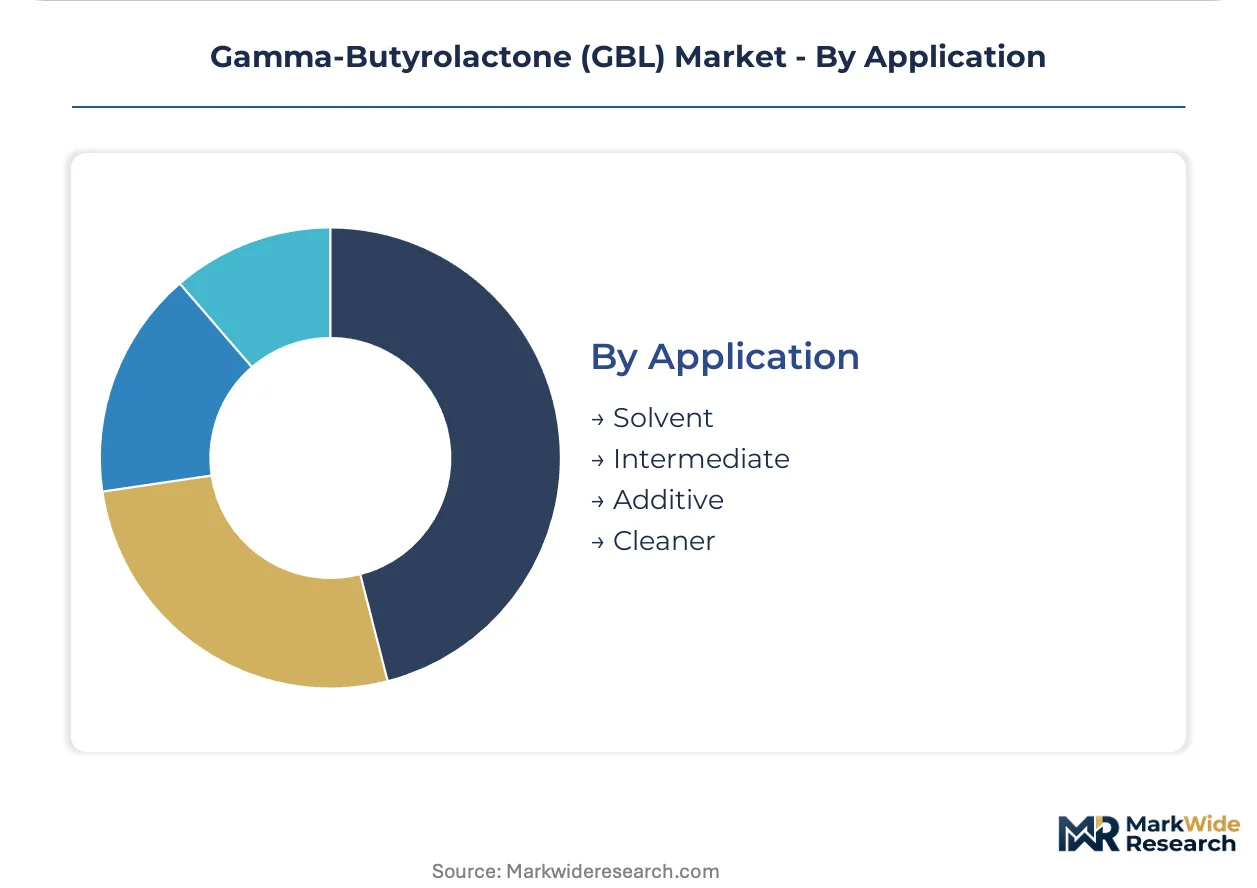
Application:
Customer type segmentation separates specification-tolerant industrial buyers from pharmaceutical manufacturers whose validation protocols demand dedicated production campaigns and segregated storage infrastructure.
- Solvent:Polar aprotic characteristics serve agrochemical formulation and electronics cleaning where industrial-grade purity suffices. Bio-based 2-methyltetrahydrofuran alternatives are displacing volume in European electronics applications.
- Intermediate:Pyrrolidone and N-methylpyrrolidone synthesis for battery electrolyte and polymer additive markets drives the fastest demand expansion. Japanese and Korean lithium-ion cell manufacturers specify ultra-low moisture content for high-voltage formulations.
- Additive:Polymer plasticizer and resin modifier applications concentrate in German automotive supply chains with REACH-compliant documentation requirements.
- Cleaner:Electronics and precision equipment degreasing faces green chemistry substitution pressure from aqueous and semi-aqueous alternatives in EPA-regulated US markets.
Solvent remains the volume leader. Intermediate is gaining share fastest as solid-state battery electrolyte precursor demand materializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is accelerating domestic dehydrogenation capacity expansion. China's NMPA tightened precursor chemical controls in 2023, redirecting trade flows toward compliant suppliers. Germany's chemical processing corridor anchors industrial-grade solvent demand.
United States
Battery electrolyte manufacturers in the Pacific Northwest are expanding pyrrolidone derivative procurement for lithium-ion cell production. EPA List I chemical controls under the Controlled Substances Act constrain distribution channel density and limit spot market liquidity. The Gulf Coast petrochemical corridor hosts integrated BDO-GBL operations serving polymer intermediate markets.
Germany
REACH reproductive toxicity restrictions have collapsed cosmetics-grade applications but fortified captive demand from pharmaceutical and industrial solvent buyers. ECHA classification enforcement limits formulation use in personal care products. The Ludwigshafen chemical complex sustains captive butyrolactone supply chains through integrated dehydrogenation capacity.
China
SAMR and MEE dual-use chemical export licensing requirements are reshaping cross-border trade patterns toward pre-qualified distributors. NMPA's 2023 tightening of precursor controls demands end-user verification and destination country import authorization. The Yangtze River Delta concentration of specialty chemical producers is retrofitting lines for pharmaceutical-grade output.
India
CDSCO-registered manufacturers are scaling dehydrogenation capacity under PLI scheme incentives to serve antibiotic and CNS drug synthesis. Domestic API production targets are reducing import dependency on Chinese GBL supplies. The Maharashtra-Gujarat pharmaceutical belt is anchoring South Asian production expansion with amine chemistry adjacencies.
South Korea
Cathode material producers are signing direct offtake agreements with Middle Eastern BDO operators for captive dehydrogenation capacity. MFDS pharmaceutical-grade certification requirements are fragmenting procurement into compliant and non-compliant tiers. The Busan-Ulsan industrial corridor is concentrating battery electrolyte precursor demand.
Gamma-Butyrolactone (GBL) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply chains. BASF SE leverages integrated petrochemical complexes to sustain captive butyrolactone production. Balaji Amines anchors South Asian capacity with amine chemistry adjacencies. Mitsubishi Chemical Corporation occupies the pharmaceutical-grade certification tier in Japan. Competitive moves concentrate on backward integration into BDO feedstock and pharmaceutical-grade capacity expansion.
Among Asia-Pacific-based producers, Dairen Chemical Corporation and Chang Chun Group exemplify the integrated petrochemical archetype with regional BDO-GBL coordination. Zhejiang Realsun Chemical Co., Ltd. represents the Chinese specialty chemical segment navigating SAMR dual-use licensing requirements. These three occupy positions across the volume-premium spectrum, with certification depth separating pharmaceutical-grade suppliers from industrial-grade commodity players.
| Leading Market Players |
|---|
| Dairen Chemical Corporation |
| Balaji Amines |
| BASF SE |
| Chang Chun Group |
| Zhejiang Realsun Chemical Co., Ltd. |
| Ashland |
| Sipchem Company |
| Biosynth |
| Mitsubishi Chemical Corporation |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's integrated chemical complex anchors European GBL capacity, with BASF's captive dehydrogenation operations translating feedstock control into pricing power over downstream pharmaceutical and polymer intermediate buyers. This concentration enables premium capture in pharmaceutical-grade tiers while industrial-grade spot markets face margin compression from Middle Eastern BDO-integrated entrants.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial-grade tiers, with FDA Drug Master File and EMA Certificate of Suitability documentation adding 40-60% price premiums over commodity solvent grades. Three-tier pricing structure across pharmaceutical, industrial, and cosmetics grades reflects purity thresholds and regulatory compliance burdens. Cost compression in industrial-grade segments is intensifying because bio-based 2-methyltetrahydrofuran alternatives displace volume in electronics cleaning applications. Agrochemical solvent buyers exhibit highest price sensitivity, while battery electrolyte manufacturers absorb premiums for ultra-low moisture specifications.
Supply Chain Analysis
1,4-butanediol feedstock availability in China, Germany, and Saudi Arabia shapes GBL production economics, with butane-based BDO pricing tethered to natural gas liquid markets. The value chain draws from copper catalyst suppliers, dehydrogenation technology licensors, and batch-specific certification laboratories. Single-source vulnerability concentrates in pharmaceutical-grade purification capacity, where qualified producers in India and Japan maintain tight allocation. Distribution runs through direct offtake agreements for battery electrolyte volumes and specialized precursor-compliant distributors for regulated pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery electrolyte precursor demand represents a high-growth disruption, with polymer solid-electrolyte interphase formulations requiring ultra-high purity GBL derivatives that command premium pricing tiers.
For Market Incumbents: Entrench pharmaceutical-grade certification moats by accelerating FDA Drug Master File submissions for Indian and Southeast Asian production lines before CDSCO-registered competitors close documentation gaps. Backward integration into BDO feedstock insulates margin structures from natural gas liquid volatility that compresses non-integrated dehydrogenation economics. For New Entrants and Emerging Players: Asset-light toll manufacturing arrangements in Germany's chemical processing corridor represent the most penetrable entry point for industrial-grade volume without captive BDO investment. Target South Korean cathode material producers with direct offtake proposals for pyrrolidone derivative supply, leveraging Middle Eastern BDO partnerships to bypass Chinese SAMR export licensing bottlenecks. For Investors and Strategic Acquirers: Long-term, this sits as a specialty chemical consolidation play because precursor chemical scheduling across EPA, ECHA, and SAMR jurisdictions fragments supply chains into compliant and non-compliant tiers that favor scaled documentation infrastructure. Acquisition candidates with established DEA registration and EMA CEP approval cycles command scarcity premiums. Monitor NMPA dual-use licensing enforcement intensity as the signal for trade flow redirection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BDO Feedstock | Captive butane supply from Gulf Coast petrochemical corridors insulates dehydrogenation margins from NGL volatility. |
| Pharmaceutical-Grade Capacity Expansion | CDSCO-registered Indian producers under PLI incentives are scaling API-synthesis dedicated dehydrogenation lines. |
| Long-term Supply Agreement | Korean cathode material producers are locking multi-year offtake with Middle Eastern BDO-integrated operators. |
| Green Manufacturing Transition | Continuous flow microchannel reactor retrofits halve residence time and reduce thermal degradation byproduct formation. |
| Joint Venture | Specialty chemical toll manufacturers in Antwerp and Ludwigshafen are offering dehydrogenation capacity to certification-focused entrants. |
Research Methodology
Cross-validation between primary interviews with plant managers, pharmaceutical procurement leads, and battery electrolyte R&D directors and secondary sources including customs/trade data, SEC 10-K filings, and ECHA REACH registration databases anchors the qualitative findings. Bottom-up capacity assessments across Yangtze River Delta and Maharashtra-Gujarat production clusters were reconciled with top-down demand modeling from pyrrolidone derivative consumption patterns.
Calibration against historical BDO-GBL margin spreads and precursor chemical trade flow disruptions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from electrolyte precursor demand trajectories and pharmaceutical API synthesis expansion rates under India's PLI scheme.
Practitioners should monitor EPA List I chemical scheduling expansions, ECHA green chemistry substitution mandates, and NMPA export licensing enforcement intensity for early signals requiring forecast revision. Cross-checking against ACC chemical production indices and CDSCO API registration databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Europe Organic Acid Market
Organic Chemicals
Ethyl Levulinate Market
Organic Chemicals
Aminophenol Market
Organic Chemicals
Cyclohexanone Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Alanine Market
Organic Chemicals
Chloroacetyl Chloride Market
Organic Chemicals
Ethylamine Market
Organic Chemicals
N-Hexyl Chloride Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
North America Cycloalkanes Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
Organic Coating Market