
 Expanded Polystyrene for Packaging Market | 2026-2036
Expanded Polystyrene for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Polystyrene for Packaging Market Foresight
Foodservice distributors are unwinding their historical reliance on institutional buyers as direct-to-consumer meal-kit brands expand protective packaging procurement. BASF SE leverages its integrated styrene monomer supply chain to secure feedstock cost advantages across European manufacturing hubs. NOVA Chemicals Corporation anchors North American production capacity with resin-grade specialization for molded cushioning applications. Dart Container Corporation dominates the food-contact segment through captive distribution networks serving quick-service restaurant chains.
Expanded polystyrene for packaging comprises a rigid, closed-cell thermoplastic foam manufactured through suspension polymerization of styrene monomer followed by pre-expansion of pentane-impregnated beads. The material delivers thermal resistance values near 0.033 W/m·K and compressive strengths of 70–700 kPa, making it indispensable for temperature-sensitive pharmaceutical shipments and shock-sensitive electronics transit. Rigid foam commands the largest value pool due to its entrenched role in appliance and electronics crating, while bead foam represents the fastest-expanding category as molded-shape customization penetrates medical device logistics. Thermal insulation applications concentrate margin capture in cold-chain segments where performance certification creates specification stickiness.
The EPA regulates volatile organic compound emissions from pentane blowing agents during EPS manufacturing, while the EU F-Gas Regulation and REACH framework constrain chemical inputs and mandate recyclability disclosures on packaging placed in European markets. FDA compliance for food-contact EPS surfaces adds testing burdens that favor established compounders with dedicated regulatory affairs functions. Stakeholders must monitor how extended producer responsibility schemes in California and New York reshape collection infrastructure economics for post-consumer foam recovery.
Market Dynamics
E-commerce fulfillment networks are compressing specification cycles for protective cushioning, forcing converters to reconcile legacy molded-shape capacity with on-demand customization requirements.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are redirecting capital toward recyclable foam alternatives, creating certified-recyclable product premiums.
- Cold-chain pharmaceutical logistics:Temperature-sensitive biologics shipments require validated thermal packaging, locking in demand for high-performance insulation formats.
- Bead foam molding automation:Robotics integration is reducing minimum order quantities for custom-shaped medical device packaging, opening mid-volume segments.
Market Restraints
- Styrene monomer price volatility:Benzene-ethylene feedstock swings compress converter margins unpredictably.
- European supply concentration:German and Belgian resin production clusters create single-source vulnerability for molded foodservice formats.
- REACH chemical restriction trajectory:ECHA's evolving substance evaluation list threatens pentane blowing agent continuity.
Strategic Opportunities
- India pharmaceutical exports:Cold-chain infrastructure gaps in Mumbai and Hyderabad corridors create specification voids for validated thermal shippers.
- Mechanical recycling integration:Densification and re-extrusion technologies are converging with collection network expansion to close post-consumer loops.
- Quick-commerce grocery channels:Fifteen-minute delivery platforms in São Paulo and Mexico City are generating insulated pouch demand outside traditional foodservice.
Industry Challenges
- Pentane handling certification:OSHA process safety management compliance requires specialized technician training that lags plant expansion timelines.
- Food-contact migration testing:FDA compliance documentation for new additive packages extends qualification cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Polystyrene for Packaging Market |
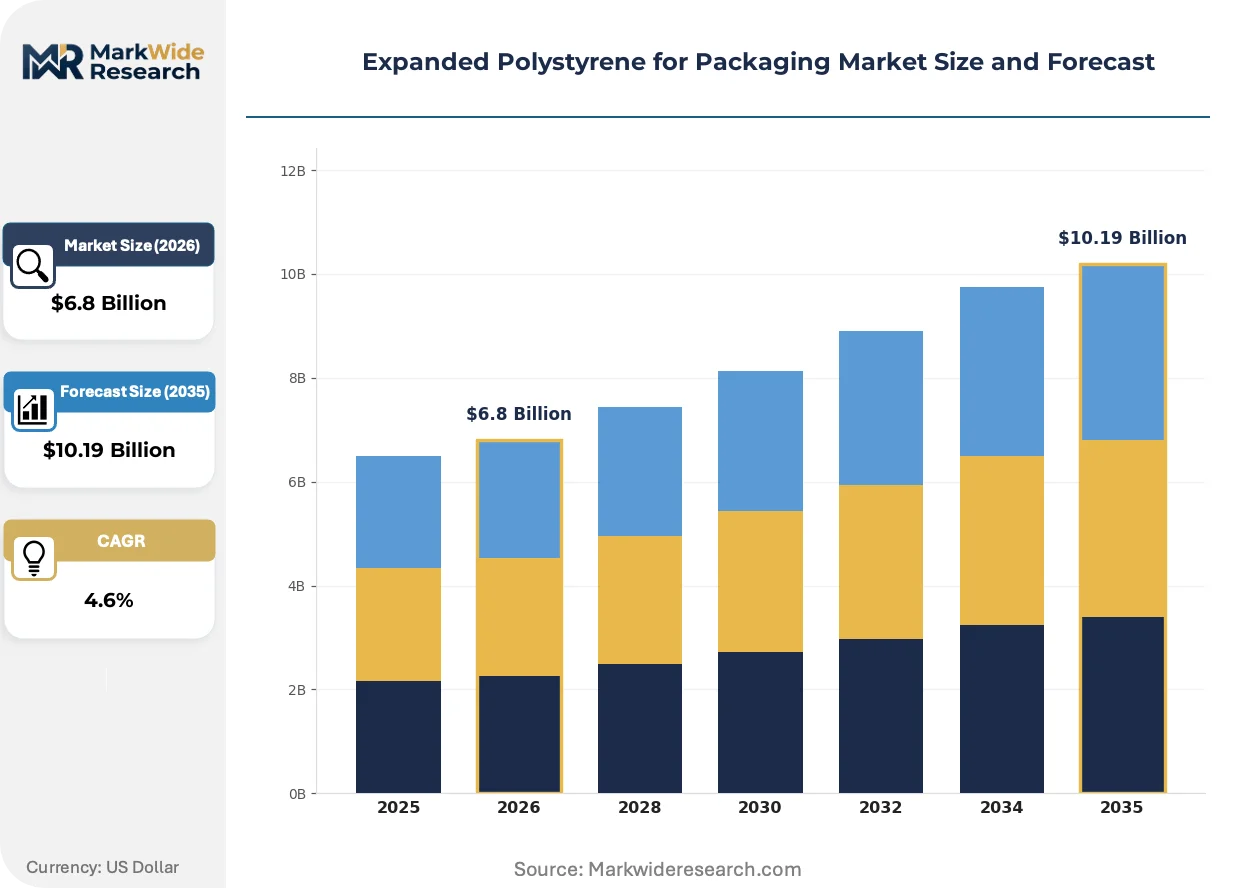
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Flexible Foam, Bead Foam, Fabricated Foam End User: Food Packaging, Electronics, Medical Devices, Consumer Goods Application: Thermal Insulation, Cushioning, Void Fill, Structural Support Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF SE, Kaneka Corporation, Synthos, Alpek SAB de CV, NOVA Chemicals Corporation, TotalEnergies SE, SABIC, Versalis S.p.A., Dart Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Polystyrene for Packaging Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are splitting the market between commodity disposables and performance-certified formats. Three developments are determining competitive positioning.
Bio-based styrene alternatives derived from lignin and agricultural waste streams are entering pilot production. Medical device logistics providers in Switzerland and the Netherlands are qualifying these materials for temperature-controlled shipments. The technology is bifurcating the supplier base into petrochemical-integrated incumbents and specialty biopolymer entrants.
REACH Article 33 disclosure requirements for substances of very high concern are forcing reformulation of flame-retardant additives in construction-adjacent packaging grades. Compounders serving electronics crating must now maintain dual stock-keeping units for EU and non-EU destinations. German appliance manufacturers are accelerating testing of halogen-free alternatives to preempt authorization sunset dates.
Direct material recovery arrangements between converters and quick-service restaurant chains are replacing arm's-length scrap markets. Franchise systems in California and New York are mandating reverse logistics participation as a procurement condition. This consolidation of collection channels is visible most acutely in the US Northeast, where extended producer responsibility legislation is compressing supplier qualification timelines.
Expanded Polystyrene for Packaging Market Segmentation
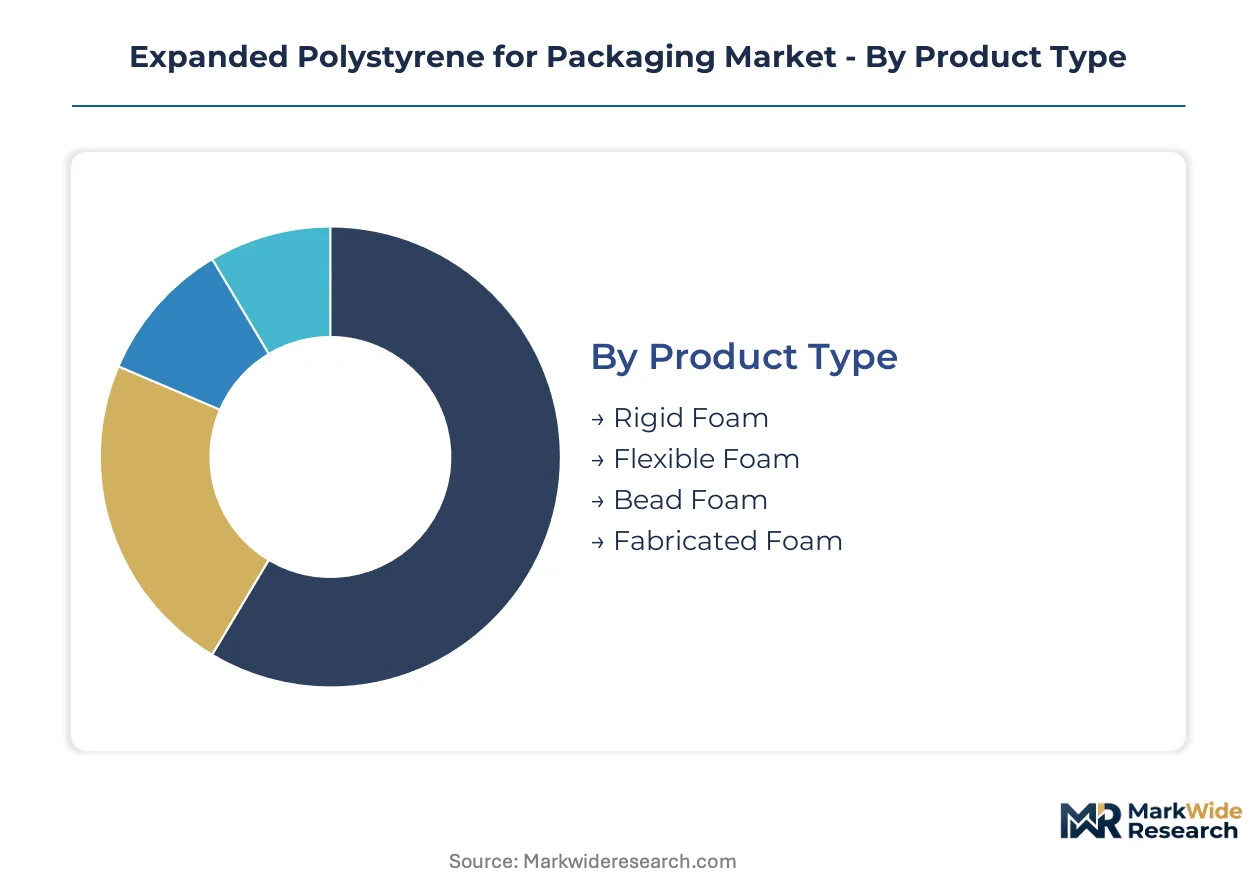
Segmentation in the expanded polystyrene packaging market reveals how substitution pressures from bio-based alternatives and paperboard formats concentrate differently across product architectures and end-use specifications. Understanding these fault lines enables suppliers to defend incumbent positions where performance certification creates stickiness versus retreating from commoditized segments.
Product Type:
Substitution pressure from molded pulp and starch-based foams weighs most heavily on commodity formats lacking thermal performance certification, while engineered grades with validated cold-chain specifications maintain specification lock-in.
- Rigid Foam:Closed-cell boards and blocks manufactured through block molding deliver compressive strengths of 70–700 kPa for appliance crating and electronics transit. German appliance manufacturers anchor volume demand for this format, though REACH flame-retardant restrictions are forcing additive reformulation cycles that extend qualification timelines.
- Bead Foam:Pre-expanded polystyrene beads molded into custom shapes through steam-chest fusion enable complex geometries for medical device logistics. Swiss and Netherlands pharmaceutical distributors are qualifying this format for temperature-controlled biologics shipments, where automation is compressing minimum order quantities for mid-volume segments.
- Flexible Foam:Low-density sheets and rolls provide surface protection for consumer goods transit. Quick-commerce grocery channels in São Paulo and Mexico City are generating insulated pouch demand outside traditional foodservice procurement patterns.
- Fabricated Foam:Die-cut and laminated components assembled from sheet stock serve niche electronics and display packaging applications. California extended producer responsibility mandates are reshaping collection economics for post-consumer recovery of this format.
Rigid foam anchors the volume base while bead foam gains share at the steepest rate as medical device logistics penetration accelerates.
End User:
Margin capture concentrates in segments where regulatory compliance creates specification stickiness and disqualifies lower-cost substitute materials.
- Food Packaging:Direct-contact trays, cups, and clamshells for quick-service restaurant chains and meal-kit distributors. FDA migration testing requirements for new additive packages extend qualification cycles, favoring established compounders with dedicated regulatory affairs functions.
- Electronics:Anti-static and cushioning formats for semiconductor and consumer electronics transit. RoHS compliance and halogen-free flame-retardant mandates in EU markets are splitting supplier bases into certified and non-certified tiers.
- Medical Devices:Validated thermal shippers for temperature-sensitive biologics and pharmaceutical distribution. Cold-chain infrastructure gaps in Mumbai and Hyderabad corridors create specification voids for exporters meeting EU and US regulatory standards.
- Consumer Goods:Protective formats for e-commerce fulfillment of household and personal care products. E-commerce networks are compressing specification cycles, forcing converters to reconcile legacy molded-shape capacity with on-demand customization requirements.
Food packaging retains the largest installed base while medical devices demonstrates the steepest expansion trajectory as pharmaceutical cold-chain requirements tighten globally.
Application:
Performance certification requirements segment the market between commodity disposables and specification-locked formats where substitution costs exceed material savings.
- Thermal Insulation:Cold-chain packaging for pharmaceuticals, fresh food, and temperature-sensitive chemicals. EU F-Gas Regulation and REACH framework constrain chemical inputs while mandating recyclability disclosures, redirecting investment toward recyclable foam alternatives with certified-recyclable premiums.
- Cushioning:Shock absorption for electronics, appliances, and industrial equipment transit. Bead foam molding automation is reducing minimum order quantities for custom-shaped protection, opening mid-volume segments previously served by standardized formats.
- Void Fill:Loose-fill and molded shapes for box-in-box protection of fragile goods. Loose-fill faces acute substitution pressure from paper-based alternatives in EU markets with aggressive extended producer responsibility schemes.
- Structural Support:Load-bearing inserts and corner posts for heavy-goods logistics. Compressive strength specifications for appliance crating create performance barriers to substitution by lower-density alternatives.
Thermal insulation commands premium positioning while cushioning expands most quickly through automation-enabled customization penetration.
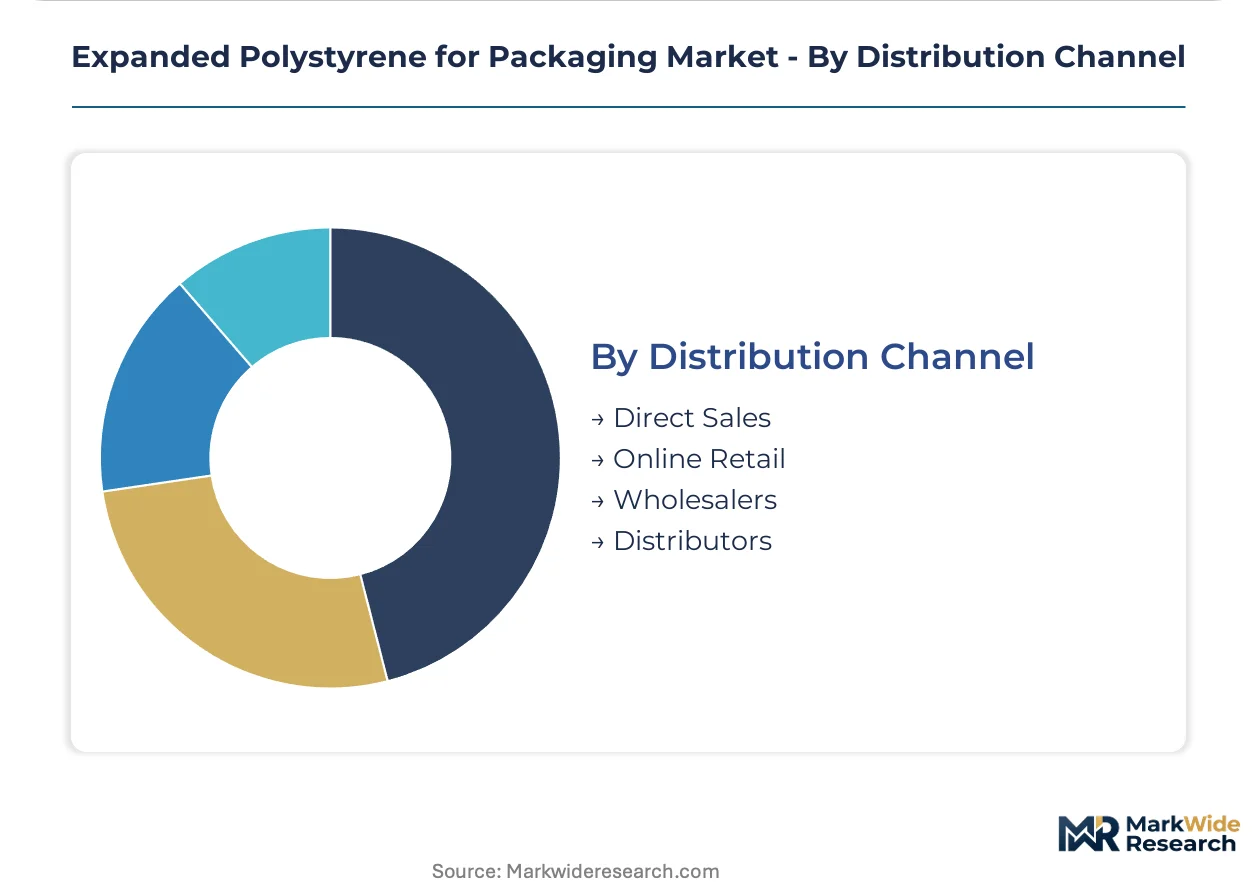
Distribution Channel:
Channel selection reflects order scale, customization requirements, and the technical intensity of specification support needed.
- Direct Sales:Converter relationships with large-volume end users requiring collaborative design and qualification support. Franchise systems in California and New York are mandating reverse logistics participation as a procurement condition, consolidating collection channel control.
- Distributors:Regional inventory and technical service for mid-volume foodservice and electronics accounts. European supply concentration in German and Belgian resin production clusters creates single-source vulnerability for molded foodservice formats distributed through this channel.
- Wholesalers:Arm's-length supply of standardized sheet and block stock for downstream fabrication. Pentane handling certification requirements under OSHA process safety management lag plant expansion timelines, constraining capacity additions serving this channel.
- Online Retail:Catalog and platform-based procurement of standardized formats for small-volume users and replacement parts. This channel captures limited share in EPS packaging due to the technical specification intensity of most applications.
Direct sales anchors relationship value while distributors face margin compression from supply concentration risks and reverse logistics mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin production clusters in Germany and Belgium concentrate molded foodservice supply for European converters, while North American bead foam capacity anchors medical device logistics networks. Asian pharmaceutical export corridors in India and Southeast Asian quick-commerce hubs are opening specification voids for validated thermal shippers.
Germany
Cold-chain logistics infrastructure drives thermal insulation demand for pharmaceutical distribution, with appliance manufacturers anchoring rigid foam volume. REACH flame-retardant restrictions and ECHA substance evaluations force additive reformulation cycles. The Rhine-Ruhr industrial corridor hosts resin production clusters that supply converters across Central Europe.
United States
Quick-service restaurant chains and meal-kit distributors sustain food-contact format demand, while e-commerce fulfillment networks compress specification cycles for protective cushioning. EPA volatile organic compound regulations govern pentane emissions from manufacturing facilities. California and New York extended producer responsibility mandates reshape collection infrastructure economics in the Northeast and Pacific Coast corridors.
India
Pharmaceutical exports from Mumbai and Hyderabad corridors create demand for validated thermal shippers meeting EU and US regulatory standards. CDSCO and DGFT frameworks govern cold-chain packaging specifications for temperature-sensitive biologics. Cold-chain infrastructure gaps in western and southern pharmaceutical clusters attract specification investment from international compounders.
China
Electronics manufacturing and appliance production sustain rigid foam demand for crating and transit protection. NMPA and GB standards regulate food-contact materials while MIIT industrial policies shape resin capacity expansion. Yangtze River Delta manufacturing hubs concentrate converter activity serving export-oriented electronics assembly.
Brazil
Quick-commerce grocery channels in São Paulo generate insulated pouch demand outside traditional foodservice procurement patterns. ANVISA pharmaceutical regulations govern cold-chain packaging for temperature-sensitive shipments. Southeastern industrial corridors concentrate molded foam fabrication serving domestic consumer goods distribution.
Expanded Polystyrene for Packaging Market Competitive Landscape
Concentration sits with integrated petrochemical groups controlling styrene monomer supply chains and specialized converters serving food-contact and medical device segments. The supplier base splits between upstream resin producers with captive raw material access and downstream fabricators with qualification-heavy end-use relationships. Strategic archetypes include integrated chemical conglomerates, captive foodservice specialists, and medical-device logistics compounders. Competitive moves center on backward integration into monomer supply and mechanization of bead foam molding for mid-volume customization.
Among European-integrated chemical producers, BASF SE exemplifies the upstream-resin archetype with captive styrene supply chain positioning. NOVA Chemicals Corporation anchors North American production capacity within the resin-grade specialization tier. Dart Container Corporation occupies a position in the food-contact segment through distribution network scale. These three represent distinct competitive vectors: petrochemical integration, regional resin specialization, and captive end-use channel control.
| Leading Market Players |
|---|
| BASF SE |
| Kaneka Corporation |
| Synthos |
| Alpek SAB de CV |
| NOVA Chemicals Corporation |
| TotalEnergies SE |
| SABIC |
| Versalis S.p.A. |
| Dart Container Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German resin producers and molded foodservice converters lock in both styrene monomer supply access and price visibility across the European market. These arrangements insulate volume buyers from benzene-ethylene feedstock swings while exposing spot-market purchasers to margin compression during volatility spikes.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the expanded polystyrene packaging market, separating certified-recyclable formats from commodity grades through compliance cost layering. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance certification, FDA food-contact approval status, and volume scale commitments. Cost compression in standard-grade molded cushioning is intensifying because bio-based starch foam substitutes are capturing e-commerce fulfillment specifications. Quick-service restaurant chains exhibit the highest price sensitivity due to procurement centralization, while pharmaceutical cold-chain logistics providers accept premium positioning for validated thermal shipper documentation.
Supply Chain Analysis
Inventory cycles for pre-expanded bead stock stretch six to eight weeks at European converters, creating working capital intensity that favors integrated resin producers. Raw material flows draw from German and Belgian styrene monomer clusters, with pentane blowing agents sourced from regional petrochemical complexes. Single-source vulnerability concentrates in the Rhine-Ruhr corridor, where resin production disruptions cascade immediately to molded foodservice format availability. Distribution runs through converter-direct relationships with large-volume end users and regional distributor networks serving mid-tier accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The expanded polystyrene packaging market functions as a defensive-moat arena where regulatory entrenchment creates specification stickiness that bio-based substitutes struggle to replicate within qualification timelines.
For Market Incumbents: Secure backward integration into styrene monomer supply to defend against benzene-ethylene feedstock volatility eroding converter margins. Lock in FDA food-contact certification renewal cycles ahead of additive reformulation mandates to preempt competitor qualification gaps. Channel control through reverse logistics participation requirements in California and New York extended producer responsibility schemes creates procurement stickiness against emerging biopolymer entrants.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for medical device packaging applications offer the most penetrable entry point, as established compounders face eight-to-fourteen-month qualification delays on new additive packages. Target cold-chain infrastructure gaps in Mumbai and Hyderabad pharmaceutical export corridors where validated thermal shipper demand outstrips local supply capability. Position around automation-enabled bead foam molding for mid-volume medical device segments where minimum order quantity compression opens white-space.
For Investors and Strategic Acquirers: Capital is best deployed toward resin-grade specialists with captive regulatory affairs functions and established EU REACH compliance documentation. Long-term viability hinges on mechanical recycling integration capabilities that close post-consumer loops ahead of extended producer responsibility mandate expansion. Watch for ECHA substance evaluation list updates on pentane blowing agents as the critical inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | BASF SE's captive supply chain secures feedstock cost advantages across European manufacturing hubs. |
| Mechanical Recycling Integration | Densification and re-extrusion technologies converge with collection network expansion to close post-consumer loops. |
| Bead Foam Molding Automation | Robotics integration reduces minimum order quantities for custom-shaped medical device packaging applications. |
| Long-term Supply Agreement | Direct material recovery arrangements with quick-service restaurant chains consolidate collection channel control. |
| Green Manufacturing Transition | Bio-based styrene alternatives derived from lignin enter pilot production for Swiss pharmaceutical distributors. |
Research Methodology
Initial hypotheses were tested against primary input from resin plant managers, foodservice procurement leads, pharmaceutical cold-chain logistics directors, and EPS converter technical R&D heads and refined through secondary validation. Customs and trade data from Eurostat and USITC, SEC 10-K filings from integrated chemical producers, Cefic industry reports, and EPA emissions disclosures provided foundational benchmarks. Bottom-up volume estimates from converter capacity utilization and top-down demand segmentation were triangulated to reconcile output figures.
Variance decomposition across product type, end-use industry, application format, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by value-per-unit differentials. Pentane blowing agent regulatory trajectories, e-commerce fulfillment network expansion rates, and cold-chain pharmaceutical shipment growth served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside EU Packaging and Packaging Waste Regulation implementation timelines or REACH substance evaluation acceleration would require recalibration. Forecasts reflect documented assumptions about resin capacity expansion and substitution elasticity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
PET Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Reel in Box Market
Packaging Materials
Child Resistant Zipper Market
Packaging Materials
Packaging Laminates Market
Packaging Materials
Mylar Market
Packaging Materials
Gift Wrapping Product Market