
 US Biofungicide Market | 2026-2036
US Biofungicide Market Size, Share, and Industry Trends Forecast 2026-2036
US Biofungicide Market Analytics
Synthetic fungicide chemistry is pivoting toward microbial and botanical alternatives as residue limits tighten and export markets enforce stricter maximum residue levels. Valent BioSciences LLC leverages its Bacillus-based fermentation infrastructure to supply consistent active ingredient volumes to major row-crop and specialty producers. Syngenta AG competes through integrated biological-chemical portfolios that allow growers to rotate modes of action within a single supplier relationship. Certis Biologicals specializes in niche fruit and vegetable segments where organic certification requirements exclude conventional synthetic options.
A biofungicide comprises living microorganisms, their metabolites, or plant-derived compounds formulated to suppress fungal and oomycete pathogens through antagonism, competition, or induced systemic resistance in host plants. These products typically contain specified colony-forming unit counts per milliliter or gram, require refrigerated or controlled-temperature storage, and function as components of integrated pest management programs in conventional and organic production systems. Fungal biopesticide formulations dominate current revenue owing to established Trichoderma and Coniothyrium minitans manufacturing platforms, while bacterial biopesticide segments led by Bacillus subtilis and Bacillus amyloliquefaciens strains represent the fastest-expanding category due to broader spectrum claims and compatibility with foliar fertilizer programs. Agricultural fields generate the largest application volume, though greenhouse operations command premium pricing because controlled-environment producers face zero-tolerance pathogen thresholds and value residue-free harvests for direct retail and foodservice channels.
EPA biopesticide registration under the Federal Insecticide, Fungicide, and Rodenticide Act shapes market access timelines, while USDA National Organic Program standards determine which formulations qualify for certified organic operations, directly influencing product development priorities. State-level departments of agriculture in California, Florida, and Washington enforce supplemental data requirements and use restrictions that fragment compliance obligations across major production regions. Stakeholders must monitor pending EPA guidance on RNA interference and other novel biofungicide modalities, as classification decisions will determine whether emerging technologies follow conventional biopesticide or genetically modified organism regulatory pathways with vastly different approval timelines and market access conditions.
Market Dynamics
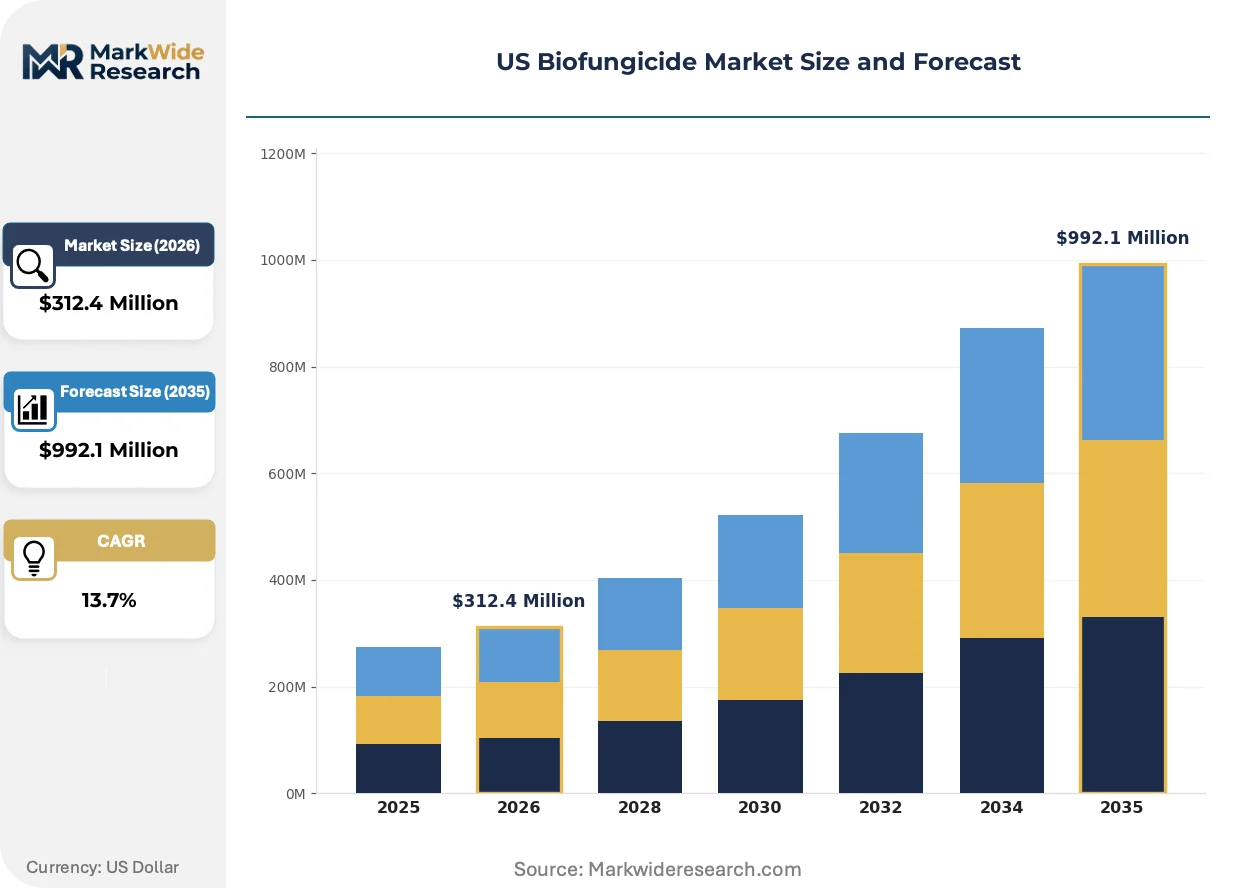
EPA registration pathway streamlining under the Federal Insecticide, Fungicide, and Rodenticide Act is compressing biopesticide approval timelines from 18 months toward 12 months, accelerating commercialization velocity for microbial active ingredients.
Growth Catalysts
- Maximum Residue Limit Enforcement:Export markets including the European Union and Japan enforce stricter residue thresholds on imported produce, compelling California specialty crop growers to adopt residue-free microbial alternatives.
- USDA National Organic Program Standards:Certified organic acreage expansion in Florida and Washington creates compliant product demand that synthetic fungicides cannot satisfy.
- Integrated Pest Management Mandates:State departments of agriculture in California and Florida require documented resistance management programs, embedding biofungicides into mandatory rotation protocols.
Market Restraints
- Fermentation Input Volatility:Soybean meal and molasses feedstock prices fluctuate with commodity markets, compressing Bacillus-based production margins.
- Cold Chain Infrastructure Gaps:Rural distribution networks in the Pacific Northwest lack consistent refrigerated storage, degrading live microbial viability before field application.
- Performance Consistency Under Field Stress:Ultraviolet degradation and desiccation reduce Trichoderma spore efficacy compared to synthetic chemical persistence.
Strategic Opportunities
- Greenhouse Controlled Environment Agriculture:Zero-tolerance pathogen protocols in hydroponic tomato and leafy green operations command premium pricing for guaranteed residue-free harvests.
- RNA Interference Modality Classification:Pending EPA guidance on nucleic acid-based biofungicides will determine whether emerging technologies access streamlined biopesticide or prolonged GMO regulatory pathways.
- Direct-to-Grower Digital Platforms:E-commerce channels bypass traditional agricultural distribution cooperatives, enabling smaller microbial manufacturers to reach specialty crop producers.
Industry Challenges
- Microbial Formulation Expertise Scarcity:Fermentation scale-up from laboratory to industrial bioreactor requires specialized biochemical engineering talent concentrated at limited academic programs.
- State-Level Registration Fragmentation:California Department of Pesticide Regulation and Washington State Department of Agriculture impose supplemental data requirements beyond federal EPA submissions, multiplying compliance costs.
- Compatibility Testing Burden:Grower demand for tank-mix flexibility with foliar fertilizers and chemical fungicides necessitates extensive field validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biofungicide Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $992.1 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungal Biopesticide, Bacterial Biopesticide, Natural Extracts, Mycoherbicides Application: Agricultural Fields, Greenhouses, Turf and Ornamental, Home and Garden End User: Farmers, Landscape Professionals, Homeowners, Agricultural Cooperatives Distribution Channel: Online Retail, Conventional Stores, Agricultural Supply Stores, Distributors |
| Companies Covered | Valent BioSciences LLC, Syngenta AG, Bioceres Crop Solutions, Gowan Company, Mitsui & Co. (U.S.A.), Inc., Corteva Agriscience, Certis Biologicals, BioWorks, Inc., Marrone Bio Innovations, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biofungicide Market Evolving Landscape
Biological active ingredient manufacturing is shifting from batch fermentation toward continuous processing, while genomic screening accelerates strain discovery pipelines. These developments are compressing product development cycles and expanding spectrum claims.
CRISPR-guided strain enhancement is rewriting competitive positioning in bacterial biopesticide development. Researchers at agricultural biotechnology laboratories deploy precision genome editing to amplify Bacillus subtilis lipopeptide production. Field trials in Florida citrus groves demonstrate improved powdery mildew suppression. This capability is compressing the historical 8-10 year development timeline toward 5-7 years for enhanced microbial products.
EPA's emerging guidance on plant-incorporated protectants and nucleic acid technologies is reshaping regulatory classification boundaries. The agency's Biopesticides and Pollution Prevention Division evaluates whether RNA interference products qualify for biopesticide registration or trigger genetically modified organism oversight. California specialty crop producers monitor these determinations closely, as pathway selection dictates approval timelines and labeling requirements for novel disease management tools.
Specialty crop buyers are consolidating procurement authority through centralized sustainability compliance teams. Large berry and vegetable processors now mandate documented biological input usage from contract growers, replacing individual farm-level purchasing decisions. This concentration is most visible in the Salinas Valley and Central Coast regions, where packer-specified input protocols override traditional independent dealer relationships.
US Biofungicide Market Segmentation
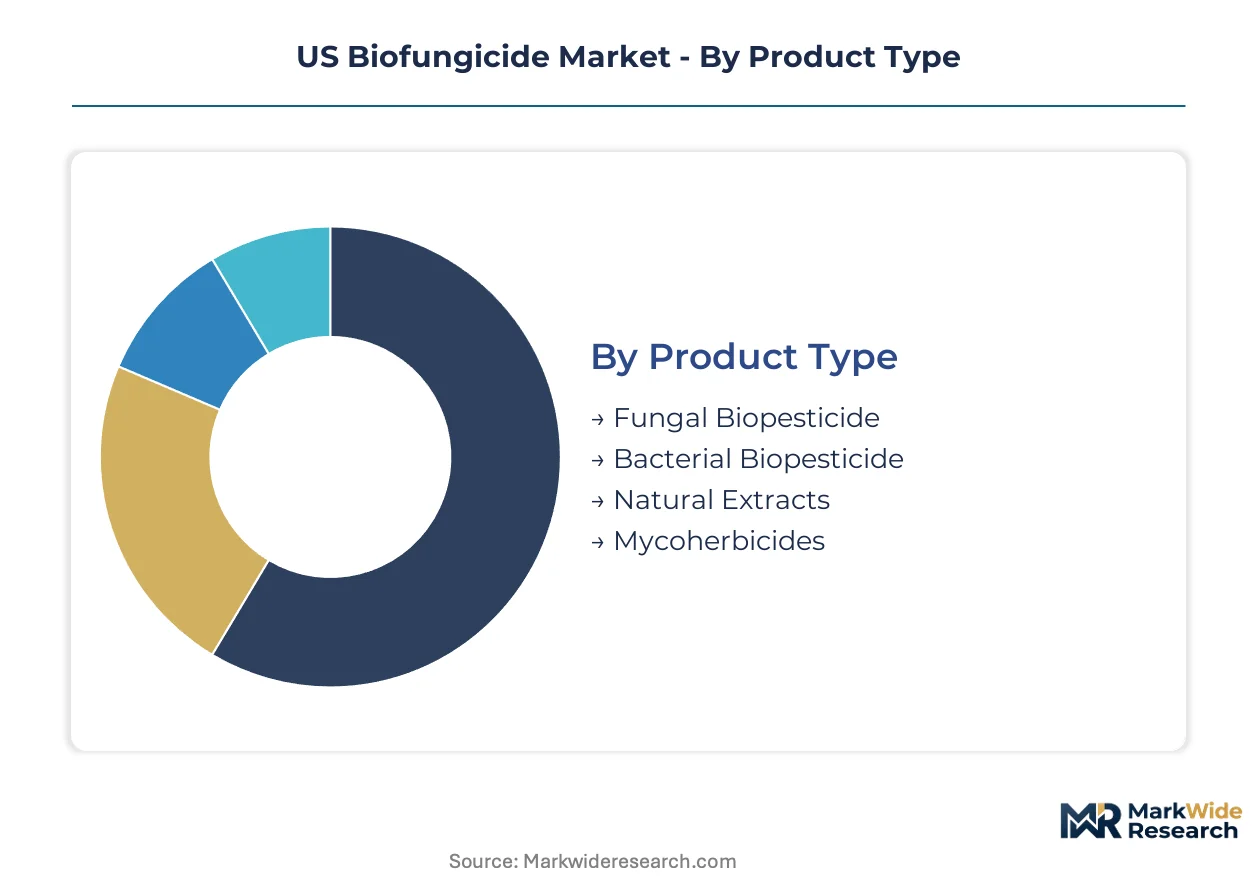
US biofungicide market segmentation reflects divergent regulatory burdens across product categories and distribution pathways. EPA biopesticide registration timelines vary significantly by active ingredient source, while USDA National Organic Program compliance requirements shape end-user purchasing decisions. Understanding these certification-driven divisions enables targeted product development and channel strategy.
Product Type:
EPA registration pathways differentiate microbial products from botanical extracts, with Bacillus-based formulations accessing streamlined 12-month review timelines under the Federal Insecticide, Fungicide, and Rodenticide Act. Natural extracts face additional residue chemistry data requirements that extend approval cycles.
- Fungal Biopesticide:Trichoderma harzianum and Coniothyrium minitans formulations dominate current manufacturing volumes through established solid-state fermentation infrastructure. California strawberry and vegetable growers generate concentrated demand for these products, though ultraviolet degradation in field conditions constrains application timing flexibility.
- Bacterial Biopesticide:Bacillus subtilis and Bacillus amyloliquefaciens strains command expanding acreage through broader spectrum claims and foliar fertilizer compatibility. Florida citrus and Pacific Northwest apple producers drive adoption as resistance management mandates embed these products into mandatory rotation protocols.
- Natural Extracts:Plant-derived compounds require supplemental residue data submissions to EPA beyond standard microbial registration packages.
- Mycoherbicides:Fungal-based weed control products occupy niche positioning with limited disease management crossover applications.
Leading the category by volume: Fungal Biopesticide. Growing fastest: Bacterial Biopesticide.
Application:
Cost tier differentiation separates commodity agricultural applications from premium controlled-environment systems where zero-tolerance pathogen protocols justify higher per-acre input spending.
- Agricultural Fields:Open-field row crops and specialty produce operations generate the largest absolute volume through broadcast and chemigation application methods. California Central Valley and Florida citrus belt producers anchor demand, though performance inconsistency under temperature and moisture stress limits replacement of synthetic fungicide programs.
- Greenhouses:Controlled environment agriculture commands premium pricing per treated acre due to zero-tolerance pathogen thresholds in hydroponic tomato and leafy green operations. Salinas Valley and Central Coast packer-specified input protocols mandate documented biological usage for contract growers supplying retail and foodservice channels.
- Turf and Ornamental:Golf course and landscape maintenance applications prioritize aesthetic outcomes over yield protection, with municipal restrictions on synthetic chemistry expanding addressable market.
- Home and Garden:Consumer-facing products retail through big-box and specialty channels with simplified application instructions and lower concentration formulations.
Highest margin concentration: Greenhouses. Steepest expansion trajectory: Agricultural Fields.
End User:
Customer type determines purchasing authority concentration, with agricultural cooperatives consolidating procurement decisions that previously rested with individual farm operators.
- Farmers:Individual growers in Washington apple and Florida vegetable sectors retain direct purchasing authority for resistance management program compliance. These operators prioritize tank-mix compatibility with existing foliar fertilizer and chemical fungicide programs, necessitating extensive field validation studies.
- Agricultural Cooperatives:Centralized buying organizations in the Pacific Northwest and California Central Coast aggregate demand across member farms to negotiate volume pricing and technical support packages. Cooperative procurement teams increasingly mandate sustainability documentation for export market access.
- Landscape Professionals:Commercial turf and grounds maintenance contractors purchase through specialized distribution with service-level agreements for technical consultation.
- Homeowners:Retail consumers select based on shelf presence and organic certification labeling with limited technical differentiation awareness.
Greatest purchasing consolidation: Agricultural Cooperatives. Fastest decision-cycle compression: Farmers.
Distribution Channel:
Supply concentration varies by channel, with agricultural supply stores maintaining refrigerated storage infrastructure that online retail and conventional stores often lack for live microbial products.
- Agricultural Supply Stores:Independent and cooperative retail locations in California, Florida, and Washington provide cold chain infrastructure and certified crop advisor consultation. These outlets capture the majority of microbial biofungicide volume through established relationships with specialty crop producers.
- Distributors:Regional and national wholesale networks manage inventory and logistics for manufacturers lacking direct field sales organizations. Distributor technical representatives bridge formulation expertise gaps in rural markets.
- Online Retail:Direct-to-grower digital platforms enable smaller microbial manufacturers to bypass traditional agricultural distribution cooperatives and reach specialty crop producers with technical documentation and application guidance.
- Conventional Stores:Mass-market retail channels carry limited SKUs focused on home and garden segments with minimal technical support.
Deepest cold chain penetration: Agricultural Supply Stores. Fastest channel share gain: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's agricultural tax incentives and research partnerships through the UC Davis Innovation Hub concentrate biofungicide development activity. State-level programs in Florida and Washington complement federal EPA streamlining to accelerate commercial deployment.
California
Specialty crop growers in the Central Valley and Salinas Valley drive bacterial biopesticide demand for strawberry and leafy green production. The California Department of Pesticide Regulation enforces supplemental data requirements beyond federal EPA submissions. Fresno County and Monterey County host concentrated fermentation manufacturing facilities serving Pacific Northwest export markets.
Florida
Citrus grove operators adopt Bacillus-based programs to manage greening disease pressure and satisfy resistance management mandates. The Florida Department of Agriculture and Consumer Services requires documented biological input rotation protocols. The Lake Alfred research corridor and Immokalee vegetable production zone anchor field trial infrastructure for microbial formulation validation.
Washington
Apple and hop producers in the Yakima Valley integrate Trichoderma products into powdery mildew management schedules. The Washington State Department of Agriculture imposes cold chain certification requirements for live microbial distribution. Wenatchee-area packing cooperatives consolidate procurement decisions and mandate residue-free documentation for export shipments to Asian markets.
Oregon
Hazelnut and wine grape growers in the Willamette Valley expand organic-certified acreage requiring compliant disease management inputs. The Oregon Department of Agriculture coordinates with EPA Region 10 on biopesticide registration streamlining initiatives. Portland-area biotechnology incubators support strain discovery partnerships between regional universities and agricultural input manufacturers.
Texas
Winter vegetable producers in the Lower Rio Grande Valley adopt microbial alternatives for onion and melon disease suppression. The Texas Department of Agriculture administers cost-share programs for integrated pest management adoption. The Weslaco research station hosts efficacy trials comparing Bacillus formulations against conventional fungicide benchmarks.
US Biofungicide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with microbial fermentation expertise determining tier placement. The market structures around three concentration nodes: multinational agrochemical portfolios, dedicated biological platforms, and regional fermentation service providers. Two strategic archetypes dominate competitive positioning — integrated biological-chemical suppliers and pure-play microbial specialists. Capacity expansion in controlled-temperature fermentation infrastructure and strategic partnerships with university research stations represent the dominant competitive moves.
Within the multinational tier, Syngenta AG and Corteva Agriscience occupy positions as integrated portfolio suppliers offering rotation protocols across synthetic and biological modes of action. Valent BioSciences LLC exemplifies the dedicated biological platform archetype through its Bacillus-focused fermentation infrastructure. Certis Biologicals represents the specialty crop specialist segment with concentrated positioning in fruit and vegetable segments where organic certification requirements exclude conventional synthetic options.
| Leading Market Players |
|---|
| Valent BioSciences LLC |
| Syngenta AG |
| Bioceres Crop Solutions |
| Gowan Company |
| Mitsui & Co. (U.S.A.), Inc. |
| Corteva Agriscience |
| Certis Biologicals |
| BioWorks, Inc. |
| Marrone Bio Innovations |
| Others |
Value Network & Pricing Analysis
Packer-specified input protocols in California's Salinas Valley and Central Coast are compressing procurement timelines for microbial biofungicides, forcing fermentation manufacturers to hold finished goods inventory closer to end-use regions and elevating working capital costs that transmit into contract pricing premiums.
Pricing Analysis
Expedited delivery premiums for live microbial products with sub-48-hour shelf-life windows command 15-25% markups over standard lead-time orders. Three-tier pricing structure across premium cold-chain-guaranteed, standard temperature-controlled, and economy bulk-tank segments stratifies the market. Pricing pressure stems from fermentation input volatility in soybean meal and molasses feedstocks. Agricultural cooperatives exhibit highest price sensitivity due to consolidated volume bargaining power, while greenhouse operators show lowest sensitivity given zero-tolerance pathogen protocols.
Supply Chain Analysis
Single-source vulnerability sits with domestic Bacillus strain repositories concentrated in California and Florida research corridors. Manufacturing draws from Midwest corn-derived dextrose, Gulf Coast molasses, and Pacific Northwest yeast extract suppliers. Tariff exposure on Brazilian soybean meal imports threatens production margin stability. Distribution runs through agricultural supply stores with certified cold-chain infrastructure, bypassing conventional retail channels lacking live microbial storage capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where captive fermentation capacity and in-house strain development pipelines determine margin capture. Players are pursuing backward integration into feedstock sourcing to insulate against commodity volatility.
For Market Incumbents: Anchor market position through captive Bacillus fermentation infrastructure expansion in Fresno County and Monterey County manufacturing clusters. Defend against emerging CRISPR-enhanced strain developers by accelerating EPA registration timelines for next-generation lipopeptide formulations. Prioritize cold-chain distribution partnerships with agricultural cooperatives to lock in volume commitments. For New Entrants and Emerging Players: Direct-to-grower digital platforms represent the most penetrable channel, bypassing entrenched cooperative procurement hierarchies in the Pacific Northwest. Target Washington apple and hop producers with tank-mix compatibility guarantees for foliar fertilizer programs. Pursue white-label manufacturing arrangements with established fermentation service providers to circumvent capital-intensive infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors mid-cap microbial specialists with EPA-registered strain libraries and existing California Department of Pesticide Regulation compliance dossiers. Long-term viability hinges on RNA interference modality classification outcomes that will reshape regulatory pathway economics. Watch EPA guidance timing on nucleic acid-based biofungicides as the critical inflection signal for portfolio rebalancing toward or away from emerging technology platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Temperature Fermentation Capacity Expansion | California-based capacity additions secure EPA registration advantages for Bacillus-based active ingredients. |
| University Research Station Partnerships | UC Davis and Lake Alfred collaborations accelerate strain discovery pipelines for Florida citrus applications. |
| Cold Chain Distribution Certification | Washington State Department of Agriculture compliance opens access to apple export markets with residue-free documentation requirements. |
| RNA Interference Regulatory Pathway Positioning | Early EPA Biopesticides and Pollution Prevention Division engagement determines classification as biopesticide or GMO oversight. |
| Direct-to-Grower Digital Platform Launch | E-commerce channels bypass agricultural cooperative procurement consolidation in specialty crop segments. |
Research Methodology
EPA registration databases, USDA National Organic Program certified operation listings, and state department of agriculture pesticide use reports formed the secondary backbone of this analysis. Primary interviews with fermentation plant managers, agricultural cooperative procurement leads, certified crop advisors, and EPA biopesticide registration specialists were cross-referenced against customs data on fermentation feedstock imports and SEC filings from publicly traded agricultural biotechnology firms. Bottom-up strain-level production estimates were triangulated against top-down market size assessments derived from acreage application rates and pricing surveys.
Historical trendline analysis of bacterial and fungal biopesticide registration volumes informed projection modeling across the analysis window. Segmentation dimensions included active ingredient source, application environment, end-user purchasing authority concentration, and distribution channel cold-chain capability. CAGRs were derived from weighted average growth trajectories across these segments, incorporating EPA review timeline compression assumptions and organic acreage expansion patterns in Florida and Washington.
Caveats apply where EPA guidance timing on RNA interference classification or feedstock commodity price spikes could materially shift the outlook. Deviation in state-level registration fragmentation severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Agricultural Biologicals Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Biofumigation Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Japan Biofertilizer Market