
 Europe Biological Organic Fertilizer Market | 2026-2036
Europe Biological Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biological Organic Fertilizer Market Foresight
Multi-source procurement of microbial inoculants and composted manures is rebalancing supply relationships across European farm cooperatives. Koppert Biological Systems BV leverages its Dutch greenhouse expertise to dominate biological input distribution in northwest Europe. ORGANAZOTO FERTILIZZANTI SPA anchors southern European demand through specialized manure-based formulations for Mediterranean cropping systems. RovensaNext differentiates via integrated biostimulant-fertilizer portfolios that extend beyond standalone organic nutrition products.
Europe biological organic fertilizer comprises plant- or animal-derived materials processed through composting, anaerobic digestion, or microbial fermentation to deliver nitrogen, phosphorus, and potassium with active microbiological populations. These inputs restore soil organic carbon, suppress pathogen loads, and reduce synthetic chemical dependency in certified organic and conventional transitional operations. Microbial formulations command premium positioning due to technical complexity in strain stabilization and shelf-life extension, while compost maintains volume leadership across broadacre cereal applications. Horticulture channels generate superior margin pools per hectare compared to agronomy, driven by greenhouse growers in the Netherlands and Belgium pursuing residue-free export certification.
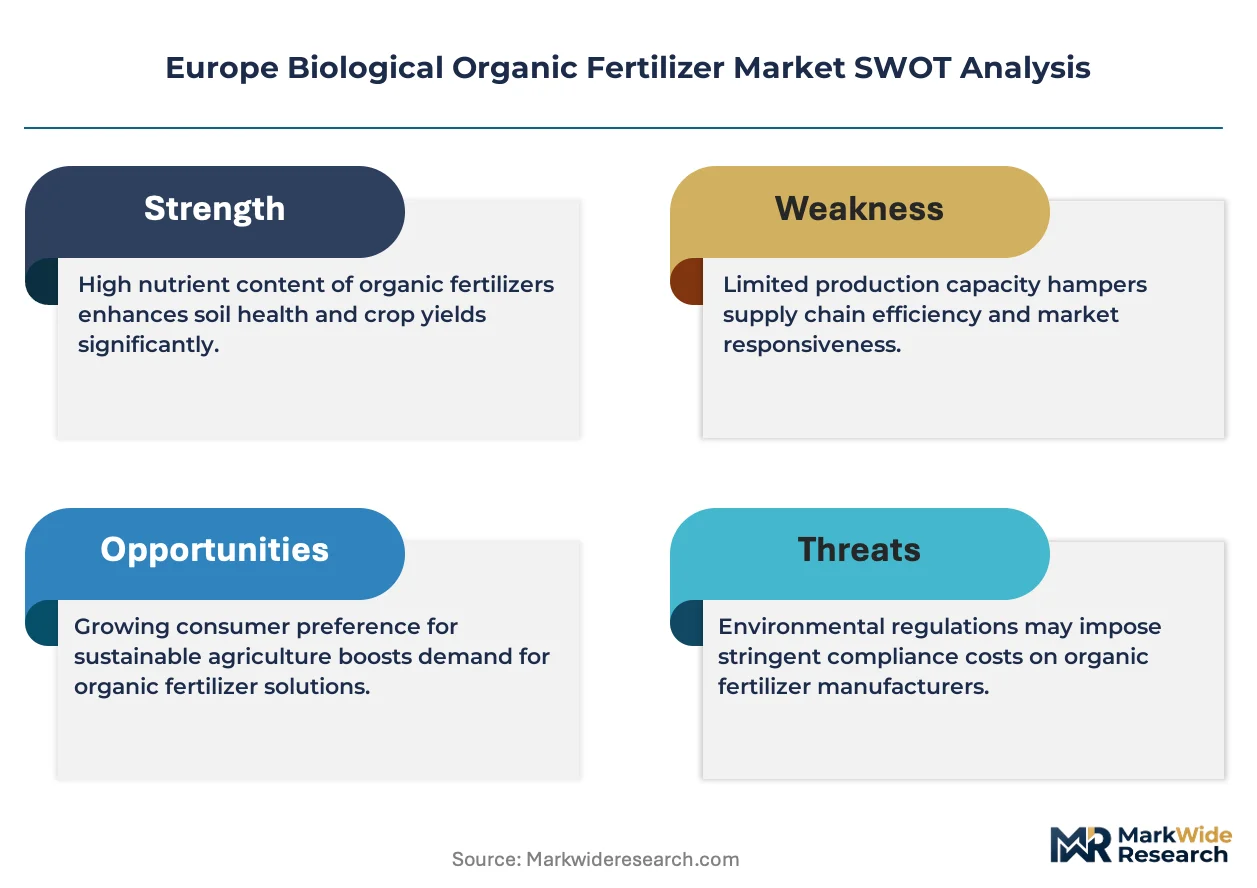
The EU Green Deal, REACH, and the F-Gas Regulation collectively elevate product registration barriers and mandate transparent substrate sourcing for organic fertilizer manufacturers seeking CE-marked distribution. EFSA evaluation protocols for microbial strains and ECHA substance classification requirements shape formulation investment priorities and cross-border commercialization timelines. Stakeholders must monitor evolving national interpretations of the EU AI Act for precision agriculture tools that pair biological fertilizers with sensor-based application systems.
Market Dynamics
EU Green Deal nitrogen caps are forcing a wholesale reallocation of farm input budgets from synthetic to certified organic alternatives, compressing adoption timelines across Mediterranean and northwest European cropping systems.
Growth Catalysts
- Farm to Fork Strategy:Synthetic fertilizer reduction targets redirect public and private capital toward biological alternatives. Dutch greenhouse operators lead compliance-driven procurement.
- Spain's specialty crop expansion:Vineyard and olive grove managers in Andalusia and Catalonia scale biological inputs for export certification. Premium horticulture channels absorb higher per-hectare input costs.
- Soil health monitoring:Standardized carbon and microbiome testing protocols validate biological fertilizer performance. French cereal belt cooperatives tie procurement decisions to measurable organic matter gains.
Market Restraints
- Microbial strain stabilization:Shelf-life extension for liquid inoculants requires cold chain infrastructure absent in southern European distribution networks. Technical complexity elevates failure rates in field conditions.
- Substrate sourcing transparency:REACH and ECHA substance classification mandates impose documentation burdens on compost and digestate suppliers. Smaller processors lack compliance capacity.
- Synthetic fertilizer price volatility:Natural gas feedstock fluctuations create intermittent price advantages for conventional nitrogen. Transitional farmers delay full biological conversion.
Strategic Opportunities
- Poland's broadacre underpenetration:Large-scale cereal operations remain synthetic-dependent. Early biological adopters capture first-mover premiums in EU-funded sustainable agriculture pilots.
- Sensor-based application convergence:Variable-rate spreaders paired with microbiological formulations enable precision organic nutrition. Netherlands-based equipment manufacturers pilot integrated systems.
- EFSA microbial strain pre-approval:Streamlined evaluation protocols reduce registration timelines for novel consortia. Investors prioritize pipeline assets with regulatory pathway clarity.
Industry Challenges
- Microbiologist talent scarcity:Strain isolation and fermentation scale-up expertise concentrates in academic and large corporate laboratories. Mid-tier formulators compete for limited technical personnel.
- CE marking timeline compression:ECHA substance notification and EFSA safety evaluation run sequentially rather than parallel. Product launch delays extend 18-24 months beyond development completion.
- Legacy synthetic equipment incompatibility:Existing spreaders and injectors damage viable microbial populations through shear and temperature exposure. Retrofit costs deter rapid fleet conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biological Organic Fertilizer Market |
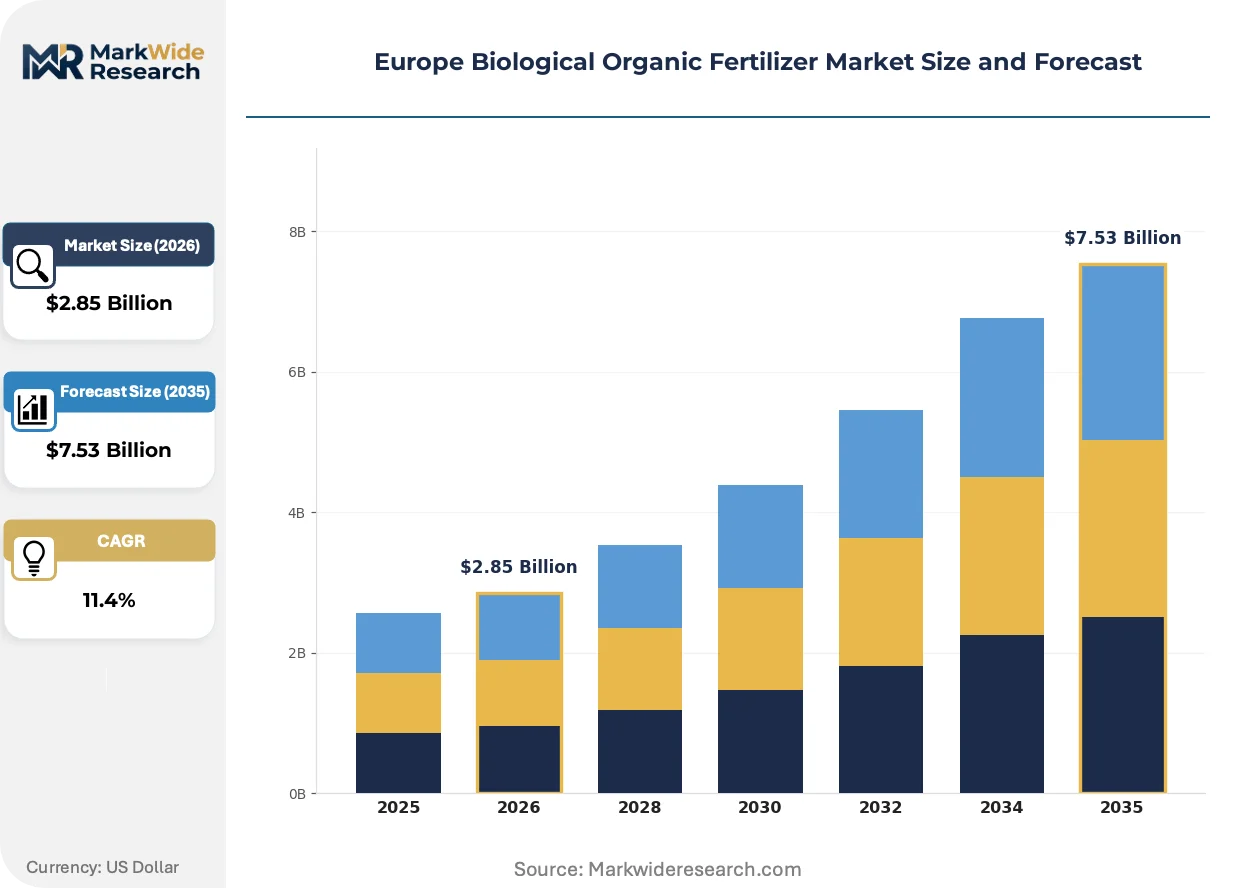
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Seaweed, Microbial Application: Agronomy, Horticulture, Turf Management, Landscaping Customer Type: Agricultural Producers, Commercial Growers, Home Gardeners, Retailers Distribution Channel: Direct Sales, Online Retail, Wholesale, Garden Centers |
| Companies Covered | Angibaud, ORGANAZOTO FERTILIZZANTI SPA, Fertikal NV, Koppert Biological Systems BV, Plantin, HELLO NATURE ITALIA srl, APC AGRO, RovensaNext, Agribios Italiana s.r.l., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biological Organic Fertilizer Market Shifts & Advancements
Biological organic fertilizer markets are restructuring around verification technologies, regulatory data requirements, and procurement centralization. Three developments dominate investment and competitive positioning.
Automated soil microbiome sequencing is automating strain efficacy validation for commercial inoculant suppliers. Netherlands greenhouse operators deploy real-time microbial population monitoring to optimize application timing. This technology is automating the translation of laboratory strain performance into field-specific dosage recommendations, compressing the feedback loop between research and commercial formulation.
EU AI Act precision agriculture provisions are reshaping liability frameworks for sensor-guided biological fertilizer application. Equipment manufacturers must document algorithmic decision-making pathways for nutrient release timing. French and German farm machinery regulators are interpreting these requirements most strictly, slowing connected spreader deployment in those markets relative to Belgium and Denmark.
Cooperative procurement consolidation is displacing individual farm purchasing across European cereal regions. French and German farm cooperatives now negotiate multi-year biological input contracts with volume guarantees and technical service bundling. This shift concentrates buyer power and favors suppliers with integrated agronomic advisory capabilities over pure product vendors.
Europe Biological Organic Fertilizer Market Segmentation
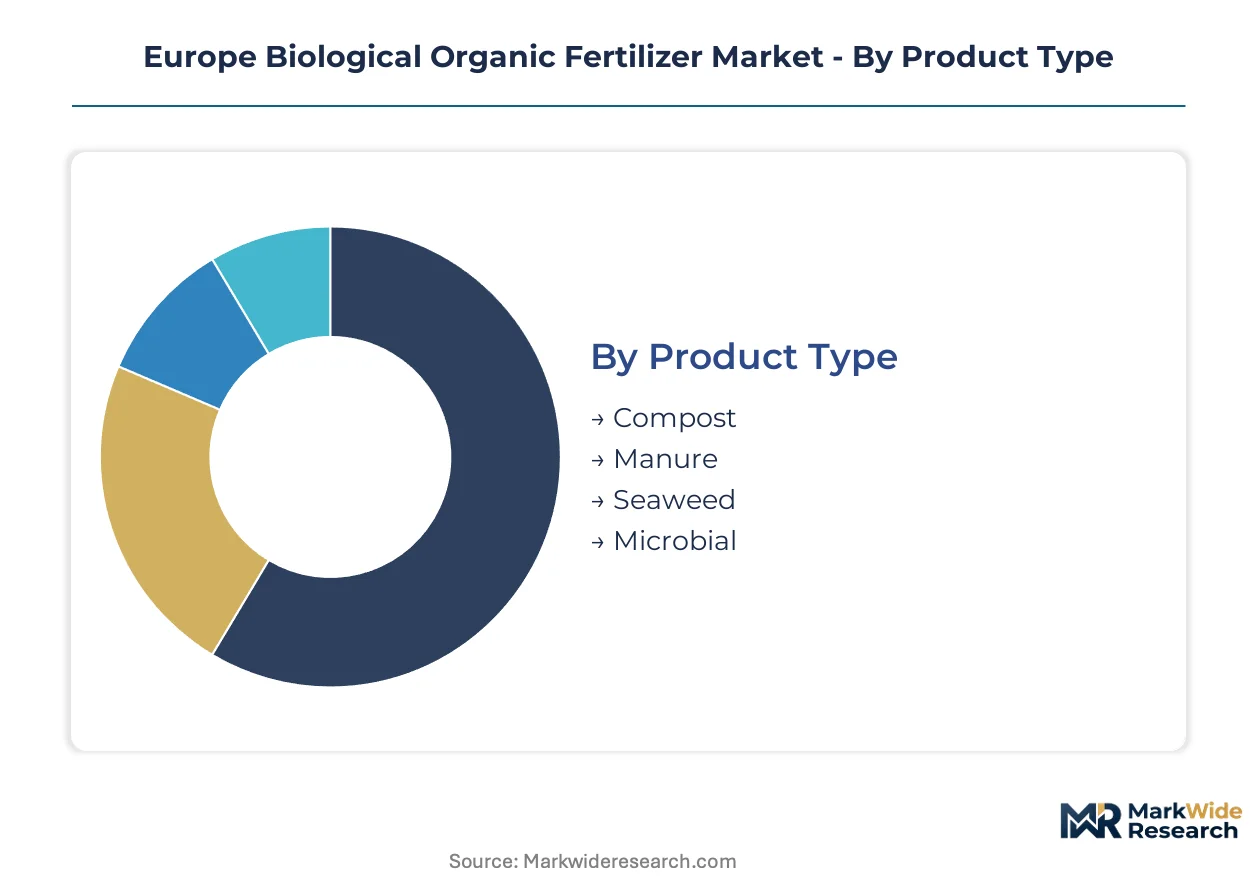
Biological organic fertilizer markets fragment across product chemistry, application intensity, and procurement sophistication. Each dimension reveals distinct margin pools, technical requirements, and regulatory exposure that shape supplier strategy across European farm cooperatives and greenhouse operations.
Product Type:
Integration depth varies sharply: compost and manure function as standalone soil amendments, while microbial formulations embed within precision application systems requiring technical service bundling.
- Compost:Decomposed organic matter from agricultural residues and municipal green waste delivers baseline nitrogen and soil carbon restoration. French cereal belt cooperatives specify thermophilic-processed compost with pathogen suppression certification for broadacre wheat and barley rotations.
- Microbial:Concentrated bacterial and fungal inoculants—nitrogen-fixing rhizobia, phosphorus-solubilizing bacillus—demand cold chain distribution and strain-specific application protocols. Dutch greenhouse operators pair these with sensor-based irrigation systems for residue-free vegetable export certification.
- Manure:Processed animal waste from anaerobic digesters supplies phosphorus and potassium with reduced odor and pathogen loads compared to raw applications.
- Seaweed:Marine-derived extracts provide trace minerals and biostimulant compounds for high-value horticulture in Belgium and the Netherlands.
Compost leads volumes today; microbial formulations are gaining share fastest.
Application:
Cost tier separation dominates: horticulture commands premium pricing per hectare while agronomy operates on volume-scaled procurement contracts.
- Horticulture:Greenhouse vegetable and protected fruit production in the Netherlands, Belgium, and Spain's Almería province requires residue-free certification and precise nutrient timing. Biological inputs here absorb input cost premiums of 40-60% above agronomy rates.
- Agronomy:Cereal, oilseed, and pulse cultivation across France, Germany, and Poland emphasizes soil organic carbon building and synthetic nitrogen displacement. French cooperatives tie biological fertilizer procurement to measurable carbon sequestration outcomes.
- Turf Management:Golf courses and sports pitches in the UK and Ireland prioritize rapid establishment and wear recovery with reduced synthetic chemical dependency.
- Landscaping:Municipal parks and commercial grounds maintenance in urban Germany and Scandinavia follows public procurement sustainability mandates.
Horticulture captures the steepest margin expansion trajectory; agronomy anchors absolute tonnage demand.
Customer Type:
Procurement sophistication stratifies sharply: institutional buyers negotiate multi-year technical service contracts while fragmented retail channels compete on shelf availability.
- Agricultural Producers:Large-scale cereal and livestock operations in Poland and eastern Germany purchase through cooperative buying groups with volume guarantees and integrated soil testing services.
- Commercial Growers:Specialized vegetable and fruit operations in Spain's Murcia region and Italy's Po Valley demand batch-traceable formulations with export certification documentation.
- Home Gardeners:Urban consumers in France, Germany, and the UK purchase through garden centers and online channels, price-sensitive but responsive to organic certification labeling.
- Retailers:Agricultural supply cooperatives and garden center chains intermediate between manufacturers and end-users, consolidating shelf space and technical advisory roles.
Agricultural producers dominate tonnage procurement; commercial growers are expanding contract values most rapidly.
Distribution Channel:
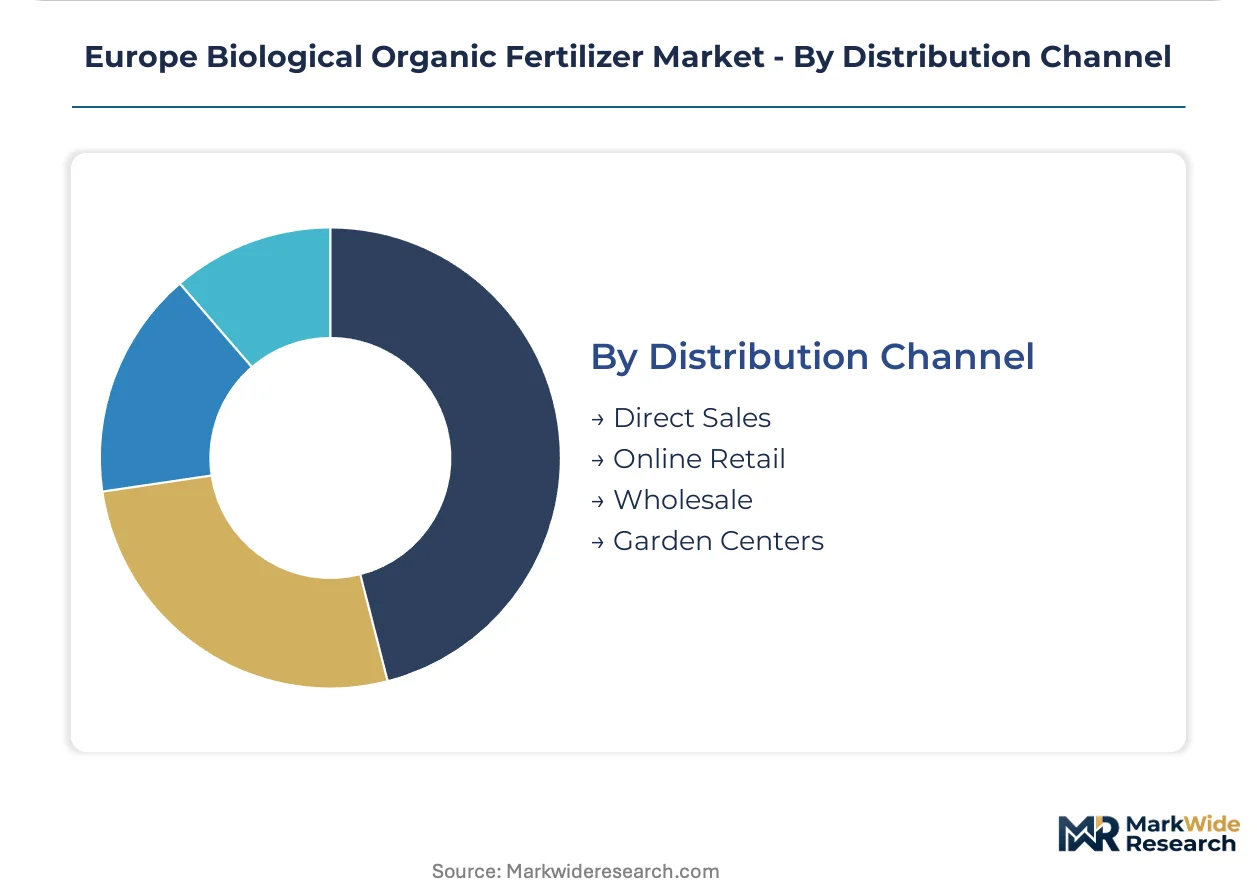
Supply concentration in northwest Europe shapes channel viability: direct sales require local technical presence, while wholesale networks extend reach into fragmented southern markets.
- Direct Sales:Manufacturer-to-farm relationships with embedded agronomists dominate large greenhouse operations in the Netherlands and Belgium. Koppert Biological Systems BV leverages this channel for integrated pest and nutrition management bundling.
- Wholesale:Regional distributors aggregate compost and manure volumes for French and German farm cooperatives, managing logistics complexity and seasonal demand spikes.
- Online Retail:E-commerce platforms capture home gardener demand in urban UK, German, and French markets, constrained by microbial product shelf-life and temperature sensitivity.
- Garden Centers:Physical retail maintains relevance for tactile product evaluation and immediate availability among amateur cultivation segments.
Direct sales command the highest margin capture; wholesale channels are expanding geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands greenhouse belt concentrates biological organic fertilizer innovation, with Dutch operators setting residue-free certification standards that cascade across northwest European procurement networks.
Netherlands
Greenhouse vegetable exporters in Westland and Aalsmeer drive microbial inoculant demand for precision nutrient timing. EU Green Deal nitrogen caps redirect public R&D funding toward biological alternatives. Wageningen University research clusters validate strain performance for commercial suppliers serving Belgian and German cross-border markets.
France
Cereal cooperatives in the Paris Basin and Champagne-Ardenne tie biological fertilizer procurement to measurable soil carbon gains. REACH substance classification mandates reshape compost supplier documentation requirements. Lyon-based agronomic service firms bundle soil microbiome testing with multi-year input contracts for broadacre wheat and barley operations.
Spain
Andalusian olive grove managers and Catalan vineyard operators scale biological inputs for organic export certification. Farm to Fork Strategy synthetic reduction targets accelerate adoption timelines in Murcia's protected vegetable sector. Almería's greenhouse concentration absorbs premium-priced microbial formulations for residue-free tomato and pepper shipments.
Germany
Lower Saxony livestock operations expand anaerobic digestate processing for phosphorus recovery. ECHA notification requirements compress product launch timelines for novel formulations. Bavarian farm machinery manufacturers pilot sensor-guided spreader systems compatible with viable microbial population delivery.
Italy
Po Valley fruit and vegetable growers demand batch-traceable manure-based formulations with export documentation. EFSA microbial strain evaluation protocols shape investment priorities for domestic formulators. Emilia-Romagna's agricultural input distribution networks anchor southern European supply relationships for specialized Mediterranean cropping systems.
Europe Biological Organic Fertilizer Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and distribution reach, producing a tiered structure where scale-driven players battle specialized service integrators. Three archetypes dominate: multinational biological input platforms with greenhouse-to-field portfolios, manure-based processors anchored in Mediterranean livestock regions, and precision agriculture equipment manufacturers bundling hardware with microbial subscriptions. Competitive moves concentrate on cooperative procurement consolidation and EFSA pre-approval pipeline building.
Within the integrated service tier, Koppert Biological Systems BV and ORGANAZOTO FERTILIZZANTI SPA exemplify divergent geographic anchoring strategies. RovensaNext occupies a position bridging biostimulant and fertilizer categories. Dutch greenhouse expertise and Italian manure processing capabilities represent distinct regional specialization moats that resist easy replication.
| Leading Market Players |
|---|
| Angibaud |
| ORGANAZOTO FERTILIZZANTI SPA |
| Fertikal NV |
| Koppert Biological Systems BV |
| Plantin |
| HELLO NATURE ITALIA srl |
| APC AGRO |
| RovensaNext |
| Agribios Italiana s.r.l. |
| Others |
Supply & Pricing Matrix
Captive integration into substrate sourcing anchors both cost control and premium positioning for European biological organic fertilizer manufacturers. Dutch greenhouse operators and French cereal cooperatives leverage backward integration into compost processing and anaerobic digestion to secure supply continuity while capturing margin from certified organic end-products.
Pricing Analysis
Input-cost pass-through from livestock manure and municipal green waste substrates determines contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-pre-approved microbial formulations from composted manures and raw digestates. Certification grade and cold chain logistics requirements drive price differentiation between horticulture and broadacre channels. Pricing pressure stems from natural gas volatility creating intermittent synthetic nitrogen price advantages. Transitional farmers in Poland and eastern Germany exhibit highest price sensitivity; Dutch greenhouse exporters absorb premium input costs for residue-free certification.
Supply Chain Analysis
REACH substrate sourcing mandates and national organic certification rules are reshaping procurement toward documented domestic feedstocks. Supply concentrates in the Netherlands, France, and Spain, with Dutch greenhouse clusters and French cereal cooperatives anchoring volume procurement. Raw material dependencies center on livestock manure streams, municipal green waste, and marine biomass for seaweed extracts. Single-source vulnerability runs through specialized microbial strain suppliers concentrated in academic and large corporate laboratories. Distribution runs through cooperative buying groups in northwest Europe and regional distributors serving fragmented Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in microbial formulation tiers where EFSA pre-approval creates scarcity value, and in sensor-integrated application systems that bundle hardware with recurring input subscriptions.
For Market Incumbents: To counter cooperative procurement consolidation compressing pure-product margins, incumbents should deepen technical service bundling with embedded agronomists and pursue backward integration into anaerobic digestion facilities to secure substrate supply. EFSA microbial strain pipeline investment creates regulatory moats that delay generic competition. For New Entrants and Emerging Players: The gap between premium microbial formulations and economy compost tiers offers entry space for mid-grade processed manure products with batch traceability. Poland's synthetic-dependent broadacre cereal operations represent the most penetrable geography, with EU-funded sustainable agriculture pilots providing anchor contracts. A cooperative technical service partnership model bypasses capital-intensive direct sales infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional manure processors with certified organic capacity because REACH compliance burdens favor scaled documentation systems over fragmented operators. Mid-term viability hinges on EFSA evaluation protocol streamlining. Acquisition targets should demonstrate existing CE-marked product portfolios. The signal to watch is EFSA microbial strain pre-approval timeline compression indicating regulatory pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Microbial Strain Pre-Approval Investment | Streamlined evaluation protocols reduce registration timelines for novel consortia and create first-mover premiums. |
| Backward Integration into Anaerobic Digestion | Captive substrate supply secures phosphorus recovery streams and insulates against livestock manure price volatility. |
| Sensor-Based Application System Partnerships | Variable-rate spreader compatibility extends microbial formulation viability through precision delivery timing. |
| Cooperative Technical Service Bundling | Multi-year contracts with French and German farm cooperatives concentrate buyer relationships beyond product transactions. |
| Cross-Border Distribution Network Expansion | Regional distributors extend reach into Spain's Murcia and Italy's Po Valley specialty crop clusters. |
Research Methodology
Coverage spans northwest Europe, the Mediterranean basin, and eastern European transition markets, with primary inputs from each. The analysis combines structured interviews with product formulators, cooperative procurement managers, greenhouse operations directors, and regulatory affairs specialists with secondary validation from EFSA evaluation databases, ECHA substance notifications, EU Green Deal implementation reports, and national organic certification registries. Bottom-up demand modeling from farm-level input intensity and top-down macro constraint triangulation anchor volume and value estimates.
Granularity-level modeling disaggregates the projection horizon by product chemistry, application intensity, and procurement sophistication. Segmentation dimensions include microbial versus compost versus manure formulations, horticulture versus agronomy end-uses, and direct sales versus wholesale versus retail channels. CAGRs derive from trend extrapolation moderated by regulatory timeline and technology adoption curve assumptions. Industry-specific forecast inputs incorporate EU nitrogen cap implementation schedules and cold chain infrastructure development patterns.
Caveats apply where EFSA microbial strain evaluation delays, synthetic fertilizer price volatility spikes, or REACH substance classification scope expansions could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pathway timelines and farm budget reallocation elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Marine Biotechnology Market