
 Horticulture Bioplastic Market | 2026-2036
Horticulture Bioplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Horticulture Bioplastic Market Analysis
European biopolymer producers is repositioning capacity toward horticulture-grade resins as agricultural plastic bans tighten across the continent. NatureWorks LLC leverages its Blair, Nebraska fermentation complex to supply high-purity PLA pellet streams optimized for mulch film extrusion. BASF SE anchors its position through backward integration into PBAT monomer production, securing cost advantages in greenhouse cover applications. Total Corbion PLA competes aggressively on optical clarity specifications critical to nursery propagation trays.
Horticulture bioplastic denotes polymer formulations engineered to maintain structural integrity through single growing seasons before undergoing microbial decomposition in soil or industrial composting environments, typically achieving complete biodegradation within defined temperature and humidity parameters. These materials serve the primary commercial purpose of eliminating polyethylene retrieval costs and soil contamination risks in intensive cultivation systems. Mulch film dominates current volume flows due to its direct replacement of conventional polyethylene in row-crop production, while PHA grades command premium positioning in ornamental horticulture where marine biodegradability certifications unlock landscaping contracts near sensitive watersheds. Starch blends occupy the economy tier of seed tray applications where short functional lifespans minimize performance requirements.
The EU Green Deal and REACH frameworks restrict persistent microplastic release from agricultural films, compelling reformulation toward certified compostable chemistries. FDA and USDA BioPreferred specifications in the United States create parallel compliance pathways for exporters seeking North American market access. Stakeholders must monitor evolving soil biodegradability test protocols across jurisdictions, as harmonization failures between EN 13432 and ASTM D6400 threaten to fragment product certification requirements and complicate cross-border supply strategies.
Market Dynamics
EU Green Deal plastics reduction mandates are forcing immediate reformulation of agricultural films toward certified soil-biodegradable chemistries, compressing adoption timelines from voluntary preference to compliance-driven procurement.
Growth Catalysts
- REACH microplastic restrictions:The European Chemicals Agency's tightening limits on persistent polymer release in agricultural soils compel commercial growers to replace polyethylene mulch with certified compostable alternatives ahead of enforcement deadlines.
- Soil contamination liability:Intensive vegetable operations in Spain and Italy face escalating remediation costs from legacy plastic accumulation, accelerating conversion to single-season biodegradable films that eliminate retrieval labor.
- PHA fermentation scale-up:Advances in microbial production economics for polyhydroxyalkanoates are narrowing cost gaps with conventional resins, unlocking marine-biodegradable certifications for watershed-proximate landscaping contracts.
Market Restraints
- Feedstock cost volatility:Corn starch and sugarcane sucrose prices fluctuate with biofuel policy shifts, compressing margins for PLA and starch-blend producers dependent on agricultural commodity inputs.
- PBAT monomer concentration:Butanediol and adipic acid supply chains cluster in Northeast Asian petrochemical complexes, exposing European compounders to freight cost spikes and currency exposure.
- Soil temperature dependency:Biodegradation rates for certified films collapse below 10°C, limiting reliable performance in Nordic spring cultivation windows and delaying regional adoption.
Strategic Opportunities
- Netherlands greenhouse cluster:The Westland region's 4,000 hectares of intensive glasshouse operations remain underpenetrated by compostable propagation trays, presenting volume scale for optical-grade PLA suppliers.
- USDA BioPreferred procurement:Federal purchasing preferences for biobased horticulture inputs create a parallel compliance pathway for European exporters seeking North American institutional contracts.
- Drone-applied mulch films:Convergence of precision agriculture equipment with ultra-thin biodegradable formulations enables mechanized laying in row-crop systems previously resistant to manual film deployment.
Industry Challenges
- EN 13432/ASTM D6400 harmonization gaps:Divergent industrial composting test protocols between European and North American certification bodies fragment product specifications and complicate cross-border inventory management.
- Extrusion technician scarcity:The specialized skill set for processing heat-sensitive biopolymers without thermal degradation concentrates in legacy packaging film workforces, constraining horticulture-grade capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horticulture Bioplastic Market |
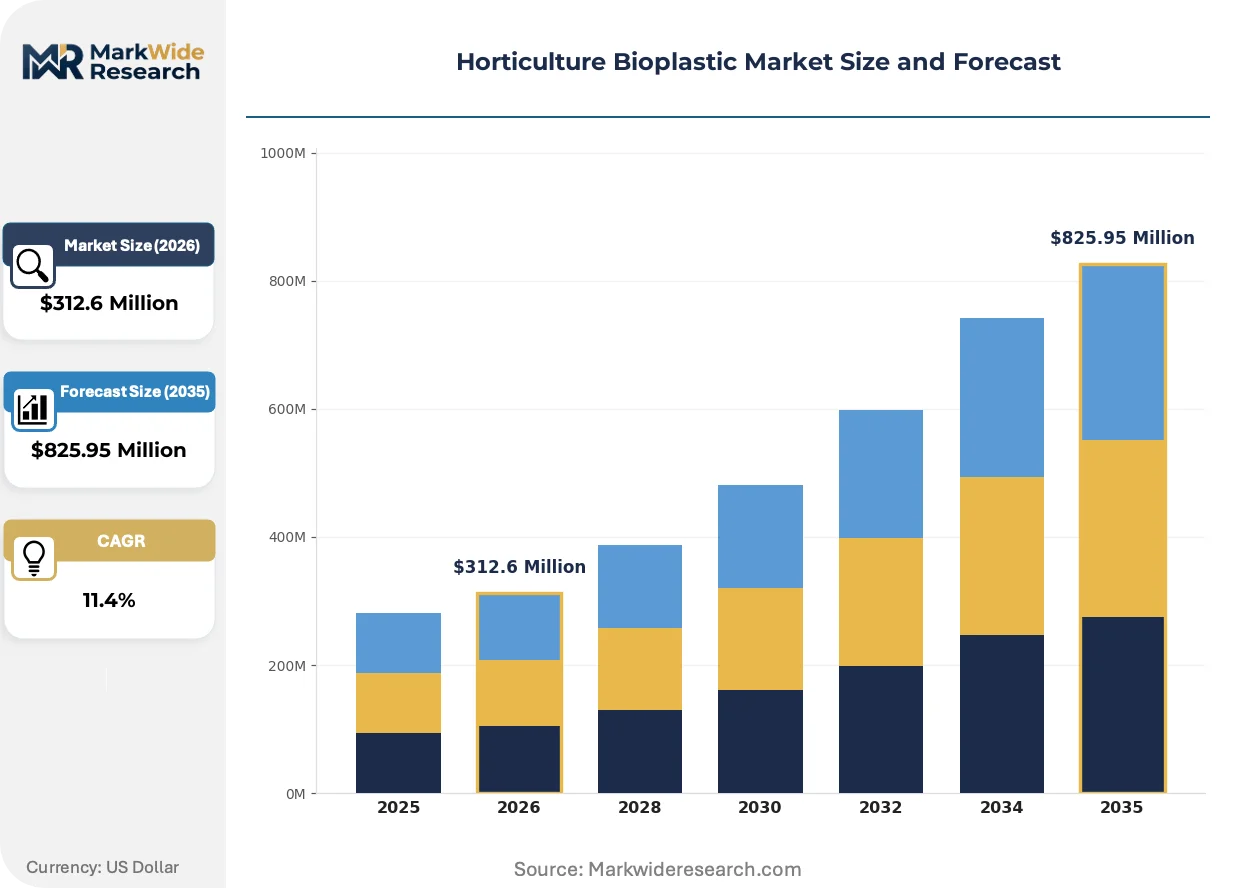
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $825.95 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mulch Film, Plant Pots, Seed Trays, Greenhouse Covers Material: PLA, PHA, Starch Blends, PBAT End User: Commercial Growers, Retail Nurseries, Home Gardeners, Landscaping Services Application: Agricultural Production, Ornamental Horticulture, Nursery Production, Greenhouse Management |
| Companies Covered | NatureWorks LLC, Danimer Scientific, BASF SE, Novamont S.p.A, Green Dot Bioplastics, Biome Bioplastics Limited, Total Corbion PLA, Braskem S.A., FKuR Kunststoff GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horticulture Bioplastic Market Emerging Trajectories
Active reformulation of polymer architectures is compressing functional lifespans while accelerating soil decomposition rates, enabling precise matching of material durability to crop cycle lengths.
Multilayer coextrusion technology is integrating PLA surface layers with PBAT core structures to combine optical clarity for weed suppression with mechanical toughness for wind resistance. German tomato greenhouse operators are adopting these constructions at commercial scale during the 2024-2025 growing seasons. The approach is integrating performance attributes previously requiring separate film products, collapsing SKU complexity for distributor inventories.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based greenhouse climate control, indirectly pressuring cover film suppliers to demonstrate thermal performance without high-emission heating dependencies. Spanish pepper producers in Almería are responding by specifying infrared-blocking bioplastic formulations that reduce nocturnal heat loss. This regulatory pressure is redirecting R&D budgets from opacity tuning toward emissivity engineering.
Certification-driven specification is displacing price-primary procurement in Dutch auction supply chains, where supermarket sustainability scorecards now weight soil-biodegradability credentials above per-meter film cost. French retail cooperatives are mandating TÜV OK compost SOIL labels for supplier qualification. This behavioral shift is most visible in Belgian endive forcing operations, where grower-processor contracts now embed bioplastic compliance clauses with penalty structures for non-conformance.
Horticulture Bioplastic Market Segmentation
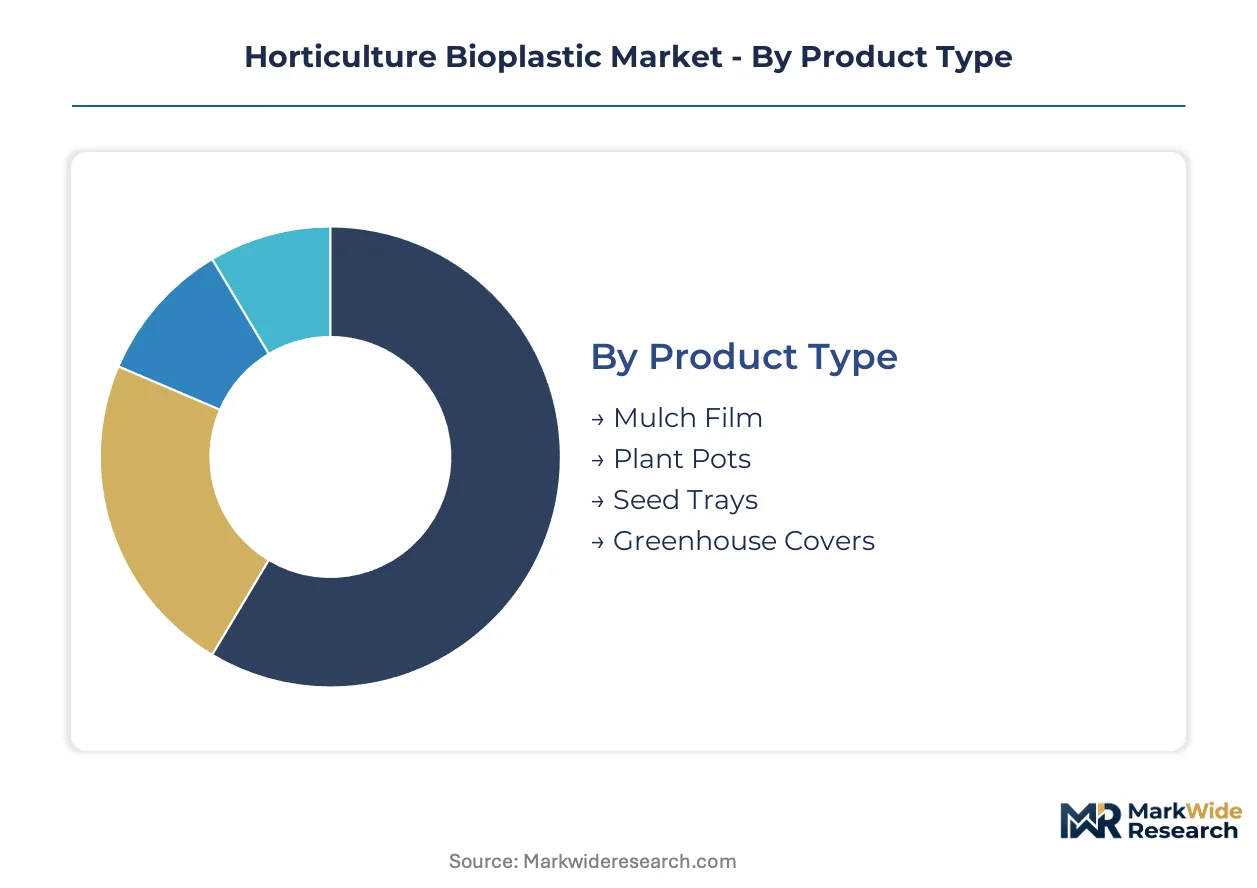
Segmentation in horticulture bioplastics reveals how capital deployment, regulatory exposure, and biodegradation performance requirements fragment procurement patterns across cultivation systems. Material chemistry and film thickness specifications determine which grower categories can absorb premium pricing, while application durability needs dictate replacement cycles and inventory turnover.
Product Type:
Capital intensity varies sharply across product categories, with extrusion equipment for thin-gauge mulch film demanding substantially higher upfront tooling investment than thermoformed propagation containers.
- Mulch Film:Ultra-thin extruded sheets formulated for single-season soil coverage dominate current resin offtake. German vegetable operations in Lower Saxony are converting polyethylene acres fastest, driven by EU Green Deal retrieval cost penalties and TÜV OK compost SOIL certification requirements for supermarket contract eligibility.
- Plant Pots:Injection-molded containers with wall thicknesses engineered for mechanical transplanting withstand 12-18 month functional lifespans. Dutch ornamental producers specify these for automated greenhouse logistics where structural integrity during robotic handling overrides rapid biodegradation timelines.
- Seed Trays:Shallow-celled propagation formats prioritize optical clarity for root inspection and rapid thermal cycling in germination chambers.
- Greenhouse Covers:Large-area blown films require infrared-blocking additives and anti-drip surface treatments to manage condensation and nocturnal heat retention in Almería-style protected cultivation.
Mulch film absorbs the bulk of installed capacity; greenhouse covers are expanding most quickly.
Material:
Feedstock sourcing geography and fermentation scale economics segment material selection, with corn belt proximity favoring PLA adoption and petrochemical integration determining PBAT competitiveness.
- PLA:High-purity polylactic acid pellets from Blair, Nebraska supply optical-grade clarity specifications for propagation trays and greenhouse covers. Spanish pepper producers specify PLA surface layers in multilayer constructions to combine weed suppression visibility with mechanical durability.
- PBAT:Butanediol-adipic acid copolyesters deliver the flexibility and tear resistance required for mulch film field laying. BASF's backward integration into monomer production anchors European supply security for this segment.
- PHA:Microbial polyhydroxyalkanoates command premium positioning where marine biodegradability certifications unlock watershed-proximate landscaping contracts.
- Starch Blends:Compounded thermoplastic starches occupy economy-tier seed tray applications where short functional lifespans minimize performance requirements and cost sensitivity dominates procurement.
PLA claims the largest share of current compounding capacity; PHA is climbing the fastest as fermentation scale economics improve.
End User:
Procurement sophistication and sustainability mandate exposure segment end users, with institutional buyers embedding compliance clauses that downstream garden centers cannot match.
- Commercial Growers:Intensive vegetable and ornamental operations with direct supermarket supply contracts face the steepest compliance pressure. Belgian endive forcing operations now embed bioplastic penalty structures for non-conformance with retailer sustainability scorecards.
- Retail Nurseries:Consumer-facing garden centers prioritize shelf aesthetics and point-of-sale biodegradability labeling over field-proven soil decomposition performance.
- Home Gardeners:Small-scale cultivation represents price-sensitive demand concentrated in seasonal peaks, with product availability through mass retail channels determining adoption.
- Landscaping Services:Municipal and commercial grounds maintenance contracts near sensitive watersheds specify marine-biodegradable grades where runoff contamination liability concentrates procurement discretion.
Commercial growers absorb the bulk of certified compostable volume; landscaping services are gaining share fastest on watershed protection mandates.
Application:
Functional durability requirements and retrieval labor economics segment applications, with open-field systems benefiting most from elimination of polyethylene recovery costs.
- Agricultural Production:Row-crop and intensive vegetable systems in Spain and Italy face escalating soil contamination liability from legacy plastic accumulation. Italian tomato cooperatives are specifying soil-biodegradable mulch to eliminate retrieval labor and disposal fees.
- Ornamental Horticulture:Nursery propagation and container production prioritizes optical clarity for root health monitoring and aesthetic presentation in retail channels.
- Nursery Production:Specialized propagation operations require precise matching of container degradation rates to transplant timing, with premature failure causing crop loss and delayed decomposition blocking field replanting.
- Greenhouse Management:Climate control film specifications are redirecting from opacity tuning toward emissivity engineering as EU F-Gas Regulation phase-down eliminates hydrofluorocarbon heating dependencies.
Agricultural production commands the bulk of mulch film deployment; greenhouse management is expanding most quickly on thermal performance reformulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nebraska corn belt fermentation complexes anchor North American PLA supply chains, while European petrochemical integration around Ludwigshafen and Tarragona secures PBAT monomer flows for mulch film compounders.
Germany
Lower Saxony vegetable growers are converting polyethylene mulch acres fastest under EU Green Deal retrieval cost penalties. The F-Gas Regulation phase-down eliminates hydrofluorocarbon greenhouse heating, redirecting cover film specifications toward infrared-blocking bioplastic formulations. BASF's Ludwigshafen complex anchors backward integration into butanediol-adipic acid monomer production for regional compounders.
Spain
Almería intensive greenhouse operators face escalating soil contamination liability from legacy plastic accumulation, accelerating certified compostable mulch adoption. The national packaging law transposes EU single-use plastics directives into farm-level procurement mandates. Andalusian pepper cooperatives are specifying multilayer PLA-PBAT constructions to combine weed suppression with mechanical durability.
Netherlands
Westland region glasshouse operations represent underpenetrated demand for optical-grade PLA propagation trays across 4,000 hectares of intensive cultivation. Dutch auction supply chains now weight TÜV OK compost SOIL labels above per-meter film cost in supermarket sustainability scorecards. Belgian endive forcing operations embed bioplastic penalty structures for non-conformance with retailer contracts.
United States
USDA BioPreferred procurement preferences create federal purchasing pathways for biobased horticulture inputs, parallel to European compliance frameworks. The Blair, Nebraska fermentation complex supplies high-purity PLA pellet streams optimized for mulch film extrusion. California Central Valley tomato producers are piloting soil-biodegradable mulch to eliminate seasonal retrieval labor costs.
Italy
Po Valley vegetable cooperatives specify certified compostable films to eliminate polyethylene disposal fees and soil remediation liabilities. National transposition of REACH microplastic restrictions compels reformulation ahead of enforcement deadlines. Emilia-Romagna tomato forcing operations are converting to single-season biodegradable films that decompose within defined temperature parameters.
Horticulture Bioplastic Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue marine-biodegradable certifications and precision agriculture integrations. The vendor base clusters around three strategic archetypes: petrochemical-integrated compounders with captive monomer supply, fermentation-based biopolymer specialists, and regional toll compounders serving niche cultivation systems. Dominant competitive moves include backward integration into feedstock fermentation and strategic partnerships with precision agriculture equipment manufacturers.
Among petrochemical-integrated compounders, BASF SE exemplifies the backward-integrated archetype through captive butanediol-adipic acid production. NatureWorks LLC anchors the fermentation-specialist tier with Nebraska-based lactic acid fermentation capacity. Total Corbion PLA occupies a position between these models, combining sugar feedstock sourcing with optical-grade PLA specifications for propagation tray applications.
| Leading Market Players |
|---|
| NatureWorks LLC |
| Danimer Scientific |
| BASF SE |
| Novamont S.p.A |
| Green Dot Bioplastics |
| Biome Bioplastics Limited |
| Total Corbion PLA |
| Braskem S.A. |
| FKuR Kunststoff GmbH |
| Others |
Supply Flow & Price Mechanics
Corn starch futures and sugarcane commodity benchmarks cascade through fermentation-based PLA production into three-tier pricing structures across premium, standard, and economy levels. PBAT compounders absorb butanediol and adipic acid cost volatility from Northeast Asian petrochemical complexes, compressing margins for European mulch film extruders serving German supermarket supply chains.
Pricing Analysis
Warranty-backed soil-biodegradability certifications bundle TÜV OK compost SOIL labels and marine-biodegradability guarantees into premium horticulture resin tiers. Three-tier pricing structure across premium, standard, and economy levels separates PHA grades with watershed certifications from commodity starch-blend seed trays. Cost compression in standard-tier PBAT mulch films intensifies because of freight cost spikes from Asian monomer supply chains. Home gardeners through mass retail channels exhibit the highest price sensitivity, while Belgian endive forcing operations under retailer penalty structures show the least.
Supply Chain Analysis
Extrusion technician scarcity in German and Dutch manufacturing corridors constrains horticulture-grade biopolymer capacity expansion beyond legacy packaging film workforces. Supply concentrates in the United States through Nebraska corn belt fermentation complexes, Germany via Ludwigshafen petrochemical integration, and Thailand around sugarcane-derived lactic acid processing. Raw material dependencies draw from corn starch, sugarcane sucrose, and butanediol-adipic acid monomer streams. Single-source vulnerability in PBAT precursor supply chains exposes European compounders to currency and logistics disruption. Distribution runs through agricultural cooperative procurement networks and precision agriculture equipment OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH microplastic enforcement deadlines and retrieval cost penalties force undercapitalized toll compounders toward exit or acquisition.
For Market Incumbents: Anticipate fermentation scale-up economics narrowing PHA cost gaps and eroding PLA premium positioning in ornamental horticulture. Backward integration into captive monomer production anchors margin defense against Asian petrochemical supply volatility. Certification investment in harmonized EN 13432/ASTM D6400 protocols protects cross-border inventory positions from regulatory fragmentation. For New Entrants and Emerging Players: Precision agriculture equipment OEMs represent the most accessible channel partners for drone-applied mulch film formulations previously resistant to manual deployment. Underpenetrated demand in Netherlands Westland greenhouse propagation trays offers white-space volume for optical-grade PLA suppliers. Marine-biodegradable certification pathways unlock municipal landscaping contracts near sensitive watersheds with concentrated procurement discretion. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-specialist mid-caps with Nebraska or Thai feedstock proximity and existing supermarket supply chain relationships. Long-term viability across the next decade hinges on regulatory harmonization progress and precision agriculture equipment convergence. Watch for TÜV OK compost SOIL label adoption velocity in Dutch auction supply chains as the inflection signal for premium-tier pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | BASF's Ludwigshafen complex secures PBAT cost advantages against Asian supply volatility. |
| Marine-Biodegradability Certification Investment | PHA grades unlock watershed-proximate landscaping contracts near sensitive Spanish and Italian coastlines. |
| Precision Agriculture Equipment Partnership | Drone-applied mulch film convergence enables mechanized laying in resistant row-crop systems. |
| Optical-Grade PLA Capacity Expansion | Total Corbion PLA targets Netherlands Westland greenhouse propagation tray underpenetration. |
| Harmonized Certification Protocol Development | Dual EN 13432/ASTM D6400 compliance reduces cross-border inventory fragmentation for exporters. |
Methodological Framework
Independent corroboration across agricultural cooperative procurement managers, precision agriculture equipment OEM technical directors, biopolymer plant fermentation engineers, and supermarket sustainability compliance officers underwrites the qualitative findings. Secondary validation draws from EU F-Gas Regulation implementation tracking, REACH microplastic restriction enforcement schedules, USDA BioPreferred procurement databases, and customs trade data on corn starch and sugarcane derivative flows. Bottom-up resin offtake modeling triangulates against top-down cultivation system penetration estimates.
Comparable-period anchoring to historical EU Green Deal implementation phases and F-Gas Regulation phase-down schedules structured the projection horizon. The analytical framework segments by material chemistry, film thickness specification, cultivation system type, and regional regulatory cluster. CAGRs derive from weighted average adoption curves across enforcement deadline cohorts. Forecast inputs include fermentation scale-up economics for PHA and multilayer coextrusion technology diffusion rates in German tomato greenhouse operations.
Caveats apply where EN 13432/ASTM D6400 harmonization failures, corn starch price volatility from biofuel policy shifts, or Nordic spring soil temperature collapses below biodegradation thresholds could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Fish Vaccines Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Global Feed Phytogenics Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Agricultural Biologicals Market