
 Asia-Pacific Agricultural Biologicals Market | 2026-2036
Asia-Pacific Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Biologicals Market Insights
Specialty fruit and vegetable growers are reorganizing procurement priorities around residue-free crop protection, pulling demand from broad-acre grain operations that historically dominated biological offtake. BASF SE leverages its microbial fermentation infrastructure to supply high-potency rhizobia strains across Australian viticulture regions. Syngenta AG anchors its regional position through integrated seed-treatment biologicals bundled with hybrid genetics. UPL Limited competes via extensive distribution through Indian agricultural cooperatives that reach smallholder networks.
Agricultural biologicals comprise living microorganisms, botanical extracts, and biochemical compounds formulated to enhance crop nutrition, suppress pests, or stimulate plant defenses through modes distinct from conventional synthetic chemistry. These inputs typically require storage between four and twenty-five degrees Celsius to preserve viable cell counts, and their efficacy depends on soil pH, moisture, and organic carbon levels that modulate microbial colonization. Microbial products dominate current revenue as mature fermentation platforms deliver consistent batch quality at scale, while biopesticides represent the fastest-expanding category as resistance management protocols in integrated pest management programs mandate rotation away from single-site synthetic modes. Biofungicides command premium positioning in protected horticulture systems where humidity-driven disease pressure justifies repeated foliar applications.
India's FSSAI residue standards and Australia's APVMA biological data requirements are tightening product registration pathways, forcing reformulation investments that favor firms with established toxicology dossiers. China's MEE enforcement of pesticide runoff limits in the Yangtze basin is redirecting procurement toward bioherbicides with shorter soil half-lives. Stakeholders must monitor how Japan's amended Agricultural Chemicals Regulation Act treats metabolites of microbial origin, as this classification will determine whether existing registrations require supplemental ecotoxicology studies or qualify for streamlined renewal.
Market Dynamics
Specialty crop growers across Southeast Asia are reorganizing procurement priorities around residue-free crop protection, pulling demand from broad-acre grain operations that historically dominated biological offtake. India's PLI scheme for agri-input manufacturing is accelerating domestic production capacity while water stress in Australia's horticulture belt drives biological alternatives to synthetic chemistry.
Growth Catalysts
- FSSAI Residue Standards:India's tightening maximum residue limits for fresh produce exports are compelling growers to adopt microbial inoculants and biopesticides that leave negligible chemical traces.
- Protected Horticulture Expansion:Vietnam's greenhouse vegetable sector is scaling rapidly, creating concentrated demand for biofungicides that manage humidity-driven disease pressure without synthetic chemistry.
- Soil Microbiome Research:Advances in metagenomic sequencing are enabling strain-specific formulation of rhizobia and mycorrhizal products tailored to acidic tropical soils.
Market Restraints
- Cold Chain Infrastructure:Microbial products requiring four to twenty-five degrees Celsius storage face viability losses across Southeast Asia's fragmented distribution networks.
- Registration Timeline Friction:Australia's APVMA biological data requirements demand multi-year ecotoxicology dossiers that delay market entry for novel strains.
- Synthetic Chemistry Substitution:Generic glyphosate and neonicotinoid alternatives retain cost advantages for broad-acre grain growers in price-sensitive procurement decisions.
Strategic Opportunities
- Seed-Treatment Integration:Biological coating technologies applied at hybrid seed production facilities are capturing value upstream of traditional farm-gate sales channels.
- Indonesian Archipelago Penetration:Java's vegetable cooperatives remain underpenetrated by microbial inoculant suppliers due to archipelago logistics complexity.
- China's Yangtze Runoff Mandates:MEE enforcement of pesticide discharge limits is redirecting procurement toward bioherbicides with abbreviated soil half-lives in rice-wheat systems.
Industry Challenges
- Formulation Stability Expertise:Shelf-life extension of liquid microbial concentrates requires specialized fermentation scientists in short supply across the region.
- Metabolite Classification Uncertainty:Japan's amended Agricultural Chemicals Regulation Act has not clarified whether microbial metabolites trigger supplemental ecotoxicology requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Biologicals Market |
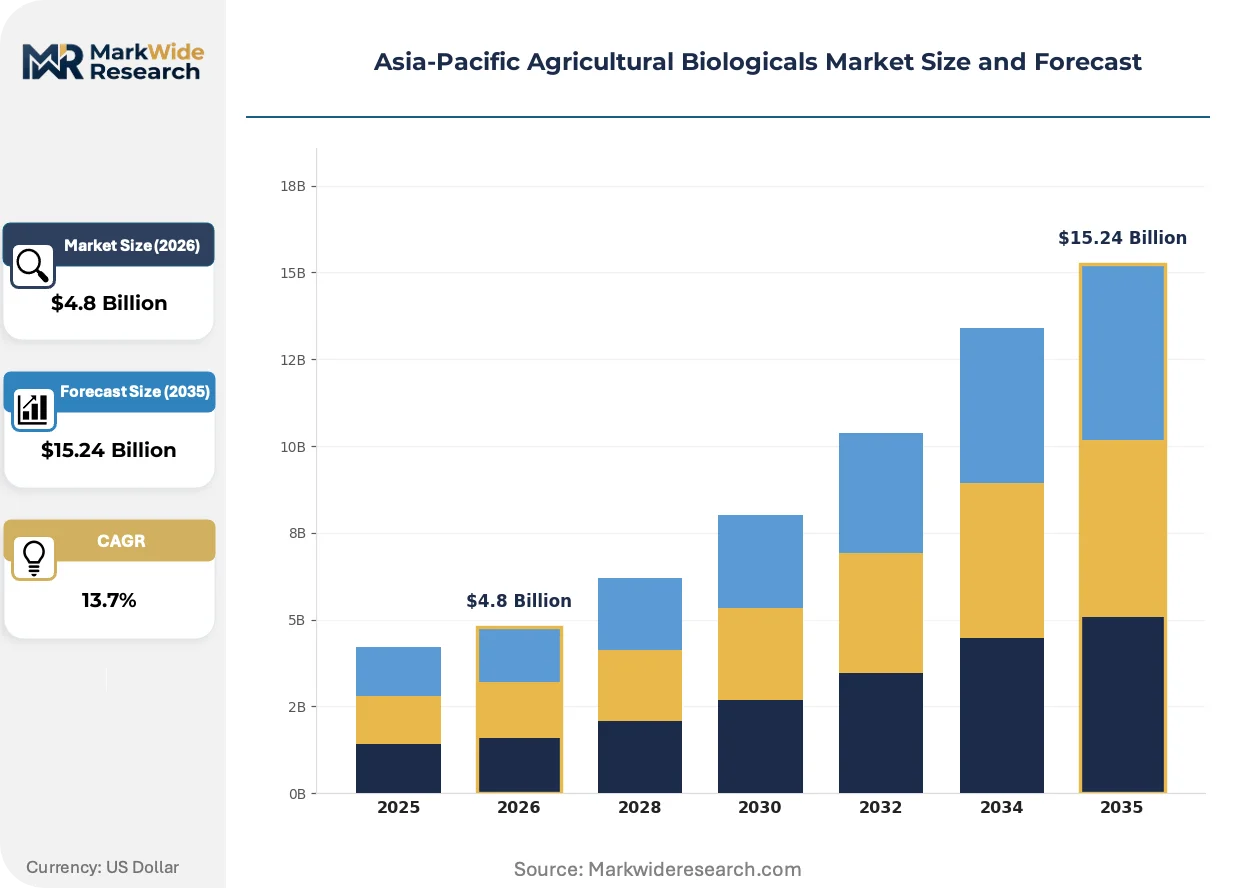
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Products, Biopesticides, Biofungicides, Bioherbicides End Use Industry: Agronomy, Horticulture, Viticulture, Floriculture Application: Soil Treatment, Seed Treatment, Foliar Spray, Post-Harvest Distribution Channel: Direct Sales, Online Retail, Wholesale, Agricultural Cooperatives |
| Companies Covered | BASF SE, Syngenta AG, UPL Limited, Bayer AG, Corteva Agriscience, Lallemand Inc, Novozymes, Coromandel International Ltd, T. Stanes and Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Biologicals Market Trends and Innovations
Biological active ingredient platforms are converging with precision application technologies, reshaping how growers integrate living inputs into intensive production systems. Formulation science and digital agriculture are compressing the traditional gap between biological potential and field-level consistency.
RNA-interference biopesticides targeting lepidopteran pests in brassica and solanaceous crops are supplanting Bt toxin formulations that face resistance pressure in intensive horticulture zones. Thai and Vietnamese vegetable exporters are piloting these nucleic acid-based products ahead of EU residue compliance deadlines. The technology is compressing development timelines for novel modes of action while raising manufacturing complexity and regulatory classification questions.
China's MEE is enforcing pesticide runoff limits in the Yangtze basin through watershed-specific discharge permits that penalize synthetic chemistry persistence. Rice-wheat rotation systems in Jiangsu and Hubei provinces are responding with bioherbicide procurement that meets shortened soil half-life thresholds. The policy is redirecting research investment toward allelopathic microbial strains with documented degradation kinetics.
Direct-to-farm digital platforms are fragmenting traditional cooperative-based distribution in India's Maharashtra and Karnataka vegetable belts. Growers are accessing strain-specific microbial products through agritech applications that bypass mandi intermediaries and provide application timing algorithms. This channel compression is most visible in grape and pomegranate export zones where residue documentation requirements favor traceable input sourcing.
Asia-Pacific Agricultural Biologicals Market Segmentation
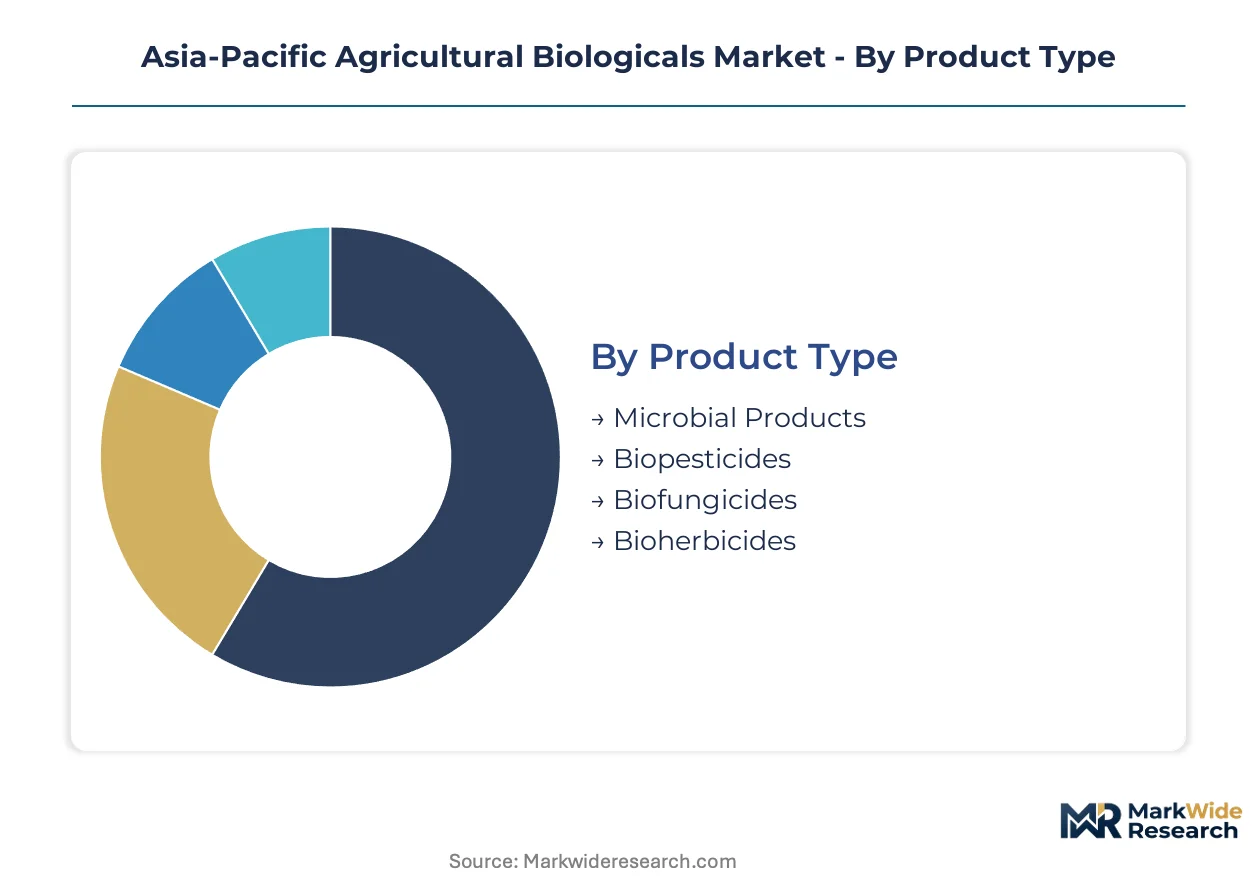
Segmentation reveals how biological input demand fragments across crop systems, application methods, and procurement channels. Each dimension exposes distinct technical requirements, regulatory exposures, and margin structures that reshape supplier positioning across the region.
Product Type:
Domestic fermentation capacity in India and China supplies Microbial Products and Biopesticides for local grain and vegetable systems, while Biofungicides and specialized Bioherbicides serve export-oriented horticulture in Australia and Vietnam.
- Microbial Products:Living bacterial and fungal formulations including rhizobia, mycorrhizae, and plant growth-promoting microbes cultivated through submerged fermentation. Australian viticulture regions concentrate demand for high-potency rhizobia strains that colonize acidic vineyard soils under water stress conditions.
- Biopesticides:Microbial and biochemical agents targeting insect pests through modes distinct from synthetic neurotoxins. Vietnam's greenhouse vegetable exporters are pulling nucleic acid-based RNA interference formulations ahead of EU residue compliance deadlines.
- Biofungicides:Trichoderma and Bacillus-based formulations suppressing fungal pathogens in humid environments. These command premium positioning in protected horticulture systems.
- Bioherbicides:Allelopathic microbial strains and botanical extracts managing weed pressure. China's Yangtze basin rice-wheat systems are redirecting procurement here to meet MEE runoff mandates.
Microbial Products holds the largest share; momentum sits with Biopesticides.
End Use Industry:
Margin structures diverge sharply between broad-acre commodity systems and intensive export-oriented cropping, with the latter absorbing premium biological pricing.
- Agronomy:Field crop production of cereals, oilseeds, and pulses across rainfed and irrigated systems. Indian wheat and rice growers under FSSAI residue pressure are adopting microbial inoculants at scale.
- Horticulture:Intensive fruit and vegetable production in greenhouses and open fields. Vietnam's protected vegetable sector is scaling biofungicide applications for humidity-driven disease management.
- Viticulture:Wine grape cultivation concentrated in Australia's Murray-Darling and cooler climate regions. Water stress is displacing synthetic chemistry with biological alternatives in canopy and soil management.
- Floriculture:Cut flower and ornamental production for domestic and export markets. Thai rose and orchid exporters are piloting residue-free protocols.
Horticulture generates the highest biological input intensity per hectare; Viticulture shows the steepest substitution trajectory from synthetic chemistry.
Application:
Application method determines formulation requirements, equipment compatibility, and timing windows that segment supplier technical capabilities.
- Soil Treatment:Direct incorporation of microbial inoculants into root zone environments. Southeast Asian specialty crop growers are reorganizing procurement priorities around soil microbiome restoration for residue-free output.
- Seed Treatment:Biological coating applied to hybrid seed prior to sowing. Integrated seed-treatment biologicals bundled with genetics are capturing value upstream of farm-gate channels.
- Foliar Spray:Aerial or ground application of biocontrol agents to plant surfaces. Protected horticulture systems justify repeated applications under humidity-driven disease pressure.
- Post-Harvest:Biological treatments extending shelf life and managing storage pathogens. This segment remains underdeveloped relative to pre-harvest applications.
Soil Treatment dominates current volume; Seed Treatment is expanding most quickly through integrated supply chains.
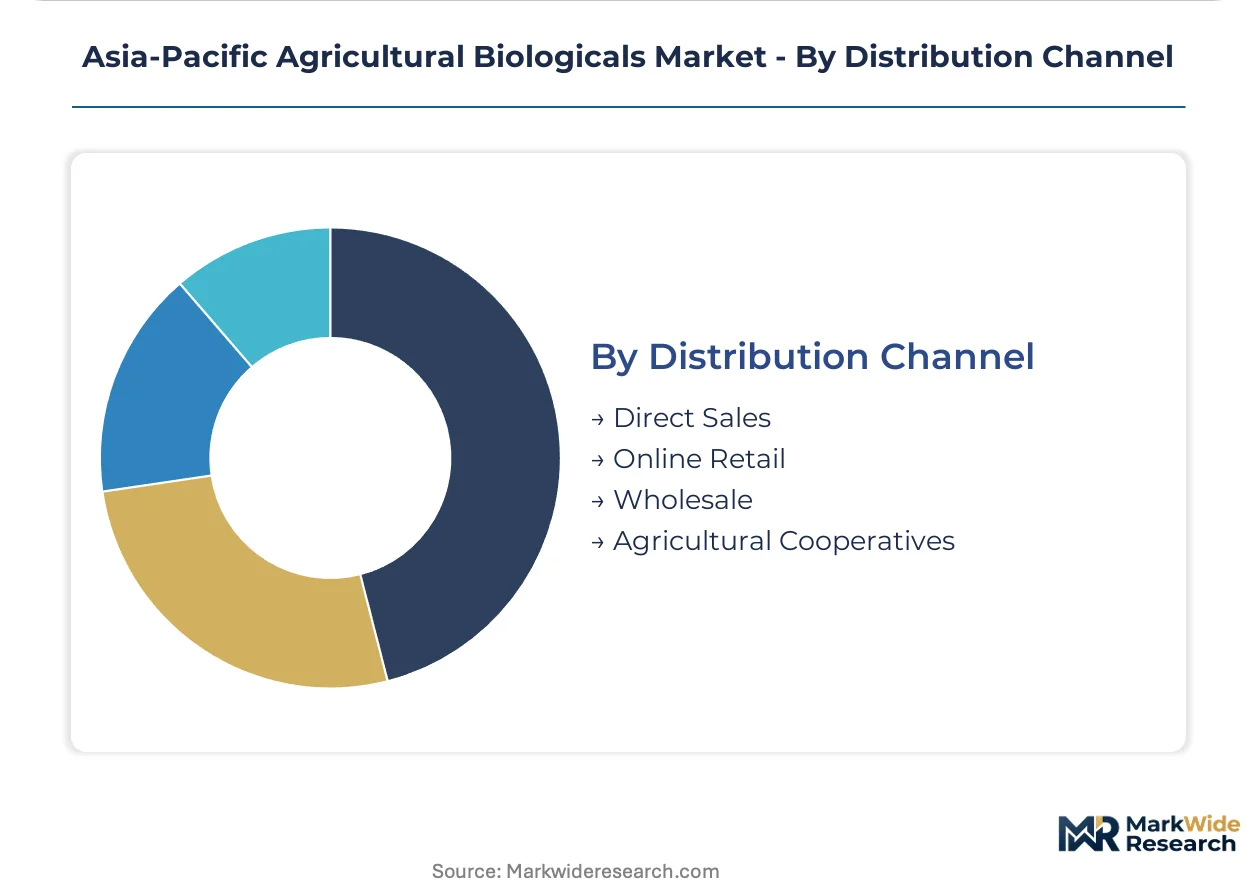
Distribution Channel:
Channel structure reflects farm scale, digital penetration, and cooperative density across national agricultural systems.
- Direct Sales:Manufacturer-to-grower relationships for large-scale commercial operations. Australian horticulture enterprises source directly for technical support and residue documentation.
- Online Retail:Agritech platforms connecting manufacturers with growers through digital interfaces. Maharashtra and Karnataka vegetable belts are fragmenting traditional cooperative-based distribution via direct-to-farm applications.
- Wholesale:Aggregator networks supplying input dealers and regional distributors. These retain importance in fragmented Southeast Asian markets.
- Agricultural Cooperatives:Member-based procurement organizations reaching smallholder networks. UPL Limited competes extensively through Indian cooperative channels.
Agricultural Cooperatives hold the broadest smallholder reach; Online Retail is gaining share fastest in export-oriented production zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports biological inputs to Southeast Asian horticulture markets through established maritime corridors, with Vietnam and Thailand serving as primary demand anchors for residue-free crop protection systems.
India
Domestic fermentation capacity expansion under the PLI scheme is accelerating microbial inoculant production for wheat and rice systems. FSSAI residue standards for fresh produce exports are compelling growers to adopt biopesticides with negligible chemical traces. Maharashtra and Karnataka vegetable belts are fragmenting traditional cooperative distribution through direct-to-farm agritech platforms.
China
Rice-wheat rotation systems in Jiangsu and Hubei provinces are redirecting procurement toward bioherbicides with abbreviated soil half-lives. MEE enforcement of pesticide runoff limits in the Yangtze basin is penalizing synthetic chemistry persistence. The Yangtze River Delta research clusters are advancing allelopathic microbial strain development for documented degradation kinetics.
Australia
Water stress across the Murray-Darling horticulture belt is displacing synthetic chemistry with biological alternatives in canopy and soil management. APVMA biological data requirements demand multi-year ecotoxicology dossiers that delay market entry for novel strains. Viticulture regions in cooler climate zones concentrate demand for high-potency rhizobia strains colonizing acidic vineyard soils.
Vietnam
Greenhouse vegetable exporters are scaling biofungicide applications for humidity-driven disease pressure without synthetic chemistry. Protected horticulture expansion is creating concentrated demand for residue-free protocols ahead of EU compliance deadlines. The Mekong Delta vegetable cooperatives remain underpenetrated by microbial inoculant suppliers due to archipelago logistics complexity.
Japan
Amended Agricultural Chemicals Regulation Act uncertainty around microbial metabolite classification is forcing reformulation investments. METI guidance on supplemental ecotoxicology requirements remains pending for existing registrations. Kanto region precision agriculture adopters are piloting RNA-interference biopesticides for brassica export compliance.
Asia-Pacific Agricultural Biologicals Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and formulation stability expertise. The vendor base fragments between multinational agrochemical conglomerates with microbial fermentation infrastructure and domestic specialists leveraging cooperative networks. Three archetypes dominate: integrated seed-treatment bundlers, fermentation-platform scale operators, and cooperative-channel penetrators. Competitive moves concentrate on seed-treatment integration upstream of farm-gate channels and archipelago logistics partnerships for island nation penetration.
Within the fermentation-platform tier, BASF SE and Novozymes exemplify capacity-led positioning, while UPL Limited occupies the cooperative-channel archetype through extensive Indian agricultural cooperative networks. Syngenta AG represents the integrated bundler model, anchoring regional position through combined biological and genetic offerings. These three patterns illustrate how scale, distribution depth, and vertical integration into seed production facilities separate competitive outcomes across national agricultural systems.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| UPL Limited |
| Bayer AG |
| Corteva Agriscience |
| Lallemand Inc |
| Novozymes |
| Coromandel International Ltd |
| T. Stanes and Company Limited |
| Others |
Pricing and Supply Chain Analysis
India's FSSAI residue standards and Australia's APVMA biological data requirements simultaneously gate supplier qualification and stratify price tiers, compelling exporters to absorb premium certification costs while generic microbial inoculants compete on volume in domestic grain markets. This regulatory overlay compresses margins for reformulation-heavy portfolios while rewarding established toxicology dossiers with pricing power in protected horticulture channels.
Pricing Analysis
Next-generation RNA-interference biopesticides command substantial premiums over mature Bt toxin formulations and commodity Bacillus-based products, with price differentiation anchored in patent-protected nucleic acid delivery systems and EU residue compliance documentation. Three-tier pricing structure across premium, standard, and economy levels separates export-grade biofungicides with full ecotoxicology packages from domestic microbial inoculants and generic fermentation byproducts. Pricing pressure stems from generic glyphosate alternatives in Indian broad-acre wheat systems, where smallholders exhibit acute price sensitivity. Australian viticulture enterprises show lowest price sensitivity, prioritizing residue-free certification and technical support over per-hectare input costs.
Supply Chain Analysis
Cold chain inventory cycles for liquid microbial concentrates stretch lead times across Southeast Asia's fragmented distribution networks, with viability losses accelerating in ambient storage conditions outside four-to-twenty-five-degree Celsius parameters. Manufacturing concentrates in India, China, and Australia, with fermentation feedstocks drawing from domestic molasses and soy-based substrates. Single-source vulnerability sits with specialized cryoprotectant formulations for shelf-life extension, where regional formulation scientists remain scarce. Distribution runs through agricultural cooperatives in India, direct-to-farm agritech platforms in Maharashtra and Karnataka, and wholesale aggregator networks in Vietnam and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific agricultural biologicals market operates as a defensive-moat arena where regulatory entrenchment creates formidable switching costs—growers cannot rotate suppliers without jeopardizing residue documentation trails required for EU and Japanese export clearances.
For Market Incumbents: Consolidate fermentation capacity in India under PLI scheme incentives to capture domestic wheat and rice volume before generic competition intensifies. Deepen backward integration into cryoprotectant formulation science to resolve the shelf-life extension bottleneck constraining liquid microbial concentrate distribution. Lock in seed-treatment integration partnerships with hybrid genetics suppliers to preempt channel compression by direct-to-farm agritech platforms.
For New Entrants and Emerging Players: Anchor in Java's underpenetrated vegetable cooperatives, where archipelago logistics complexity has excluded established microbial inoculant suppliers. Target Vietnam's greenhouse vegetable exporters with RNA-interference biopesticide pilots ahead of EU residue compliance deadlines. Pursue white-label manufacturing arrangements with Indian fermentation platforms to bypass multi-year APVMA registration timelines for Australian market entry.
For Investors and Strategic Acquirers: Japan's amended Agricultural Chemicals Regulation Act reshapes the acquisition landscape by forcing reformulation investments that favor targets with existing metabolite toxicology dossiers. Long-term viability hinges on regulatory data assets rather than fermentation scale alone. Monitor METI guidance on supplemental ecotoxicology requirements as the inflection signal determining whether existing registrations qualify for streamlined renewal or require costly restudies.
| Strategic Initiative | Industry Significance |
|---|---|
| Seed-Treatment Integration | Biological coating applied at hybrid seed production facilities captures value upstream of farm-gate channels. |
| Fermentation Capacity Expansion | Domestic microbial inoculant production under India's PLI scheme accelerates supply security for wheat and rice systems. |
| Direct-to-Farm Platform Partnership | Agritech applications in Maharashtra and Karnataka fragment traditional cooperative distribution with traceable input sourcing. |
| Archipelago Logistics Alliance | Specialized cold chain partnerships unlock Java's underpenetrated vegetable cooperatives for microbial suppliers. |
| RNA-Interference Pipeline Advancement | Nucleic acid-based biopesticide development compresses timelines for novel modes of action against lepidopteran resistance. |
Research Methodology
A standing panel of fermentation platform directors, APVMA registration consultants, Indian agricultural cooperative procurement managers, and Vietnamese greenhouse export operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FSSAI residue limit notifications, APVMA biological product registration databases, China's MEE watershed discharge permit records, and Indian PLI scheme beneficiary disclosures. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against national agri-input trade flows ensured consistency.
External benchmark validation against customs data and cooperative offtake records confirmed analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, application method, and distribution channel, with additional granularity on regulatory compliance tier. CAGRs were derived from slope analysis of annual volume trajectories, incorporating soil microbiome adoption curves in Australian viticulture and protected horticulture expansion rates in Vietnam as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued FSSAI enforcement intensity, MEE runoff mandate persistence, and APVMA biological data requirement stability; material deviation in any would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market