
 Agricultural Biologicals Market | 2026-2036
Agricultural Biologicals Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Biologicals Market Intelligence
Margin from microbial-based biopesticide formulation is reconfiguring the value chain for crop protection inputs. Bayer AG leverages its extensive R&D infrastructure and global distribution to develop novel microbial strains with targeted efficacy. Meanwhile, Koppert Biological Systems specializes in integrated pest management solutions, combining macrobials with beneficial insects for horticultural applications. Corteva Agriscience also competes through its portfolio of seed treatments and biostimulants.
Agricultural biologicals are a class of products derived from natural materials like microorganisms, plant extracts, and other organic matter. They are applied to crops to enhance productivity by improving nutrient availability, managing pests, and stimulating physiological processes. Biopesticides and biostimulants represent the most dynamic product type segments, attracting substantial research investment. Demand from high-value applications, particularly in vegetable and fruit cultivation, is expanding faster than in traditional cereal crops.
Regulatory frameworks like the biopesticide registration process under the US Environmental Protection Agency (EPA) and substance evaluation under the EU's REACH regulation govern market access. These standards set the data requirements for proving product safety and efficacy, influencing development timelines. Successfully navigating the divergent registration pathways across key agricultural markets like the US, EU, and Brazil remains a critical strategic challenge for developers.
Market Dynamics
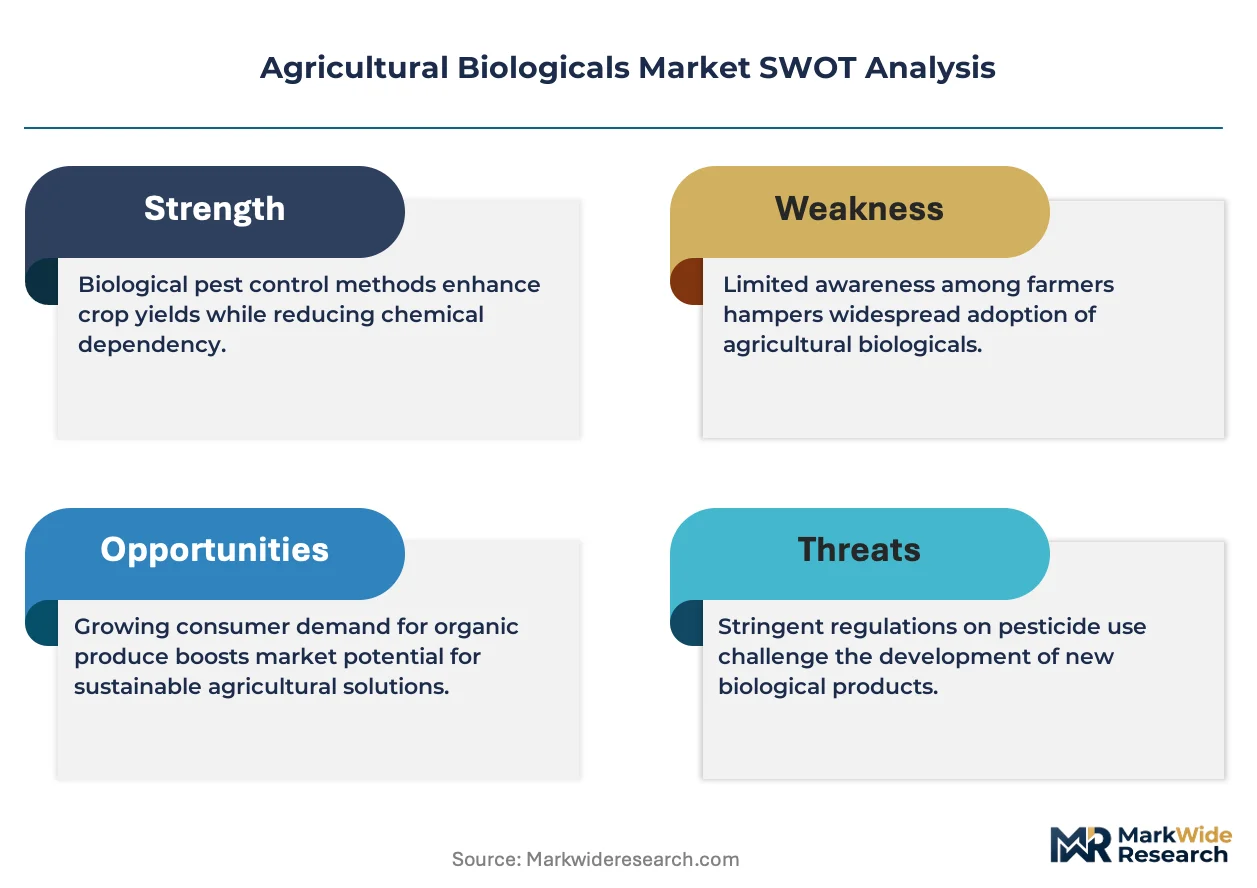
The central dynamic shaping the agricultural biologicals market is the global regulatory pivot towards sustainable agriculture, exemplified by the EU Green Deal, which directly incentivizes the substitution of synthetic chemicals, creating a powerful market-pull for natural inputs.
Growth Catalysts
- Policy Mandates:The European Union's Farm to Fork strategy creates a direct regulatory tailwind by setting targets for reducing chemical pesticide use, compelling a structural shift toward biopesticides and biostimulants across member states.
- Microbial Strain Discovery:Advances in genomic sequencing and high-throughput screening are accelerating the identification and development of novel microbial strains with enhanced efficacy for specific crops and pests, improving product performance.
- Intensive Agriculture Demand:Major agricultural economies like Brazil require continuous yield improvements in large-scale soybean and corn cultivation, driving demand for biostimulants that enhance nutrient uptake and stress tolerance.
Market Restraints
- High R&D Investment:The significant upfront cost and time required for field trials to prove efficacy and secure regulatory approval for new biological formulations create a high barrier to entry for smaller innovators.
- Regulatory Divergence:Navigating the disparate and lengthy registration requirements of the US EPA, the EU's ECHA, and Brazil's ANVISA complicates international market access and increases compliance costs for manufacturers.
- Product Viability:Many microbial-based products have a limited shelf life and require specific storage conditions, such as refrigeration, posing logistical challenges compared to chemically stable synthetic alternatives.
Strategic Opportunities
- Soil Health Focus:The growing adoption of regenerative agriculture principles opens a significant opportunity for biologicals, particularly microbial inoculants and biostimulants designed to restore soil biodiversity and organic matter.
- Precision Application:Integrating biological products with digital farming platforms allows for data-driven, site-specific application, optimizing efficacy and providing a clear value proposition for tech-forward farming operations.
- Expansion in Horticulture:High-value fruit and vegetable cultivation in developing agricultural regions, such as in Southeast Asia, represents an underpenetrated market for specialized biological pest and disease control solutions.
Industry Challenges
- Knowledge and Training Gaps:Effective use of biologicals requires specialized knowledge of application timing and environmental conditions, creating a need for extensive education and training for farmers and agronomists.
- Quality Control Standardization:Ensuring consistent product quality and performance across different batches of living microbial products presents a significant manufacturing and quality assurance challenge for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Biologicals Market |
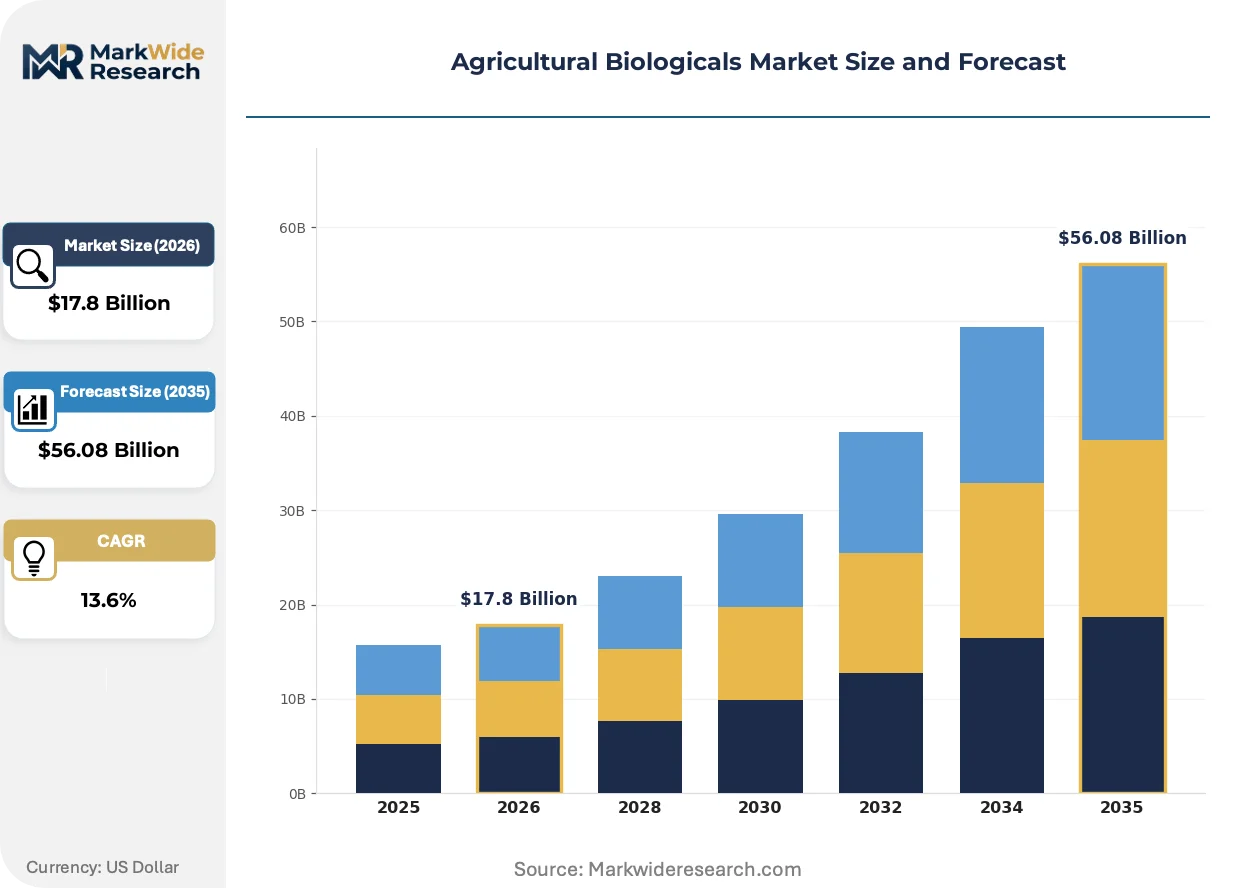
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $56.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biofertilizers, Biopesticides, Plant Growth Regulators, Biostimulants Application: Cereal Crops, Oilseed Crops, Vegetables, Fruits, Plantation Crops End Use Industry: Crop Farming, Horticulture, Aquaculture, Floriculture, Silviculture Distribution Channel: Direct Sales, Dealers & Distributors, E-Commerce, Retail Stores |
| Companies Covered | FMC Corporation, Novozymes A/S, BASF SE, Koppert Biological Systems B.V., Valent BioSciences LLC, Bayer AG, Syngenta Group, UPL Ltd., Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Biologicals Market Strategic Shifts & Innovations
Precision is becoming the core principle, as the market moves away from broad-spectrum applications toward targeted biological interventions. This evolution is driven by innovations in formulation science, regulatory pressures, and new demands from the downstream food value chain.
Advanced gene-editing tools like CRISPR are being applied to enhance the efficacy and environmental resilience of beneficial microbial strains. Large-scale agribusinesses focused on commodity crops like corn and wheat are early adopters, seeking more potent seed treatments and soil inoculants. This application of biotechnology is collapsing the development timeline between the discovery of a promising organism and the commercialization of a stable, high-performance product.
Regulatory frameworks are actively creating preferential pathways for biological products. The EU's Sustainable Use of Pesticides Regulation, for example, directly incentivizes the adoption of lower-risk biocontrol agents over conventional chemical pesticides. Producers of high-value horticultural crops in Spain and the Netherlands are among the most affected, accelerating their transition to integrated pest management systems that prioritize biological solutions.
A shift in procurement criteria among large food processors and retailers is altering the competitive landscape for input suppliers. These buyers now increasingly demand verifiable evidence of sustainable farming practices, including the use of biologicals, from their agricultural suppliers. This disrupts traditional distribution channels based on volume and price, favoring suppliers who can offer integrated agronomic support and data-backed sustainability metrics, a trend most visible in North American food systems.
Agricultural Biologicals Market Segmentation
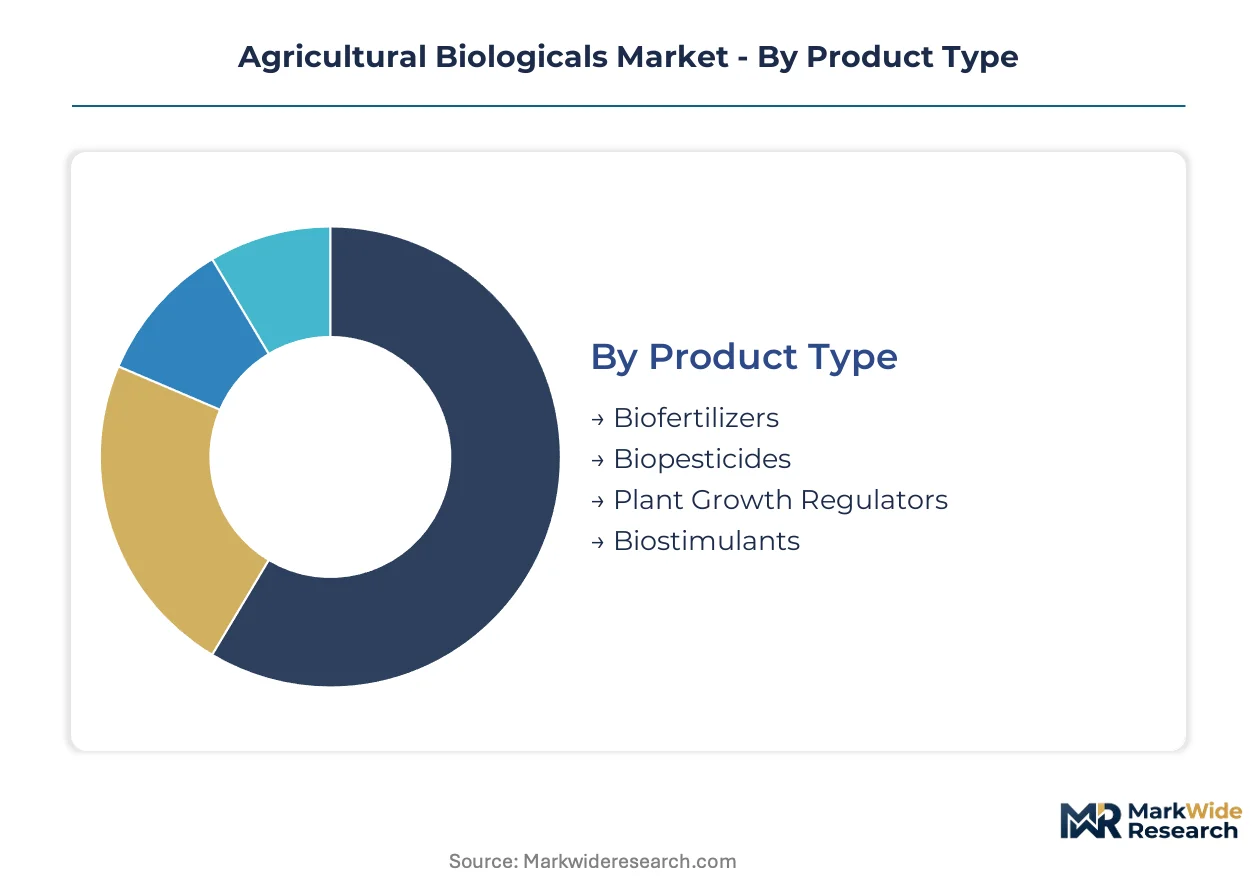
The agricultural biologicals market is highly segmented, reflecting the diverse applications and product types essential for enhancing crop productivity and sustainability. Understanding these distinctions is crucial for identifying specific growth pockets and tailoring product development to meet varied agricultural demands.
Product Type:
The product type segmentation reveals a market balancing mature, established solutions with rapidly evolving, high-growth innovations.
- Biofertilizers:These products contain living microorganisms that enhance nutrient availability to crops, improving soil fertility and plant growth. Demand for biofertilizers is particularly strong in large-scale cereal crop cultivation across Brazil and India, where nutrient management is critical for yield optimization.
- Biopesticides:Derived from natural materials, biopesticides offer targeted pest and disease control with reduced environmental impact, often comprising microbial agents or biochemicals. European Union regulations, such as the Farm to Fork strategy, directly incentivize their adoption as substitutes for synthetic chemical pesticides in high-value horticulture.
- Plant Growth Regulators:These biological compounds influence plant physiological processes, including flowering, fruiting, and maturation, often derived from plant extracts or microbial metabolites.
- Biostimulants:Biostimulants are substances or microorganisms applied to plants to enhance nutrient uptake, improve stress tolerance, and boost overall crop vigor, particularly in intensive agriculture.
Biofertilizers retain volume leadership; biostimulants hold the steepest expansion curve.
Application:
Application segments highlight diverse crop needs, ranging from large-scale commodity production to specialized high-value cultivation.
- Cereal Crops:This segment includes large-scale applications on staple crops like corn, wheat, and rice, where biologicals enhance nutrient use efficiency and stress resilience. Major agricultural economies, including the United States and Argentina, increasingly integrate these solutions for consistent yield improvements.
- Oilseed Crops:Biologicals applied to crops such as soybeans and canola improve seed quality and oil content while protecting against common pathogens. Brazil's expansive soybean cultivation represents a significant demand center for these inputs.
- Vegetables:High-value vegetable cultivation often employs biopesticides and biostimulants to meet stringent residue limits and consumer demand for sustainably grown produce. Spain and the Netherlands are prominent markets for these specialized applications.
- Fruits:Fruit orchards utilize biologicals for pest management and enhanced fruit quality, especially in regions with strict export standards.
- Plantation Crops:This category covers applications in crops like coffee, tea, and palm oil, focusing on soil health and disease suppression.
Cereal crops continue to dominate application volume, while fruit and vegetable cultivation drives specialized solution development.
End Use Industry:
End use industry differentiation reflects varied grower requirements, from broad-acre farming to niche horticultural practices.
- Crop Farming:This segment encompasses large-scale cultivation of commodity crops, where biologicals are integrated into existing farm management systems for efficiency and sustainability.
- Horticulture:Specialized applications in horticulture focus on high-value crops grown in controlled environments or intensive open-field systems, requiring precise biological interventions.
- Aquaculture:Biologicals in aquaculture improve water quality and enhance the health of aquatic organisms, reducing disease incidence.
- Floriculture:This industry uses biologicals to improve ornamental plant vigor, disease resistance, and aesthetic quality.
- Silviculture:Biological products in silviculture support forest health, tree growth, and pest management in commercial forestry operations.
Crop farming accounts for the largest end-use segment, with horticulture demonstrating significant value growth.
Distribution Channel:
Distribution channels illustrate the evolving pathways for product delivery, from traditional direct models to modern digital platforms.
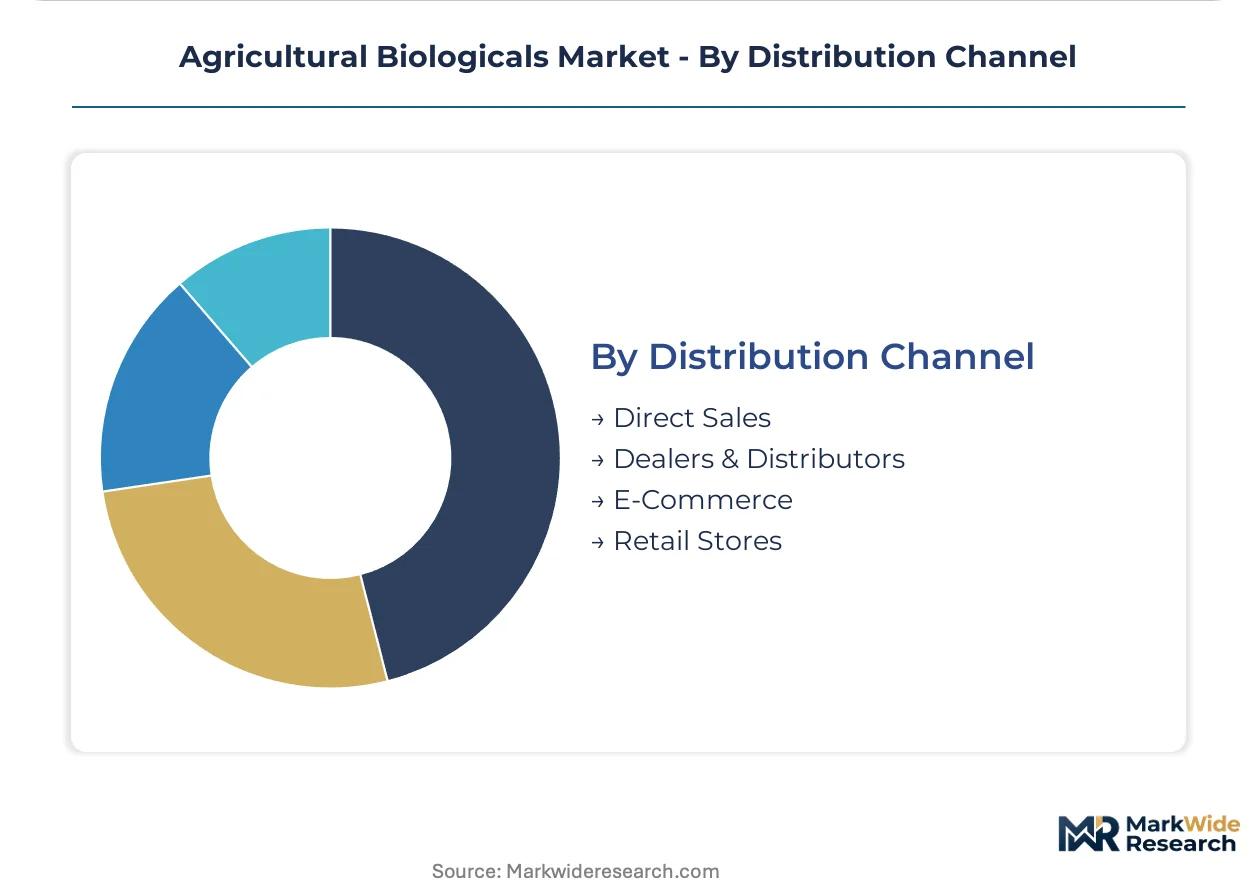
- Direct Sales:Manufacturers engage directly with large agricultural enterprises or cooperatives, offering tailored solutions and technical support. This channel ensures direct communication and customized product delivery for specific needs.
- Dealers & Distributors:These intermediaries provide regional market access and logistical support, supplying a broad range of biological products to diverse farming operations. This established network is critical for reaching a wide base of growers across various geographies.
- E-Commerce:Online platforms facilitate convenient access to biological products for smaller farms and specialized growers, particularly for niche or high-value items. This channel offers extensive reach and competitive pricing.
- Retail Stores:Agricultural retail outlets serve local farmers, offering immediate access to common biological inputs and expert advice.
Dealers and distributors remain critical for market access, though e-commerce is rapidly expanding its reach to new customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's vast agricultural land and intensive farming practices establish it as a primary hub for agricultural biologicals production and consumption. Major global players often establish regional manufacturing and R&D centers within its borders. This concentration supports the rapid deployment of biological solutions tailored for local crop challenges.
Brazil
Demand for yield enhancement in soybean and corn cultivation drives biologicals adoption. ANVISA's streamlined registration pathways facilitate market entry for new biopesticides and biostimulants. The state of Mato Grosso, a major agricultural producer, sees significant investment in biological input facilities.
United States
Policy incentives from the USDA promote sustainable farming practices, increasing biologicals use in cereal crops. The US Environmental Protection Agency (EPA) oversees a structured biopesticide registration process, ensuring product safety and efficacy. California's Central Valley, a high-value agricultural region, integrates biologicals for pest management in specialty crops.
Germany
European Union's Farm to Fork strategy directly incentivizes biopesticide adoption to reduce synthetic chemical reliance. Germany's national agricultural policies support organic farming and precision agriculture technologies. The Rhine-Main region, with its strong chemical and biotech industry, fosters innovation in microbial strain development.
Spain
Horticultural applications, particularly in fruit and vegetable cultivation, generate high demand for biological solutions. Strict EU residue limits compel Spanish growers to adopt biopesticides and biostimulants. Andalusia, a key agricultural region, leads in the adoption of integrated pest management systems for greenhouse crops.
India
Government initiatives, including subsidies for organic farming, boost the demand for biofertilizers and biopesticides. The FSSAI regulates agricultural inputs, ensuring quality standards for biological products. Maharashtra, a significant agricultural state, witnesses a surge in biofertilizer production and farmer training programs.
Agricultural Biologicals Market Key Industry Players
Diversified agribusiness conglomerates and specialized biologicals producers split the market for agricultural biologicals. Large established players leverage extensive R&D infrastructure and global distribution networks. Niche innovators focus on specific microbial strains or application methods. Strategic partnerships and technology licensing agreements represent common competitive moves.
Global chemical and seed giants like Bayer AG and Corteva Agriscience represent the diversified agribusiness archetype, integrating biologicals into their broader crop protection portfolios. Koppert Biological Systems B.V., a Netherlands-based entity, exemplifies a specialized biologicals producer, focusing on integrated pest management solutions. These companies occupy positions across the value chain, from microbial discovery to product distribution.
| Leading Market Players |
|---|
| FMC Corporation |
| Novozymes A/S |
| BASF SE |
| Koppert Biological Systems B.V. |
| Valent BioSciences LLC |
| Bayer AG |
| Syngenta Group |
| UPL Ltd. |
| Corteva Agriscience |
| Others |
Cost & Logistics Intelligence
Regulatory divergence creates significant pricing tier spreads and shapes the supply chain for agricultural biologicals. This complexity arises from varied market access requirements across key agricultural regions like the US, EU, and Brazil, impacting product availability and cost structures.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for biopesticides, favoring products with lower environmental impact. Value-based pricing dominates, where efficacy and formulation stability drive premium tiers. Price differentiation stems from proven field performance and the specific crop application, such as high-value horticulture versus commodity cereals. Pricing pressure stems from large-scale cereal crop farmers seeking cost-effective yield enhancements. High-value fruit and vegetable growers exhibit less price sensitivity due to stringent residue limits and consumer demand for sustainable produce.
Supply Chain Analysis
Extended payment terms are common across agricultural input supply chains, influencing distributor relationships and working capital. Supply of key microbial strains concentrates in regions with advanced biotech R&D, including the United States, Germany, and the Netherlands. The supply chain depends on specialized fermentation inputs and efficient cold chain logistics for viable microbial products. Product viability due to limited shelf life and specific storage conditions poses a significant logistical chokepoint. Distribution runs through established dealer and distributor networks, which remain critical for market access and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global food security concerns are driving a cyclical recovery in agricultural input investments, positioning biologicals for sustained expansion.
For Market Incumbents: Harden R&D pipelines against the threat of rapidly evolving synthetic chemical alternatives. Focus on integrating novel biological formulations into existing crop protection portfolios, leveraging established distribution channels. Invest in certification processes to navigate regulatory divergence across major agricultural economies. Control over distribution networks remains a critical lever to maintain market share against new entrants.
For New Entrants and Emerging Players: High-value horticultural applications in developing agricultural regions, such as Southeast Asia, represent a penetrable entry point. Specialize in biostimulants designed for specific crop stress tolerance, offering clear performance metrics. A strong go-to-market angle involves partnerships with digital farming platforms for precision application and data-driven value propositions.
For Investors and Strategic Acquirers: Niche microbial discovery firms with proprietary strains offer attractive acquisition targets for long-term growth. The market’s viability extends over the next decade, driven by policy mandates and consumer demand for sustainable agriculture. Accelerated regulatory approvals for novel biologicals in major markets serve as a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D investment in gene editing | Enhances microbial strain efficacy for large-scale cereal crops. |
| Partnerships with digital farming platforms | Optimizes biological application for tech-forward farming operations. |
| Expansion into high-value horticulture | Captures demand from fruit and vegetable cultivation in Southeast Asia. |
| Investment in cold chain logistics | Addresses product viability challenges for microbial-based biopesticides. |
| Strategic acquisitions of specialized biotechs | Integrates novel biostimulant technologies into existing portfolios. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, farm managers, regulatory affairs specialists, and distribution channel partners, and refined through an iterative process. Secondary validation involved comprehensive review of USDA reports, EU Commission documents, ANVISA publications, and academic journals. This approach ensured bottom-up and top-down triangulation of market insights.
The analytical framework centers on demand-supply-balance to project market trajectories over the projection horizon. Segmentation dimensions modeled include product type, application, end-use industry, distribution channel, and key regulatory regions. Compound annual growth rates were derived from historical data analysis and future trend projections. Industry-specific forecast inputs include chemical pesticide reduction targets and biostimulant efficacy rates in diverse cropping systems.
Practitioners should monitor shifts in agricultural policy and new microbial strain discoveries for early signals impacting market dynamics. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
China Biopesticides Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
Biochar Machine Market