
 Smart Feature Phone Market | 2026-2036
Smart Feature Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Feature Phone Market Insights
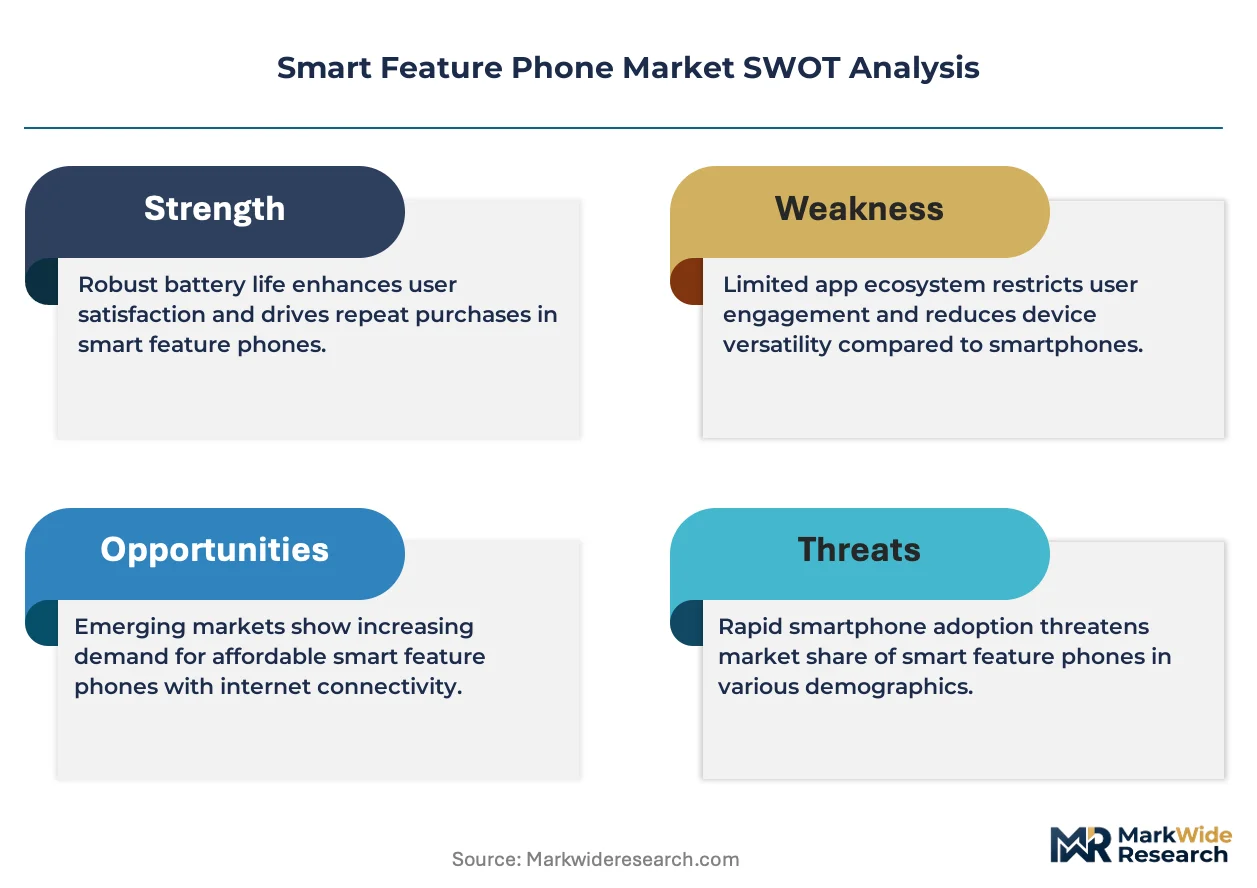
Carrier-led distribution in emerging economies is fragmenting as open-market retail and direct-to-consumer platforms capture growing volume. HMD Global leverages its licensed Nokia brand to sustain carrier relationships across African and South Asian markets. Unihertz specializes in compact physical-keyboard form factors that occupy a defensible niche among productivity-focused users. Hisense competes on manufacturing scale, extending its consumer electronics supply chain into budget handset production.
A smart feature phone combines tactile keypad or limited touchscreen input with 4G connectivity, proprietary or lightweight operating systems, and essential apps such as voice calls, messaging, and mobile payments, typically running on processors with under 1 GB RAM and optimized for week-long battery endurance. These devices serve price-sensitive users requiring reliable communication without smartphone cost or complexity. Touchscreen Devices command attention as the fastest-growing product type, while Classic Phones retain volume leadership in rural African and South Asian markets where durability and simplicity dominate purchasing decisions. KaiOS-enabled units concentrate margin pools where app ecosystem licensing creates recurring revenue streams for platform holders.
FCC certification requirements in the United States govern RF emissions and network compatibility, while India's BIS mandatory testing standards enforce safety and interoperability for domestically sold devices. The EU's RoHS and REACH frameworks restrict hazardous substances in batteries and circuit assemblies, directly affecting component sourcing for manufacturers targeting European distribution. Stakeholders must monitor operating system licensing cost trajectories and regional spectrum reallocation timelines that could obsolete 2G-dependent hardware before end-of-design life.
Market Dynamics
KaiOS platform licensing fees are compressing hardware margins while simultaneously creating recurring revenue dependencies that reshape manufacturer business models across emerging market supply chains.
Growth Catalysts
- India's PLI scheme for telecom equipment:Production-linked incentives reduce landed costs for domestic assembly operations, attracting component suppliers to establish local manufacturing footprints.
- Mobile money interoperability standards:GSMA-led technical frameworks in sub-Saharan African markets accelerate device refresh cycles as payment functionality becomes table stakes.
- 2G spectrum reallocation mandates:National regulators in Bangladesh, Pakistan, and Nigeria force network migrations that obsolete legacy handsets and create replacement demand for 4G-capable alternatives.
Market Restraints
- Application processor supply concentration:Mediatek and Unisoc dominate sub-$10 chipset supply, creating single-source vulnerability for tier-two manufacturers.
- REACH substance restrictions:EU battery and circuit board material compliance adds certification overhead that excludes budget manufacturers from European distribution.
- Smartphone price compression:Entry-level Android devices at $40-60 price points capture functionality overlap that constrains smart feature phone addressable market expansion.
Strategic Opportunities
- Rural Indian connectivity gaps:BharatNet infrastructure expansion targets 250,000 village-level access points, creating first-time subscriber bases for voice-first devices.
- Offline digital payment integration:NFC-enabled merchant acceptance networks in Kenya and Ghana enable tap-to-pay functionality without smartphone dependency.
- Direct-to-consumer platform emergence:JioMart and Konga bypass carrier-controlled distribution, allowing manufacturers to capture margin previously allocated to retail intermediaries.
Industry Challenges
- KaiOS developer certification bottlenecks:Application store approval timelines stretch 8-14 weeks, delaying feature rollouts for hardware partners locked into platform exclusivity.
- Multi-band RF engineering scarcity:4G/LTE modem integration for fragmented regional spectrum allocations requires specialized talent concentrated in Shenzhen and Taipei design houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Feature Phone Market |
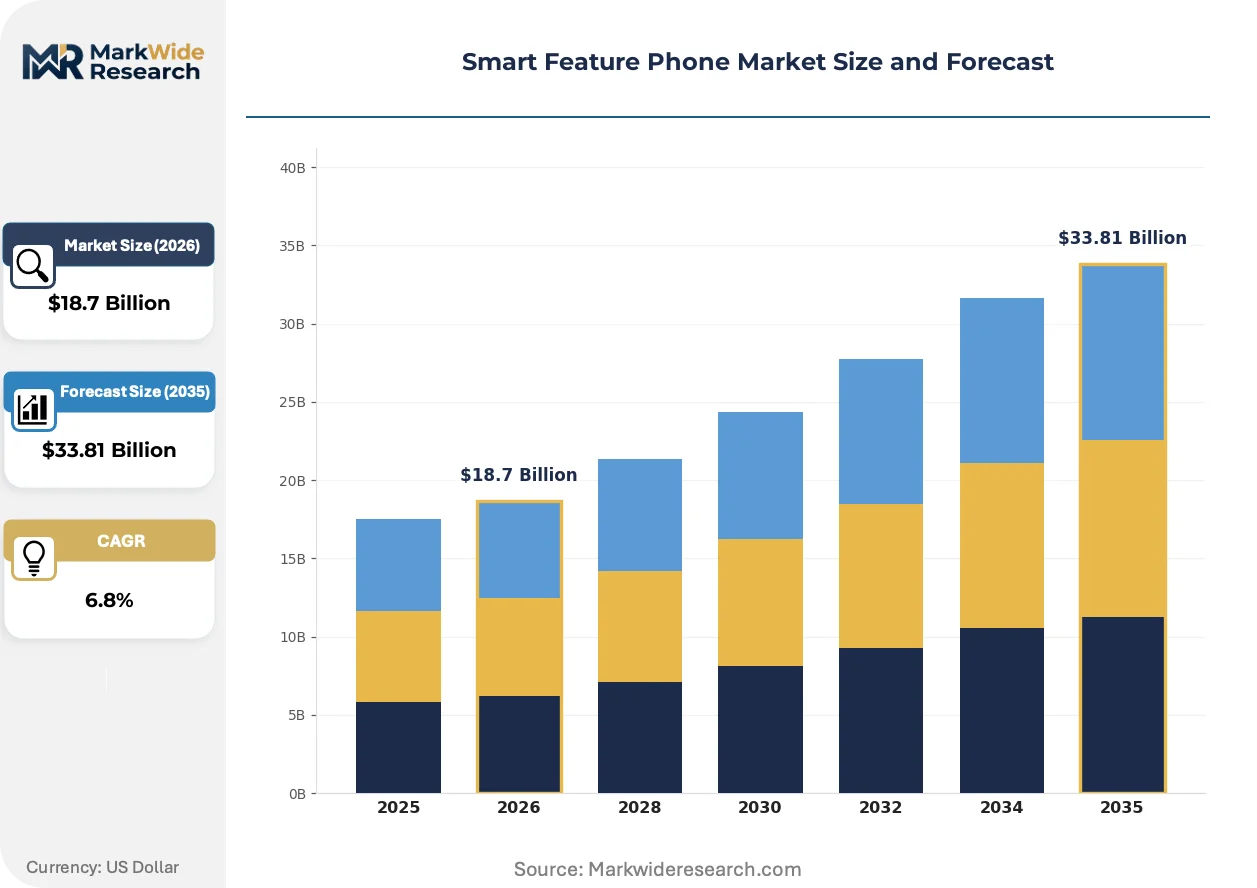
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Phones, Touchscreen Devices, Dual SIM Phones, Multimedia Phones Operating System: KaiOS, Android Go, proprietary OS, Feature OS End User: Senior Citizens, Emerging Market Consumers, Budget-Conscious Users, Casual Mobile Users Distribution Channel: Online Retail, Brick-and-Mortar Stores, Mobile Carriers, Wholesale Distributors |
| Companies Covered | Cat, Unihertz, HMD Global, BigMe, Doro, Nokia, Hisense, Boox, Punkt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Feature Phone Market Trends and Innovations
Cloud-native application architectures are migrating down the hardware stack, enabling lightweight operating systems to deliver smartphone-equivalent services on resource-constrained devices without local processing overhead.
Progressive web application runtimes are virtualizing core service delivery for KaiOS and similar lightweight platforms. Mobile money providers in East African markets deploy these architectures to bypass native app store dependencies. Platform holders capture recurring licensing revenue while hardware manufacturers shed local storage and RAM requirements.
India's BIS mandatory certification for cellular devices tightens electromagnetic compatibility testing protocols effective 2024. Domestic manufacturers face 12-16 week approval timelines that compress product launch windows. Export-oriented assembly operations in Noida and Sri City redirect capacity toward Middle Eastern and African markets with mutual recognition agreements.
Carrier subsidy withdrawal is accelerating open-market retail penetration. MTN Nigeria and Airtel Kenya reduce handset financing programs, shifting volume toward independent electronics markets in Lagos Computer Village and Nairobi Luthuli Avenue. Cash-preferred purchasing patterns in these channels favor unlocked dual-SIM configurations over operator-locked inventory.
Smart Feature Phone Market Segmentation
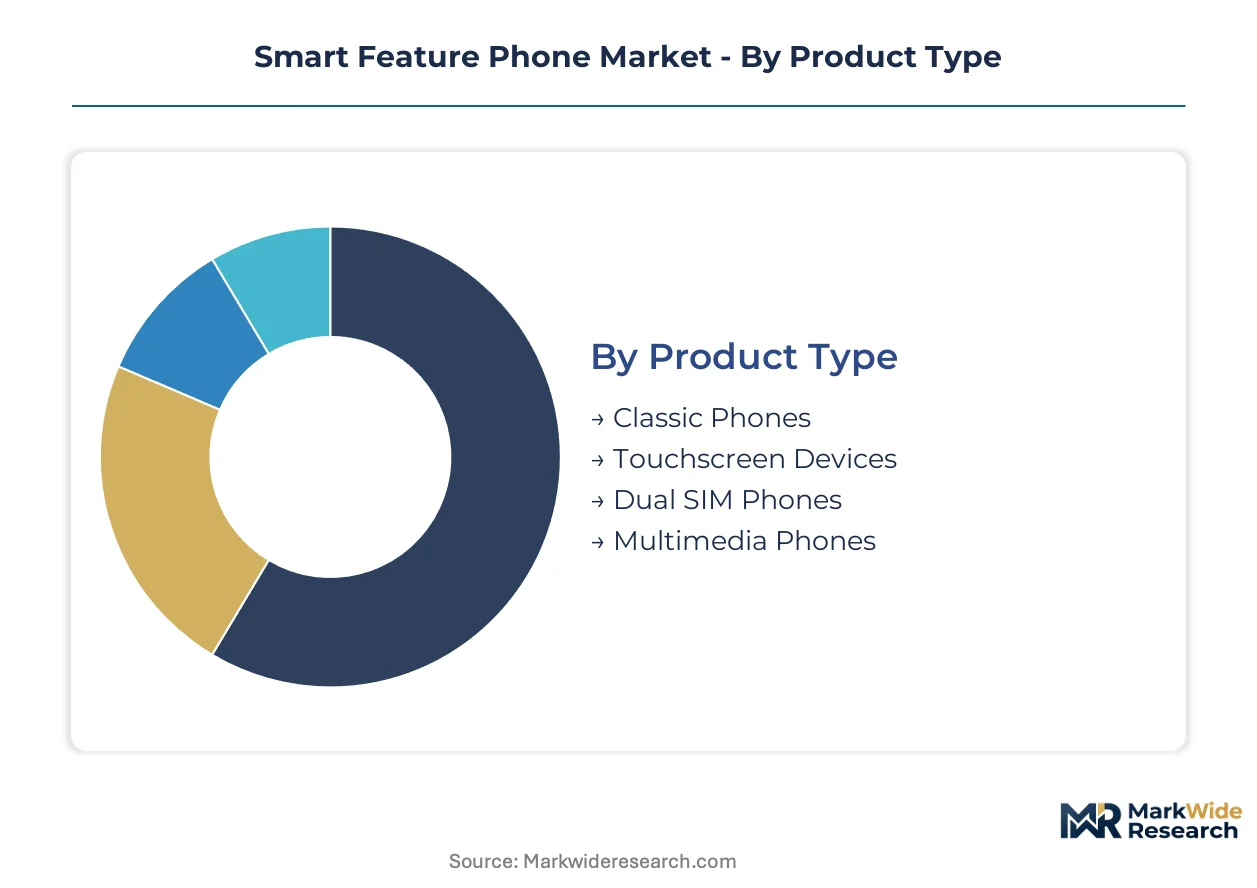
Smart feature phone segmentation reveals how hardware specifications, software ecosystems, and distribution economics partition addressable demand across radically different user needs and purchasing contexts. Each dimension carries distinct margin structures and competitive dynamics that shape manufacturer portfolio strategy.
Product Type:
The use-case spectrum spans voice-first minimalism through media-capable hybrid devices, with input modality and durability requirements driving hardware architecture decisions.
- Classic Phones:Tactile keypad interfaces with monochrome or basic color displays prioritize week-long battery endurance and mechanical resilience. Demand concentrates in rural India and sub-Saharan African markets where dust resistance and drop tolerance outweigh connectivity sophistication.
- Touchscreen Devices:Limited capacitive displays with gesture navigation bridge smartphone interaction patterns while retaining sub-1GB RAM efficiency. Adoption climbs fastest in Bangladesh and Nigerian urban peripheries where younger users demand app-like experiences without smartphone cost burdens.
- Dual SIM Phones:Dual standby architecture enables network arbitrage across competing carriers in price-sensitive markets.
- Multimedia Phones:Integrated FM radio, expandable storage, and basic cameras serve entertainment needs in offline-dominant usage environments.
Established volume favors Classic Phones; emerging adoption favors Touchscreen Devices.
Operating System:
Platform economics range from royalty-bearing licensed stacks to zero-cost proprietary firmware, directly determining app ecosystem depth and manufacturer margin retention.
- KaiOS:Firefox-derived lightweight runtime enabling WhatsApp, YouTube, and Google Assistant on 256MB RAM configurations. Licensing fees compress hardware margins while creating recurring revenue dependencies for platform holders; device certification timelines stretch 8-14 weeks.
- Android Go:Google's optimized Android variant strips background processes and preinstalls lightweight app alternatives. Deployment concentrates where carrier partnerships demand Play Store compatibility and security update commitments.
- Proprietary OS:Manufacturer-developed firmware stacks eliminate licensing overhead but limit third-party application availability.
- Feature OS:Legacy embedded systems maintain minimal connectivity stacks for 2G-to-4G transition markets.
Margin retention favors Proprietary OS; ecosystem breadth favors KaiOS.
End User:
User archetypes segment by digital literacy, income constraints, and primary communication modality rather than demographic abstraction alone.
- Senior Citizens:Large physical keypads, amplified audio output, and simplified menu hierarchies address dexterity and vision limitations. Demand localizes in Japan and Western European markets where aging populations sustain premium pricing for accessibility-optimized hardware.
- Emerging Market Consumers:First-time subscribers requiring voice reliability, mobile money compatibility, and basic internet access without smartphone learning curves. Concentration in rural Indian states and East African agricultural corridors drives dual-SIM and extended battery requirements.
- Budget-Conscious Users:Secondary device purchasers seeking cost minimization for backup or child communication needs.
- Casual Mobile Users:Intermittent connectivity seekers prioritizing digital detox and distraction reduction.
Volume scale favors Emerging Market Consumers; price realization favors Senior Citizens.
Distribution Channel:
Channel structure determines working capital intensity, brand control, and margin capture across fragmented retail ecosystems.
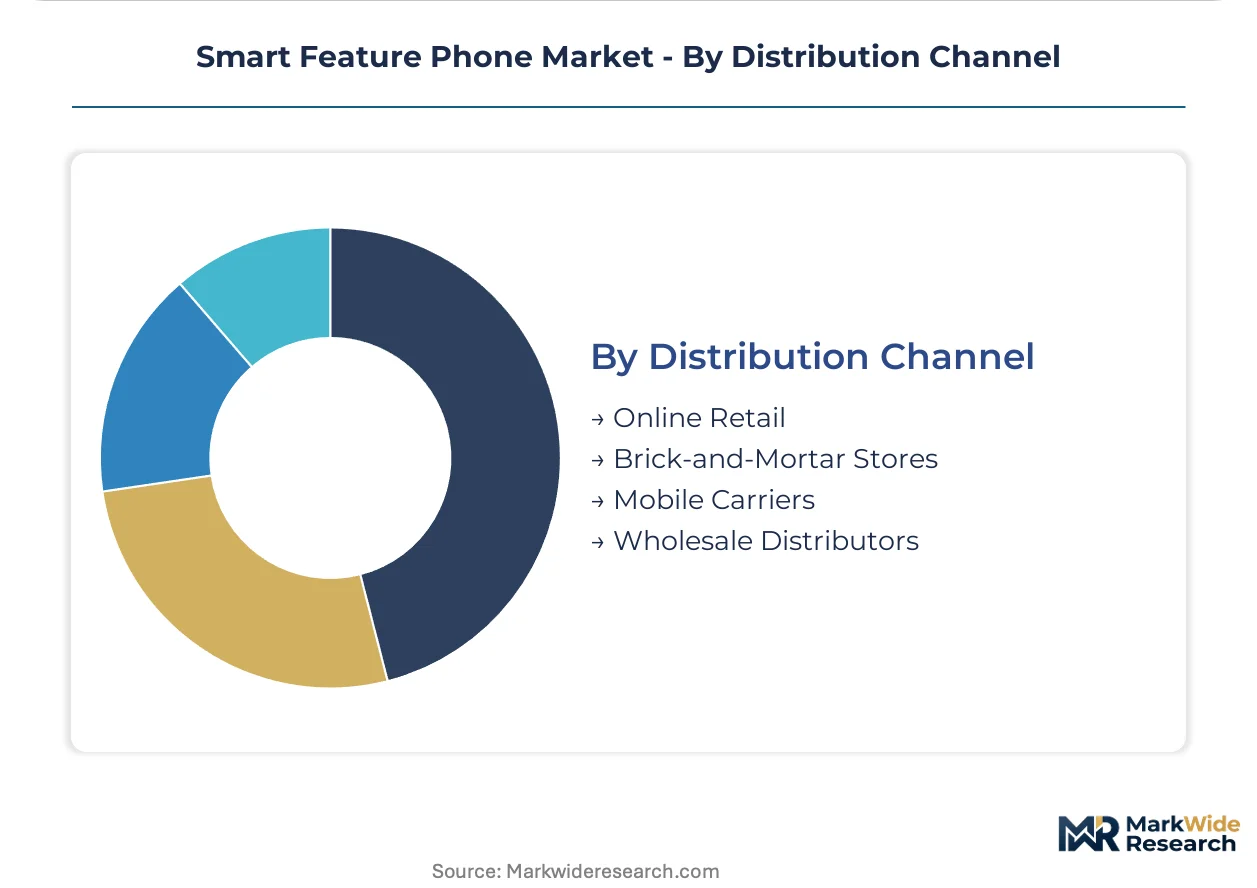
- Online Retail:Direct-to-consumer platforms and marketplace listings bypass carrier commission structures. JioMart and Konga expansion enables manufacturers to capture margin previously allocated to retail intermediaries in Indian and Nigerian markets.
- Brick-and-Mortar Stores:Independent electronics markets in Lagos Computer Village and Nairobi Luthuli Avenue sustain cash-preferred purchasing and unlocked dual-SIM configurations.
- Mobile Carriers:Subsidized handset financing programs concentrate in MTN Nigeria and Airtel Kenya operations, though withdrawal trends accelerate open-market migration.
- Wholesale Distributors:Regional aggregators manage inventory risk and logistics for tier-two manufacturers lacking direct retail presence.
Margin capture favors Online Retail; volume throughput favors Wholesale Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for telecom equipment is redirecting component supply chains toward domestic assembly hubs, creating ripple effects across adjacent manufacturing economies. Rural connectivity programs in sub-Saharan Africa and spectrum reallocation mandates in South Asia are accelerating hardware refresh cycles in parallel.
India
BharatNet infrastructure expansion targets 250,000 village-level access points, generating first-time subscriber demand for voice-first devices. BIS mandatory certification for cellular devices tightens electromagnetic compatibility testing protocols effective 2024, compressing product launch windows to 12-16 weeks. Export-oriented assembly operations in Noida and Sri City redirect capacity toward Middle Eastern and African markets with mutual recognition agreements.
Nigeria
2G spectrum reallocation mandates from the Nigerian Communications Commission force network migrations that obsolete legacy handsets and create replacement demand for 4G-capable alternatives. MTN Nigeria reduces handset financing programs, shifting volume toward independent electronics markets. Lagos Computer Village anchors cash-preferred purchasing patterns that favor unlocked dual-SIM configurations over operator-locked inventory.
Kenya
GSMA-led mobile money interoperability standards accelerate device refresh cycles as payment functionality becomes table stakes for handset acceptance. Airtel Kenya follows subsidy withdrawal trends, accelerating open-market retail penetration. Nairobi Luthuli Avenue sustains independent electronics market activity where NFC-enabled merchant acceptance networks enable tap-to-pay functionality without smartphone dependency.
Bangladesh
National regulators enforce 2G-to-4G network migration timelines that obsolete legacy hardware and generate replacement demand. Touchscreen device adoption climbs fastest in urban peripheries where younger users demand app-like experiences without smartphone cost burdens. Dhaka-based distribution networks manage working capital intensity for tier-two manufacturers lacking direct retail presence.
Ghana
Offline digital payment integration through NFC-enabled merchant networks creates hardware differentiation opportunities independent of smartphone platforms. Mobile money providers deploy progressive web application architectures to bypass native app store dependencies. Accra serves as a regional logistics hub for West African distribution channels capturing margin previously allocated to retail intermediaries.
Smart Feature Phone Market Competitive Landscape
On the supply side, the industry is bifurcated between licensed brand operators and original design manufacturers competing on certification speed and manufacturing scale. Tier-one players leverage carrier relationships and brand recognition to sustain premium positioning, while tier-two manufacturers compete on price realization through direct-to-consumer channels. Two strategic archetypes dominate: brand licensees exploiting nostalgia equity and compact-form-factor specialists occupying defensible productivity niches. Competitive moves concentrate on geographic expansion into subsidy-withdrawing markets and platform exclusivity negotiations that lock hardware partners into extended certification timelines.
Within the brand-licensee archetype, HMD Global represents the dominant positioning through its Nokia licensed portfolio, while Unihertz exemplifies the compact physical-keyboard specialization that targets productivity-focused users. Hisense anchors the manufacturing-scale tier, extending consumer electronics supply chain efficiencies into budget handset production. These three entities collectively illustrate how hardware certification pathways, distribution channel control, and operating system licensing dependencies stratify competitive positioning across emerging market supply chains.
| Leading Market Players |
|---|
| Cat |
| Unihertz |
| HMD Global |
| BigMe |
| Doro |
| Nokia |
| Hisense |
| Boox |
| Punkt |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's component manufacturing corridors anchor global smart feature phone assembly capacity, with Noida and Sri City emerging as alternative hubs where India's PLI scheme for telecom equipment compresses landed costs for domestic operations. This geographic reconfiguration tightens hardware margins while redistributing pricing power toward platform holders capturing recurring KaiOS licensing revenue.
Pricing Analysis
Certification level creates the primary spread across hardware tiers, with BIS mandatory testing for Indian distribution and FCC certification for US markets adding compliance overhead that stratifies pricing across regulatory clusters. Three-tier pricing structure separates KaiOS-enabled units with app ecosystem access from proprietary OS devices and legacy Feature OS handsets. Cost compression in sub-$20 segments intensifies because Mediatek and Unisoc processor supply concentration limits alternative sourcing. Emerging market consumers exhibit highest price sensitivity, while senior citizen segments in Japan and Western Europe absorb premium accessibility-optimized hardware.
Supply Chain Analysis
Extended payment terms from Shenzhen design houses to tier-two manufacturers in Dhaka and Lagos compress working capital cycles across assembly operations. Component sourcing draws from China's display and battery suppliers, Taiwan's RF engineering specialists, and Vietnam's emerging packaging capacity. Single-source vulnerability concentrates in sub-$10 application processors where Unisoc and Mediatek dominate. Distribution runs through open-market retail channels in Lagos Computer Village and Nairobi Luthuli Avenue as carrier subsidy withdrawal accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier subsidy withdrawal fragments distribution control across emerging markets, creating white-space opportunities for manufacturers bypassing traditional retail intermediaries through direct-to-consumer platforms.
For Market Incumbents: Pre-empt platform exclusivity negotiations by accelerating KaiOS developer certification timelines before 8-14 week bottlenecks lock hardware partners into competitor ecosystems. Secure backward integration into 4G/LTE modem design capabilities concentrated in Shenzhen and Taipei to reduce single-source RF engineering dependency. Defend margin position by capturing direct-to-consumer channel share through JioMart and Konga expansion before tier-two manufacturers establish footholds. For New Entrants and Emerging Players: Build out offline digital payment integration capabilities targeting NFC-enabled merchant networks in Kenya and Ghana where smartphone-independent tap-to-pay functionality creates hardware differentiation. Rural Indian connectivity gaps present the most penetrable geography, with BharatNet infrastructure expansion generating first-time subscriber demand for voice-first devices. Pursue carrier bypass strategies through independent electronics market relationships in cash-preferred purchasing environments. For Investors and Strategic Acquirers: Long-term, this sits as a connectivity infrastructure play because 2G spectrum reallocation mandates across Bangladesh, Pakistan, and Nigeria force hardware refresh cycles independent of consumer discretionary spending. Acquisition targets should concentrate on compact-form-factor specialists with defensible productivity niches and licensed brand operators exploiting nostalgia equity. Monitor GSMA-led mobile money interoperability standard adoption as the inflection signal for device refresh acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| KaiOS Platform Exclusivity Negotiation | Locks hardware partners into extended certification timelines that delay competitor feature rollouts. |
| Direct-to-Consumer Channel Expansion | JioMart and Konga bypass carrier commission structures to capture margin from retail intermediaries. |
| Backward Integration into RF Engineering | In-house 4G/LTE modem design reduces dependency on Shenzhen and Taipei specialist talent pools. |
| NFC Payment Hardware Integration | Tap-to-pay functionality differentiates devices in Kenyan and Ghanaian merchant acceptance networks. |
| BIS Certification Fast-Track Investment | Accelerated approval timelines compress 12-16 week product launch windows for Indian market entry. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hardware engineering directors, carrier procurement leads, mobile money platform operators, and independent electronics market distributors; and secondary validation through BIS certification databases, TRAI spectrum allocation filings, GSMA mobile money deployment reports, and customs trade records for component imports. Bottom-up assembly capacity estimates from Noida, Sri City, and Shenzhen manufacturing hubs triangulated against top-down addressable population calculations across BharatNet target villages and sub-Saharan African agricultural corridors.
Forecast inputs considered operating system licensing cost trajectories, regional spectrum reallocation timelines, and mobile money interoperability standard adoption curves across the projection horizon. Segmentation dimensions modeled include input modality, platform ecosystem, user archetype digital literacy, and channel working capital intensity. CAGRs derived from installed base replacement cycles, first-time subscriber penetration rates, and platform holder recurring revenue capture. Industry-specific inputs incorporated KaiOS certification pipeline delays and PLI scheme capacity redirection effects.
Sensitivities concentrate around 2G network sunset acceleration, application processor supply disruption, and platform licensing fee escalation. Forecasts reflect assumptions regarding infrastructure deployment timelines and regulatory enforcement consistency. Macroeconomic volatility in emerging market currencies, unilateral spectrum policy shifts, or alternative low-cost smartphone price compression would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Video Door Phones Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Italy Telecom Market
Telecommunications
Cellular Modem Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Germany ICT Market
Telecommunications
Underwater Modems Market
Telecommunications
Telecom Services Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Australia Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
MVNO Market
Telecommunications
LTE Base Station System Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Global Roaming Tariff Market