
 Embedded SIM (Esim) Market | 2026-2036
Embedded SIM (Esim) Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded SIM (Esim) Market Intelligence
Automotive OEM demand is recalibrating the Embedded SIM value chain as connected vehicle architectures require permanent, reprogrammable cellular identity. Thales Group leverages its aerospace security heritage to anchor trust infrastructure for automotive eSIM deployments. Giesecke+Devrient competes through vertically integrated smart card manufacturing that extends into embedded secure elements. NXP Semiconductors specializes in automotive-grade secure microcontrollers that integrate eSIM functionality with vehicle network gateways.
An embedded SIM is a solderable or integrated chip that stores multiple operator profiles and enables remote provisioning over-the-air without physical card replacement, typically conforming to MFF2 or smaller wafer-level packages. Its primary purpose is to provide persistent, scalable cellular connectivity for devices where manual SIM access is impractical or impossible. The M2M Communication application segment dominates current volume as industrial telemetry and fleet management systems standardize on embedded connectivity, while IoT Solutions represents the fastest structural expansion as low-power wide-area networks proliferate across asset tracking and smart metering. Remote SIM Provisioning technology leads in deployment maturity, though Security Protocols commands the deepest margin pools as hardware-based tamper resistance becomes mandatory for automotive and healthcare certification.
The GSMA's SGP standards framework governs interoperability architecture, while ETSI defines the underlying M2M form factor and electrical specifications for European markets. The FCC's device authorization requirements in the United States shape testing protocols for eSIM-enabled products entering North American networks. Stakeholders must monitor how fragmented national cybersecurity certification schemes reshape supplier qualification timelines and regional sourcing decisions.
Market Dynamics
GSMA's remote SIM provisioning standards are compressing interoperability timelines while automotive OEMs demand permanent cellular identity for connected vehicle architectures. This dual pressure is restructuring supplier qualification pathways and certification requirements.
Growth Catalysts
- Connected vehicle mandates:Regulatory requirements for emergency call systems and telematics in Germany, France, and Italy are mandating embedded cellular connectivity in new vehicle platforms.
- GSMA SGP.32:The updated remote provisioning standard for consumer and IoT devices is streamlining multi-carrier profile management and reducing integration friction.
- Industrial telemetry standardization:Fleet management and asset tracking systems are converging on eSIM form factors to eliminate physical SIM replacement costs in distributed deployments.
Market Restraints
- Secure element supply concentration:Wafer-level packaging capacity for MFF2 form factors concentrates among a limited set of semiconductor foundries in East Asia.
- FCC device authorization complexity:Multi-carrier eSIM configurations require iterative testing protocols that extend product launch timelines for North American market entry.
- Subscription management platform fragmentation:Incompatible proprietary implementations across carrier ecosystems force redundant certification investments.
Strategic Opportunities
- Healthcare device certification:FDA's evolving cybersecurity guidance for connected medical devices is creating demand for hardware-anchored identity that eSIM secure elements provide.
- Smart metering infrastructure:Utilities in Spain and the Netherlands are specifying eSIM for next-generation AMI deployments to enable carrier flexibility over 15-year asset lifecycles.
- eSIM-iSIM convergence:Integration of eSIM functionality directly into cellular baseband processors is automating cost reduction pathways for high-volume IoT endpoints.
Industry Challenges
- Embedded systems security engineering:Automotive OEMs face acute shortages of engineers qualified to implement GSMA-compliant trusted execution environments.
- Multi-stakeholder certification orchestration:eSIM deployments require sequential approvals from semiconductor vendors, subscription managers, and carrier operations teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded SIM (Esim) Market |
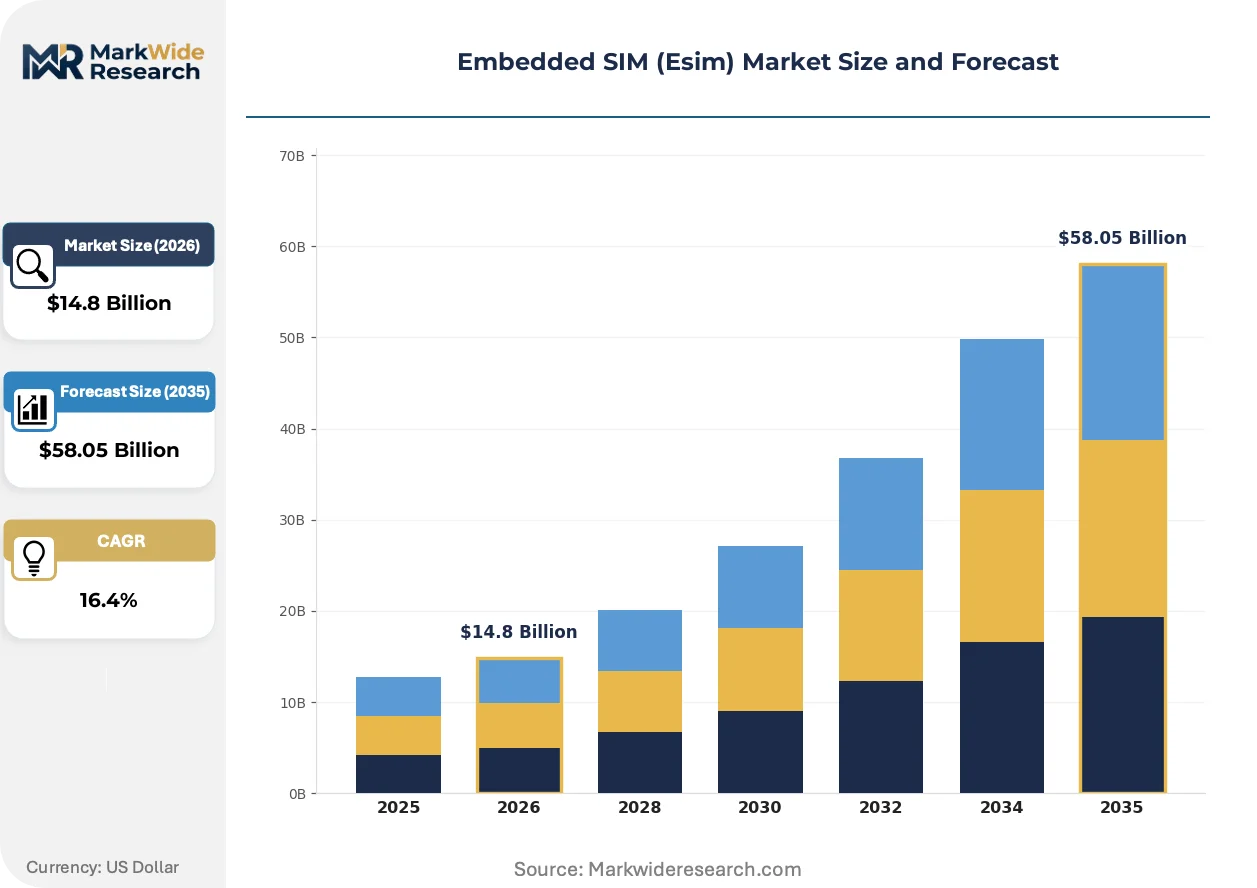
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
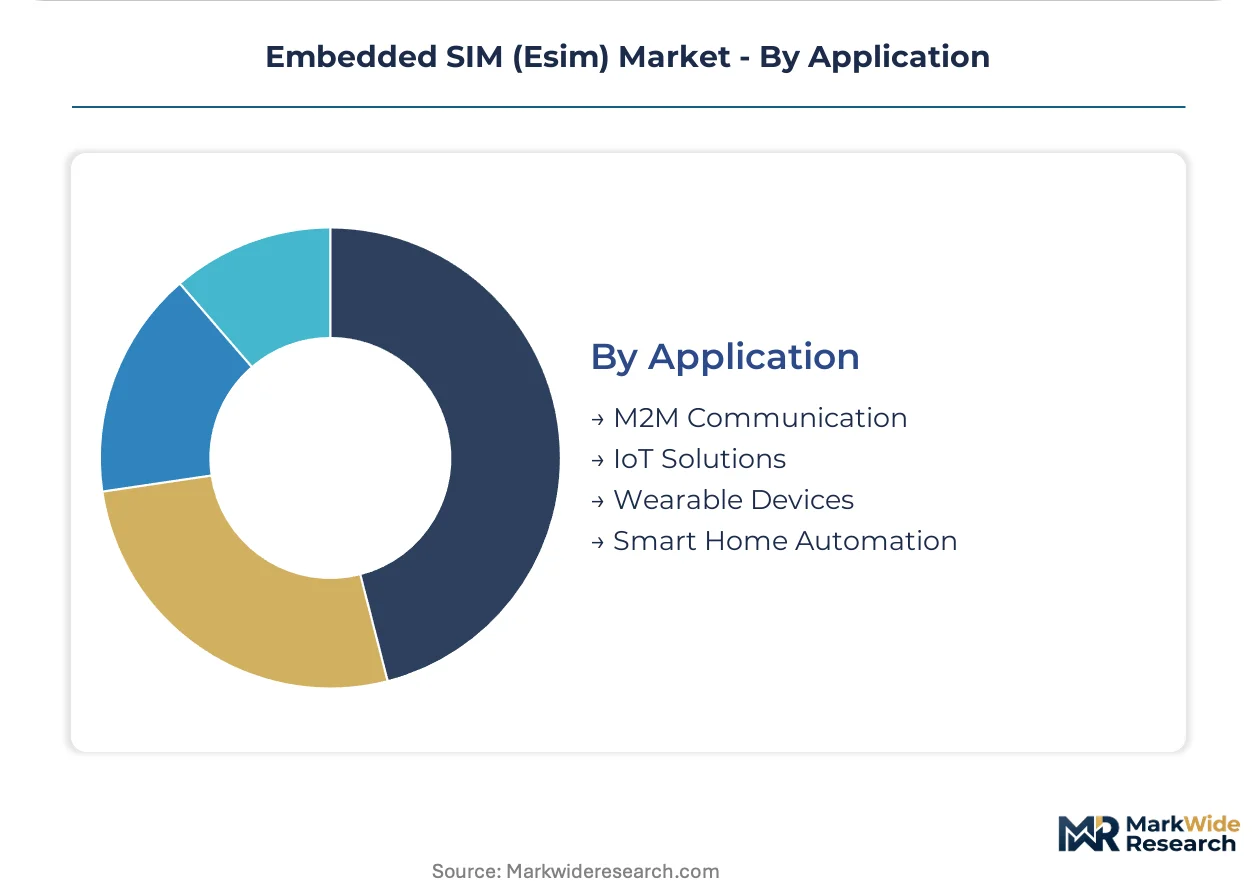
| Segmentation | Product Type: Consumer Electronics, Automotive, Industrial Devices, Healthcare Devices Technology: Remote SIM Provisioning, Cloud Management, Security Protocols, Data Encryption End User: Telecom Operators, OEMs, Enterprises, System Integrators Application: M2M Communication, IoT Solutions, Wearable Devices, Smart Home Automation |
| Companies Covered | Giesecke+Devrient, Thales Group, IDEMIA, NXP Semiconductors, STMicroelectronics, Infineon Technologies, Qualcomm, Deutsche Telekom, KORE Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded SIM (Esim) Market Strategic Shifts & Innovations
Remote provisioning infrastructure is maturing while hardware integration depths are expanding. These shifts are compressing the boundary between connectivity hardware and device system architecture.
Integrated SIM (iSIM) technology is automating the migration of eSIM functionality from discrete secure elements into cellular system-on-chip designs. Qualcomm and MediaTek are embedding iSIM capabilities into automotive and IoT modem platforms. This integration is automating bill-of-material reductions and board-space optimization for space-constrained devices.
The EU Cybersecurity Act's Common Criteria certification requirements are mandating hardware-based tamper resistance for critical infrastructure connectivity. ETSI's updated M2M specifications are incorporating these assurance levels. Automotive suppliers in Germany and France are restructuring component sourcing to satisfy these evaluation schemes.
Fleet operators are consolidating connectivity procurement under managed service contracts that bundle hardware, subscription management, and carrier negotiation. Traditional SIM distribution channels are losing relevance as enterprise buyers demand unified lifecycle management. This consolidation is most advanced in German commercial vehicle and logistics sectors.
Embedded SIM (Esim) Market Segmentation
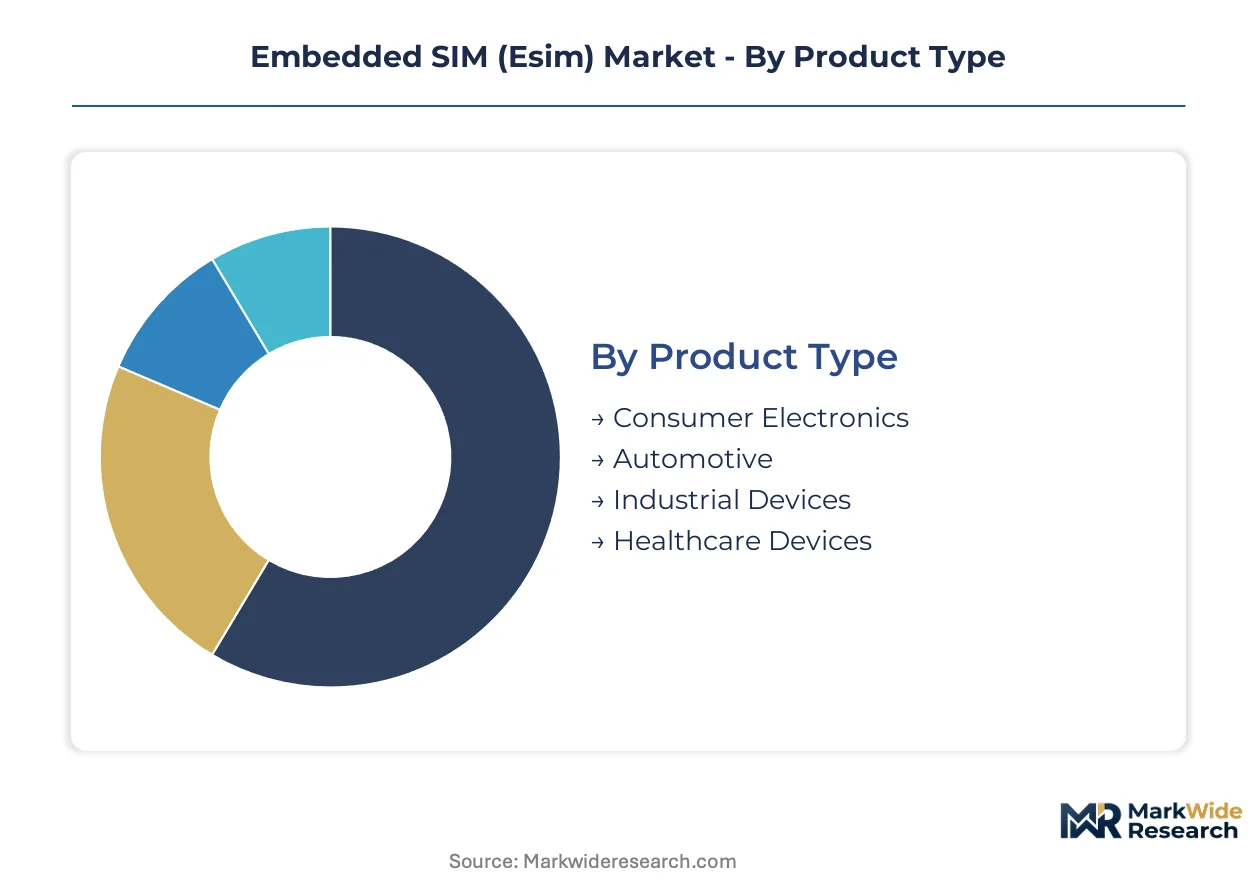
eSIM segmentation reflects divergent certification requirements across automotive, healthcare, and industrial verticals. Supply-side specialization forces buyers to qualify components against distinct regulatory frameworks rather than interchangeable commodity tiers.
Product Type:
Wafer-level packaging capacity concentrates among East Asian foundries, forcing automotive and healthcare OEMs to secure MFF2 supply through long-term offtake agreements.
- Automotive:Solderable MFF2 and smaller wafer-level packages must survive AEC-Q100 temperature cycling and vibration profiles. German and French OEMs dominate procurement volumes as KBA and ANSM mandates for emergency call systems harden connectivity requirements into homologation rules.
- Consumer Electronics:Smartphones and tablets utilize removable eUICC or embedded variants depending on OEM architecture preferences. Supply prioritization shifts toward automotive grades during capacity crunches, compressing availability for consumer-tier orders.
- Industrial Devices:Ruggedized M2M modules specify extended temperature ranges and conformal coating compatibility for telemetry applications.
- Healthcare Devices:FDA cybersecurity guidance and EMA MDR requirements mandate hardware-anchored identity for connected diagnostics and remote patient monitoring systems.
Automotive absorbs the bulk of installed capacity; Healthcare Devices is expanding most quickly as regulatory deadlines for connected medical equipment approach.
Technology:
Cost tiers separate standardized provisioning infrastructure from premium security implementations requiring Common Criteria certification.
- Security Protocols:Hardware-based tamper resistance through secure microcontrollers and trusted execution environments commands premium positioning. EU Cybersecurity Act evaluation schemes in Germany and France mandate these assurance levels for critical infrastructure connectivity.
- Remote SIM Provisioning:GSMA SGP.32 standards enable over-the-air profile management across multiple carrier relationships. Deployment maturity concentrates among Tier 1 carriers with established subscription management platforms.
- Cloud Management:Centralized lifecycle platforms bundle device onboarding, profile switching, and usage analytics for enterprise fleets.
- Data Encryption:End-to-end cryptographic protection for sensitive payloads in healthcare and financial applications.
Remote SIM Provisioning captures the highest deployment volumes; Security Protocols climbs the fastest as certification requirements harden across automotive and healthcare verticals.
End User:
Procurement patterns diverge between carriers seeking subscription control and OEMs demanding supply security for multi-year production programs.
- Telecom Operators:Deutsche Telekom, Orange, and Vodafone operate proprietary subscription management platforms that lock device ecosystems into carrier-specific provisioning workflows. Platform fragmentation forces redundant certification investments from hardware vendors.
- OEMs:Automotive and industrial manufacturers negotiate direct secure element supply to decouple hardware procurement from carrier service agreements. BMW and Siemens exemplify this backward integration strategy.
- Enterprises:Fleet operators and utilities consolidate connectivity procurement under managed service contracts spanning hardware, provisioning, and carrier negotiation.
- System Integrators:Engineering firms bundle eSIM modules with application-layer development for vertical-specific deployments.
OEMs absorb the bulk of component volume; Enterprises is gaining share fastest as fleet and utility buyers consolidate procurement under outcome-based contracts.
Application:
Volume concentration in established M2M deployments contrasts with rapid expansion across emerging IoT endpoints.
- M2M Communication:Industrial telemetry, fleet management, and asset tracking systems standardized on embedded connectivity years ago. German logistics operators and Dutch utility AMI deployments represent mature demand centers with 10-15 year asset replacement cycles.
- IoT Solutions:Low-power wide-area networks proliferate across smart metering, agriculture sensors, and supply chain trackers. Spanish utilities and Netherlands grid operators specify eSIM for next-generation infrastructure to preserve carrier flexibility.
- Wearable Devices:Smartwatches and health monitors utilize compact eSIM variants for standalone cellular connectivity.
- Smart Home Automation:Security systems and energy management hubs embed cellular backup connectivity beyond Wi-Fi dependency.
M2M Communication holds the largest installed base; IoT Solutions shows the steepest expansion trajectory as LPWAN coverage extends across European industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian foundries dominate wafer-level packaging output, while European automotive OEMs consume the bulk of finished secure elements. This production-consumption divide forces German and French manufacturers into long-term supply contracts with Taiwan and South Korean semiconductor houses.
Germany
Automotive OEMs in Stuttgart and Munich drive concentrated demand for AEC-Q100 qualified MFF2 modules. KBA mandates for emergency call systems harden eSIM into vehicle homologation requirements. The Baden-Württemberg semiconductor corridor hosts qualification labs where Thales and Infineon validate secure element designs against EU Cybersecurity Act evaluation schemes.
United States
Fleet operators and healthcare device manufacturers anchor procurement volumes for remote provisioning platforms. FCC device authorization rules impose iterative testing protocols that extend launch timelines for multi-carrier configurations. California's connected health ecosystem in San Diego and Silicon Valley generates FDA-guided demand for hardware-anchored identity in diagnostics equipment.
China
Domestic smartphone OEMs and industrial IoT module vendors absorb substantial wafer output from local foundries. MIIT cybersecurity standards for critical infrastructure connectivity mandate hardware-based tamper resistance in smart grid deployments. The Yangtze River Delta manufacturing belt concentrates MFF2 packaging capacity serving both domestic consumption and export markets.
France
ANSM regulations for connected medical devices and emergency call mandates from the transport ministry create dual demand streams. Paris-based subscription management platforms compete with German and Dutch carriers for enterprise fleet contracts. The Sophia Antipolis technology cluster hosts integration labs where automotive suppliers validate GSMA SGP.32 compliance.
Japan
METI industrial digitization programs accelerate eSIM specification in factory automation and supply chain tracking systems. Automotive suppliers in Toyota City and Nagoya integrate secure elements into telematics units for export to European markets. Japanese module vendors qualify components against both domestic JIS standards and ETSI specifications for European OEM customers.
Embedded SIM (Esim) Market Key Industry Players
Top-tier vendors anchor subscription management and secure element supply, while mid-tier module integrators compete on vertical specialization and regional carrier relationships. The vendor base stratifies across three functional layers: semiconductor foundries producing MFF2 wafers, secure element specialists packaging tamper-resistant chips, and subscription management platform operators orchestrating remote provisioning. Consolidation pressures concentrate around M&A activity targeting subscription management capabilities and strategic partnerships linking automotive OEMs directly to secure element foundries.
Within the secure element tier, Thales Group and Giesecke+Devrient exemplify European heritage players that have migrated smart card manufacturing expertise into automotive-grade embedded solutions. NXP Semiconductors occupies a position bridging semiconductor fabrication with vehicle network gateway integration. Deutsche Telekom represents carrier-anchored competition that bundles connectivity service with proprietary provisioning infrastructure.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| Thales Group |
| IDEMIA |
| NXP Semiconductors |
| STMicroelectronics |
| Infineon Technologies |
| Qualcomm |
| Deutsche Telekom |
| KORE Wireless |
| Others |
Cost & Logistics Intelligence
German automotive OEM procurement concentration anchors contract-based long-term offtake pricing for AEC-Q100 qualified MFF2 modules, compressing spot-market liquidity and amplifying foundry bargaining power during capacity crunches.
Pricing Analysis
Margin tightening in automotive-grade secure elements reflects wafer-level packaging capacity bottlenecks at East Asian foundries. Three-tier pricing structure across Common Criteria-certified premium, automotive-standard, and industrial-economy levels separates subscription management platform bundles from discrete hardware supply. Cost-down pressure on consumer-tier variants accelerates because smartphone OEMs divert volume commitments toward automotive allocations during supply constraints. Fleet operators and utilities demonstrate lowest price sensitivity due to 15-year asset lifecycle calculations, while consumer electronics buyers face acute margin compression.
Supply Chain Analysis
Dual-sourcing mandates from BMW and Siemens force qualification of Taiwanese and South Korean foundry alternatives for MFF2 wafer output. Silicon wafers, tamper-resistant packaging substrates, and GSMA-certified subscription management software constitute critical input dependencies. Single-source vulnerability concentrates around advanced node secure element fabrication at TSMC and Samsung facilities. Distribution runs through direct OEM contracts rather than distributor channels, with subscription management platforms operated by Deutsche Telekom and Vodafone capturing recurring service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Embedded SIM market functions as a vertical-integration race where foundry capacity control and subscription management platform ownership determine margin capture across the value chain.
For Market Incumbents: To counter iSIM displacement from Qualcomm and MediaTek baseband integration, Thales and Giesecke+Devrient must deepen backward integration into wafer-level packaging capacity in Taiwan and South Korea while accelerating Common Criteria certification pipelines for EU Cybersecurity Act compliance. For New Entrants and Emerging Players: Enter via healthcare device certification white space where FDA cybersecurity guidance and EMA MDR deadlines create qualification bottlenecks incumbent vendors cannot service simultaneously. Spanish and Dutch utility AMI deployments offer the most penetrable infrastructure segment for managed service bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor subscription management platform specialists in Germany and France where carrier fragmentation forces redundant certification investments from hardware vendors. Watch GSMA SGP.32 adoption velocity as the inflection signal distinguishing scalable platform architectures from stranded proprietary implementations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captures margin from wafer-level packaging bottleneck at TSMC and Samsung facilities. |
| Common Criteria Certification Investment | Unlocks EU Cybersecurity Act-mandated procurement from German and French automotive OEMs. |
| Subscription Management Platform Acquisition | Consolidates carrier-proprietary workflows into unified enterprise lifecycle orchestration. |
| Healthcare Device Qualification Pipeline | Addresses FDA-guided demand for hardware-anchored identity in connected diagnostics equipment. |
| iSIM Technology Partnership | Automates cost reduction pathways through baseband processor integration with Qualcomm modem platforms. |
Research Approach
Multi-period observation of GSMA standard adoption timelines and automotive OEM platform launch schedules anchored the trend analysis, supplemented by interviews with secure element procurement directors at Tier 1 suppliers, subscription management platform architects at European carriers, and regulatory affairs specialists at semiconductor certification labs. Secondary validation drew from ETSI M2M specification releases, FCC equipment authorization databases, and EU Cybersecurity Act evaluation scheme documentation. Bottom-up component demand modeling triangulated against top-down carrier connectivity revenue projections.
Segment-weighting across automotive, healthcare, industrial, and consumer verticals calibrated volume and value outputs, with technology tiers distinguishing remote provisioning infrastructure from security protocol implementations. CAGRs derived from fitted growth curves applied to installed base replacement cycles and new vehicle platform penetration assumptions. Forecast inputs incorporated KBA and ANSM mandate enforcement timelines alongside LPWAN network coverage expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GSMA standard revision delays or foundry capacity allocation shocks. Deviation in EU Cybersecurity Act certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G System Integration Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
A2P SMS Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Norway Telecom Market
Telecommunications
5G Monetization Market
Telecommunications
Global Relay Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
GPON Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Romania Telecom Market
Telecommunications
Algeria Telecom Market
Telecommunications
Global B2B Telecommunication Market