
 Cloud Radio Access Network (C-RAN) Market | 2026-2036
Cloud Radio Access Network (C-RAN) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Radio Access Network (C-RAN) Market Intelligence
Telecom operator procurement is restructuring around centralized baseband pooling and shared infrastructure models. Huawei Technologies Co., Ltd. dominates integrated radio and transport solutions across multiple continents. Telefonaktiebolaget LM Ericsson sustains leadership in cloud-native RAN software stacks. Nokia Corporation differentiates through its anyRAN approach bridging purpose-built and cloud platforms.
Cloud Radio Access Network architecture disaggregates baseband processing from remote radio heads through fronthaul links operating at 25 Gbps or higher, enabling centralized resource orchestration for multi-cell coordination. The deployment model dimension shows hybrid cloud configurations capturing the strongest momentum as operators balance latency-sensitive workloads against elastic capacity scaling. By technology, 5G-NR deployments anchor near-term infrastructure spending while LTE refactoring extends legacy asset viability.
3GPP specifications govern radio interface protocols and interoperability testing, while O-RAN Alliance open fronthaul requirements reshape vendor qualification criteria. National regulators including the FCC in the United States, Ofcom in the United Kingdom, and Anatel in Brazil influence spectrum allocation timelines that directly determine C-RAN rollout cadence. Stakeholders must track Open RAN security certification frameworks and their integration into operator procurement mandates.
Market Dynamics
Telecom infrastructure procurement is pivoting from integrated vendor stacks toward disaggregated, software-centric architectures. Open RAN specifications from the O-RAN Alliance are forcing incumbent equipment manufacturers to unbundle hardware and software layers, while operators in South Korea, Japan, and India mandate multi-vendor interoperability in spectrum auctions.
Growth Catalysts
- Mid-band spectrum auctions:Governments in South Korea, Japan, and India are releasing 3.5 GHz and 28 GHz bands with C-RAN deployment conditions attached, accelerating centralized baseband pooling mandates.
- O-RAN Alliance open fronthaul:The 7-2x split specification is standardizing interfaces between radio units and distributed units, enabling multi-vendor procurement and reducing vendor lock-in.
- Edge computing convergence:Hyperscale cloud providers are deploying baseband processing at metro edge locations, creating shared infrastructure models that amortize 5G densification costs across multiple tenants.
Market Restraints
- Optical transport cost volatility:25G and 100G coherent pluggable optics for fronthaul links face supply constraints from concentrated III-V semiconductor foundry capacity in Taiwan.
- Legacy LTE asset stranding:Purpose-built baseband hardware from 2015-2019 lacks software upgrade paths to 5G-NR, forcing parallel infrastructure investment without depreciation recovery.
- Local content mandates:India's PLI scheme for telecom equipment requires domestic manufacturing of C-RAN components, extending procurement timelines for multinational operators.
Strategic Opportunities
- Rural coverage gaps:India's BharatNet program and underserved prefectures in Japan present whitespace for low-density C-RAN deployments using satellite backhaul integration.
- Private 5G networks:Manufacturing campuses and port authorities in South Korea are procuring dedicated C-RAN slices for ultra-reliable low-latency communications, bypassing public network congestion.
- AI-driven radio resource management:Machine learning inference at centralized baseband pools enables real-time interference coordination and predictive maintenance, creating service revenue layers beyond connectivity.
Industry Challenges
- Fronthaul synchronization precision:Phase and frequency alignment across distributed radio units requires sub-microsecond timing distribution, complicating integration with legacy GPS-dependent architectures.
- Multi-vendor system integration:Operators assembling radio units from one supplier, distributed units from another, and centralized units from a third face interoperability testing cycles that extend deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Radio Access Network (C-RAN) Market |
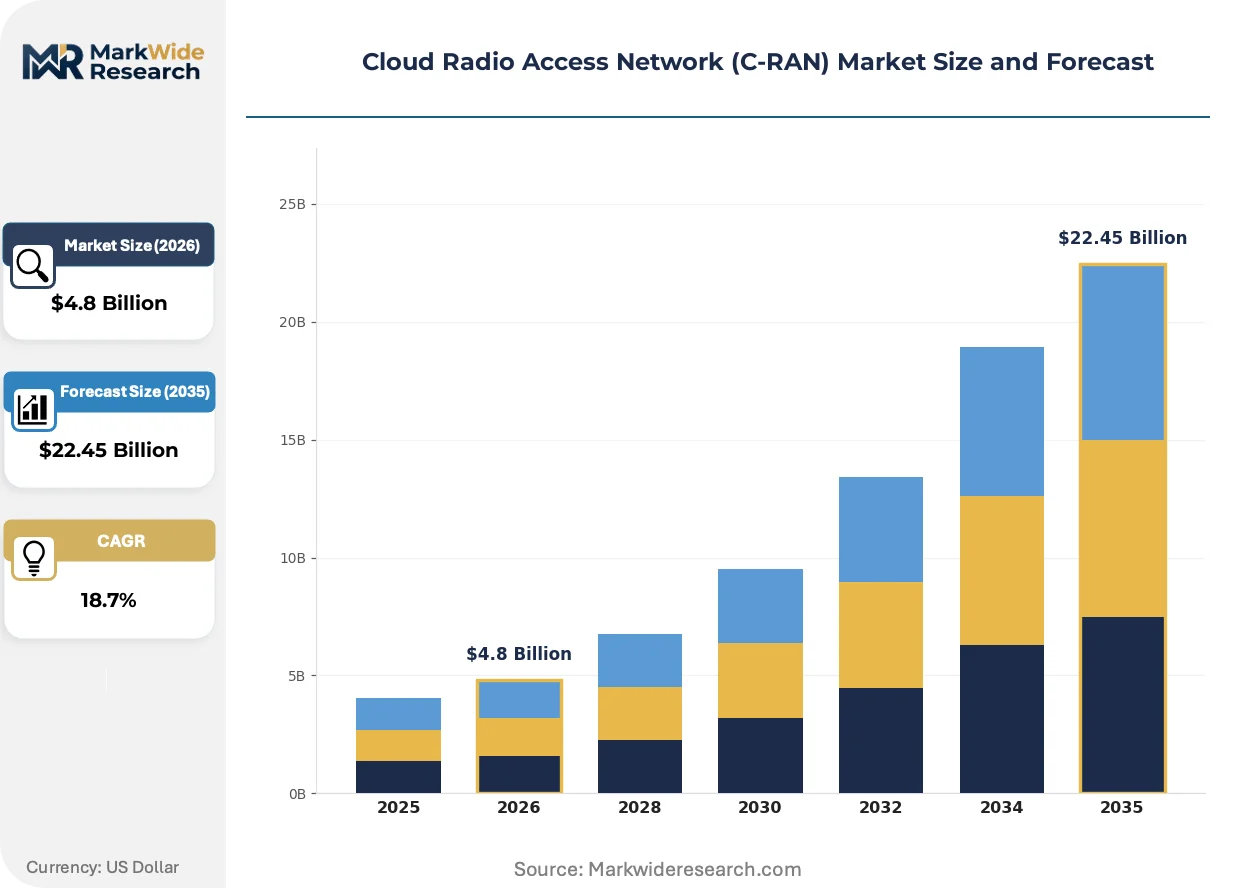
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Private Cloud, Public Cloud, Hybrid Cloud, On-Premises End User: Telecom Operators, Enterprises, Government Agencies, Managed Service Providers Technology: LTE, 5G, NR, Wi-Fi Solution: Infrastructure, Software, Services, Hardware |
| Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Cisco Systems, Inc., Intel Corporation, Samsung Electronics Co., Ltd., NEC Corporation, Mavenir Systems, Inc., ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Radio Access Network (C-RAN) Market Strategic Shifts & Innovations
Intelligent automation is penetrating every layer of radio access infrastructure. Artificial intelligence, cloud-native software architectures, and policy-driven procurement models are converging to compress deployment timelines and shift capital structures from hardware ownership to service consumption.
Cloud-native RAN software stacks are unifying containerized baseband functions with Kubernetes orchestration across multi-cloud substrates. Tier-1 operators in South Korea and Japan are migrating network functions from bare-metal appliances to microservices architectures, enabling elastic scaling during traffic spikes. This unification is compressing the traditional three-year hardware refresh cycle into continuous software delivery pipelines.
The FCC in the United States is conditioning mid-band spectrum licenses on cybersecurity certification frameworks for Open RAN deployments. Equipment vendors must now demonstrate supply chain integrity and software bill of materials transparency before qualifying for operator procurement shortlists. North American mobile network operators are responding by embedding security requirements into RFP specifications earlier in vendor selection processes.
Consolidated buying consortia are displacing bilateral operator-vendor negotiations in Asia-Pacific infrastructure procurement. Shared infrastructure entities in Japan and South Korea are pooling spectrum resources and centralizing equipment purchasing for multiple regional operators. This concentration is most visible in rural 5G rollouts where single C-RAN hubs serve subscriber bases previously fragmented across three or more network footprints.
Cloud Radio Access Network (C-RAN) Market Segmentation
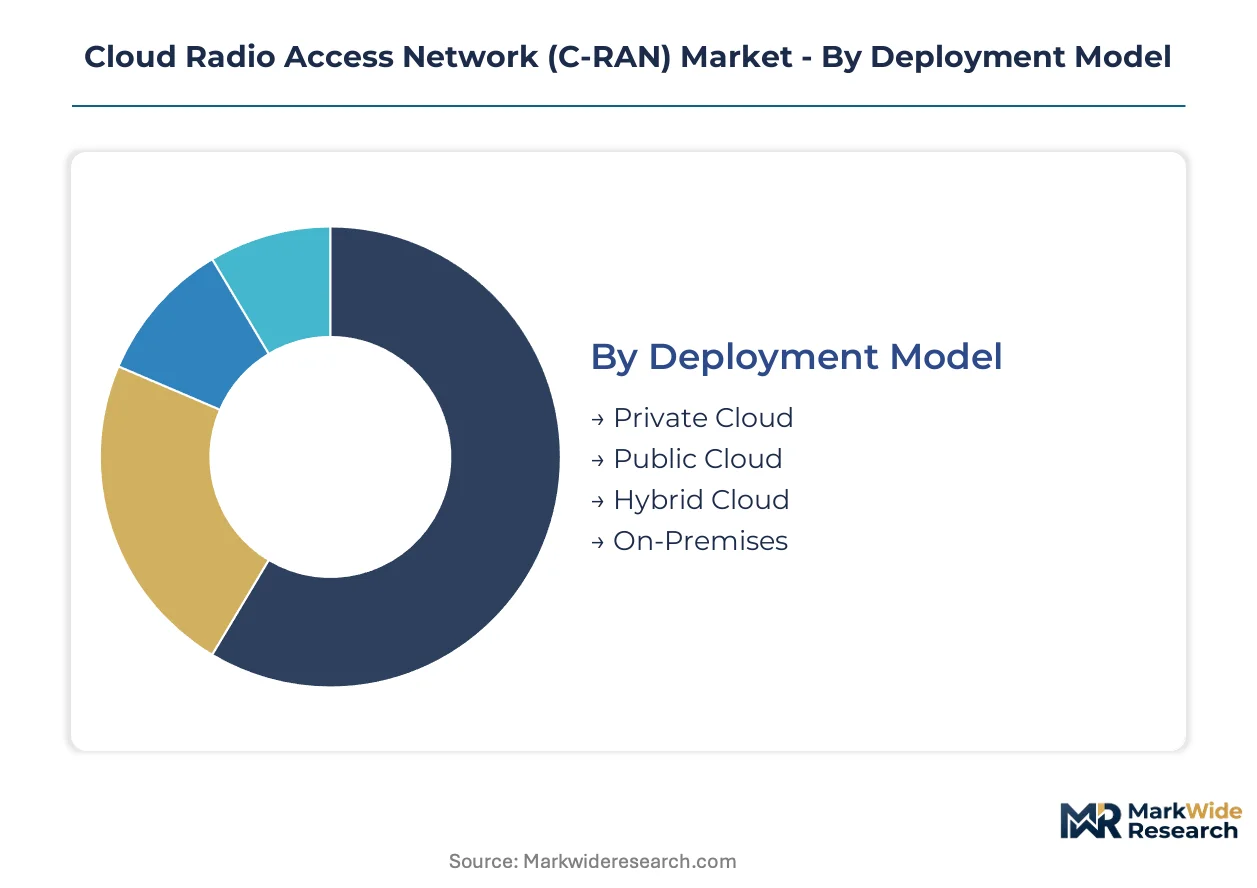
C-RAN procurement patterns diverge sharply across deployment architectures and buyer categories. Infrastructure buyers weigh latency constraints against capital efficiency, while technology choices reflect spectrum availability and legacy asset positions.
Deployment Model:
Capital intensity and data sovereignty requirements separate buyers in this dimension.
- Hybrid Cloud:Combines on-premises baseband pooling with burst capacity from hyperscale cloud providers. South Korean operators favor this architecture for 5G densification in Seoul and Busan, balancing sub-10ms latency requirements against elastic scaling for stadium events and transit corridors.
- Private Cloud:Dedicated infrastructure deployed in operator-controlled data centers with full hardware ownership. Japanese regional carriers select this model to satisfy METI data localization guidelines while maintaining deterministic performance for industrial IoT contracts.
- Public Cloud:Baseband functions hosted on AWS, Azure, or GCP infrastructure with consumption-based pricing.
- On-Premises:Traditional appliance-based deployment with no cloud abstraction layer.
Volume sits with Private Cloud; growth tilts toward Hybrid Cloud.
End User:
Procurement sophistication and contract scale distinguish buyer types.
- Telecom Operators:Tier-1 mobile network operators with multi-billion-dollar infrastructure budgets and established vendor relationships. India's Reliance Jio and Bharti Airtel drive concentrated demand as TRAI mandates C-RAN deployment for 3.5 GHz spectrum licensees.
- Enterprises:Manufacturing conglomerates and logistics operators procuring dedicated network slices. South Korean automotive plants in Ulsan and Gwangju deploy private C-RAN instances for autonomous guided vehicle coordination.
- Government Agencies:National broadband programs and defense communications procurements.
- Managed Service Providers:Systems integrators offering C-RAN as-a-service to mid-market enterprises.
Telecom Operators dominate installed base; Enterprises are expanding most quickly.
Technology:
Spectrum allocation timelines and equipment refresh cycles determine technology adoption.
- 5G NR:New radio implementations using 3GPP Release 15 and beyond specifications with massive MIMO support. Deployment concentrates in markets where regulators have released mid-band spectrum with C-RAN conditions attached.
- LTE:Legacy 4G infrastructure requiring baseband virtualization to extend asset viability. Indian operators refactor existing 2017-2019 deployments to avoid stranding investments before 5G-NR overlay completion.
- NR:Standalone 5G deployments without LTE anchor.
- Wi-Fi:Unlicensed spectrum integration for indoor coverage extension.
LTE carries current volume; 5G NR claims the steepest expansion trajectory.
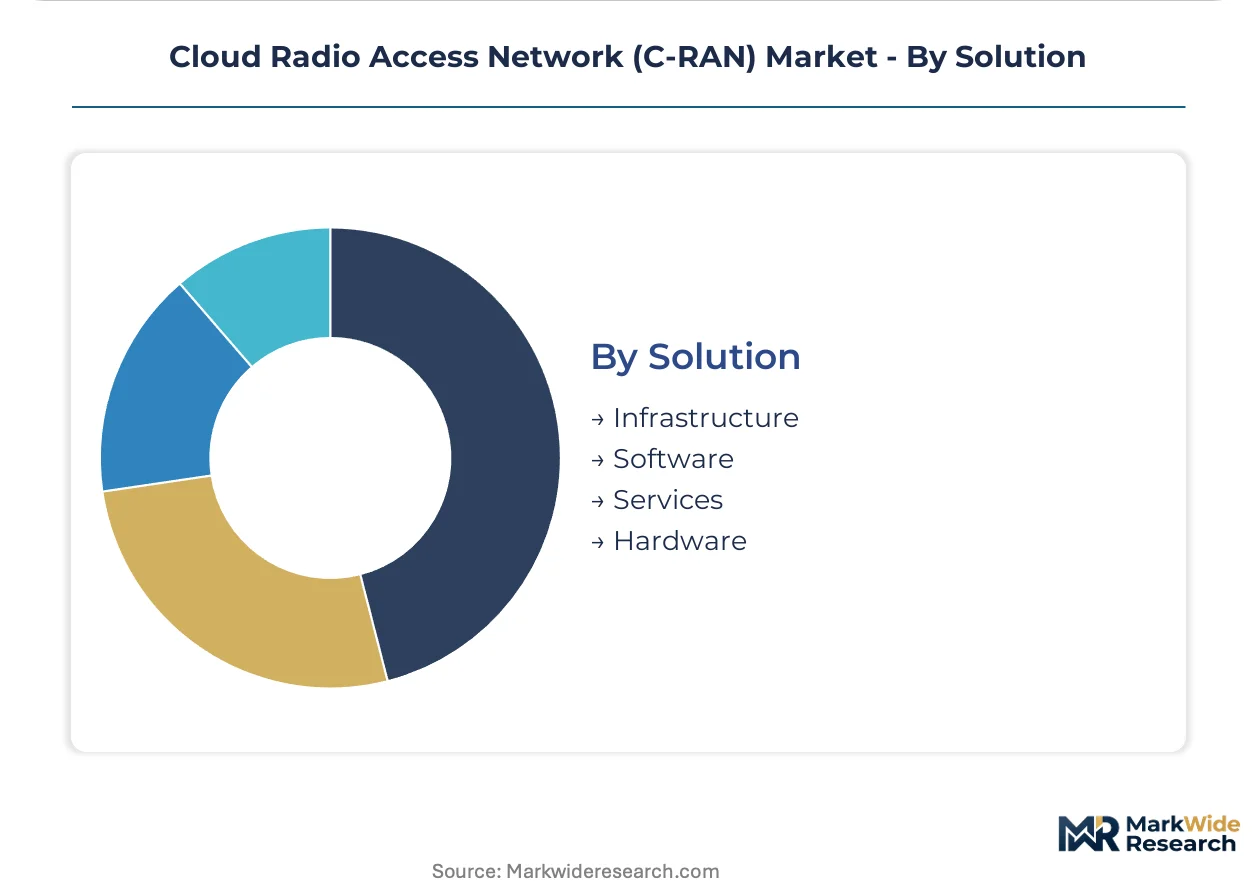
Solution:
Value capture migrates from hardware ownership to software licensing and professional services.
- Software:Cloud-native baseband functions, orchestration platforms, and AI-driven radio resource management tools. Japanese operators prioritize containerized RAN software with Kubernetes orchestration to compress three-year hardware cycles into continuous delivery pipelines.
- Services:System integration, network design, and managed operations contracts. Demand concentrates where multi-vendor Open RAN deployments require specialized interoperability testing and ongoing performance optimization.
- Infrastructure:Data center facilities, power systems, and cooling equipment.
- Hardware:Radio units, distributed units, centralized units, and fronthaul transport equipment.
Hardware dominates current procurement value; Software is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Cloud Radio Access Network infrastructure concentrates in Asia-Pacific markets where 5G spectrum auctions impose centralized baseband pooling mandates. South Korea, Japan, and India anchor near-term deployment volume as regulators attach C-RAN conditions to mid-band licenses.
South Korea
SK Telecom and KT Corporation drive fronthaul densification in Seoul and Busan to support massive MIMO deployments. The Ministry of Science and ICT requires multi-vendor interoperability for 28 GHz spectrum licensees. Gwangju metropolitan area hosts private 5G C-RAN instances serving automotive manufacturing campuses.
Japan
NTT Docomo and KDDI prioritize containerized baseband functions with Kubernetes orchestration across Tokyo-Osaka corridors. METI data localization guidelines steer regional carriers toward private cloud deployments. Rural prefectures including Hokkaido and Tohoku present whitespace for satellite-backhaul C-RAN hubs.
India
Reliance Jio and Bharti Airtel refactor legacy LTE infrastructure to avoid asset stranding during 5G-NR overlay. TRAI mandates C-RAN deployment for 3.5 GHz spectrum holders. The PLI scheme for telecom equipment extends procurement timelines by requiring domestic manufacturing of centralized unit components.
United States
Verizon and AT&T condition vendor qualification on Open RAN security certification frameworks. The FCC attaches cybersecurity requirements to mid-band spectrum licenses in the 3.45-3.55 GHz range. Dallas-Fort Worth and Phoenix metro clusters concentrate early standalone 5G C-RAN deployments.
Germany
Deutsche Telekom pilots cloud-native RAN software stacks in Bavaria and North Rhine-Westphalia industrial zones. The national telecom regulator BNetzA influences 5G rollout cadence through spectrum renewal timelines. Baden-Württemberg automotive suppliers procure dedicated network slices for factory-floor automation.
Cloud Radio Access Network (C-RAN) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native software specialization and open interface compliance. The vendor base stratifies across integrated equipment manufacturers, disaggregated software specialists, and silicon platform providers. Three archetypes dominate: full-stack incumbents unbundling hardware-software layers, pure-play software vendors capitalizing on O-RAN momentum, and semiconductor firms supplying baseband processing silicon. Competitive moves center on strategic partnerships for multi-vendor interoperability testing and portfolio diversification into edge computing convergence.
Within the full-stack tier, Huawei Technologies Co., Ltd. and Telefonaktiebolaget LM Ericsson exemplify divergent responses to disaggregation pressure. Among software-centric challengers, Mavenir Systems, Inc. occupies a position representing pure-play open architecture specialists. Nokia Corporation anchors the transitional archetype bridging purpose-built and cloud-native deployment models.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Cisco Systems, Inc. |
| Intel Corporation |
| Samsung Electronics Co., Ltd. |
| NEC Corporation |
| Mavenir Systems, Inc. |
| ZTE Corporation |
| Others |
Cost & Logistics Intelligence
III-V semiconductor foundry capacity in Taiwan governs optical transport module costs as 25G and 100G coherent pluggable optics move through tiered pricing structures toward telecom operators in South Korea, Japan, and India.
Pricing Analysis
Volume concentrates in standardized fronthaul optics where margin compression runs deepest, while premium tiers capture value in software-defined baseband orchestration and AI-driven radio resource management tools. Price differentiation stems from certification tier—O-RAN Alliance compliance verification adds procurement qualification costs—and volume scale, with hyperscale cloud providers extracting steepest discounts through consolidated buying consortia. Pricing pressure intensifies in hardware tiers as open interface specifications commoditize radio unit components, eroding incumbent vendor premiums. Tier-1 telecom operators exhibit highest price sensitivity due to multi-billion-dollar infrastructure budgets and competitive 5G rollout timelines, while private 5G network deployments in manufacturing campuses show lower sensitivity given mission-critical latency requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for centralized baseband units, while systems integrators and managed service providers intermediate enterprise and mid-market procurement. Supply concentrates in Taiwan for III-V semiconductor foundry capacity, South Korea for memory and advanced packaging, and China for radio unit manufacturing and assembly. Raw material dependencies include gallium arsenide substrates, indium phosphide wafers, and specialized optical coatings for fronthaul transceivers. Single-source vulnerability in Taiwan-based foundry capacity for coherent pluggable optics presents structural risk, compounded by India's PLI scheme mandating domestic manufacturing of C-RAN components that fragments procurement timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race as players pursue captive supply of baseband processing silicon to escape foundry bottlenecks and secure cost positions.
For Market Incumbents: Anchor market position through backward integration into III-V semiconductor foundry partnerships or captive optical module production, neutralizing supply constraints that threaten 5G densification timelines. Defend against pure-play software vendors by accelerating cloud-native RAN certification cycles and embedding AI-driven orchestration into existing installed bases. Prioritize interoperability testing investments to maintain relevance as O-RAN Alliance specifications reshape procurement qualification criteria.
For New Entrants and Emerging Players: Begin with underserved rural prefectures in Japan and satellite-backhaul C-RAN deployments in India's BharatNet program, where incumbent coverage gaps create whitespace for low-density infrastructure models. Target private 5G network slices in South Korean automotive manufacturing campuses, where ultra-reliable low-latency requirements favor specialized system integrators over public network operators. Lead with managed C-RAN-as-a-service offerings that amortize capital costs across multiple enterprise tenants.
For Investors and Strategic Acquirers: O-RAN Alliance security certification framework adoption by the FCC is the leading indicator that procurement mandates are hardening toward supply chain transparency requirements, favoring vendors with demonstrable software bill of materials documentation. Long-term viability across the analysis window rests on cloud-native software specialization rather than hardware ownership, positioning pure-play orchestration platform developers as prime acquisition targets. Monitor hyperscaler edge computing partnership announcements as signals of shared infrastructure model validation.
| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Certification Investment | FCC and TRAI procurement mandates now require compliance verification for spectrum license eligibility. |
| Backward Integration into Optical Module Production | Taiwan foundry concentration creates vulnerability that captive supply chains can neutralize for tier-1 operators. |
| Cloud-Native RAN Software Stack Development | Kubernetes orchestration compresses hardware refresh cycles into continuous delivery pipelines for Japanese operators. |
| Private 5G Network Slice Specialization | South Korean automotive plants in Ulsan procure dedicated instances for autonomous guided vehicle coordination. |
| Multi-Vendor Interoperability Testing Partnership | Open fronthaul specifications force extended qualification cycles that specialized integrators can monetize. |
Research Approach
Document review covered 3GPP specification releases, O-RAN Alliance technical documents, TRAI and FCC spectrum auction filings, and operator procurement RFP disclosures, complemented by interviews with network planning executives at tier-1 mobile operators, procurement leads at hyperscale cloud providers, semiconductor foundry account managers, and systems integration specialists. Secondary validation drew from customs trade data for optical transport equipment, SEC filings of listed telecom infrastructure vendors, and national spectrum allocation databases. Bottom-up deployment tracking across Seoul, Tokyo, Mumbai, and Dallas-Fort Worth metro clusters was triangulated against top-down infrastructure spending estimates.
Market size outputs reflect segment-level modeling across deployment architecture, end-user category, technology generation, and solution type throughout the forecast period. CAGRs were derived from regression analysis of historical infrastructure spending patterns against spectrum auction timelines and regulatory mandate implementation schedules. Industry-specific forecast inputs include mid-band spectrum release calendars, PLI scheme localization requirements, and edge computing convergence indicators from hyperscaler capex disclosures.
Underlying measurement precision varies by segment; 5G-NR deployment volumes carry tighter precision than LTE refactoring estimates due to clearer regulatory timelines. Forecasts reflect base-case assumptions regarding foundry capacity expansion and Open RAN security certification adoption rates. Periodic stress-testing of base assumptions against foundry utilization reports and spectrum auction participation data is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Telecom Order Management Market
Telecommunications
5G MVNO Market
Telecommunications
Iceland Telecom Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
5G System Integration Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
GPON Equipment Market
Telecommunications
Fixed Voice Market
Telecommunications
5G in Defense Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
5G Transport Networks Market
Telecommunications
Voip Phone Market