
 Asia-Pacific Animal Protein Market | 2026-2036
Asia-Pacific Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Animal Protein Market Outlook
Wholesale distribution networks across Southeast Asia is reconfiguring as cold chain investments consolidate procurement routes toward urban food service hubs. Fonterra Co-operative Group Limited leverages its New Zealand dairy protein sourcing to anchor premium ingredient supply across Australian and Chinese processing channels. Glanbia PLC competes through specialized whey and collagen isolates directed at sports nutrition manufacturers in Japan and South Korea. Kerry Group PLC extends its flavor-protein integration capabilities to dominate clean-label formulation partnerships with regional quick-service restaurant chains.
Asia-Pacific animal protein encompasses tissue-derived and extracted protein products from poultry, cattle, swine, and aquatic species, typically processed to achieve specified moisture content, protein concentration, and microbiological standards for human consumption or industrial formulation. These proteins serve as functional ingredients providing emulsification, gelation, and nutritional fortification across prepared foods, nutritional supplements, and foodservice applications. Poultry protein leads volume contribution due to cost-efficient conversion ratios and shorter production cycles across Thailand and Chinese broiler operations. Beef protein sustains premium positioning within aging-demographic nutritional products and high-end foodservice channels across Japan. Pork protein dominates processed meat and savory flavor base applications through integrated slaughter-to-render operations in Vietnam and the Philippines.
China's SAMR enforces updated GB standards for contaminant limits and labeling transparency that directly determine import eligibility for foreign protein suppliers. Japan's PMDA and Ministry of Health, Labour and Welfare maintain stringent specifications for functional protein health claims that shape R&D investment priorities among ingredient innovators. Australia's FSANZ and New Zealand's MPI coordinate trans-Tasman standards that facilitate unified market access for cross-border dairy and meat protein trade. Stakeholders must monitor evolving ASEAN harmonization initiatives and country-specific halal certification requirements that will determine which processing configurations secure preferential placement across Indonesian and Malaysian distribution channels.
Market Dynamics
Cold chain modernization across Southeast Asia is consolidating procurement routes toward urban food service hubs, forcing suppliers to reconfigure distribution networks around compliance with China's updated GB standards and halal certification requirements in Indonesia and Malaysia.
Growth Catalysts
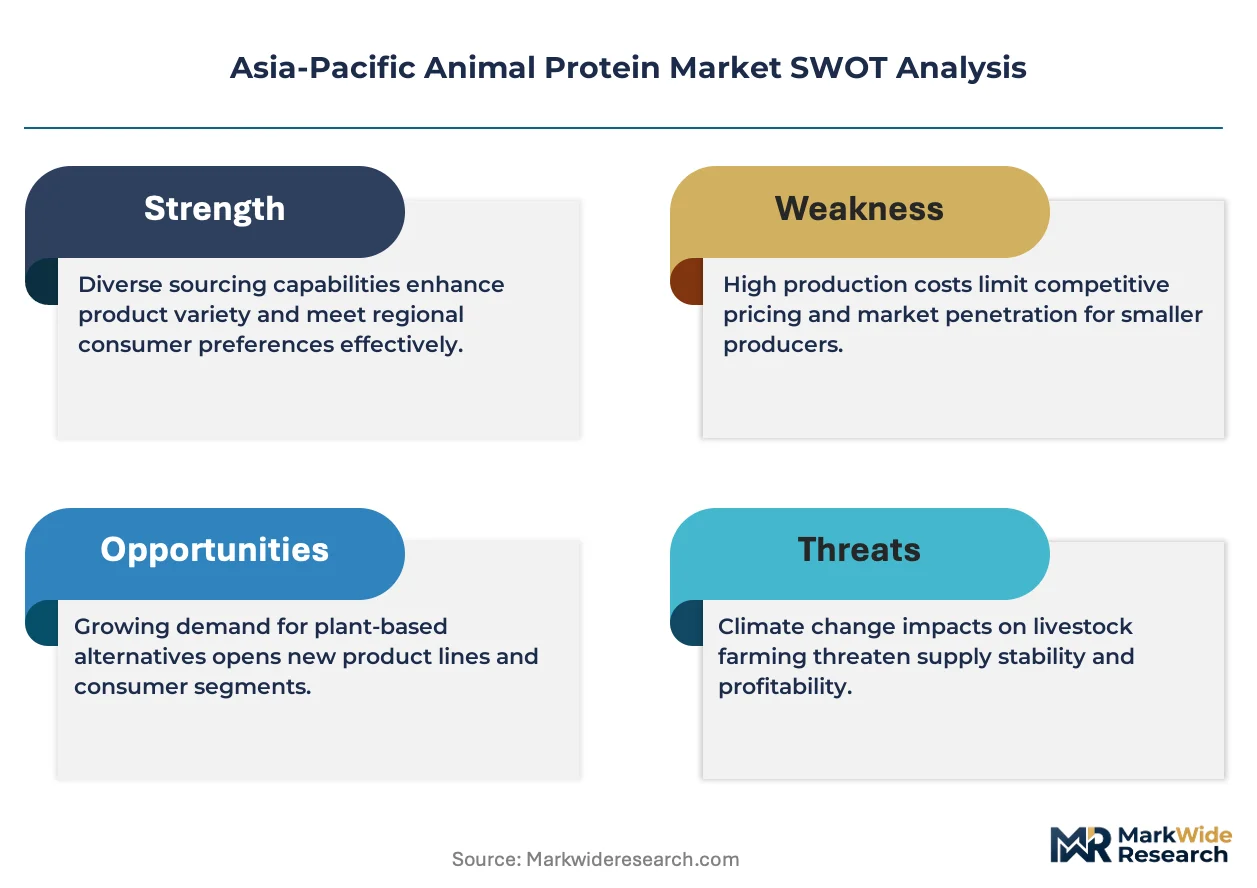
- Urban food service expansion:Southeast Asian metropolitan centers are driving volume demand as quick-service restaurant chains scale protein-intensive menu offerings.
- Japan's functional health claims framework:PMDA specifications for protein-based nutritional products are channeling R&D investment toward aging-demographic formulations.
- Dual carbon policy alignment:China's MEE enforcement of carbon intensity benchmarks is accelerating cleaner rendering technologies in integrated slaughter-to-processing facilities.
Market Restraints
- Feed input cost volatility:Soybean meal and fishmeal price fluctuations squeeze margin structures for Thai and Vietnamese broiler operations.
- Import eligibility friction:SAMR's contaminant limit updates under GB standards create compliance windows that disqualify legacy foreign suppliers.
- Plant protein substitution:Pea and soy isolate advances in South Korean sports nutrition are compressing addressable market for whey-derived offerings.
Strategic Opportunities
- Philippine archipelago distribution:Underdeveloped cold chain infrastructure in secondary cities creates first-mover advantage for integrated logistics investments.
- Clean-label formulation partnerships:Flavor-protein integration capabilities are opening quick-service restaurant chain supply positions previously held by synthetic additive suppliers.
- ASEAN harmonization tailwind:Emerging regional standards convergence will reduce multi-country certification burdens for Malaysia-Indonesia cross-border processors.
Industry Challenges
- Halal certification timeline compression:MUI and JAKIM audit backlogs in Indonesia and Malaysia are extending product launch cycles by 4-8 months.
- Cold chain capex intensity:Refrigerated transport fleet expansion and blast freezing capacity require capital deployment that mid-tier renderers struggle to finance.
- Microbiological testing standard divergence:Australia's FSANZ and New Zealand's MPI maintain non-identical pathogen thresholds that complicate unified trans-Tasman production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Animal Protein Market |
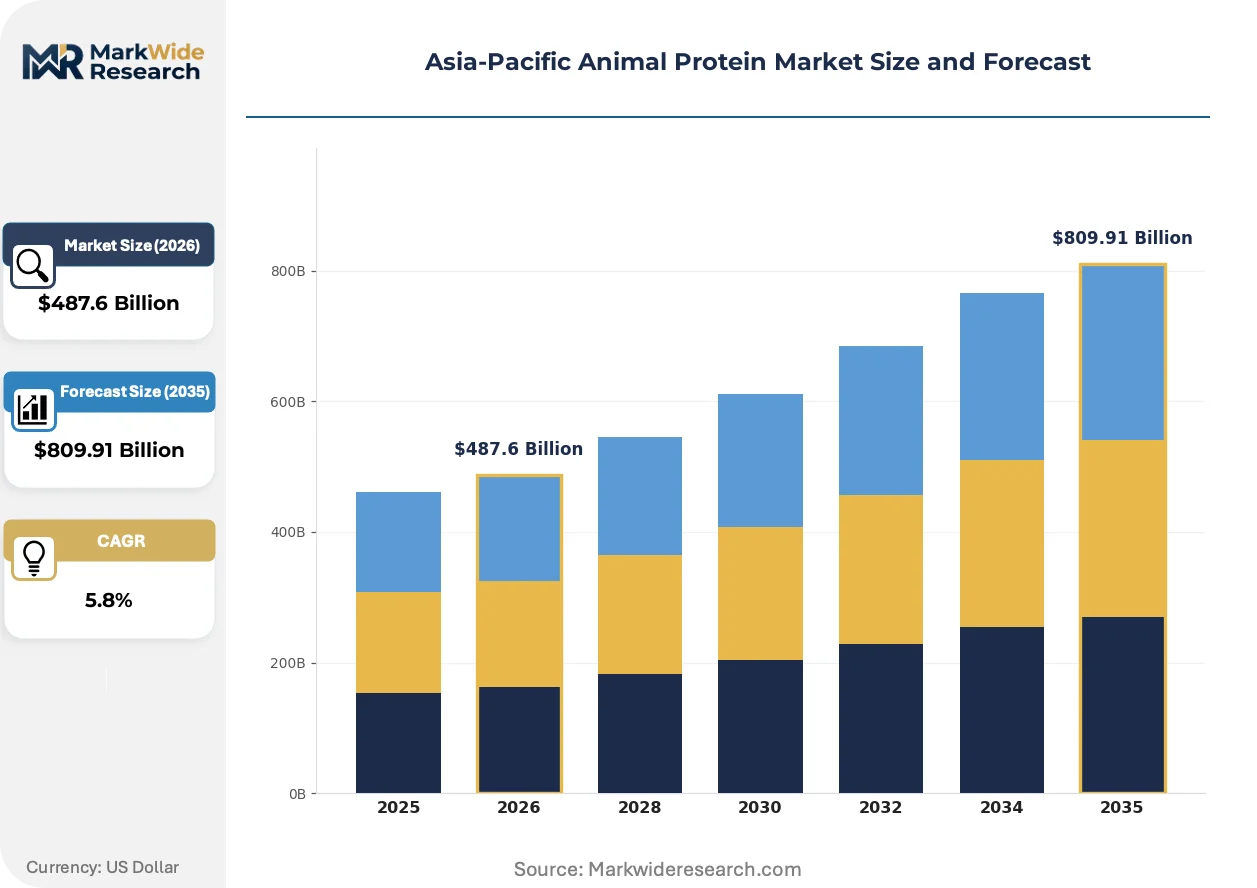
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $809.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Beef, Pork, Seafood Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Food Services, Processing Industries, Exporters Form: Fresh, Frozen, Processed, Dried |
| Companies Covered | Darling Ingredients Inc, Glanbia PLC, Arla Foods amba, Morinaga Milk Industry Co Ltd, Groupe LACTALIS, Fonterra Co-operative Group Limited, Kerry Group PLC, Nitta Gelatin Inc, Koninklijke FrieslandCampina N V, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Animal Protein Market Strategic Shifts
Protein extraction and formulation technologies are converging with digital traceability systems, reshaping how suppliers demonstrate compliance and how buyers verify provenance across fragmented Asia-Pacific supply chains.
Enzymatic hydrolysis systems are hybridizing traditional rendering with precision fractionation, enabling processors to isolate specific peptide sequences for functional applications. Japanese nutraceutical manufacturers are adopting these systems at pilot scale, with commercial deployment accelerating through 2025. The technology is hybridizing commodity protein markets into tiered ingredient categories based on bioactive peptide content rather than crude protein percentage alone.
China's SAMR enforcement of updated GB standards for contaminant limits and labeling transparency is eliminating import pathways for suppliers lacking batch-level traceability documentation. Foreign protein ingredient vendors are restructuring quality assurance protocols to accommodate unannounced facility audits and real-time laboratory data submission. Australian and New Zealand dairy protein exporters face the steepest compliance ramp, with existing China-registered facilities prioritizing capital upgrades over market expansion.
Foodservice procurement consolidation is concentrating buying power among regional quick-service restaurant chains and centralized catering operators. Traditional wet market distributors in Vietnam and the Philippines are losing share to contracted direct-supply arrangements with integrated processors. This pattern is most visible in Ho Chi Minh City and Metro Manila, where multinational chain expansion is displacing fragmented wholesale intermediaries within prepared protein categories.
Asia-Pacific Animal Protein Market Segmentation
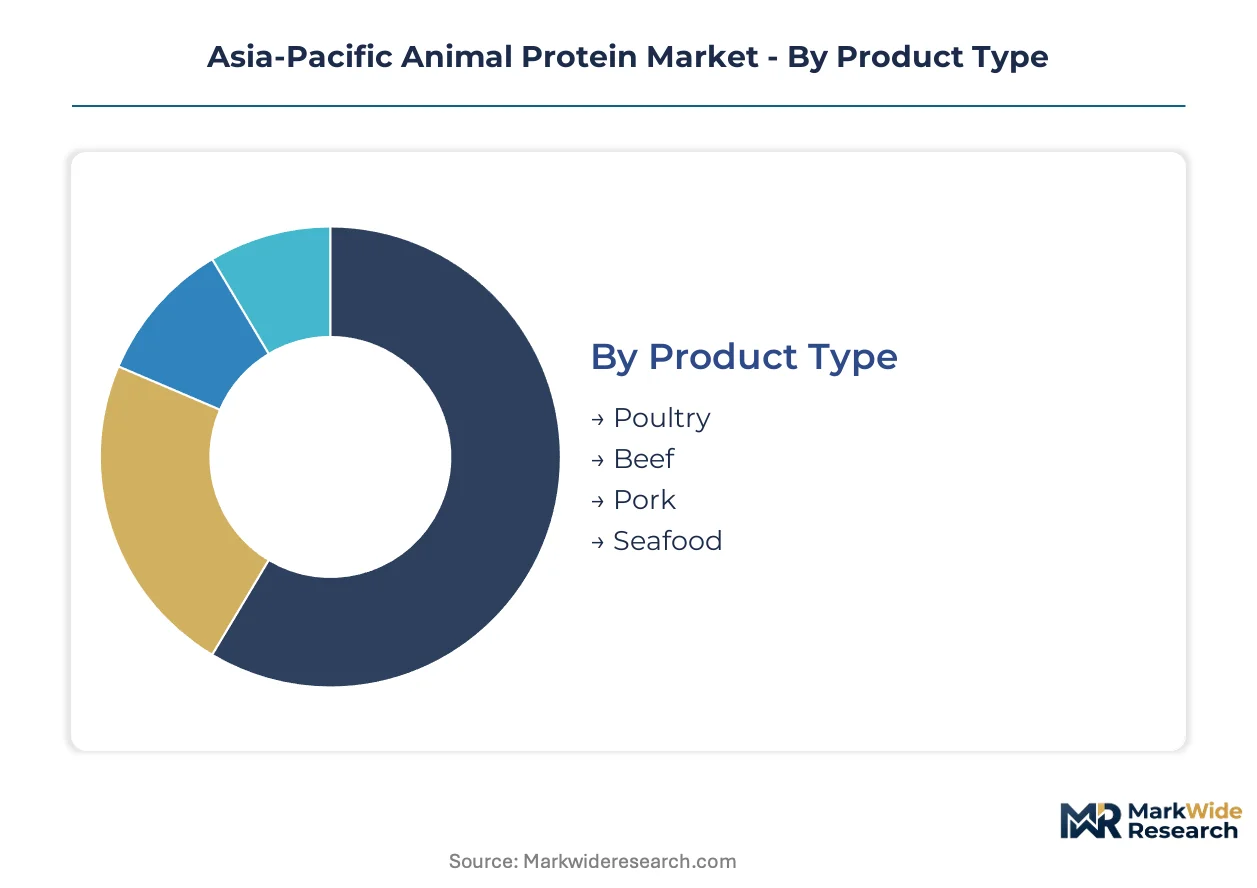
Protein sourcing configurations across Asia-Pacific diverge sharply by preservation requirements, channel access, and end-use processing intensity. Segmentation reveals where cold chain investments concentrate procurement power and which product forms command formulation premiums in functional nutrition applications.
Product Type:
Cost tier determines conversion efficiency and production cycle economics across species categories.
- Poultry:Broiler operations achieve the shortest feed-to-protein conversion cycles among land-based species. Thai and Chinese integrators dominate volume through verticalized hatch-to-processing facilities that supply quick-service restaurant chains across Southeast Asian urban corridors.
- Beef:Grass-fed and grain-finished categories sustain premium positioning in aging-demographic nutritional products. Japanese foodservice channels absorb high-marbled imports for yakiniku and shabu-shabu applications where texture specifications override price sensitivity.
- Pork:Integrated slaughter-to-render operations in Vietnam and the Philippines supply processed meat and savory flavor base applications.
- Seafood:Aquaculture-derived proteins from Vietnamese pangasius and Indonesian tilapia operations compete on cost with terrestrial alternatives in surimi and fishmeal markets.
Poultry holds installed capacity. Beef is rotating up the share rankings.
Distribution Channel:
Channel selection maps directly to buyer scale, temperature control requirements, and certification documentation burdens.
- Supermarkets:Modern retail consolidation in South Korea and urban China concentrates procurement through centralized distribution centers. Chilled cabinet space allocation favors packaged fresh and marinated proteins with visible halal or organic credentials.
- Online Retail:Frozen protein subscription models and same-day delivery platforms are capturing household volume in tier-one Chinese cities. Cold chain last-mile reliability remains the binding constraint for seafood and premium beef categories.
- Convenience Stores:Ready-to-eat protein snacks and pre-cooked bento applications drive shelf-space competition in Japanese and Taiwanese urban networks.
- Wholesale:Traditional wet market intermediaries in Vietnam and the Philippines retain share in fresh pork and poultry despite consolidation pressure from contracted direct-supply arrangements.
Wholesale retains transaction volume density. Online retail is climbing the fastest.
End User:
Customer type dictates specification stringency, from microbiological standards to functional protein concentration requirements.
- Households:Retail-packaged fresh and frozen categories dominate protein acquisition in Australian and New Zealand markets where food safety labeling transparency influences purchase decisions.
- Food Services:Quick-service restaurant chains across Indonesia, Vietnam, and the Philippines scale protein-intensive menu offerings through centralized procurement from integrated processors.
- Processing Industries:Sports nutrition manufacturers in Japan and South Korea specify whey and collagen isolates with defined peptide profiles for aging-demographic and athletic recovery formulations.
- Exporters:China-registered facilities prioritize GB standard compliance and batch-level traceability documentation to maintain SAMR import eligibility.
Processing industries command specification premiums. Food services is gaining share fastest.
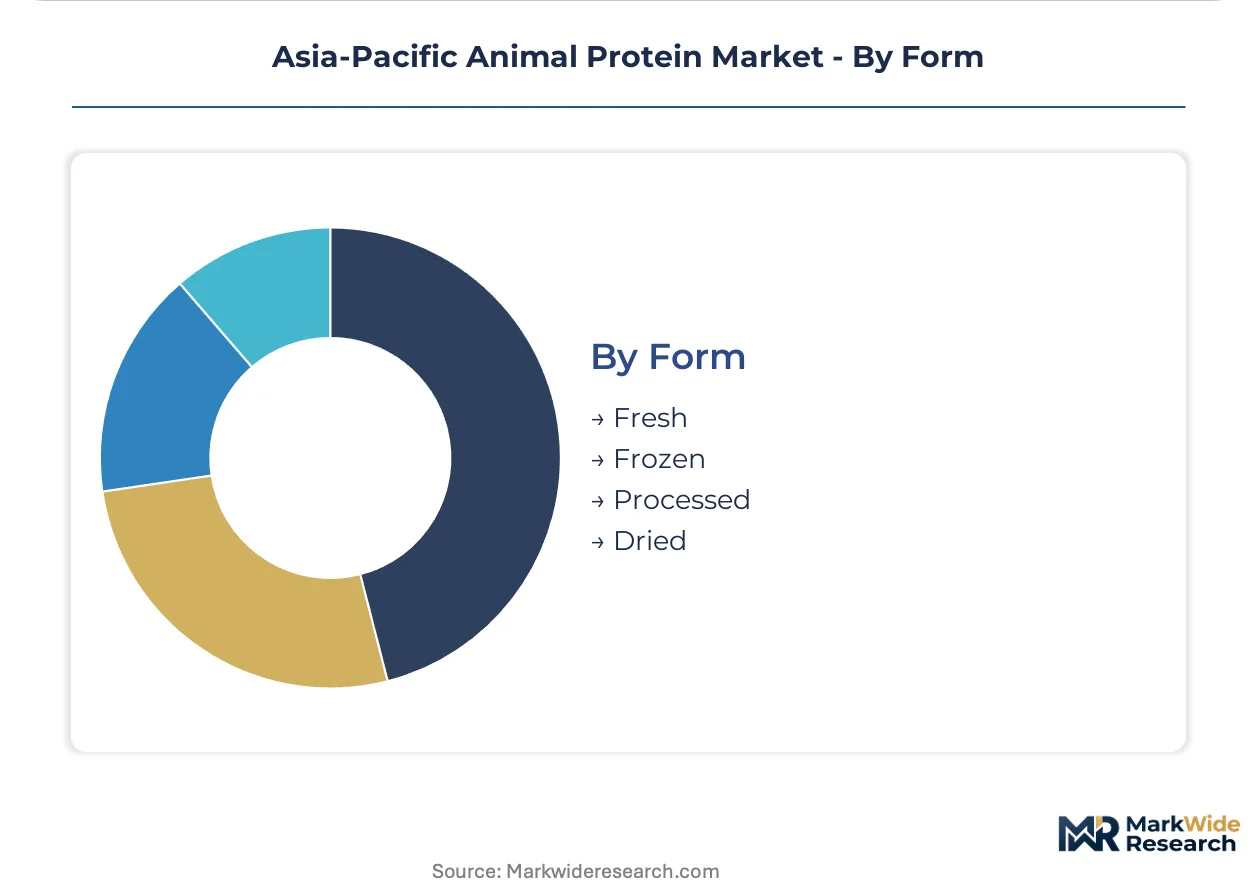
Form:
Preservation state determines shelf life, logistics cost structure, and application flexibility across the value chain.
- Fresh:Same-day slaughter-to-retail distribution dominates premium poultry and pork in Thai and Vietnamese wet markets where texture and color visibility drive purchase decisions.
- Frozen:Blast-frozen beef and seafood sustain extended supply chains from Australian and New Zealand processing facilities to Chinese and Japanese import channels.
- Processed:Emulsified and extruded protein formats serve clean-label formulation partnerships with regional quick-service restaurant chains seeking synthetic additive replacement.
- Dried:Low-moisture protein concentrates and hydrolyzed peptides support shelf-stable nutritional supplement applications across Japanese and South Korean markets.
Frozen maintains infrastructure lock-in. Processed is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japanese functional nutrition formulations commands premiums that Thai commodity poultry operations cannot replicate, creating a structural asymmetry that shapes investment flows across the region.
China
Urban food service chains in Shanghai and Beijing are consolidating procurement through direct contracts with integrated processors. SAMR's updated GB standards for contaminant limits and labeling transparency are eliminating import pathways for suppliers lacking batch-level traceability documentation. Yangtze River Delta rendering facilities are prioritizing capital upgrades to maintain China-registered status over geographic expansion.
Japan
Aging-demographic nutritional products sustain premium demand for beef protein isolates with defined peptide profiles. PMDA specifications for functional protein health claims channel R&D investment toward bioactive peptide extraction systems. Kanto region nutraceutical manufacturers are adopting enzymatic hydrolysis at pilot scale, with commercial deployment accelerating through foodservice and supplement channels.
Vietnam
Quick-service restaurant expansion in Ho Chi Minh City and Hanoi is displacing traditional wet market intermediaries within prepared protein categories. Integrated slaughter-to-render operations in the Mekong Delta supply processed meat and savory flavor base applications to regional food manufacturers. Cold chain infrastructure gaps in secondary cities create first-mover opportunities for logistics investments.
Indonesia
Urban protein intake climbs in Jakarta and Surabaya as middle-class households shift from traditional markets to modern retail. MUI halal certification audit backlogs are extending product launch cycles by four to eight months, compressing margins for foreign suppliers. JAKIM requirements in neighboring Malaysia add multi-country certification burdens that favor Malaysia-Indonesia cross-border processors with unified compliance protocols.
Australia
Grass-fed beef exports to Chinese and Japanese import channels sustain extended supply chains from Queensland and New South Wales processing facilities. FSANZ coordination with New Zealand's MPI facilitates unified trans-Tasman standards, though non-identical pathogen thresholds complicate unified production runs. Dairy protein exporters face steep compliance ramps to meet SAMR enforcement priorities.
Asia-Pacific Animal Protein Market Competitive Environment
Vertically integrated dairy cooperatives and specialized protein fractionators split the market between scale-driven commodity supply and specification-premium ingredient categories. Concentration is moderate, with top-tier players controlling cold chain infrastructure and certification registrations that mid-tier renderers struggle to replicate. Three archetypes dominate: Australasian dairy-origin cooperatives with China-registered facilities, European whey and collagen specialists targeting Japanese nutraceutical channels, and Southeast Asian integrated poultry processors serving quick-service restaurant chains. Competitive moves center on halal certification pre-positioning in Indonesia and Malaysia, and enzymatic hydrolysis capacity installation for peptide isolate production.
Within the dairy-origin tier, Fonterra Co-operative Group Limited and Arla Foods amba exemplify cooperative structures with established Asia-Pacific distribution. Among specialized fractionators, Glanbia PLC occupies a position representing European whey isolate capabilities directed at sports nutrition manufacturers. Kerry Group PLC anchors the flavor-protein integration archetype, exemplifying clean-label formulation partnerships with regional foodservice chains. These three represent distinct strategic positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Darling Ingredients Inc |
| Glanbia PLC |
| Arla Foods amba |
| Morinaga Milk Industry Co Ltd |
| Groupe LACTALIS |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Nitta Gelatin Inc |
| Koninklijke FrieslandCampina N V |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta cold corridor freight lanes anchor cost dynamics that simultaneously concentrate supply power among China-registered processors and force three-tier pricing stratification across premium, standard, and economy protein tiers. Cold chain capex intensity at blast freezing nodes compresses margins for mid-tier Vietnamese and Indonesian renderers while amplifying pricing leverage for integrated Thai poultry operators and Australian grass-fed beef exporters with captive logistics assets.
Pricing Analysis
The customization-premium spread between configured-to-order peptide isolates and commodity bulk protein runs wide across Japanese nutraceutical channels versus Southeast Asian foodservice procurement. Pricing stratifies across premium, standard, and economy tiers driven by halal certification grade and volume scale commitments. Pricing pressure stems from soybean meal and fishmeal input cost volatility squeezing Thai and Vietnamese broiler margins. Quick-service restaurant chains in Jakarta and Manila exhibit acute price sensitivity while aging-demographic supplement manufacturers in Japan absorb specification premiums with minimal elasticity.
Supply Chain Analysis
Export-control regime friction around dual-use enzymatic hydrolysis equipment limits technology transfer to Japanese and South Korean peptide fractionators. Geographic supply concentrates in Thailand, China, and Australia where integrated hatch-to-processing facilities and grass-fed beef operations feed regional demand. Raw material flows draw from Argentine soybean meal, Peruvian fishmeal, and domestic corn across key producing zones. Single-source vulnerability runs through MUI and JAKIM halal certification audit backlogs extending Indonesian and Malaysian product launch cycles. Distribution runs through contracted direct-supply arrangements with multinational quick-service restaurant chains displacing traditional wet market intermediaries in Ho Chi Minh City and Metro Manila.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among regional quick-service restaurant chains and centralized catering operators across Southeast Asian metropolitan corridors, fragmenting traditional wet market intermediaries and forcing processor compliance investments that favor scaled incumbents.
For Market Incumbents: Entrench halal certification pre-positioning across Indonesia and Malaysia before MUI and JAKIM audit backlogs worsen, locking in preferential placement with modern retail and foodservice channels. Anchor cold chain infrastructure investments in Philippine secondary cities where underdeveloped logistics create first-mover capture opportunities. Defensive consolidation around enzymatic hydrolysis capacity installation counters European whey isolate specialists targeting Japanese sports nutrition manufacturers. For New Entrants and Emerging Players: Establish a beachhead in Philippine archipelago distribution where cold chain gaps in secondary cities offer logistics partnership entry points with minimal incumbent saturation. Target clean-label formulation partnerships with quick-service restaurant chains seeking synthetic additive replacement in emulsified protein applications. A certification-first go-to-market angle leveraging unified ASEAN harmonization protocols reduces multi-country compliance burdens for Malaysia-Indonesia cross-border processing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic hydrolysis capacity owners with pilot-scale bioactive peptide extraction systems commercializing through Japanese nutraceutical channels. Long-term viability over the coming decade rests on securing China-registered facility status with SAMR batch-level traceability documentation as import eligibility friction intensifies. Acquisition target archetype: Southeast Asian integrated poultry processors with verticalized hatch-to-processing assets and existing quick-service restaurant chain contracts. The signal to watch is ASEAN harmonization initiative progress reducing certification duplication costs across Malaysia-Indonesia cross-border operations.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Positioning | MUI and JAKIM audit prioritization secures preferential placement in Indonesian and Malaysian modern retail channels before backlog compression worsens. |
| Cold Chain Infrastructure Expansion | Blast freezing capacity installation in Philippine secondary cities captures first-mover advantage as urban food service procurement consolidates. |
| Enzymatic Hydrolysis Capacity Installation | Bioactive peptide extraction systems enable premium positioning in Japanese PMDA-regulated functional health claim formulations. |
| China-Registered Facility Compliance Upgrade | SAMR GB standard alignment with batch-level traceability documentation maintains import eligibility as contaminant limit enforcement tightens. |
| Clean-Label Formulation Partnership | Flavor-protein integration capabilities displace synthetic additive suppliers in regional quick-service restaurant chain supply positions. |
Study Parameters
Cross-validation between processor facility audits and foodservice procurement contract analysis anchors the qualitative findings across the Asia-Pacific animal protein value chain. Primary interviews with rendering plant managers, quick-service restaurant chain procurement directors, halal certification body auditors, cold chain logistics operators, and sports nutrition formulation scientists combined with secondary validation from SAMR GB standard filings, ASEAN trade harmonization protocols, customs and cold chain investment records, and PMDA functional food registration databases. Bottom-up capacity utilization modeling and top-down consumption elasticity estimates triangulate volume and value outputs.
Calibration against historical protein price volatility patterns and cold chain capex deployment cycles refines projection reliability across the modeling period. Segmentation dimensions include species category, preservation state, distribution channel, end-user specification tier, and regional regulatory cluster. CAGRs derive from elasticity-adjusted consumption trajectories and capacity expansion pipelines. Forecast inputs incorporate feed input cost correlation models and halal certification timeline compression effects on product launch velocity.
Sensitivities concentrate around SAMR enforcement intensity on contaminant limits, MUI-JAKIM audit capacity expansion, and ASEAN harmonization initiative implementation pace. Cross-checking against FAO protein consumption statistics and cold chain infrastructure investment tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Tarragon Market