
 Global Coco Peat Market | 2026-2036
Global Coco Peat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coco Peat Market Analysis
RHP certification for horticultural substrates is bifurcating the competitive landscape between qualified exporters and commodity traders. Dutch Plantin leverages its RHP-accredited processing facilities near Rotterdam to control quality-sensitive European channels. Kumaran Coirs anchors South Indian supply through integrated washing and buffering operations in Tamil Nadu. Sai Cocopeat differentiates via specialized low-EC formulations targeting hydroponic tomato and cucumber growers in the Netherlands and Spain.
Coco peat is the fibrous husk residue of coconut processing, typically holding eight to ten times its dry weight in water while maintaining aeration porosity above 70 percent; manufacturers wash, buffer, and compress this material into standardized bricks, blocks, or loose fill for soilless cultivation systems. Bricks and blocks dominate export logistics due to compression ratios that reduce container freight costs by over half versus loose material. Hydroponics represents the fastest-expanding application segment as greenhouse operators replace rock wool with biodegradable coir slabs, while fiber grades command premium positioning in orchid and bromeliad propagation where drainage velocity determines root health outcomes.
REACH compliance in Europe restricts chemical loading in imported substrates, while India's APEDA export protocols mandate moisture and impurity thresholds for coir pith shipments. The EU F-Gas Regulation indirectly bolsters coir demand by pressuring energy-intensive greenhouse heating, pushing growers toward substrate systems that improve water-use efficiency and reduce climate control loads. Stakeholders must monitor buffer capacity standardization across origin countries, as inconsistent calcium and magnesium treatment rates create crop failure risks that could trigger buyer recertification requirements or origin switching.
Market Dynamics
The EU Green Deal's soil health directives are compressing demand timelines for peat moss alternatives, forcing substrate buyers to recertify supply chains around renewable media with verified carbon footprints and buffer-standardized chemistry.
Growth Catalysts
- REACH substrate compliance:European chemical loading restrictions on imported growing media are disqualifying peat suppliers, opening procurement channels to RHP-certified coir processors with documented heavy-metal thresholds.
- Hydroponic greenhouse expansion:Commercial vegetable producers in the Netherlands and Spain are replacing rock wool slabs with biodegradable coir substrates to reduce disposal costs and improve water-use efficiency.
- F-Gas Regulation pressure:EU restrictions on energy-intensive greenhouse heating are pushing growers toward substrate systems that reduce climate control loads through superior moisture retention.
Market Restraints
- Input cost volatility:Coconut husk availability fluctuates with monsoon patterns in Tamil Nadu and Kerala, compressing processor margins during drought cycles.
- Supply concentration risk:Over half of global washing and buffering capacity sits within 200 kilometers of Coimbatore, creating single-point vulnerability to regional logistics disruptions.
- Substitution threat from peat alternatives:Wood fiber substrates and composted bark are capturing price-sensitive ornamental growers in Eastern Europe.
Strategic Opportunities
- Underpenetrated specialty floriculture:Orchid and bromeliad propagators in Japan represent a premium segment demanding high-drainage fiber grades with customized porosity profiles.
- Regulatory tailwind from CSRD disclosure rules:Corporate sustainability reporting mandates are forcing European agribusinesses to document Scope 3 emissions, favoring substrates with certified renewable sourcing.
- Technology convergence of sensor-integrated substrates:Embedding moisture and EC probes directly into coir blocks is enabling precision irrigation feedback loops for automated greenhouse systems.
Industry Challenges
- Certification timeline compression:RHP accreditation requires 18-24 months of facility audits and product testing, delaying market entry for new processors.
- Buffer chemistry standardization gaps:Inconsistent calcium and magnesium treatment rates across Indian and Sri Lankan origin points create crop failure risks that trigger buyer recertification demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coco Peat Market |
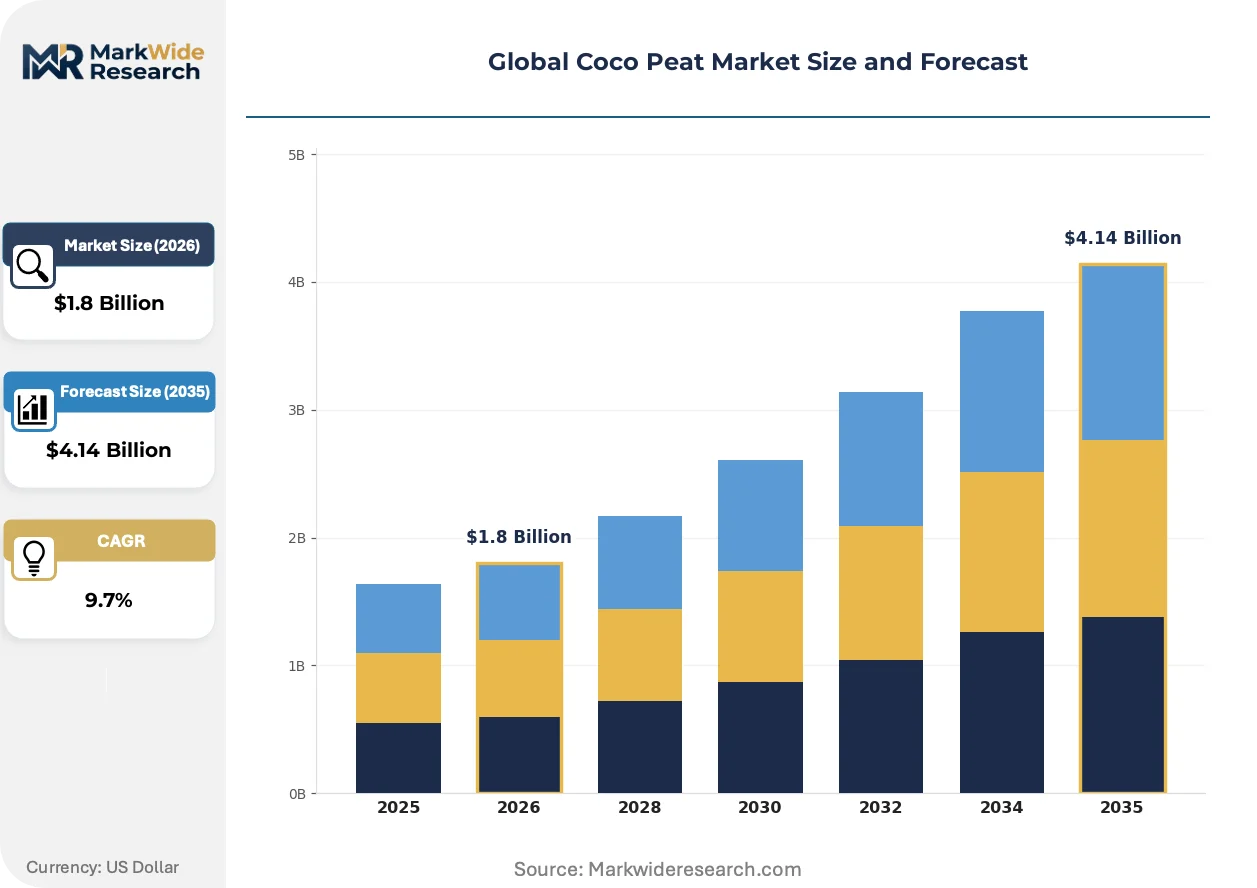
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bricks, Blocks, Pellets, Fiber Application: Agriculture, Horticulture, Landscaping, Hydroponics Form: Dried, Compressed, Loose, Loose Fill End User: Farmers, Nurseries, Greenhouses, Retailers |
| Companies Covered | Kumaran Coirs, Allwin Coir, Dutch Plantin, CoirGreen, Dynamic International, Samarasinghe Brothers, SMS Exporters, Benlion Coir Industries, Sai Cocopeat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coco Peat Market Emerging Trajectories
Substrate chemistry standardization and embedded sensing capabilities are reshaping how greenhouse operators evaluate growing media, shifting procurement criteria from bulk cost to performance-verified outcomes.
Automated buffering lines with real-time ion-exchange monitoring are decomposing the historical advantage of manual washing operations. Dutch processing facilities near Rotterdam are adopting these systems to guarantee EC stability within 0.2 mS/cm across batch runs. The technology is decomposing price competition based on labor arbitrage, compressing margins for processors without capital-intensive automation.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in soil improvers are tightening acceptable thresholds for imported substrates. ECHA enforcement actions against non-compliant peat moss shipments are redirecting buyer audits toward coir suppliers with third-party contaminant testing. Hydroponic tomato and cucumber growers in Almeria are responding by mandating batch-specific lab reports for every container load.
Direct contracting between greenhouse consortia and origin-country processors is shortening traditional distribution hierarchies. Dutch grower cooperatives are establishing volume commitments with Tamil Nadu washing facilities, bypassing Rotterdam traders. This pattern is most visible in the Netherlands, where Rijk Zwaan and other propagation specialists are building captive supply relationships to secure buffer-standardized product.
Global Coco Peat Market Segmentation
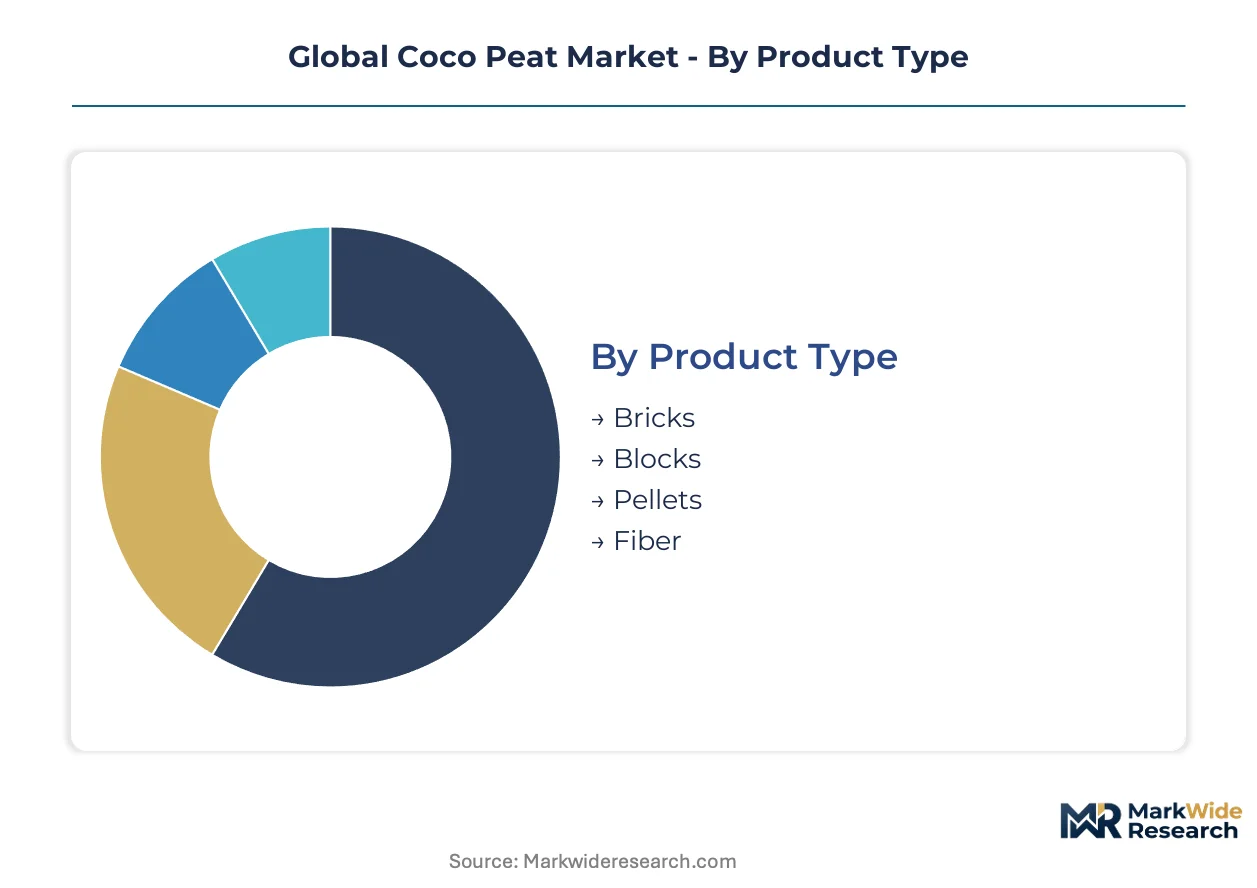
Product configuration determines freight economics and application suitability across the coco peat value chain. Compression ratios and moisture content specifications create distinct procurement patterns between bulk agricultural buyers and precision horticulture operators.
Product Type:
Bricks and blocks dominate containerized export flows from Tamil Nadu and Kerala processing clusters, while fiber grades serve specialized domestic propagation markets.
- Bricks:Rectangular compressed units with 5:1 volume reduction enable cost-efficient maritime freight from Indian ports to Rotterdam and Almeria. Dutch greenhouse consortia specify brick dimensions for automated slab production lines.
- Blocks:Larger format substrates with customized porosity profiles command premium positioning in hydroponic tomato operations across the Netherlands and Spain. Block compression density varies by destination humidity conditions.
- Pellets:Rapid-expansion discs target retail garden center distribution in Germany and France.
- Fiber:High-drainage grades serve orchid propagators in Japan and bromeliad specialists in Florida.
Bricks command the established base. The steepest expansion runs through blocks.
Application:
End-use requirements differentiate buffer chemistry specifications and certification thresholds across buyer segments.
- Agriculture:Field crop amendment applications in India's coconut belt utilize unwashed low-grade material with minimal processing overhead.
- Horticulture:Commercial nursery operations in Italy and Poland drive demand for RHP-certified buffered substrates with documented heavy-metal compliance under REACH Annex XVII.
- Landscaping:Municipal greening projects across Gulf Cooperation Council cities specify salt-buffered grades for desert soil amendment.
- Hydroponics:Soilless vegetable producers in Almeria and the Netherlands are displacing rock wool with biodegradable coir slabs that reduce disposal costs and improve water-use efficiency metrics under EU F-Gas Regulation pressure.
Horticulture anchors volume concentration. Hydroponics is gaining share fastest.
Form:
Moisture content and compression state determine shelf stability and reconstitution labor requirements at point of use.
- Dried:Oven-reduced moisture below 15 percent enables extended storage for seasonal agricultural procurement in India's monsoon-dependent supply cycles.
- Compressed:Hydraulic-pressed formats with 80 percent air removal minimize container cube utilization for transoceanic shipments to European distribution hubs.
- Loose:Uncompressed pith serves immediate-application landscaping contractors in Saudi Arabia and UAE with high-volume, low-frequency purchasing patterns.
- Loose Fill:Aerated bagged material targets hobbyist retailers requiring minimal reconstitution effort.
Compressed forms dominate export value. Loose fill shows the steepest expansion trajectory.
End User:
Procurement scale and technical sophistication create distinct channel structures from origin processors to final application.
- Farmers:Smallholder coconut cultivators in Kerala and Karnataka utilize on-farm coir pith for soil conditioning with minimal value-add processing.
- Nurseries:Commercial propagation specialists in Japan and Taiwan specify fiber-grade porosity profiles for epiphytic plant root health outcomes.
- Greenhouses:Dutch and Spanish vegetable producers mandate batch-specific EC documentation and buffer-standardized chemistry for automated irrigation systems.
- Retailers:Garden center chains in Germany and France source branded pellet formats for consumer convenience positioning.
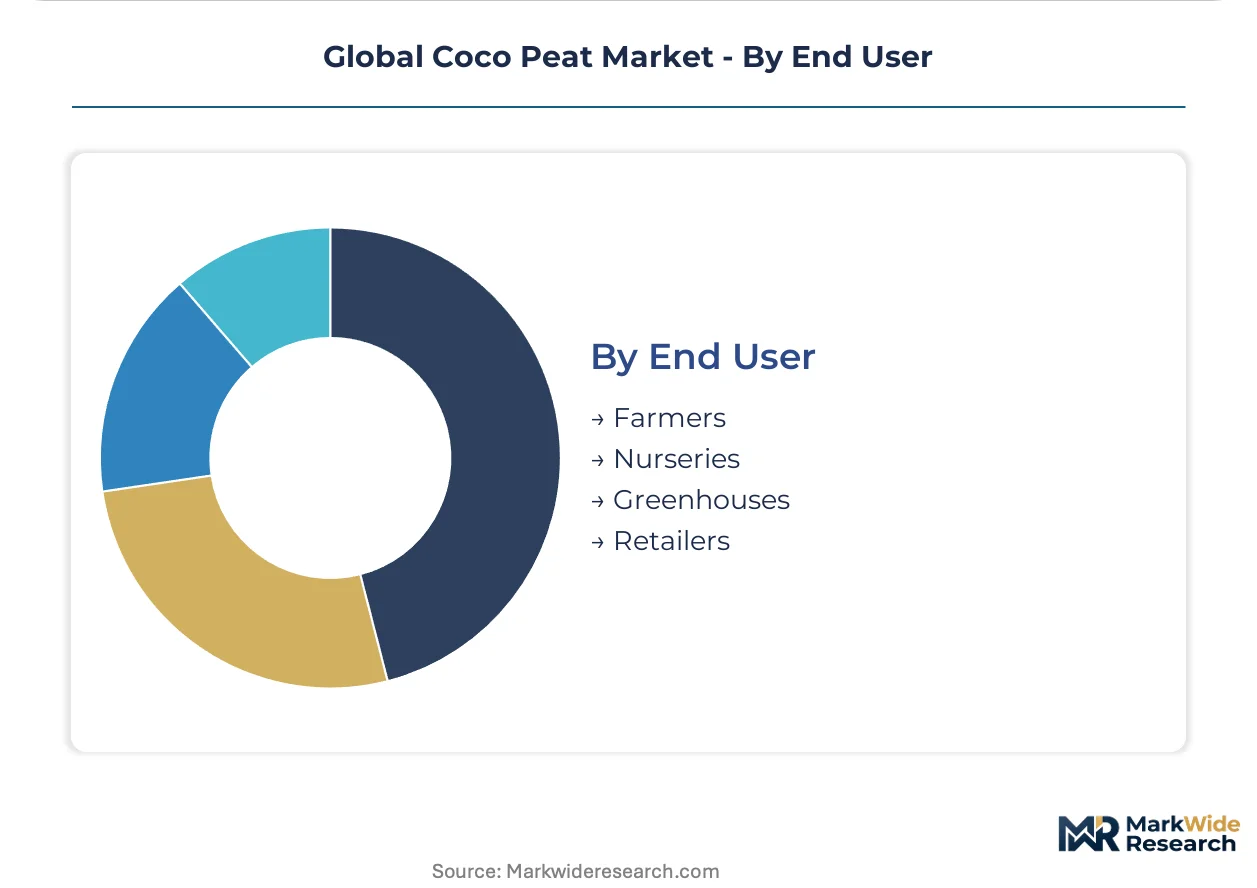
Greenhouses command the established base. Retailers show the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation pressure on greenhouse heating costs is accelerating substrate substitution patterns across commercial horticulture clusters. REACH Annex XVII enforcement against peat moss contaminants is redirecting procurement audits toward RHP-certified coir suppliers with documented heavy-metal thresholds. Dutch distribution gateways near Rotterdam control quality-sensitive European channels.
Netherlands
Almeria-style hydroponic tomato and cucumber growers mandate batch-specific EC documentation for automated irrigation systems. Dutch Plantin leverages RHP-accredited processing facilities near Rotterdam to buffer-standardized chemistry for greenhouse consortia. Direct contracting between grower cooperatives and Tamil Nadu washing facilities is shortening traditional distribution hierarchies.
Spain
Andalusian greenhouse operators are displacing rock wool with biodegradable coir slabs to reduce disposal costs under EU circular economy directives. Almeria province concentrates the Mediterranean basin's most intensive hydroponic vegetable production. Spanish buyers now require third-party contaminant testing aligned with ECHA enforcement patterns against non-compliant peat shipments.
India
APEDA export protocols mandate moisture and impurity thresholds for coir pith shipments from Tamil Nadu and Kerala processing clusters. Coimbatore anchors over half of global washing and buffering capacity within a 200-kilometer radius. Monsoon-dependent coconut husk availability creates seasonal input cost volatility compressing processor margins.
Germany
Garden center retail chains in Bavaria and North Rhine-Westphalia source branded pellet formats for consumer convenience positioning. CSRD disclosure rules are forcing agribusinesses to document Scope 3 emissions, favoring substrates with certified renewable sourcing. German procurement patterns increasingly prioritize batch-specific lab reports for every container load.
Japan
Orchid and bromeliad propagators in the Kanto region demand high-drainage fiber grades with customized porosity profiles. Japanese nursery operations specify fiber-grade drainage velocity thresholds determining epiphytic plant root health outcomes. METI-supported precision agriculture initiatives are embedding moisture and EC probes into imported coir blocks.
Global Coco Peat Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions. The vendor base separates into RHP-accredited processors controlling European quality channels and commodity traders serving price-sensitive agricultural amendment markets. Three archetypes dominate: integrated origin-country processors with captive washing capacity, Rotterdam-based distribution specialists with buffer-standardization technology, and fiber-grade specialists targeting premium floriculture segments. Competitive moves concentrate on backward integration into coconut husk sourcing and automated buffering line deployment.
Within the integrated processing tier, Kumaran Coirs anchors South Indian supply through Tamil Nadu washing and buffering operations, while Dutch Plantin exemplifies the European distribution specialist archetype with Rotterdam-adjacent facilities. Sai Cocopeat occupies a position among formulation specialists developing low-EC grades for hydroponic vegetable producers. These three represent distinct capability configurations: origin-country vertical control, destination-market quality assurance, and application-specific chemistry customization.
| Leading Market Players |
|---|
| Kumaran Coirs |
| Allwin Coir |
| Dutch Plantin |
| CoirGreen |
| Dynamic International |
| Samarasinghe Brothers |
| SMS Exporters |
| Benlion Coir Industries |
| Sai Cocopeat |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Dutch greenhouse consortia and Tamil Nadu washing facilities lock in both supply access and price visibility, insulating buyers from monsoon-driven coconut husk volatility while compressing margins for processors without RHP accreditation.
Pricing Analysis
Certification level creates the primary spread, with RHP-accredited buffered substrates commanding premium positioning over unwashed commodity grades. Three-tier pricing structure across premium certified, standard buffered, and economy unwashed levels reflects divergent compliance costs and quality assurance investments. Price differentiation stems from REACH Annex XVII testing documentation and automated ion-exchange monitoring systems that guarantee EC stability. Cost compression in the economy tier is intensifying because wood fiber substitutes capture price-sensitive ornamental buyers in Eastern Europe. Smallholder field crop amendment users in India's coconut belt exhibit highest price sensitivity, while Dutch hydroponic tomato producers prioritize batch-specific chemistry documentation over unit cost.
Supply Chain Analysis
India and Sri Lanka anchor global washing and buffering capacity, with over half concentrated within 200 kilometers of Coimbatore. The supply chain draws from coconut husk feedstock, calcium and magnesium buffering agents, and automated compression equipment. Single-source vulnerability to regional logistics disruptions in Tamil Nadu monsoon cycles poses structural risk. Distribution runs through Rotterdam-adjacent processing facilities controlled by European distribution specialists, with direct contracting patterns shortening traditional trader hierarcharies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates entry niches as EU F-Gas Regulation pressure forces substrate buyers to recertify supply chains around renewable media with verified carbon footprints.
For Market Incumbents: Shield RHP-accredited market position by accelerating backward integration into coconut husk sourcing in Kerala and Karnataka, and deploy automated buffering lines with real-time ion-exchange monitoring to neutralize labor arbitrage advantages. Wood fiber substitution threats in Eastern Europe ornamental markets demand proactive buffer chemistry standardization investments. For New Entrants and Emerging Players: Embedded sensor-integrated substrate development represents an under-served service layer where incumbents under-invest, creating white-space for precision agriculture technology convergence. Target Japanese orchid propagators demanding customized porosity fiber grades with drainage velocity specifications. Partner with METI-supported precision agriculture initiatives to accelerate moisture and EC probe integration into coir blocks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated origin-country processors with captive washing capacity and existing APEDA export protocol compliance, positioned to capture direct contracting trends bypassing Rotterdam traders. Long-term viability rests on buffer-standardization technology ownership rather than commodity trading relationships. Monitor ECHA enforcement action patterns against non-compliant peat moss shipments as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Husk Sourcing | Captive feedstock supply in Kerala insulates processors from monsoon-driven input cost volatility. |
| Automated Buffering Line Deployment | Real-time ion-exchange monitoring guarantees EC stability within 0.2 mS/cm for Dutch greenhouse consortia. |
| RHP Accreditation Investment | Eighteen-month facility audit timeline creates defensive moat against commodity trader competition. |
| Direct Contracting with Greenhouse Cooperatives | Volume commitments with Almeria and Netherlands growers bypass Rotterdam distribution margins. |
| Sensor-Integrated Substrate Development | Embedding moisture and EC probes enables precision irrigation feedback loops for automated greenhouse systems. |
Methodological Framework
Cross-validation between primary interviews with substrate procurement managers at Dutch greenhouse consortia and secondary analysis of APEDA export protocol filings anchors the qualitative findings. Conversations with Tamil Nadu washing facility operators, Rotterdam distribution specialists, and Japanese orchid propagators combined with REACH Annex XVII enforcement records, EU F-Gas Regulation implementation documents, and customs trade data. Bottom-up processor capacity estimates and top-down end-use demand modeling provide triangulation.
Sensitivity analysis across product configuration, application segment, and geographic demand clusters shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application, form, and end user, with regional regulatory framework as an additional industry-specific dimension. CAGRs derive from volume trajectory analysis calibrated against substitution elasticity parameters and certification penetration curves. Forecast inputs incorporate monsoon pattern correlation with coconut husk availability and RHP accreditation facility expansion timelines.
Underlying assumptions cover stable EU Green Deal implementation trajectory and REACH enforcement continuity, with deviation risk concentrated in buffer chemistry standardization gaps across Indian and Sri Lankan origin points. Forecasts reflect these conditions with revision triggers tied to regulatory recalibration or technology disruption events. Recalibration cycles align with material shifts in ECHA enforcement patterns and CSRD disclosure rule implementation phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
GCC Poultry Meat Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Ginseng Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Malaysia Floriculture Market