
 Fermented Soybean Meal Protein for Animal Feed Market | 2026-2036
Fermented Soybean Meal Protein for Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Soybean Meal Protein for Animal Feed Market Insights
Modular premix-to-complete-feed bundling is recalibrating procurement patterns across integrated livestock operations. ADM leverages its North American oilseed processing footprint to secure consistent substrate supply for fermentation partners. CJ BIO anchors volume leadership through captive bioreactor capacity in Southeast Asian feed corridors. Lallemand Inc. specializes in strain-specific fermentation protocols that differentiate finished meal digestibility profiles for swine and poultry integrators.
Fermented soybean meal protein denotes soy substrate transformed via controlled microbial fermentation to elevate amino acid bioavailability, reduce anti-nutritional factors, and standardize crude protein content typically between 50% and 55% for ration formulation precision. Its primary commercial purpose centers on displacing fishmeal and unfermented soy fractions in species-specific diets where protein digestibility directly governs feed conversion ratios. Defatted soybean meal captures the dominant volume position owing to lower oil interference with microbial substrate penetration and subsequent amino acid standardization. Aquaculture feed represents the fastest-growing application as marine ingredient substitution accelerates among shrimp and salmonid producers facing finite wild-catch supply.
China's MIIT enforces GB standards on fermented feed additive production that dictate strain registration, contamination thresholds, and facility hygiene protocols for domestic manufacturers. The EU F-Gas Regulation and REACH framework constrain solvent-based extraction alternatives, indirectly channeling European compounders toward biological upgrading of oilseed meals. The USDA and FDA jointly oversee GRAS notifications and facility inspections for imported fermented protein entering US feed channels. Stakeholders must monitor divergence between Asian fermentation strain approval pathways and Western veterinary feed directive compliance to avoid cross-border shipment rejections.
Market Dynamics
China's zero-antibiotic livestock policies and GB standards enforcement are compressing fermentation substrate quality tolerances, forcing feed compounders to upgrade bioprocessing infrastructure or exit contract supply chains serving export-oriented integrators.
Growth Catalysts
- Defatted substrate standardization:Lower oil content enables deeper microbial penetration and amino acid profile consistency, accelerating adoption among Vietnamese and Indonesian aquaculture feed producers seeking fishmeal alternatives.
- EU F-Gas Regulation constraints:Solvent-based extraction alternatives face tightening restrictions, indirectly channeling European compounders toward biological upgrading of oilseed meals.
- East Asian coastal aquaculture zones:Contract growers face mounting pressure from export-market veterinary residue rules, concentrating demand for certified fermented protein in Vietnam, Indonesia, and coastal China.
Market Restraints
- Input cost volatility:Soybean meal prices fluctuate with North American oilseed harvests and crushing capacity utilization, compressing fermentation facility margins.
- Strain registration bottlenecks:China's MIIT bioprocessing standards require facility-by-facility approvals, creating multi-quarter delays for new fermentation entrants.
- Technical digestibility variance:Inconsistent protease activity across fermentation batches forces feed formulators to maintain wider safety margins in ration design.
Strategic Opportunities
- Underpenetrated salmonid segments:Norwegian and Chilean producers remain tethered to marine ingredients, presenting conversion potential as fermentation scale achieves cost parity.
- Regulatory tailwind from USDA-FDA alignment:Streamlined GRAS notification pathways for imported fermented proteins reduce cross-border shipment friction for qualified suppliers.
- Modular premix bundling:Integrated livestock operations seek single-source complete-feed procurement, creating channel consolidation opportunities for fermentation-capable compounders.
Industry Challenges
- Bioreactor operator scarcity:Fermentation facilities require trained personnel capable of monitoring pH, temperature, and microbial viability across multi-day batch cycles, with limited vocational pipeline in Southeast Asian feed corridors.
- Certification timeline compression:Export-market veterinary residue rules demand lot-level traceability documentation, forcing smaller fermentation facilities to invest in laboratory infrastructure or lose contract eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Soybean Meal Protein for Animal Feed Market |
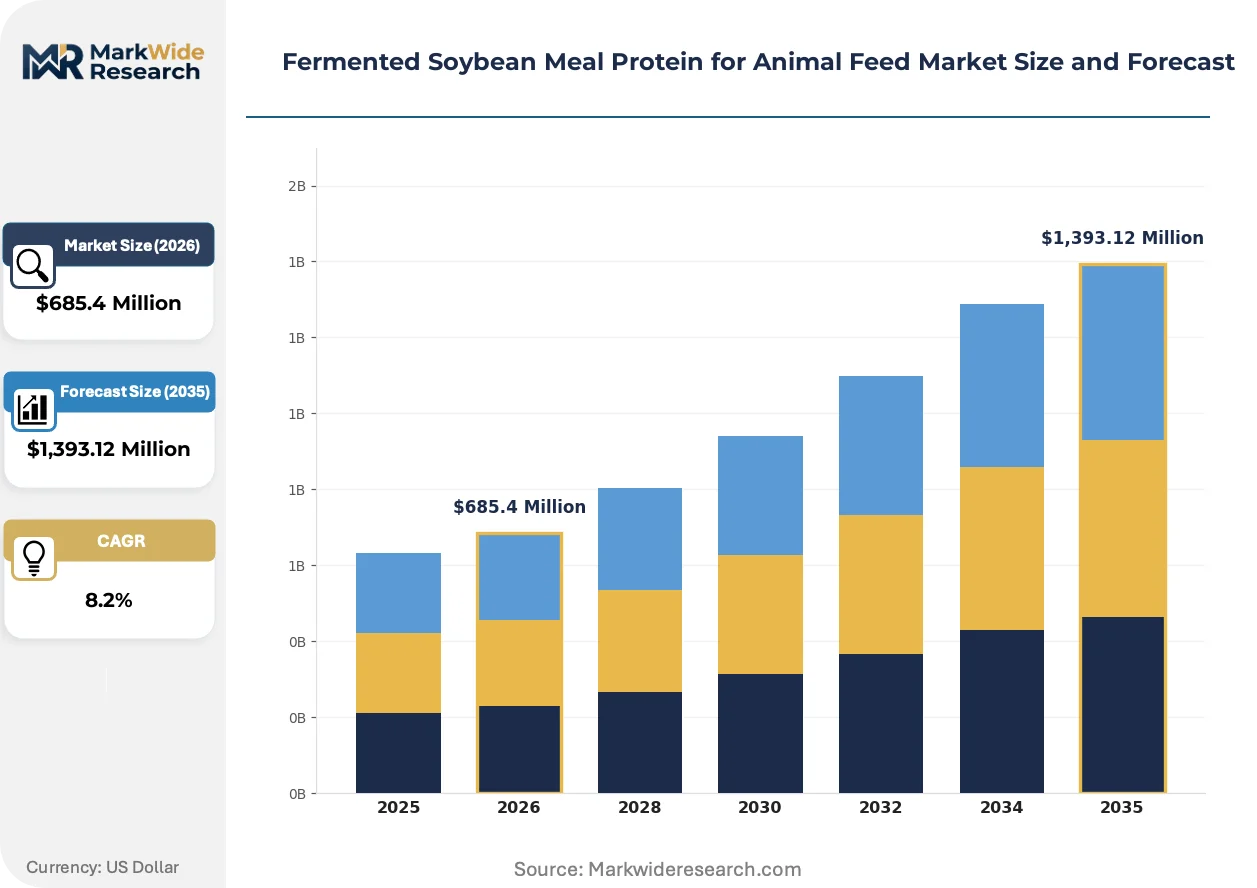
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Fat Soybean Meal, Defatted Soybean Meal, Isolate Protein, Concentrate Protein Application: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Formulation Type: Complete Feed, Supplementary Feed, Premix, Textured Protein Packaging Type: Bags, Bulk Containers, Drums, Totes |
| Companies Covered | ADM, CJ BIO, Wilmar Group, Cargill, InnovaFeed, Angel Yeast, Lallemand Inc., dsm-firmenich, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Soybean Meal Protein for Animal Feed Market Trends and Innovations
Controlled microbial fermentation protocols are advancing from batch consistency improvements toward strain-specific customization, enabling finished meal digestibility profiles tailored to species-specific feed conversion optimization.
Solid-state fermentation systems is converging with automated moisture and temperature control platforms, enabling precise management of anti-nutritional factor degradation. Swine and poultry integrators in China's Shandong and Guangdong provinces are piloting these integrated systems. The technology is converging with real-time sensor networks to compress batch-to-batch protein variability from historical ranges of 4-5 percentage points down to sub-2-point deviation bands.
REACH framework constraints on chemical processing inputs continue tightening across European Union member states, elevating biological upgrading pathways relative to solvent extraction alternatives. Compound feed manufacturers in Germany and the Netherlands face elevated compliance documentation burdens. Aquaculture feed segments serving export-certification markets are responding by dual-sourcing from fermentation facilities holding both EU and Asian regulatory registrations.
Integrated livestock operations are consolidating premix-to-complete-feed procurement under single-source contracts, displacing fragmented ingredient purchasing. Large-scale poultry and swine integrators in Vietnam's Mekong Delta and Indonesia's Java corridor now specify fermented protein inclusion rates directly in grower contracts. This consolidation is most visible among export-oriented operations supplying EU and Japanese retail channels where veterinary residue documentation requirements cascade backward through supply tiers.
Fermented Soybean Meal Protein for Animal Feed Market Segmentation
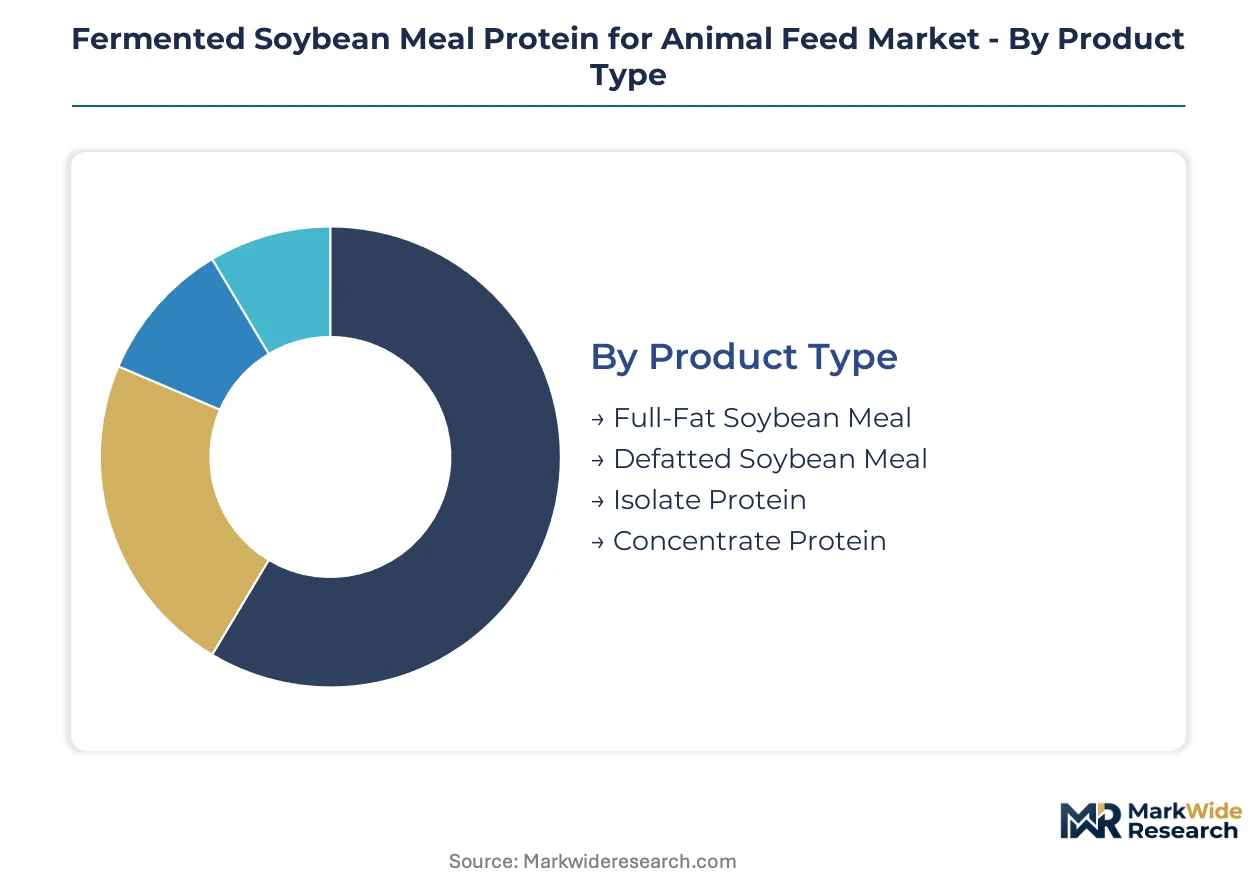
Segmentation in fermented soybean meal protein markets tracks how substrate oil content, species-specific digestibility requirements, and procurement bundling preferences reshape supplier-customer relationships across feed manufacturing tiers.
Product Type:
Buyers prioritize oil interference levels and amino acid standardization precision when selecting fermented substrate grades.
- Defatted Soybean Meal:Lower residual oil content permits deeper microbial penetration during fermentation, yielding crude protein consistency between 50% and 55%. Vietnamese and Indonesian aquaculture feed producers are scaling purchases to displace fishmeal in shrimp and salmonid diets.
- Full-Fat Soybean Meal:Retains natural oil content that complicates microbial substrate access and amino acid profile standardization. Poultry integrators in China's Shandong province utilize full-fat variants for energy-dense broiler rations where oil content substitutes for separate lipid additives.
- Isolate Protein:Highly refined protein fraction exceeding 90% purity serves specialty premix formulations requiring precise amino acid fortification.
- Concentrate Protein:Intermediate refinement grade bridges standardization needs between full meals and isolates for mid-tier compounders.
Defatted soybean meal leads on scale; isolate protein leads on momentum.
Application:
Species-specific feed conversion optimization dictates fermentation protocol selection and supplier certification requirements.
- Aquaculture Feed:Marine ingredient substitution accelerates among shrimp and salmonid producers facing finite wild-catch supply and export-market veterinary residue documentation mandates. Coastal contract growers in Vietnam, Indonesia, and China concentrate procurement of certified fermented protein.
- Poultry Feed:Broiler and layer integrators leverage fermented meal to reduce anti-nutritional factor loads in high-density housing systems. China's zero-antibiotic livestock policies compress substrate quality tolerances for export-oriented operations.
- Swine Feed:Nursery and grower-finisher phases utilize fermented protein to improve ileal digestibility and gut health markers.
- Ruminant Feed:Dairy and beef operations incorporate fermented soy as bypass protein sources, though rumen microbial degradation limits premium pricing capture relative to monogastric applications.
Aquaculture feed climbs the fastest; poultry feed holds the largest installed base.
Formulation Type:
Procurement consolidation toward single-source complete-feed contracts reconfigures ingredient supplier access channels.
- Complete Feed:Fully formulated rations delivered ready-to-use dominate integrated livestock operations seeking to displace fragmented ingredient purchasing. Vietnam's Mekong Delta and Indonesia's Java corridor poultry integrators now specify fermented protein inclusion rates directly in grower contracts.
- Premix:Concentrated vitamin-mineral-protein blends require precise fermentation batch consistency to maintain formulation integrity across dilution ratios.
- Supplementary Feed:Top-dressing or ration-balancing products serve smaller operations lacking on-site formulation capabilities.
- Textured Protein:Extruded or flaked forms enhance palatability and intake consistency in high-performance genetic lines.
Complete feed commands volume concentration; premix retains margin premium.
Packaging Type:
Logistics infrastructure maturity and lot-level traceability requirements determine containerization preferences across supply tiers.
- Bulk Containers:Tanker and silo delivery minimizes per-unit handling costs for large-scale compounders with dedicated intake infrastructure.
- Bags:25-50kg woven polypropylene sacks dominate mid-tier feed mills and distributor networks across Southeast Asian feed corridors.
- Totes:Intermediate bulk containers bridge bag and bulk formats for operations lacking pneumatic unloading systems.
- Drums:Sealed steel or plastic drums serve specialty premix manufacturers requiring contamination control for high-value fermentation batches.
Bulk containers minimize unit economics; bags maximize channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale fermentation of soybean meal for animal protein traces its commercial roots to East Asian aquaculture expansion during the 1990s, when Vietnamese and Indonesian shrimp producers first piloted microbially processed soy as fishmeal replacement.
China
Zero-antibiotic livestock policies and MIIT GB standards enforcement are compressing substrate quality tolerances for domestic fermentation facilities. Shandong and Guangdong provinces host the densest concentration of integrated bioreactor operations serving poultry and swine integrators. Export-oriented contract growers in these coastal clusters now require lot-level traceability documentation to maintain EU and Japanese retail channel eligibility.
Vietnam
Mekong Delta aquaculture feed producers are scaling defatted fermented meal purchases to reduce dependence on volatile fishmeal supplies. The country's national agricultural regulator enforces veterinary residue documentation requirements that cascade backward through shrimp and pangasius supply chains. Can Tho and An Giang provinces concentrate the highest density of fermentation-capable compounders serving export-certification markets.
Indonesia
Java corridor poultry integrators specify fermented protein inclusion rates directly in grower contracts for operations supplying EU retail channels. National feed safety standards align with MIIT bioprocessing protocols to facilitate cross-border substrate shipments from Chinese fermentation partners. East Java's Surabaya metropolitan area anchors the largest concentration of complete-feed manufacturing infrastructure.
United States
North American oilseed crushing capacity provides consistent substrate supply for fermentation partners serving domestic livestock operations. USDA-FDA joint oversight of GRAS notifications and facility inspections structures import pathways for qualified fermented protein suppliers. Iowa and Illinois processing corridors concentrate the soybean meal volumes feeding both domestic fermentation facilities and export channels.
Germany
EU F-Gas Regulation constraints on solvent-based extraction alternatives channel compounders toward biological upgrading of oilseed meals. ECHA REACH framework compliance documentation burdens elevate preference for fermentation facilities holding dual EU-Asian regulatory registrations. Lower Saxony and Bavaria host the densest networks of premix manufacturers integrating certified fermented proteins for export-market supply tiers.
Fermented Soybean Meal Protein for Animal Feed Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive oilseed processing and fermentation capacity. Three archetypes occupy distinct positions: North American grain traders with backward integration into fermentation substrate supply, Asian bioprocessing specialists with dedicated bioreactor networks, and European nutrition companies leveraging regulatory compliance differentiation. Capacity expansion and strain-specific technology licensing represent the dominant competitive moves as facilities seek to compress batch-to-batch protein variability.
Among North American agribusiness conglomerates, ADM exemplifies the substrate-security archetype through its oilseed crushing footprint. CJ BIO occupies a position within the Asian bioprocessing specialist tier, anchoring volume leadership through dedicated fermentation infrastructure. Lallemand Inc. represents the strain-specific differentiation archetype, with its nomenclature signaling microbial technology specialization. These three entities illustrate how geographic processing advantages and technical capabilities segment competitive positioning across supply corridors.
| Leading Market Players |
|---|
| ADM |
| CJ BIO |
| Wilmar Group |
| Cargill |
| InnovaFeed |
| Angel Yeast |
| Lallemand Inc. |
| dsm-firmenich |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Bioreactor operator scarcity in Vietnam's Mekong Delta and Indonesia's Java corridor compresses labor-cost differentials into pricing-tier spreads, with facilities in these Southeast Asian feed corridors commanding premium rates against smaller batch operators lacking trained personnel for pH and microbial viability monitoring.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies fermented soybean meal protein markets, with certification grade and volume scale serving as primary price differentiation drivers. Premium tiers capture facilities holding dual EU-Asian regulatory registrations with lot-level traceability documentation, while economy tiers serve domestic compounders with less stringent veterinary residue requirements. Pricing pressure stems from soybean meal input cost volatility tied to North American oilseed harvests, compressing fermentation facility margins across all tiers. Small-scale aquaculture feed producers in Vietnam exhibit highest price sensitivity, whereas export-oriented integrators supplying Japanese retail channels demonstrate lowest sensitivity due to documentation compliance premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese fermentation substrate supply, where MIIT GB standards enforcement concentrates bioprocessing capacity in Shandong and Guangdong provinces. Raw material dependencies center on defatted soybean meal from North American oilseed crushing corridors, microbial strain libraries, and automated moisture control systems. Supply chain risk manifests as regulatory restriction exposure, with strain registration bottlenecks creating multi-quarter delays for new facility approvals. Distribution runs through integrated livestock operations consolidating premix-to-complete-feed procurement under single-source contracts, displacing fragmented ingredient purchasing across Vietnamese and Indonesian feed corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through fermentation scale economies as batch-to-batch protein variability compresses from historical 4-5 percentage point ranges toward sub-2-point deviation bands.
For Market Incumbents: Lock in substrate security through backward integration into North American oilseed crushing capacity or captive bioreactor networks in Southeast Asian feed corridors. CJ BIO and ADM exemplify this defensive posture through dedicated fermentation infrastructure and oilseed processing footprints respectively. Certification investment in dual EU-Asian regulatory registrations protects against emerging entrant displacement in export-certification supply tiers. Capacity addition in Vietnam's Mekong Delta and Indonesia's Java corridor anchors channel control as integrated livestock operations consolidate procurement. For New Entrants and Emerging Players: Direct-to-aquaculture-feed-producer digital platforms bypass established compounder intermediaries, offering strain-specific fermentation protocols with real-time batch monitoring dashboards. Norwegian and Chilean salmonid segments present the most penetrable geography, with marine ingredient substitution accelerating among producers facing finite wild-catch supply. Technical digestibility variance in incumbent supply creates white-space for facilities guaranteeing sub-2-point protein deviation bands through automated solid-state fermentation systems. For Investors and Strategic Acquirers: Asian agribusiness conglomerates with captive oilseed processing and fermentation capacity are the most active acquirer in this space, seeking to compress supply chain tiers. Facilities with trained bioreactor operator pipelines and dual regulatory registrations represent the priority acquisition archetype over the medium-term horizon. The signal to watch is USDA-FDA GRAS notification pathway streamlining for imported fermented proteins, which would reduce cross-border shipment friction and revalue qualified supplier assets.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Technology Licensing | Lallemand Inc. leverages proprietary microbial protocols to differentiate finished meal digestibility profiles for species-specific feed conversion optimization. |
| Backward Integration into Oilseed Crushing | ADM secures consistent substrate supply for fermentation partners through its North American processing footprint. |
| Dual Regulatory Registration Investment | Facilities holding both EU REACH framework and Chinese MIIT GB standards compliance access export-certification markets in Vietnam and Indonesia. |
| Automated Solid-State Fermentation Scale-Up | Real-time sensor networks in Shandong and Guangdong provinces compress batch-to-batch protein variability bands. |
| Complete-Feed Procurement Consolidation | Vietnam's Mekong Delta poultry integrators specify fermented protein inclusion rates directly in grower contracts. |
Research Methodology
Direct dialogue with fermentation facility operations managers, aquaculture feed procurement leads at Vietnamese and Indonesian integrators, bioprocessing R&D directors, and regulatory affairs specialists at Chinese MIIT-registered facilities grounded qualitative insights. Secondary validation drew from customs and trade data on defatted soybean meal flows, SEC 10-K filings of North American agribusiness conglomerates, GB standards documentation from Chinese regulatory repositories, and EU F-Gas Regulation compliance databases. Bottom-up facility capacity assessments and top-down feed industry demand modeling enabled triangulation across independent analytical paths.
Bottom-up volume estimates aggregated named fermentation facility capacities across Shandong, Guangdong, Can Tho, An Giang, and East Java production clusters, while top-down demand models traced species-specific feed conversion ratios through aquaculture, poultry, and swine segments. Segmentation dimensions spanned substrate oil content tiers, species application categories, and formulation type bundling preferences. CAGRs were derived from facility expansion announcements, grower contract specifications, and regulatory pathway timelines rather than extrapolated historical trends. Forecast inputs incorporated bioreactor operator pipeline constraints and strain registration approval velocities as industry-specific demand-side and supply-side governors.
The model assumes a particular technology adoption path; alternative pathways for solid-state fermentation automation or novel microbial strain approvals would alter the outlook. Forecasts reflect documented assumptions regarding MIIT GB standards enforcement continuity, EU F-Gas Regulation constraint tightening, and zero-antibiotic livestock policy persistence in Chinese export-oriented operations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Canada Animal Protein Market