
 Organic Hemp Market | 2026-2036
Organic Hemp Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Hemp Market Analysis
Direct-to-consumer online retail is narrowing as specialty stores and wholesale distributors consolidate shelf access for certified organic hemp products. Manitoba Harvest Hemp Foods leverages its vertically controlled supply chain from Canadian prairie farms to secure premium positioning. Navitas LLC competes through broad organic superfood distribution, while Connoils LLC specializes in bulk hemp oil extraction for downstream cosmetic and nutraceutical clients.
Organic hemp denotes Cannabis sativa cultivars grown without synthetic pesticides or fertilizers, containing less than 0.3% THC by dry weight and processed through cold-pressing or mechanical decortication to preserve cannabinoid and terpene profiles. Hemp seeds and hemp oil dominate current revenue flows due to established food-grade extraction infrastructure and EFSA novel food authorizations, while hemp fibers command structural margins in European technical textile applications where REACH compliance and biodegradability certifications create pricing premiums. Hemp protein occupies a smaller but accelerating position within sports nutrition and alternative meat formulations.
USDA organic certification, FDA food additive oversight, and EFSA novel food frameworks collectively determine market access timelines and label claims for hemp-derived ingredients across North American and European trade corridors. Stakeholders must track evolving THC threshold harmonization between FDA guidance and individual state hemp programs to avoid interstate commerce disruptions. The decisive variable for competitive positioning lies in securing multi-jurisdictional organic accreditation before downstream food manufacturers lock in supplier qualification cycles.
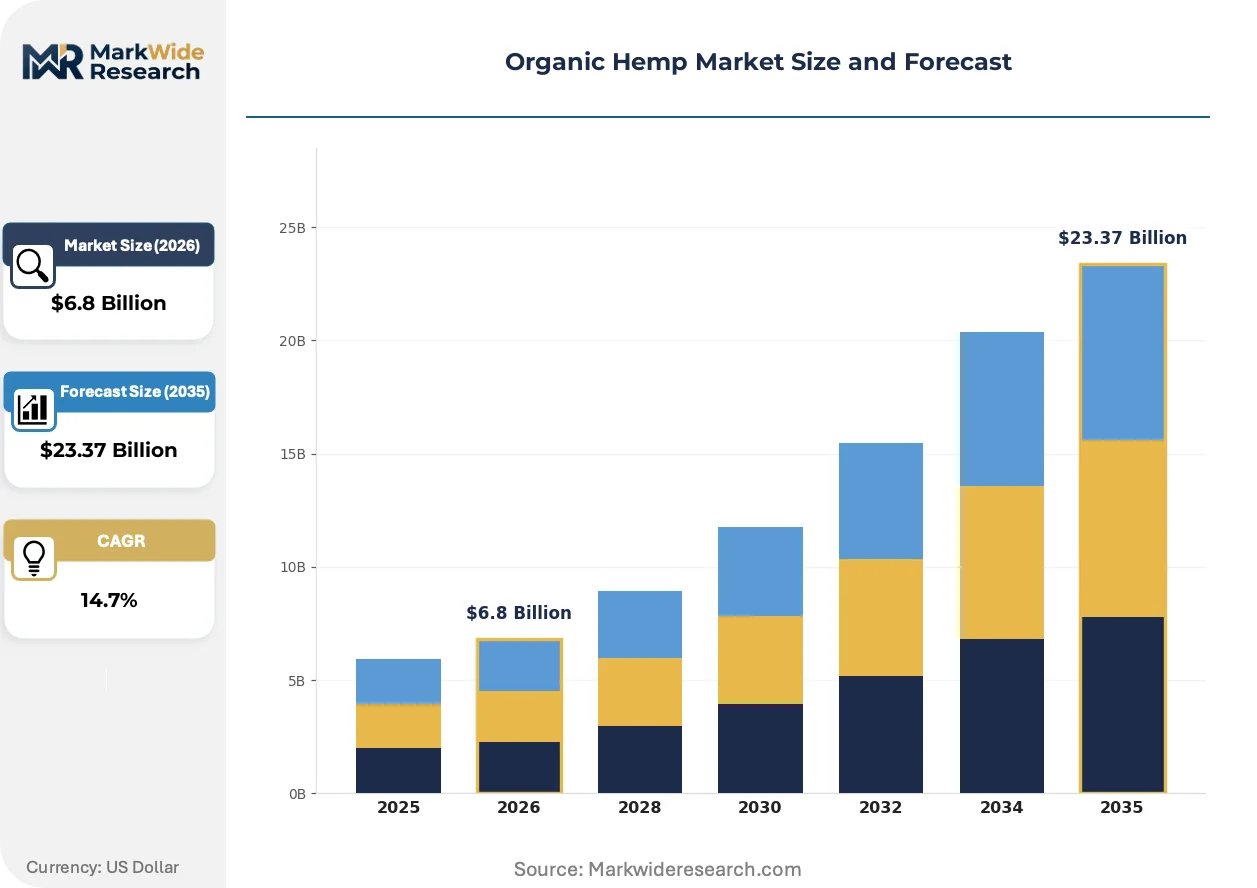
Market Dynamics
USDA organic certification timelines and EFSA novel food authorization backlogs are compressing supplier qualification windows, forcing early-mover accreditation strategies before downstream food manufacturers lock in multi-year procurement contracts.
Growth Catalysts
- EFSA Novel Food Framework:The European Food Safety Authority's streamlined approval pathways for hemp seed oil and protein isolates are accelerating market access for certified organic ingredients across EU member states.
- Sports Nutrition Formulation:Plant-based protein demand from athletic supplement brands is pulling organic hemp protein into pre-workout and recovery product lines at premium price points.
- Biodegradable Textile Mandates:European technical textile programs under REACH compliance requirements are creating structural demand for organic hemp fiber in automotive interiors and construction composites.
Market Restraints
- THC Threshold Fragmentation:Divergent state-level hemp programs in the United States create interstate commerce friction when THC testing protocols conflict with FDA guidance.
- Input Cost Volatility:Organic fertilizer and biological pest management inputs face price swings tied to petroleum-derived supply chains and seasonal weather patterns in Canadian prairie cultivation zones.
- Mechanical Decortication Bottlenecks:Limited processing infrastructure for hemp fiber separation concentrates supply risk among a small number of European technical textile processors.
Strategic Opportunities
- Alternative Meat Applications:Organic hemp protein's amino acid profile positions it for textured vegetable protein formulations targeting flexitarian consumers in German and Dutch retail channels.
- Cosmetic Cold-Pressing Expansion:Supercritical CO2 extraction convergence with organic certification standards is opening premium positioning for hemp seed oil in clean beauty formulations.
- Direct-to-Institutional Channels:Food service distributors and university procurement systems are creating bypass routes around consolidated retail shelf access for certified organic hemp ingredients.
Industry Challenges
- Multi-Jurisdictional Accreditation Timelines:Synchronizing USDA organic, Canada Organic, and EU organic certifications requires 18-24 month compliance cycles that outpace manufacturer supplier qualification windows.
- Cannabinoid Testing Protocol Standardization:Absence of harmonized THC and CBD analytical methods across ISO-accredited laboratories creates batch rejection risk at border inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Hemp Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.37 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Seeds, Hemp Oil, Hemp Fibers, Hemp Protein Application: Cosmetics, Food & Beverages, Textiles, Biofuel End User: Food Manufacturers, Cosmetic Companies, Textile Producers, Energy Sector Sales Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Organicway Inc., Manitoba Harvest Hemp Foods, Bioriginal Food & Science Corp., Connoils LLC, The Tonik, TruVibe Organics, Navitas LLC, HEMPLAND Organic Agri-Tech Inc., Linwoods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Hemp Market Emerging Trajectories
Processing technology and regulatory harmonization are converging to reshape competitive positioning in organic hemp, with digitization of supply chain verification and novel food authorization acceleration driving structural change.
Blockchain-enabled seed-to-shelf traceability platforms are digitizing organic hemp supply chain verification. Canadian prairie cooperatives and European textile consortiums are adopting these systems to compress certification audit cycles. The technology is digitizing documentation workflows that previously required manual paper trails across multiple jurisdictions.
EFSA's 2023-2025 novel food authorization batch processing is compressing approval timelines for hemp-derived ingredients. The framework is enabling faster market entry for organic hemp protein and oil products. German and Dutch food manufacturers are accelerating formulation pipelines in anticipation of streamlined authorizations.
Clean label procurement mandates from North American natural food retailers are displacing conventional superfood sourcing patterns. Specialty distributors are consolidating shelf access for certified organic hemp products ahead of mass-market penetration. This shift concentrates most visibly in Pacific Northwest and Northeast US metropolitan retail clusters.
Organic Hemp Market Segmentation
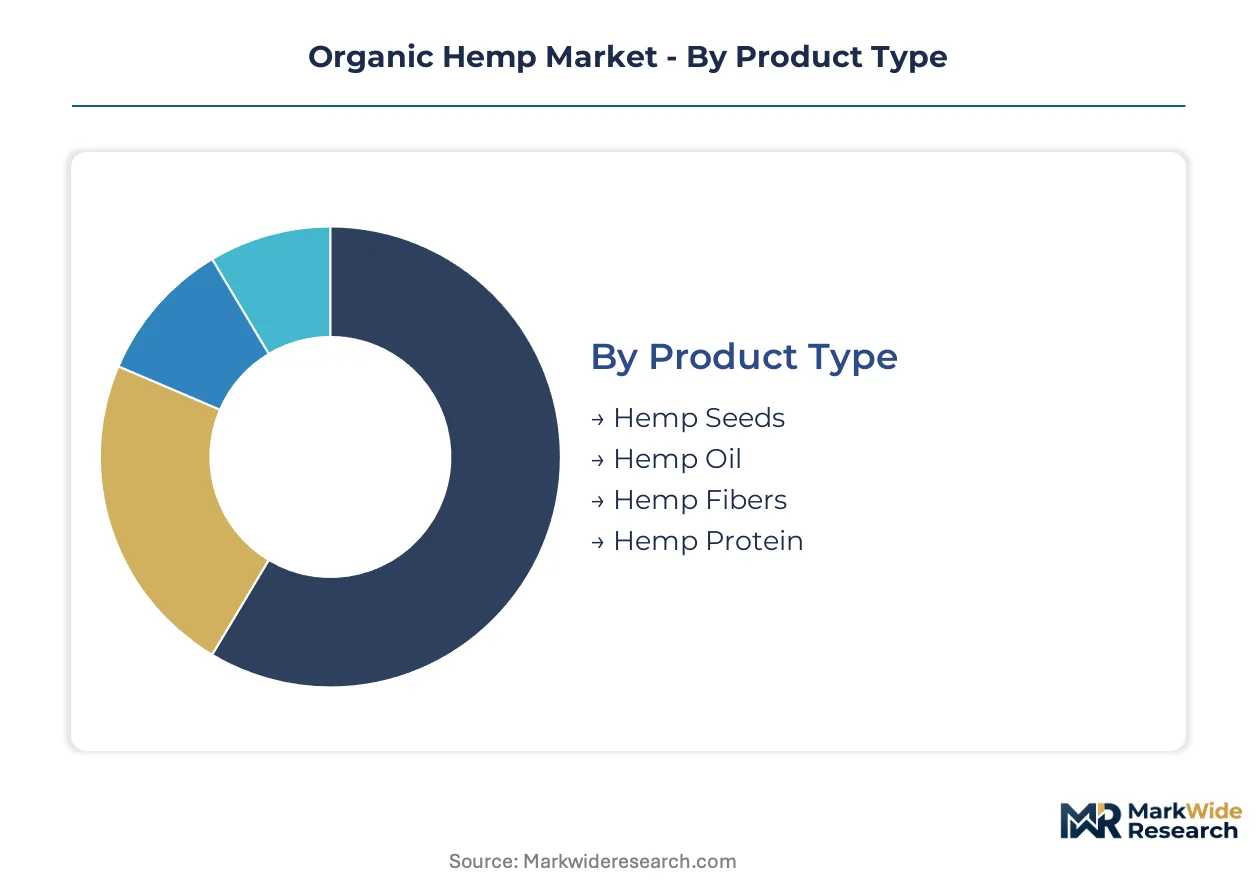
Segmentation in organic hemp reveals divergent margin profiles and certification requirements across product categories. Food-grade applications demand EFSA novel food compliance, while textile applications prioritize REACH biodegradability standards. Understanding these segment-specific regulatory pathways determines supplier qualification timelines and procurement lock-in windows.
Product Type:
Hemp seeds turn inventory fastest through established food-grade channels, while hemp fibers tie up capital longest due to mechanical decortication bottlenecks and textile processor qualification cycles.
- Hemp Seeds:Shelled and whole seeds contain complete amino acid profiles and omega fatty acid ratios suited for direct consumption and ingredient formulations. Demand concentrates in German and Dutch natural food retail channels where EFSA novel food authorizations have cleared regulatory pathways for shelled hemp seed placement.
- Hemp Oil:Cold-pressed and supercritical CO2 extracted variants preserve cannabinoid and terpene profiles for cosmetic and nutraceutical applications. Pacific Northwest US metropolitan clusters and French clean beauty formulators are pulling organic-certified cold-pressed oil at premium price points for facial serum and body care lines.
- Hemp Fibers:Bast and hurd fractions separated through mechanical decortication supply automotive interior panels and construction composites. REACH compliance mandates in German technical textile programs are creating structural demand for certified organic fiber.
- Hemp Protein:Isolate and concentrate forms deliver plant-based amino acid density for sports nutrition and alternative meat applications. Dutch and German flexitarian retail channels are accelerating textured vegetable protein formulations using organic hemp protein.
Hemp seeds dominate installed base through established food infrastructure. Hemp protein is where expansion concentrates as alternative meat formulations scale.
Application:
Cost tier stratification separates premium cosmetic positioning from commodity biofuel feedstock, with food and beverage applications occupying mid-tier margin bands.
- Cosmetics:Cold-pressed hemp seed oil and cannabinoid-rich extracts target clean beauty formulations with supercritical CO2 extraction preserving terpene profiles. French and US Pacific Northwest cosmetic formulators are specifying organic certification for facial oil and body care lines.
- Food & Beverages:Hemp seeds, protein isolates, and oil variants integrate into plant-based nutrition bars, dairy alternatives, and functional beverages. EFSA novel food authorizations are unlocking German and Dutch retail placement for shelled seed and protein concentrate ingredients.
- Textiles:Bast fiber for woven applications and hurd for non-woven composites serve automotive interiors and construction materials. REACH biodegradability certifications in German technical textile programs are creating pricing premiums for organic fiber.
- Biofuel:Hemp seed oil and residual biomass fractions supply biodiesel and cellulosic ethanol feedstocks. Energy sector procurement remains price-sensitive with limited organic certification premiums.
Food and beverages anchor volume throughput. Cosmetics is climbing the fastest on clean beauty procurement mandates.
End User:
Customer type determines contract structure, with food manufacturers demanding multi-year supply agreements and energy sector buyers operating on spot-market terms.
- Food Manufacturers:Plant-based protein and superfood ingredient suppliers lock in 18-24 month procurement cycles requiring synchronized USDA organic and EU organic accreditations. German and Dutch formulation pipelines are accelerating ahead of EFSA authorization batch processing.
- Cosmetic Companies:Clean beauty formulators specify cold-pressed oil with full seed-to-shelf traceability through blockchain-enabled verification platforms. French and US Pacific Northwest brands are consolidating supplier qualification around multi-jurisdictional organic certification.
- Textile Producers:Technical textile processors under REACH compliance mandates source bast fiber for automotive and construction applications. Limited European decortication infrastructure concentrates supply risk among German and Dutch processor networks.
- Energy Sector:Biodiesel and biomass power generators procure hemp oil and residual fractions on commodity terms with minimal organic certification requirements.
Food manufacturers lock in longest contract horizons. Cosmetic companies are gaining share fastest on clean label procurement mandates.
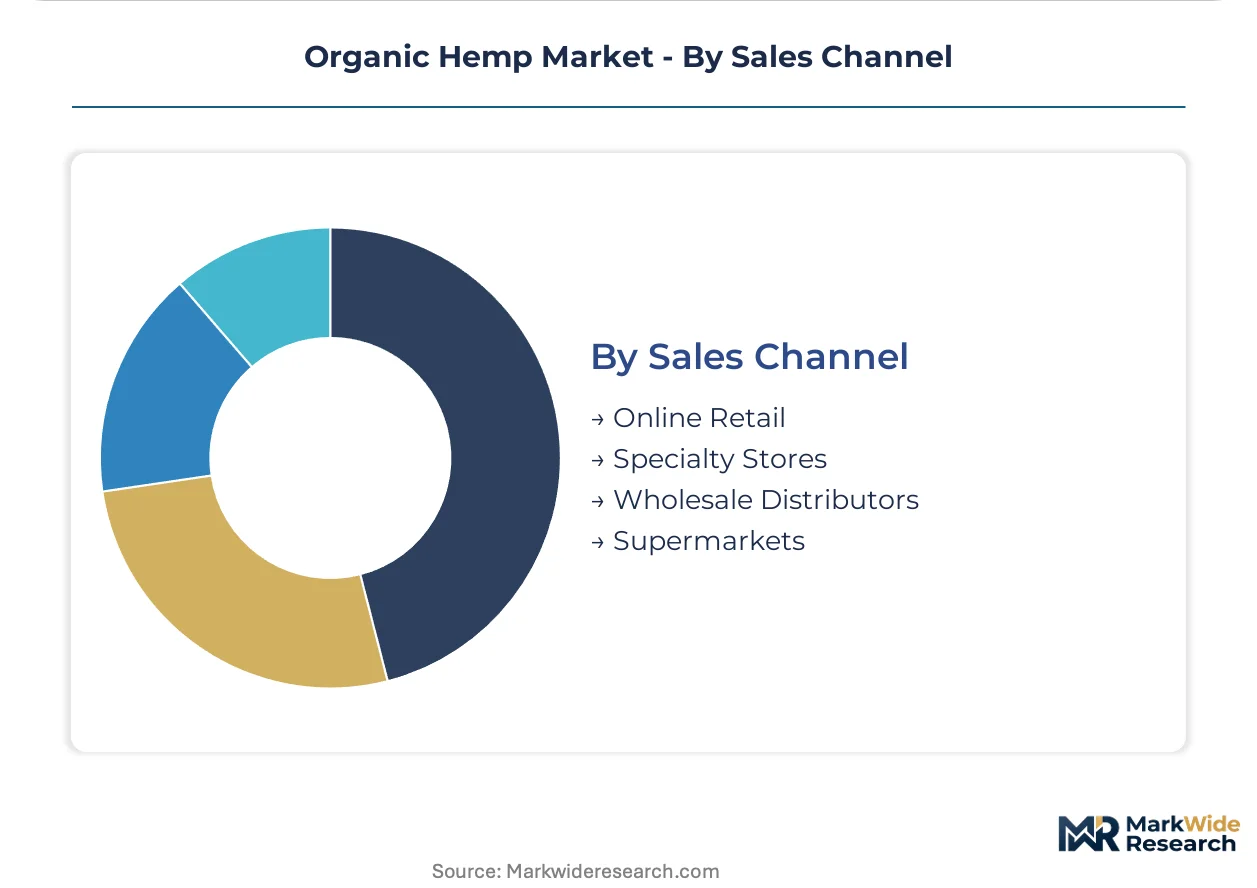
Sales Channel:
Volume concentration runs through wholesale distributors serving institutional accounts, while margin capture concentrates in specialty retail with direct consumer relationships.
- Online Retail:Direct-to-consumer platforms serve early-adopter segments in Pacific Northwest and Northeast US metropolitan clusters with subscription models for hemp seeds and protein products.
- Specialty Stores:Natural food retailers and clean beauty boutiques curate certified organic hemp products with premium positioning. Consolidation of shelf access is narrowing vendor counts in German and Dutch urban markets.
- Wholesale Distributors:Food service and institutional procurement systems bypass retail consolidation through direct-to-university and corporate cafeteria channels. Canadian prairie cooperatives are leveraging these routes for bulk seed and protein distribution.
- Supermarkets:Mass-market penetration remains limited pending harmonized THC threshold clarity across US state programs and streamlined EFSA authorizations in EU markets.
Wholesale distributors handle largest throughput volumes. Specialty stores are expanding most quickly as clean label procurement displaces conventional superfood sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification timelines anchor North American market access, while EFSA novel food frameworks govern European placement. Divergent THC testing protocols between FDA guidance and state hemp programs create interstate friction in the United States.
United States
The 2018 Farm Bill established federal hemp cultivation legality, yet FDA food additive oversight and patchwork state THC thresholds generate compliance complexity. Pacific Northwest metropolitan clusters concentrate clean beauty formulators sourcing cold-pressed hemp seed oil. Specialty distributors in Northeast urban markets are consolidating shelf access for certified organic products ahead of mass-market penetration.
Canada
Prairie cultivation zones in Manitoba and Saskatchewan supply the majority of North American organic hemp seed output. Health Canada and PMRA regulate pesticide residue limits and organic accreditation under the Canada Organic Regime. Vertically integrated cooperatives from prairie farm networks to extraction facilities are securing multi-year supply contracts with US food manufacturers.
Germany
REACH compliance mandates for biodegradable textiles drive structural demand for organic hemp fiber in automotive interior panels. EFSA novel food authorizations have cleared regulatory pathways for shelled hemp seed placement in natural food retail channels. Technical textile processors in Baden-Württemberg are concentrating supply relationships with limited European decortication infrastructure operators.
Netherlands
Flexitarian retail channels in Dutch urban markets are accelerating textured vegetable protein formulations using organic hemp protein isolates. EFSA batch processing timelines are compressing approval windows for hemp-derived ingredients ahead of manufacturer procurement lock-ins. Rotterdam-area distribution hubs are consolidating cross-border trade flows into German and Belgian food manufacturing corridors.
France
Clean beauty formulators in Provence-Alpes-Côte d'Azur and Paris metropolitan clusters specify organic-certified cold-pressed hemp seed oil for facial serum lines. ANSM cosmetic ingredient oversight intersects with EU organic certification requirements. French technical textile programs under EU Green Deal procurement mandates are creating pricing premiums for certified organic fiber in construction composite applications.
Organic Hemp Market Vendor Landscape
Vertically integrated agricultural processors and specialty ingredient distributors split the market into distinct capability tiers. Consolidation pressure runs through wholesale distributor networks as specialty retailers narrow vendor counts for certified organic shelf placement. Three archetypes dominate: prairie-based farm-to-processor operators controlling cultivation through extraction, broad organic superfood distributors leveraging multi-category placement, and bulk oil extraction specialists serving downstream cosmetic and nutraceutical formulators. Competitive moves center on multi-jurisdictional organic accreditation acceleration and blockchain-enabled seed-to-shelf traceability platform deployment.
Among North American vertically integrated operators, Manitoba Harvest Hemp Foods exemplifies the farm-controlled supply chain archetype from Canadian prairie cultivation through branded consumer placement. Navitas LLC occupies a position within the broad organic superfood distribution tier, while Connoils LLC represents the bulk extraction specialist model serving downstream B2B formulation clients. These three anchors illustrate the strategic segmentation between captive supply control, multi-category retail presence, and ingredient-focused B2B service models.
| Leading Market Players |
|---|
| Organicway Inc. |
| Manitoba Harvest Hemp Foods |
| Bioriginal Food & Science Corp. |
| Connoils LLC |
| The Tonik |
| TruVibe Organics |
| Navitas LLC |
| HEMPLAND Organic Agri-Tech Inc. |
| Linwoods |
| Others |
Supply Flow & Price Mechanics
Mechanical decortication undercapacity in European technical textile corridors is compressing supplier bargaining power while inflating organic hemp fiber premiums. This utilization squeeze cascades into seed and protein markets as prairie processors divert capacity toward higher-margin oil extraction.
Pricing Analysis
Price spreads between Canadian prairie farmgate and Rotterdam wholesale terminals capture logistics and certification arbitrage. Three-tier pricing structure across premium organic-certified, standard conventional, and economy feedstock grades segments buyer tiers. Cost compression in conventional hemp seed is intensifying because prairie cooperatives are expanding cold-pressing capacity. Energy sector biodiesel buyers exhibit highest price sensitivity; French clean beauty formulators show least sensitivity due to supercritical CO2 extraction premiums.
Supply Chain Analysis
Contract manufacturing concentration sits with Manitoba-based processors and Baden-Württemberg textile consortiums holding mechanical decortication capacity. Supply draws from Canadian prairie cultivation zones, Dutch distribution hubs, and German technical textile corridors. Organic fertilizer, biological pest management inputs, and supercritical CO2 extraction equipment constitute critical dependencies. Single-source vulnerability concentrates in limited European decortication infrastructure. Distribution runs through Rotterdam-area wholesale distributors serving institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled seed-to-shelf traceability platforms are transforming organic hemp into an interoperable data ecosystem where certification audit compression creates network effects. EFSA batch processing convergence with digitized supply chain verification marks the inflection.
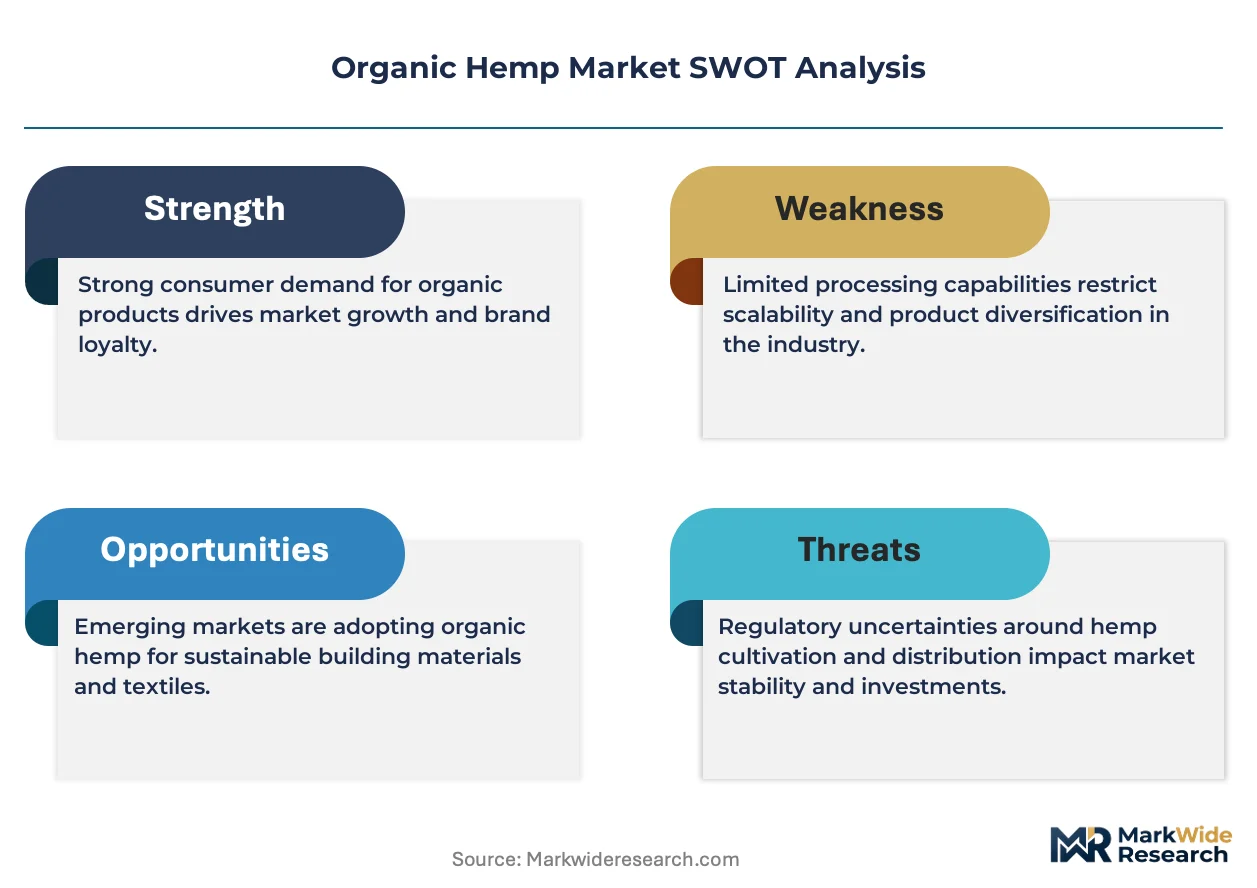
For Market Incumbents: Insulate multi-year supply contracts by accelerating Canada Organic and EU organic accreditation synchronization ahead of manufacturer qualification windows. Prairie-based farm-to-processor operators should deepen backward integration into biological pest management inputs to offset petroleum-derived fertilizer volatility. Threat of EFSA authorization backlogs locking out late movers demands preemptive compliance investment.
For New Entrants and Emerging Players: Build out direct-to-institutional channels bypassing retail shelf consolidation in Pacific Northwest metropolitan clusters. White-space opportunity concentrates in university procurement systems and corporate cafeteria networks underserved by incumbent wholesale distributors. Go-to-market angle: certified organic hemp protein for sports nutrition formulation pipelines.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated prairie cooperatives with captive supply from cultivation through extraction. Long-term viability over the coming decade rests on multi-jurisdictional organic accreditation moats rather than commodity scale. Acquisition target archetype: Canadian prairie-based processors with Health Canada and PMRA compliance infrastructure. Signal to watch: EFSA novel food authorization batch processing velocity as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Organic Accreditation | USDA organic and EU organic synchronization unlocks German and Dutch food manufacturer procurement cycles. |
| Blockchain Traceability Platform Deployment | Canadian prairie cooperatives compress certification audit cycles through digitized seed-to-shelf documentation workflows. |
| Alternative Meat Formulation Partnership | Dutch flexitarian retail channels accelerate textured vegetable protein pipelines using organic hemp protein isolates. |
| Supercritical CO2 Extraction Capacity Expansion | French clean beauty formulators specify cold-pressed oil with full cannabinoid and terpene profile preservation. |
| Direct-to-Institutional Channel Development | Food service distributors bypass retail consolidation through university and corporate cafeteria procurement systems. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings and trade databases through structured interviews with organic certification auditors, prairie cooperative operations managers, EFSA regulatory affairs specialists, and Dutch food manufacturer procurement leads. Secondary validation draws from USDA organic certification records, EFSA novel food authorization databases, Health Canada PMRA residue limit disclosures, and Canadian prairie agricultural output statistics. Bottom-up volume estimates from cultivation acreage and processor capacity triangulate against top-down demand aggregation from food manufacturer formulation pipelines and textile processor offtake agreements.
Forecast inputs span product type segmentation across hemp seeds, oil, fiber, and protein; application tiers from food and beverages through cosmetics and technical textiles; and end-user categories distinguishing food manufacturers, cosmetic formulators, textile producers, and energy sector buyers. CAGRs derive from installed base growth rates, substitution elasticity against competing plant proteins and synthetic fibers, and regulatory authorization velocity across the projection horizon. Industry-specific inputs include EFSA batch processing timeline compression and REACH biodegradability certification adoption curves in German automotive interior programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed extraction technology specialists or state-level hemp program regulators would shift outcomes. Assumptions reflect sustained EFSA authorization streamlining and stable THC threshold harmonization between FDA guidance and individual state programs. Quarterly review of EFSA novel food approval velocity, prairie organic acreage expansion rates, and European decortication capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Rice-Based Products Market
Agriculture and Agri Products
Australia Organic Farming Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Sugar Beet Market