
 Rutin Market | 2026-2036
Rutin Market Size, Share, and Industry Trends Forecast 2026-2036
Rutin Market Analytics
Custom extraction services and toll manufacturing agreements are recalibrating how rutin suppliers monetize output beyond bulk powder sales. Xian Sost Biotech leverages backward integration into Sophora japonica cultivation to secure raw material consistency. NOW Foods competes through GMP-certified manufacturing and broad retail distribution across North American health stores. Naturalin differentiates via organic certification and botanical extract specialization serving European cosmetic formulators.
Rutin is a flavonoid glycoside comprising quercetin and rutinose, typically extracted from Sophora japonica buds or buckwheat through solvent extraction and crystallization processes yielding 95% purity grades for pharmaceutical use. The compound functions primarily as a vascular protectant and antioxidant in therapeutic and nutraceutical applications. Rutin powder dominates volume shipments due to bulk procurement by pharmaceutical compounders and supplement manufacturers seeking formulation flexibility. Dietary supplements represent the fastest-growing end-user channel as consumers self-direct preventive cardiovascular spending. The antioxidant application commands premium pricing over colorant uses due to clinical substantiation requirements and dosage standardization.
The FDA's New Dietary Ingredient notification process and cGMP enforcement shape market access for novel rutin delivery formats in the United States. China's NMPA and GB standards for botanical extracts govern export quality specifications and heavy metal limits for international shipments. The EU's EFSA health claims regulation constrains promotional language for rutin-containing products across European member states. Stakeholders must monitor evolving pharmacopeial monograph revisions and adapt purification investments to meet tightening contaminant thresholds without geographic concentration risk.
Market Dynamics
Backward integration into Sophora japonica cultivation is consolidating supply control among extract processors, compressing procurement cycles for pharmaceutical-grade rutin while China's NMPA tightens export quality specifications.
Growth Catalysts
- Dietary Supplement Formulation Demand:Cardiovascular and venous health applications are pulling rutin into preventive nutraceutical portfolios as consumers self-direct spending on vascular protectants.
- EFSA Health Claims Framework:European regulatory clarity on antioxidant substantiation is enabling promotional differentiation for rutin-containing products across EU member states.
- Sophora japonica Processing Infrastructure:Concentrated cultivation and extract processing capacity in Shaanxi and Henan provinces is securing raw material throughput for international pharmaceutical compounders.
Market Restraints
- Input Cost Volatility:Sophora japonica bud harvest yields fluctuate with seasonal weather patterns, creating raw material price instability for solvent extraction operations.
- Supply Concentration Risk:Heavy reliance on Chinese cultivation clusters exposes procurement pipelines to NMPA export licensing delays and GB standards enforcement variability.
- FDA NDI Notification Friction:Novel delivery format entrants face extended review timelines under New Dietary Ingredient requirements, slowing product pipeline velocity in the United States.
Strategic Opportunities
- Cosmeceutical Application Expansion:European cosmetic formulators are integrating rutin into antioxidant skincare lines, creating premium pricing tiers beyond traditional pharmaceutical channels.
- Organic Certification Pathway:EU organic botanical extract standards are opening differentiated positioning for certified suppliers serving sustainability-focused personal care brands.
- Toll Manufacturing Services:Custom extraction agreements are monetizing processing capacity beyond bulk powder sales, capturing value from mid-tier supplement manufacturers lacking in-house purification assets.
Industry Challenges
- Pharmacopeial Compliance Timeline:Revisions to USP and EP monographs for flavonoid glycosides are requiring capital-intensive purification upgrades to meet tightening contaminant thresholds.
- Specialized Extraction Talent Scarcity:Crystallization process optimization and HPLC standardization expertise remains concentrated among legacy botanical extract technicians, constraining operational scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rutin Market |
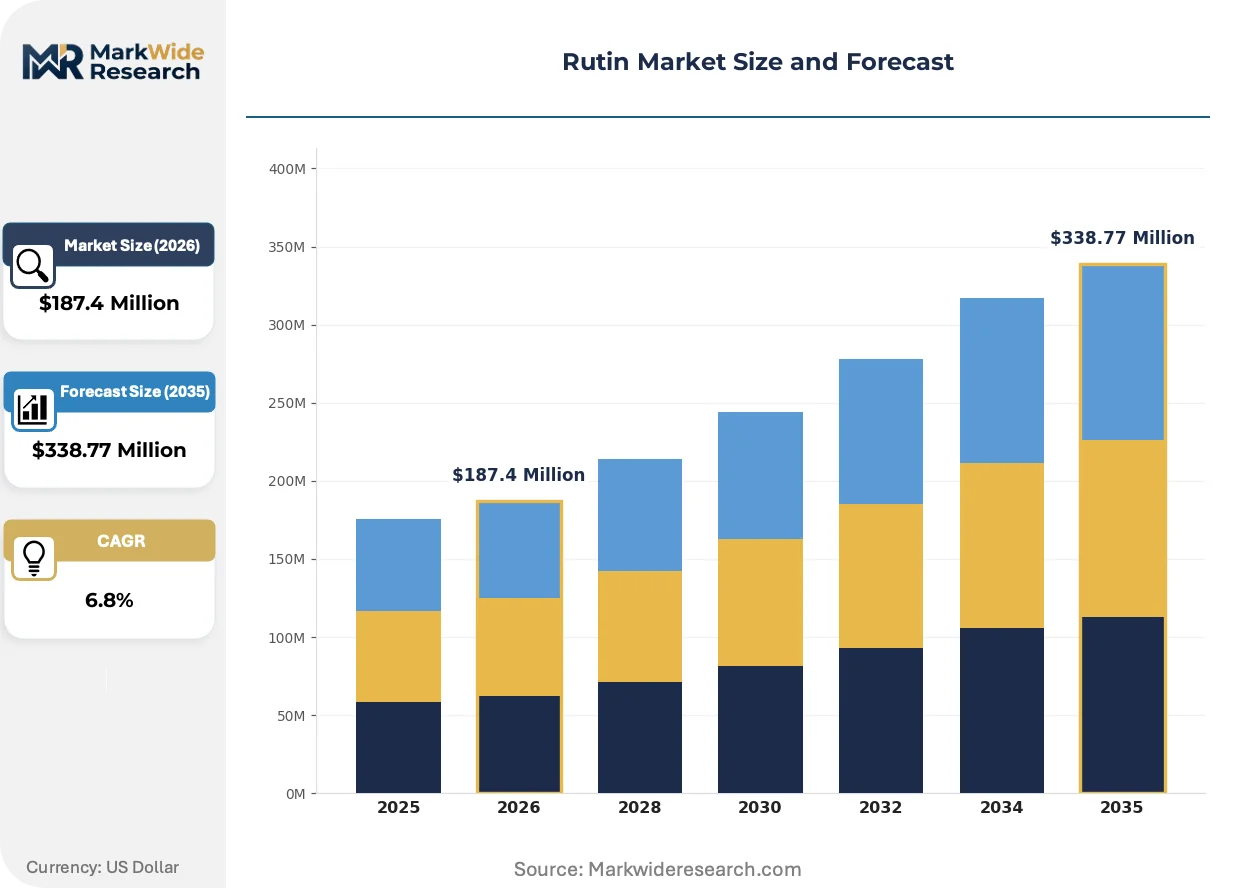
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rutin Powder, Rutin Capsules, Rutin Tablets, Rutin Extract End User: Pharmaceuticals, Dietary Supplements, Cosmetics, Food & Beverage Application: Anti-inflammatory, Antioxidant, Nutritional Supplement, Colorant Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores |
| Companies Covered | Xian Sost Biotech Co., Ltd, Organic Kreation, Herb Pharm, Xian Qingshuo Import and Export Trade Co., Ltd., Naturalin, NOW Foods, FZBIOTECH, Xuancheng Quality Herb Co., Ltd., Nature's Way, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rutin Market Evolving Landscape
Supercritical CO2 extraction technology is displacing conventional solvent-based purification, reshaping cost structures and purity benchmarks across pharmaceutical and nutraceutical supply tiers.
Supercritical CO2 extraction systems are consolidating market share among tier-one rutin processors seeking to eliminate residual solvent contamination risks. Pharmaceutical compounders in Germany and Switzerland are specifying CO2-derived grades for injectable formulations, compressing demand for traditional ethanol-extracted material. The technology is consolidating competitive position around heavy metal and pesticide compliance without multiple purification stages.
REACH registration requirements for botanical extracts are forcing European importers to document full supply chain substance volumes and hazard classifications. Toll manufacturers serving cosmetic formulators are investing in SIEF consortia participation to secure continued market access. The regulation most acutely affects mid-sized Chinese exporters lacking dedicated regulatory affairs capacity for SVHC screening and dossier preparation.
Direct-procurement agreements between dietary supplement brands and Sophora japonica cultivators are shortening traditional distributor channels. North American health store chains are negotiating backward integration into raw material sourcing, displacing layered importer-wholesaler relationships. This pattern concentrates in cardiovascular supplement categories where batch traceability and organic certification command shelf placement premiums.
Rutin Market Segmentation
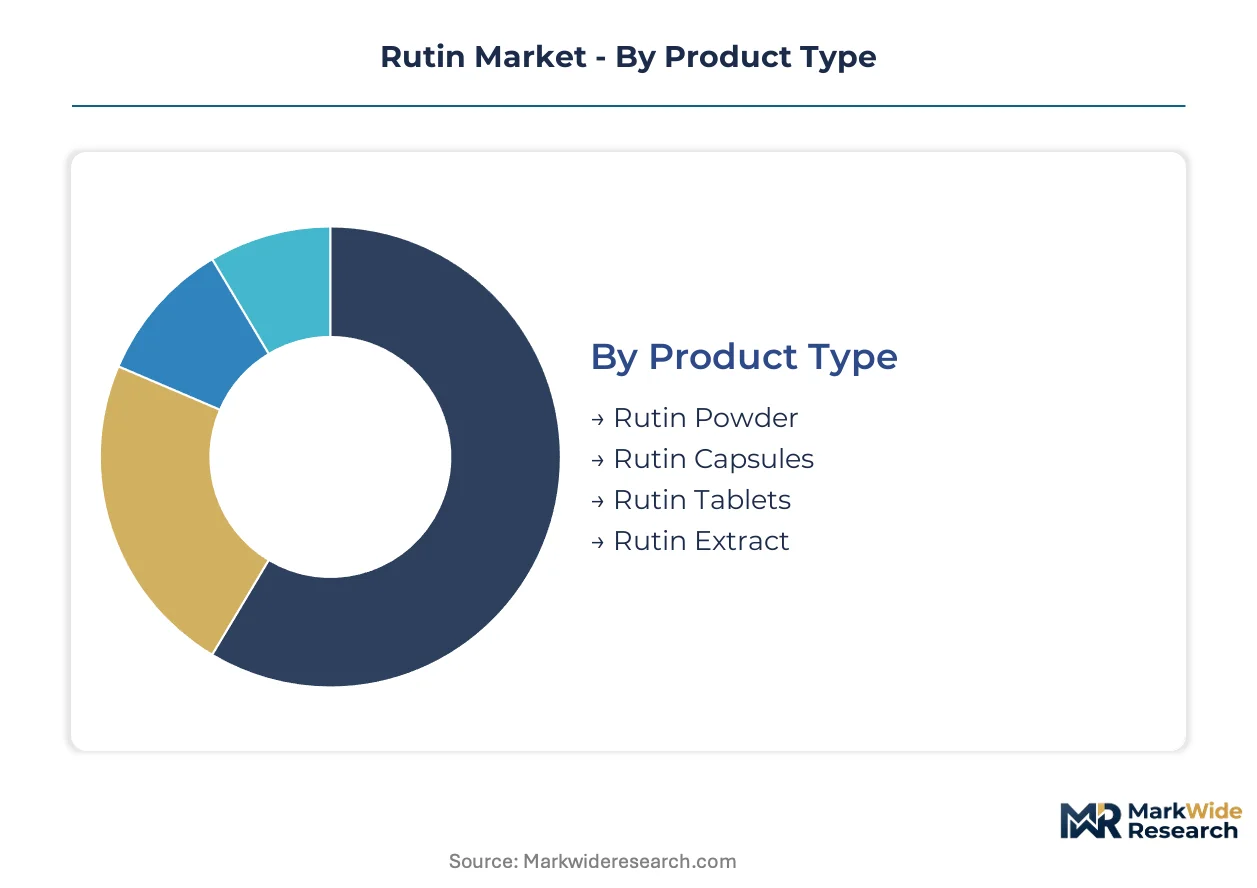
Rutin procurement patterns diverge sharply across product formats and end-use channels, with pharmaceutical compounders demanding crystalline purity grades while cosmetic formulators prioritize solubility characteristics. Supply chain configuration varies by segment, compressing margins for bulk powder traders while enabling premium capture for finished dosage specialists.
Product Type:
Sophora japonica processing infrastructure concentrates output in powder form, yet encapsulation and tableting capabilities are fragmenting across toll manufacturers seeking to capture formulation value.
- Rutin Powder:Crystalline material at 95% purity serves pharmaceutical compounders and supplement manufacturers requiring dosage flexibility. Demand clusters in Shaanxi and Henan province extract processors supplying German and Swiss injectable formulators. NMPA export licensing delays create procurement bottlenecks for international buyers.
- Rutin Capsules:Hard-shell gelatin and vegetarian capsule formats dominate North American health store shelves. NOW Foods and comparable GMP-certified manufacturers compete through retail distribution breadth. FDA cGMP enforcement shapes production location decisions.
- Rutin Tablets:Compressed dosage forms with binders and coatings suit European pharmacy channels requiring stability documentation. EFSA health claims constraints limit promotional differentiation.
- Rutin Extract:Liquid and soft-extract preparations serve cosmetic formulators integrating rutin into antioxidant skincare serums. Organic certification commands shelf placement premiums in EU personal care markets.
Rutin powder absorbs the bulk of installed capacity; rutin capsules are expanding most quickly.
End User:
Customer procurement sophistication varies by sector, with pharmaceutical buyers enforcing pharmacopeial monograph compliance while cosmetic brands prioritize organic certification and traceability documentation.
- Pharmaceuticals:Injectable and oral dosage manufacturers specify USP and EP grade material with full heavy metal and pesticide screening. Swissmedic and Health Canada oversight drives purity investment. Supercritical CO2 extraction systems displace solvent-based methods for contaminant-sensitive applications.
- Dietary Supplements:Cardiovascular and venous health positioning pulls rutin into preventive nutraceutical portfolios. Direct-procurement agreements between brands and Sophora japonica cultivators shorten traditional distributor channels.
- Cosmetics:European formulators integrate rutin into antioxidant skincare lines under EU cosmetic regulation requirements. REACH registration obligations force supply chain documentation for botanical extract volumes.
- Food & Beverage:Colorant applications in functional beverages face dosage standardization challenges. EFSA novel food assessments constrain new product entry timelines.
Pharmaceuticals command the highest purity premiums; dietary supplements are climbing the fastest.
Application:
Clinical substantiation requirements create tiered pricing structures, with therapeutic applications justifying purification investments that colorant uses cannot support.
- Anti-inflammatory:Vascular protectant positioning in chronic venous insufficiency formulations requires documented bioavailability. German compounders specify CO2-derived grades for extended-release preparations.
- Antioxidant:Free radical scavenging claims in nutraceutical and cosmetic applications command premium pricing over colorant uses. EFSA health claims framework enables promotional differentiation for substantiated products.
- Nutritional Supplement:General wellness positioning in multivitamin complexes competes on cost per active dose. Volume procurement by North American health store chains concentrates demand.
- Colorant:Natural yellow-brown hue in beverages and confectionery faces synthetic substitute competition. Price sensitivity limits upstream investment in purification.
Antioxidant applications capture the steepest expansion trajectory; colorant uses face margin compression.
Distribution Channel:
Channel selection determines regulatory exposure, with pharmacy and health store routes requiring documentation that online retail often circumvents.
- Online Retail:Direct-to-consumer platforms enable supplement brands to bypass layered importer-wholesaler relationships. Amazon and specialized nutraceutical marketplaces concentrate North American volume.
- Pharmacies:German and French pharmacy chains enforce batch traceability and organic certification for shelf placement. ANSM oversight shapes product registration requirements.
- Supermarkets:Mass-market penetration depends on price positioning against synthetic alternatives. Private label expansion by European retail chains compresses branded margin.
- Health Stores:GNC and comparable specialty retailers prioritize cardiovascular supplement categories with batch traceability documentation. NOW Foods competes through broad retail distribution.
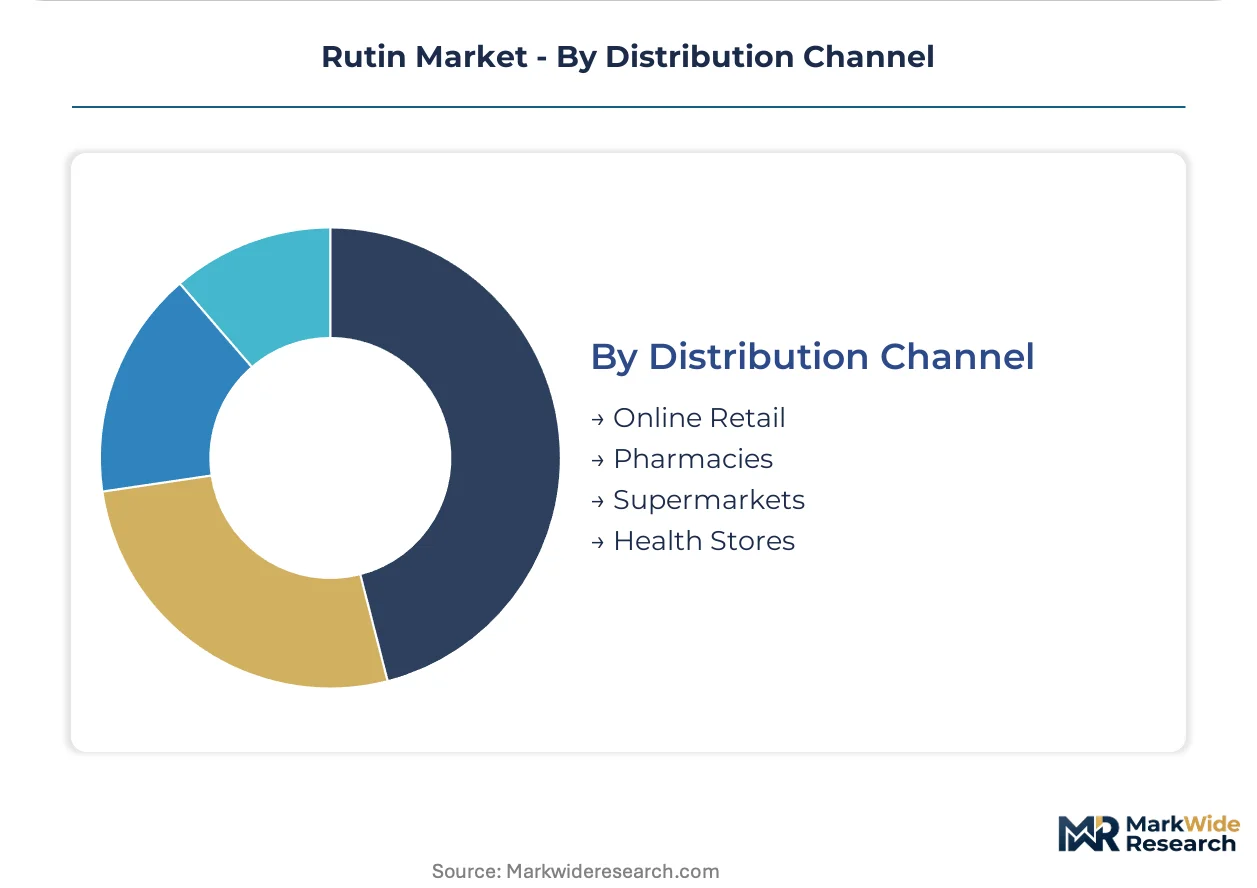
Online retail is gaining share fastest; pharmacies retain the highest documentation barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rutin production concentrates in Chinese Sophora japonica processing clusters while consumption spreads across pharmaceutical compounders in Germany, supplement manufacturers in the United States, and cosmetic formulators in France. This geographic mismatch shapes trade flows and regulatory compliance investments.
China
Shaanxi and Henan provinces host concentrated Sophora japonica cultivation and extract processing infrastructure serving international pharmaceutical buyers. NMPA export licensing and GB standards for botanical extracts govern heavy metal limits and quality specifications for outbound shipments. Xian-based processors leverage backward integration into raw material sourcing to secure batch consistency for European and North American compounders.
Germany
Injectable and oral dosage manufacturers in Bavaria and Baden-Württemberg specify USP and EP grade rutin with full contaminant screening for vascular protectant formulations. REACH registration requirements for botanical extracts force importers to document supply chain substance volumes and hazard classifications. Swissmedic-aligned oversight in adjacent markets drives purity investment among southern German compounders.
United States
Dietary supplement brands in California and Utah pull rutin into cardiovascular and venous health portfolios as consumers self-direct preventive spending. FDA New Dietary Ingredient notification requirements and cGMP enforcement shape product entry pathways and production location decisions for novel delivery formats. NOW Foods anchors GMP-certified manufacturing serving health store chains nationwide.
France
Cosmetic formulators in Île-de-France integrate rutin into antioxidant skincare lines under EU cosmetic regulation requirements. ANSM oversight and EFSA health claims constraints limit promotional differentiation for rutin-containing products. Paris-region laboratories prioritize organic certification and batch traceability documentation for shelf placement in pharmacy channels.
Switzerland
Pharmaceutical compounders in Basel and Zurich specify supercritical CO2-derived rutin grades for injectable formulations requiring elimination of residual solvent contamination. Swissmedic oversight drives premium pricing for contaminant-sensitive therapeutic applications. Alpine processing facilities serve as quality gatekeepers for material entering German and French downstream channels.
Rutin Market Competitive Landscape
Capital-heavy extract processors compete with asset-light brand marketers across differentiated supply chain positions. The vendor base splits between backward-integrated Chinese cultivators, GMP-certified North American manufacturers, and European organic-certified specialists. Three archetypes dominate: upstream raw material controllers, midstream toll manufacturers, and downstream retail brand owners. Competitive moves concentrate on direct-procurement agreements shortening distributor channels and supercritical CO2 extraction capacity expansion for pharmaceutical-grade output.
Among Chinese extract processors, Xian Sost Biotech Co., Ltd and Naturalin occupy positions representing upstream integration archetypes, with geographic identifiers signaling Shaanxi province concentration. NOW Foods exemplifies the GMP-certified North American manufacturer archetype, while Herb Pharm and Nature's Way represent brand-marketing specialists competing through retail distribution breadth rather than captive production assets.
| Leading Market Players |
|---|
| Xian Sost Biotech Co., Ltd |
| Organic Kreation |
| Herb Pharm |
| Xian Qingshuo Import and Export Trade Co., Ltd. |
| Naturalin |
| NOW Foods |
| FZBIOTECH |
| Xuancheng Quality Herb Co., Ltd. |
| Nature's Way |
| Others |
Value Network & Pricing Analysis
Sophora japonica bud harvest price volatility cascades through extraction operations into a three-tier pricing structure across premium, standard, and economy levels, with supercritical CO2-derived pharmaceutical grades commanding substantial premiums over solvent-extracted material serving colorant applications.
Pricing Analysis
Cost-down pressure on standard-grade rutin accelerates because synthetic colorant substitutes undercut natural extract pricing in beverage applications. Pharmaceutical compounders absorb premium-mid-economy pricing differentiation driven by USP and EP certification tiers, while dietary supplement manufacturers exhibit highest price sensitivity as they compete on cost per active dose in multivitamin complexes. Margin tightening in economy-tier powder reflects oversupply of unrefined extract from Shaanxi province processors lacking downstream purification assets.
Supply Chain Analysis
China's NMPA export licensing requirements are reshaping sourcing decisions for European and North American buyers seeking alternative cultivation bases. Raw material supply concentrates in Shaanxi and Henan provinces, with buckwheat from France and tartary buckwheat from Nepal providing secondary feedstock diversity. The supply chain rests on Sophora japonica bud harvests, crystallization-grade solvents, and supercritical CO2 processing equipment. Single-source vulnerability from Chinese processing concentration exposes procurement pipelines to GB standards enforcement variability. Distribution runs through layered importer-wholesaler relationships that direct-procurement agreements between supplement brands and cultivators are progressively displacing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into Sophora japonica cultivation is emerging as the decisive competitive lever, with processors securing raw material control to compress procurement cycles and buffer against NMPA licensing delays.
For Market Incumbents: Anchor market position through supercritical CO2 capacity expansion for pharmaceutical-grade output and toll manufacturing service agreements capturing mid-tier supplement manufacturers lacking in-house purification assets. Defend against emerging Chinese processors by securing EFSA-substantiated health claims and organic certification pathways that command shelf placement premiums in European pharmacy channels. For New Entrants and Emerging Players: Capture white-space opportunity in cosmeceutical applications where European formulators integrate rutin into antioxidant skincare lines under REACH registration requirements. Target organic-certified extract supply to sustainability-focused personal care brands in France and Germany, leveraging SIEF consortia participation to overcome regulatory entry barriers that constrain mid-sized Chinese exporters. For Investors and Strategic Acquirers: The window for entry favors backward-integrated processors with captive Sophora japonica cultivation and supercritical CO2 extraction assets. Long-term viability hinges on pharmacopeial compliance capabilities as USP and EP monograph revisions tighten contaminant thresholds. Watch NMPA export licensing velocity as the critical inflection signal for supply availability and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Xian Sost Biotech secures raw material consistency through captive Sophora japonica farming in Shaanxi province. |
| Supercritical CO2 Capacity Expansion | Swiss and German pharmaceutical compounders specify CO2-derived grades for injectable formulations requiring zero residual solvent. |
| Toll Manufacturing Services | Custom extraction agreements monetize processing capacity beyond bulk powder sales for mid-tier supplement manufacturers. |
| Organic Certification Pathway | EU organic botanical extract standards open differentiated positioning for certified suppliers serving Paris-region cosmetic laboratories. |
| Direct-Procurement Agreements | North American health store chains negotiate raw material sourcing that displaces layered importer-wholesaler relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with extract processing plant managers, pharmaceutical procurement leads, dietary supplement brand managers, and European cosmetic formulators. NMPA export licensing databases, EFSA health claims registers, and USP monograph revision notices provided regulatory trajectory inputs. Bottom-up volume modeling across product formats triangulated against top-down value estimates from customs trade flows.
Reconciliation of production capacity data from Shaanxi and Henan province processors with consumption patterns from German pharmaceutical compounders and North American supplement manufacturers shaped the analytical framework across the analysis window. Segmentation modeling incorporated product type, end-user channel, application, and distribution channel dimensions. CAGRs derived from volume-price elasticity analysis and regulatory pathway timelines for novel delivery formats.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA export licensing velocity, EFSA health claims substantiation rulings, and pharmacopeial monograph revision implementation. Forecasts reflect documented assumptions regarding Sophora japonica harvest yield stability and supercritical CO2 technology adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Japan Animal Protein Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Global Commercial Seaweeds Market