

Mushroom-Based Biodegradable Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom-Based Biodegradable Packaging Solutions Market Insights
A shift from outsourced petrochemical feedstocks to in-house mycelium cultivation is restructuring supply economics across the packaging value chain. Ecovative anchors North American production capacity with dedicated grow facilities in New York State. Magical Mushroom Company leverages European contract manufacturing to serve UK and EU brand customers without cross-border biosecurity complications. Sealed Air competes through its existing converter relationships, offering mycelium formats alongside conventional protective packaging lines.
Mushroom-based biodegradable packaging solutions comprise engineered mycelium composites grown on agricultural substrates such as hemp hurds or corn stalks, then heat-pressed into densities of 0.05–0.15 g/cm³ for cushioning or molded into rigid forms with compressive strength exceeding 200 kPa. These materials replace expanded polystyrene and polyethylene foams in protective and single-use applications where end-of-life compostability carries brand value. Molded packaging leads current revenue contribution due to premium positioning in electronics protection and cosmetics gift sets, while flexible packaging formats grow fastest as film lamination and coating techniques mature for food-contact barriers. Rigid packaging occupies the most contested margin pool, with multiple entrants vying for fast-food chain qualification programs.
The EPA regulates compostability claims under the FTC Green Guides in the United States, while the EU Green Deal's Packaging and Packaging Waste Regulation mandates recyclability or compostability benchmarks that mycelium formats currently meet. BIS composting standards in India create additional compliance pathways for exporters targeting emerging sustainability-conscious segments. Stakeholders must monitor regulatory divergence on home versus industrial composting certification, as this distinction determines viable customer segments and pricing architecture across jurisdictions.
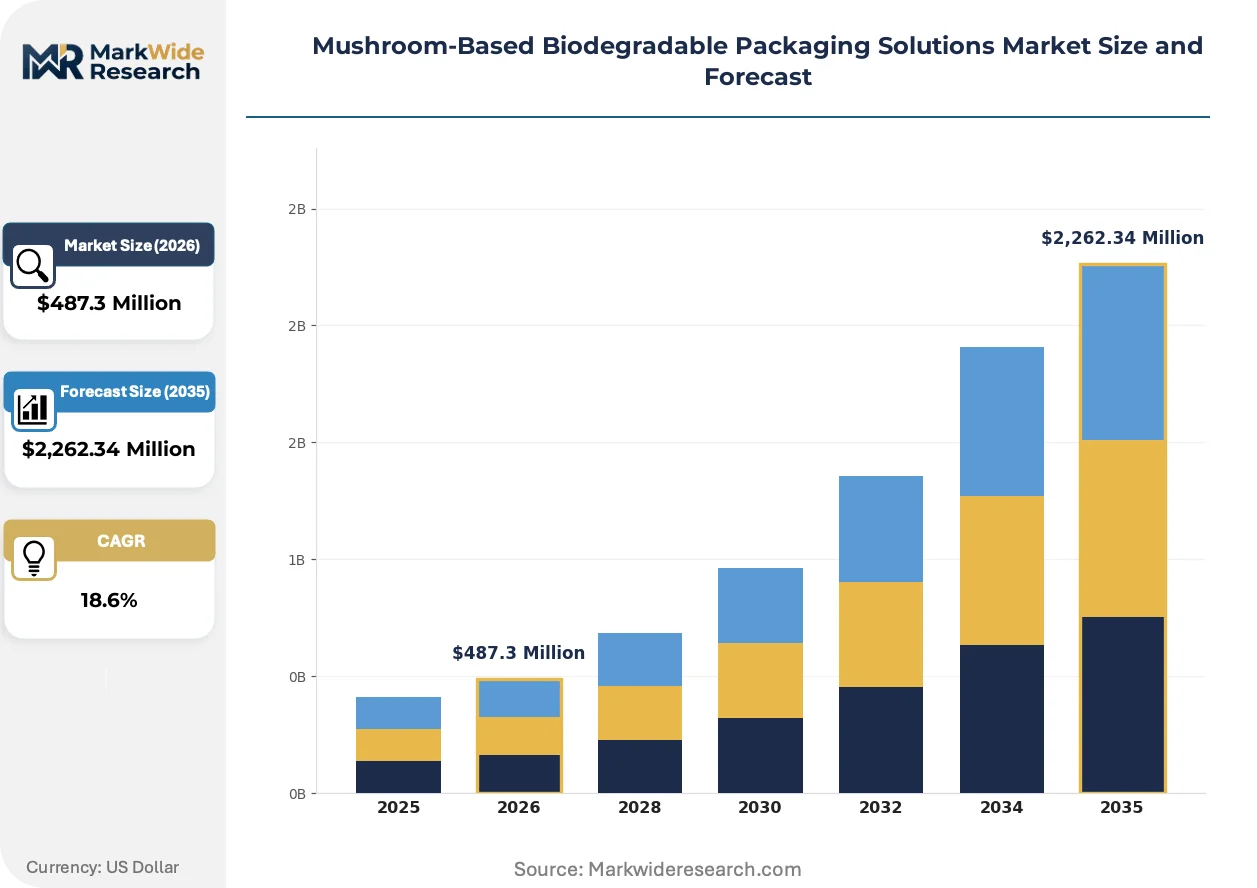
Market Dynamics
The EU Green Deal's Packaging and Packaging Waste Regulation is forcing immediate material substitution decisions across food service and electronics supply chains, compressing qualification timelines from years to months.
Growth Catalysts
- EU Green Deal mandates:The Packaging and Packaging Waste Regulation establishes legally binding recyclability and compostability benchmarks that mycelium formats satisfy, creating guaranteed demand pools across member states.
- Food service operator specifications:Quick-service restaurant chains in Germany and the Netherlands now write mycelium-based takeout containers into RFP requirements, pulling production capacity toward certified suppliers.
- Agricultural substrate abundance:Corn stalk and hemp hurd waste streams in the American Midwest and Eastern Europe provide low-cost, regionally sourced feedstock for mycelium cultivation networks.
Market Restraints
- Input cost volatility:Agricultural substrate prices fluctuate with grain commodity cycles, exposing mycelium growers to cost squeezes when corn or hemp markets tighten.
- Production concentration risk:North American mycelium packaging capacity clusters in New York State, creating single-point vulnerability for brands dependent on just-in-time delivery.
- Technical shelf-life limitations:Uncoated mycelium materials absorb atmospheric moisture above 70% relative humidity, restricting viable distribution to climate-controlled logistics corridors.
Strategic Opportunities
- Indian export pathway:BIS composting standards create a compliance route for mycelium packaging targeting sustainability-conscious consumer segments in Mumbai and Bangalore retail channels.
- Flexible food-contact barriers:Lamination and coating technique maturation enables mycelium films to replace polyethylene in fresh produce wrapping, opening volume segments beyond rigid molded applications.
- Industrial composting infrastructure buildout:Municipal composting facility expansion in France and Italy creates captive end-of-life pathways that justify premium positioning against home-compostable alternatives.
Industry Challenges
- Mycologist cultivation expertise scarcity:Scaling sterile spawn production requires specialized fungal biology talent that packaging industry veterans rarely possess, forcing expensive biotech hiring or training programs.
- Dual certification timeline compression:Simultaneous pursuit of home and industrial composting certifications under BPI and OK Compost protocols extends product launch cycles by 8-14 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom-Based Biodegradable Packaging Solutions Market Trends and Innovations
Heat-pressed mycelium composite engineering is rewriting density-to-performance ratios across protective packaging categories, enabling material scientists to tune compressive strength and cushioning coefficients through substrate selection and pressing parameters.
Engineered mycelium composites grown on hemp hurds or corn stalks, then heat-pressed into densities of 0.05–0.15 g/cm³ for cushioning or molded into rigid forms with compressive strength exceeding 200 kPa, are rewriting the economics of electronics protection. Consumer electronics brands in Germany and California now specify these materials for unboxing experience redesigns. The technology is rewriting supplier selection criteria, prioritizing in-house cultivation capabilities over conventional converter relationships.
REACH chemical registration requirements in Europe are tightening scrutiny of synthetic additives in biodegradable packaging, pushing formulators toward mycelium's inherently additive-free composition. Industrial consequence includes accelerated R&D migration from starch-based foams to mycelium matrices. Electronics and cosmetics gift set segments in France and the Netherlands respond fastest, locking in multi-year supply agreements to secure qualification status.
Brand procurement teams now mandate compostability certification as a non-negotiable gate for packaging vendor onboarding, displacing price-first evaluation frameworks. Direct supplier relationships are replacing distributor-mediated purchasing in food service and electronics verticals. This pattern concentrates most visibly in Berlin and Hamburg, where production scale-ups and brand pilot programs cluster within 200-kilometer radii, enabling just-in-time collaboration and rapid iteration cycles.
Mushroom-Based Biodegradable Packaging Solutions Market Segmentation
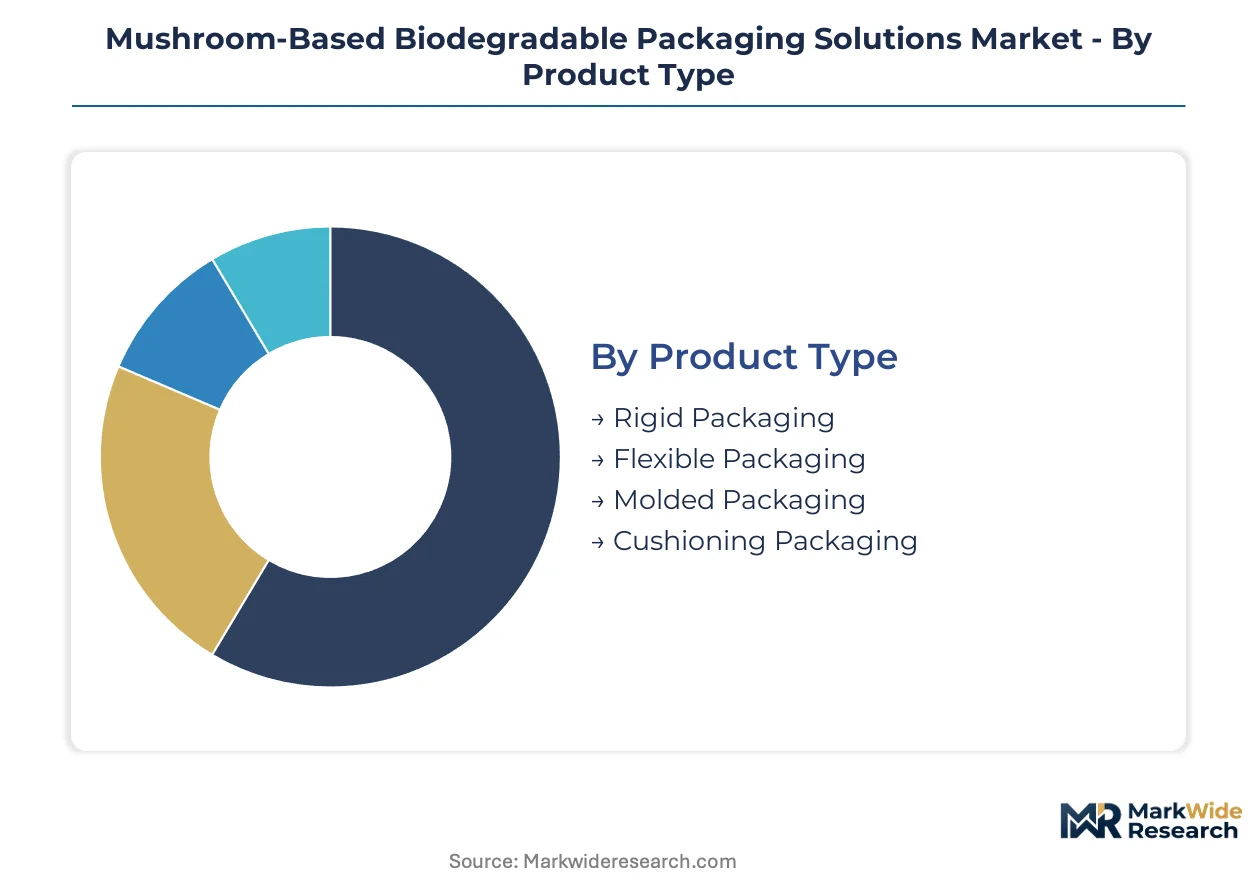
Mycelium packaging segments diverge sharply on certification requirements, with food-contact applications demanding EU EFSA and US FDA approvals while industrial protective formats navigate simpler BPI composting pathways. Understanding these compliance boundaries shapes portfolio prioritization for producers scaling across end-use verticals.
Product Type:
Certification burden varies dramatically across physical formats, with food-contact rigid packaging requiring the most extensive safety dossiers while cushioning materials face streamlined industrial composting verification only.
- Molded Packaging:Heat-pressed mycelium composites achieve compressive strength exceeding 200 kPa for electronics unboxing experiences and cosmetics gift sets. German consumer electronics brands in Berlin and Hamburg clusters now mandate molded formats for premium positioning, pulling capacity toward suppliers with in-house cultivation capabilities.
- Flexible Packaging:Laminated mycelium films with food-contact barriers are maturing for fresh produce wrapping and protein packaging. Coating technique advances enable moisture resistance above 70% relative humidity thresholds, though EFSA migration testing extends qualification timelines.
- Rigid Packaging:Molded containers for takeout applications require dual home and industrial composting certification under BPI and OK Compost protocols.
- Cushioning Packaging:Low-density mycelium foams at 0.05–0.15 g/cm³ densities replace expanded polystyrene in e-commerce void fill.
Molded packaging sits at the top of the volume ranking, with flexible packaging climbing the fastest as barrier coating technologies mature for food-contact deployment.
Technology:
Process selection determines capital intensity and geographic deployment feasibility, with heat pressing enabling distributed production while sterile spawn cultivation concentrates in specialized facilities.
- Mycelium Growth:Sterile spawn production on agricultural substrates like hemp hurds and corn stalks demands controlled-environment infrastructure and specialized fungal biology talent. New York State hosts the densest concentration of scaled grow facilities serving North American brand customers.
- Heat Pressing:Post-growth densification tunes mechanical properties through temperature and pressure parameters, enabling regional finishing facilities that reduce shipping volumes from cultivation sites.
- Compression Molding:Tooling-intensive forming for complex geometries requires precision mold fabrication and longer setup cycles.
- Spraying Coating:Barrier layer application for flexible formats remains technically immature with limited commercial scale.
Heat pressing commands the widest installed base, with mycelium growth operations expanding most quickly as brands seek captive supply security.
Application:
End-use selection dictates pricing power and contract duration, with electronics protection commanding multi-year agreements while food service operates on shorter renewal cycles tied to seasonal menu changes.
- Food Service:Quick-service restaurant chains in Germany and the Netherlands specify mycelium takeout containers in RFP requirements, creating guaranteed demand pools under EU Green Deal compliance mandates. Industrial composting infrastructure in France and Italy supports premium positioning against conventional alternatives.
- Electronics Protection:Unboxing experience redesigns by consumer electronics brands prioritize compressive strength and aesthetic surface finish for premium positioning.
- Consumer Goods:Gift set and houseware applications emphasize home compostability certification for sustainability messaging.
- Personal Care Products:Cosmetics packaging demands moisture resistance and fragrance barrier properties.
Electronics protection leads on contract value, with food service gaining share fastest as EU regulatory deadlines compress qualification timelines.
End User Industry:
Customer type determines technical specification depth and procurement engagement model, with specialty retailers demanding collaborative design iteration while e-commerce operators prioritize unit economics at volume.
- Fast-Moving Consumer Goods:Brand owners in personal care and packaged foods integrate mycelium packaging into sustainability roadmaps with multi-phase rollout schedules. Procurement teams mandate compostability certification as a non-negotiable vendor onboarding gate.
- E-commerce Warehousing:Void fill and protective applications prioritize cost parity with expanded polystyrene and polyethylene foams at scale.
- Specialty Retailers:Premium positioning justifies higher per-unit costs for differentiated unboxing experiences.
- Organic Product Manufacturers:Brand alignment with compostable packaging reinforces category positioning in health-conscious segments.
Fast-moving consumer goods dominates current revenue contribution, with e-commerce warehousing showing the steepest expansion trajectory as fulfillment networks retrofit for compostable alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions where EU Green Deal compliance costs create arbitrage opportunities for certified suppliers, while North American growers capture premium pricing through proximity to brand headquarters clusters.
Germany
Quick-service restaurant chains in Berlin and Hamburg now mandate mycelium-based takeout containers in procurement specifications, pulling production capacity toward certified suppliers. The EU Green Deal's Packaging and Packaging Waste Regulation establishes legally binding compostability benchmarks that domestic producers satisfy. Industrial composting infrastructure expansion in Bavaria and Baden-Württemberg creates captive end-of-life pathways justifying premium positioning.
United States
Consumer electronics brands in California specify heat-pressed mycelium composites for unboxing experience redesigns, prioritizing compressive strength exceeding 200 kPa. The EPA regulates compostability claims under FTC Green Guides, creating compliance clarity for interstate commerce. New York State hosts the densest concentration of scaled grow facilities serving North American brand customers through just-in-time delivery networks.
India
Sustainability-conscious retail segments in Mumbai and Bangalore create demand pull for imported mycelium packaging targeting premium organic product categories. BIS composting standards establish compliance pathways for exporters navigating the country's fragmented waste management infrastructure. Agricultural substrate abundance in Maharashtra and Gujarat provides regional feedstock advantages for domestic cultivation scale-ups.
Netherlands
Food service operators in the Randstad metropolitan corridor specify mycelium containers in RFP requirements, compressing supplier qualification timelines from years to months. REACH chemical registration requirements tighten scrutiny of synthetic additives, pushing formulators toward mycelium's inherently additive-free composition. The Eindhoven Region hosts pilot programs linking production scale-ups to brand collaboration facilities within 200-kilometer radii.
France
Cosmetics and electronics gift set segments in Île-de-France respond fastest to compostability mandates, locking in multi-year supply agreements to secure qualification status. The EU Green Deal's packaging waste directives accelerate material substitution away from expanded polystyrene in protective applications. Municipal composting facility expansion in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur creates infrastructure supporting industrial composting certification pathways.
Mushroom-Based Biodegradable Packaging Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent material science applications beyond core packaging formats. The supplier base organizes around three strategic archetypes: in-house cultivation specialists, contract manufacturing aggregators, and diversified packaging conglomerates offering mycelium alongside conventional lines. Competitive intensity concentrates on capacity expansion and certification velocity, with simultaneous pursuit of BPI and OK Compost protocols extending product launch cycles.
Among North American cultivation-focused enterprises, Ecovative anchors regional production capacity with dedicated grow facilities. Magical Mushroom Company occupies a position within the European contract manufacturing tier, leveraging distributed production to serve UK and EU brand customers. Sealed Air exemplifies the diversified packaging conglomerate archetype, competing through existing converter relationships rather than captive cultivation infrastructure.
| Leading Market Players |
|---|
| Ecovative |
| Magical Mushroom Company |
| Sealed Air |
| Vericool |
| MycoWorks |
| Grown.bio |
| Mushroom Material |
| BioFab |
| MYCO s.r.o. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between dual-certified food-contact formats and single-certified industrial cushioning creates distinct margin architectures that propagate backward through substrate sourcing and cultivation capacity deployment. Premium positioning attaches to BPI and OK Compost dual certification, commanding favorable terms from quick-service restaurant chains in Germany and the Netherlands under EU Green Deal procurement mandates. Commodity-tier cushioning for e-commerce void fill operates on spot-market agricultural substrate pricing with compressed distributor margins.
Pricing Analysis
Distributor margin layers in mycelium packaging compress as direct supplier relationships displace intermediary purchasing in food service and electronics verticals. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and barrier coating sophistication. Price differentiation hinges on dual home-industrial composting status and moisture resistance above relative humidity thresholds. Pricing pressure stems from agricultural substrate cost volatility tied to corn and hemp commodity cycles. Electronics protection buyers show least price sensitivity; e-commerce warehousing operators exhibit highest elasticity.
Supply Chain Analysis
Qualification gating through BPI and OK Compost protocols concentrates viable supply among certified cultivators in the United States, Germany, and the Netherlands. Raw material dependencies center on hemp hurd and corn stalk agricultural waste streams, supplemented by sterile spawn propagation infrastructure. Supply chain risk manifests as single-point vulnerability from North American capacity clustering in New York State. Distribution runs through just-in-time delivery networks serving Berlin, Hamburg, and California brand headquarters clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mushroom-based biodegradable packaging market functions as a stable compounder anchored by legally binding EU Green Deal substitution mandates that guarantee demand pools across member states.
For Market Incumbents: To counter input cost volatility from agricultural commodity cycles, secure long-term substrate supply agreements with Midwest corn processing cooperatives and Eastern European hemp fiber producers. Add dedicated sterile spawn production capacity in Baden-Württemberg or Bavaria to reduce trans-Atlantic logistics exposure and accelerate dual certification velocity for EU food service accounts. For New Entrants and Emerging Players: Food service contract manufacturers in France and Italy represent the most penetrable channel partner type for qualification-light market entry. Target industrial composting infrastructure corridors in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur where municipal facility expansion justifies premium positioning against home-compostable alternatives. Pursue private-label supply agreements with established converter networks rather than captive cultivation buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where sterile spawn production expertise concentrates among a limited pool of fungal biology specialists. The five-to-ten-year viability window favors acquisition of mid-tier cultivators with existing BPI certification and underutilized heat-pressing capacity. Watch for inflection when quick-service restaurant chains in Germany convert pilot programs to system-wide rollout specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Long-term hemp hurd contracts with Eastern European fiber processors lock in cost predictability against commodity volatility. |
| Dual Certification Investment | Simultaneous BPI and OK Compost pursuit opens EU food service procurement pools under Packaging and Packaging Waste Regulation deadlines. |
| Regional Cultivation Scale-Up | Baden-Württemberg facility deployment reduces logistics vulnerability from New York State concentration. |
| Barrier Coating R&D Partnership | Collaboration with lamination specialists enables moisture resistance above relative humidity thresholds for flexible food-contact formats. |
| Direct Brand Relationship Development | Bypassing distributor networks captures margin compression from procurement team mandates for compostability certification gating. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with packaging industry stakeholders and secondary source validation. Interview targets included sterile spawn production managers at cultivation facilities, procurement leads at German quick-service restaurant chains, sustainability officers at California consumer electronics brands, composting facility operators in France and Italy, and regulatory affairs specialists navigating EU Green Deal implementation. Secondary sources encompassed EPA compostability guidance documents, EFSA food-contact migration testing protocols, BIS certification standards for Indian market entry, customs trade data on agricultural substrate flows, and SEC filings from diversified packaging conglomerates. Bottom-up cultivation capacity modeling and top-down demand segmentation from end-use verticals were triangulated for convergence.
Segment-weighting approaches distributed value and volume estimates across product type, technology process, application vertical, and end-user industry dimensions. The analytical framework applied penetration curves and substitution elasticity parameters across the projection horizon, with CAGRs derived from segment-level growth rate blending. Industry-specific forecast inputs incorporated EU Green Deal compliance timeline acceleration, industrial composting infrastructure buildout schedules in target municipalities, and barrier coating technical maturity curves for flexible format commercialization.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to agricultural substrate price volatility and regulatory divergence on home versus industrial composting certification. Forecasts reflect documented assumptions on qualification timeline compression and brand procurement mandate adoption rates. A model refresh is warranted upon material change in EU member state implementation schedules for Packaging and Packaging Waste Regulation benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.