
 Asia-Pacific Biodegradable Film Market | 2026-2036
Asia-Pacific Biodegradable Film Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biodegradable Film Market Outlook
Specialty store distribution across Southeast Asia is fragmenting as e-commerce platforms and wholesale distributors capture bulk procurement contracts for biodegradable films. BASF SE leverages its Ludwigshafen-based R&D network to supply PLA formulations to Japanese food packagers. Kingfa Technology anchors domestic supply chains through its Guangzhou manufacturing complex, while Futamura Chemical Co., Ltd. specializes in cellulose-derived films for premium agricultural applications.
Asia-Pacific biodegradable film comprises polymer sheets engineered from polylactic acid, polyhydroxyalkanoates, starch blends, or regenerated cellulose, typically manufactured via blown film extrusion or cast film processes at thicknesses ranging from ultra-thin to thick gauges. These films decompose under industrial composting or soil burial conditions within defined timeframes, serving primarily as petroleum-based plastic replacements in packaging and agricultural mulch. PLA formulations currently dominate value generation due to favorable thermal properties and scalable fermentation feedstocks from corn and cassava. Starch-based variants compete aggressively on price in Indian and Chinese agricultural sectors where cost-per-hectare governs purchasing decisions. Cellulose films retain premium positioning in Japanese medical supply packaging where oxygen barrier performance justifies higher unit economics.
Japan's METI enforces strict biodegradability certification under JIS standards, while China's SAMR implements GB standards for compostable plastics that restrict non-degradable additives. India's BIS mandates testing protocols for carry bag and packaging film thickness that directly determine market access eligibility. Stakeholders must monitor evolving composting infrastructure gaps across Indonesia, Vietnam, and Thailand where collection and industrial processing capacity lags behind material supply expansion.
Market Dynamics
China's dual carbon goals and Japan's METI sustainability directives are compressing compliance timelines for biodegradable film formulations, forcing rapid retooling of extrusion lines and feedstock sourcing across the region's manufacturing base.
Growth Catalysts
- Compostable packaging mandates:China's GB standards for compostable plastics under SAMR enforcement are eliminating petroleum-based alternatives in food service applications across eastern manufacturing corridors.
- Agricultural mulch substitution:Starch-based films are capturing hectare-scale deployments in India's western industrial belt where cost-per-acre governs procurement decisions.
- Cellulose barrier performance:Regenerated cellulose films from Futamura Chemical satisfy oxygen permeability requirements for Japanese medical supply packaging under JIS certification protocols.
Market Restraints
- Cassava feedstock volatility:PLA fermentation input costs fluctuate with Southeast Asian cassava harvest cycles, compressing margin stability for blown film extruders.
- Industrial composting infrastructure gaps:Collection and processing capacity in Indonesia, Vietnam, and Thailand lags behind material supply expansion, creating end-of-life uncertainty.
- Thickness compliance friction:India's BIS testing protocols for carry bag gauge specifications create market access delays for imported film rolls.
Strategic Opportunities
- Underpenetrated Vietnamese processing zones:Export-oriented food packagers in northern Vietnam lack qualified local biodegradable film suppliers, creating white space for technical partnerships.
- E-commerce bulk procurement channels:Wholesale distributors are displacing specialty store networks across Southeast Asia, enabling direct mill-to-warehouse supply relationships.
- PHAs fermentation scale-up:Polyhydroxyalkanoates production from waste feedstocks converges with marine biodegradability requirements for aquaculture netting applications.
Industry Challenges
- Composting certification timeline compression:JIS and GB standard testing cycles extend 18-24 months, delaying product launches for reformulated resin grades.
- Extrusion technician scarcity:Blown film operators skilled in biopolymer temperature control and gauge uniformity command premium wages in China's Pearl River Delta cluster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biodegradable Film Market |
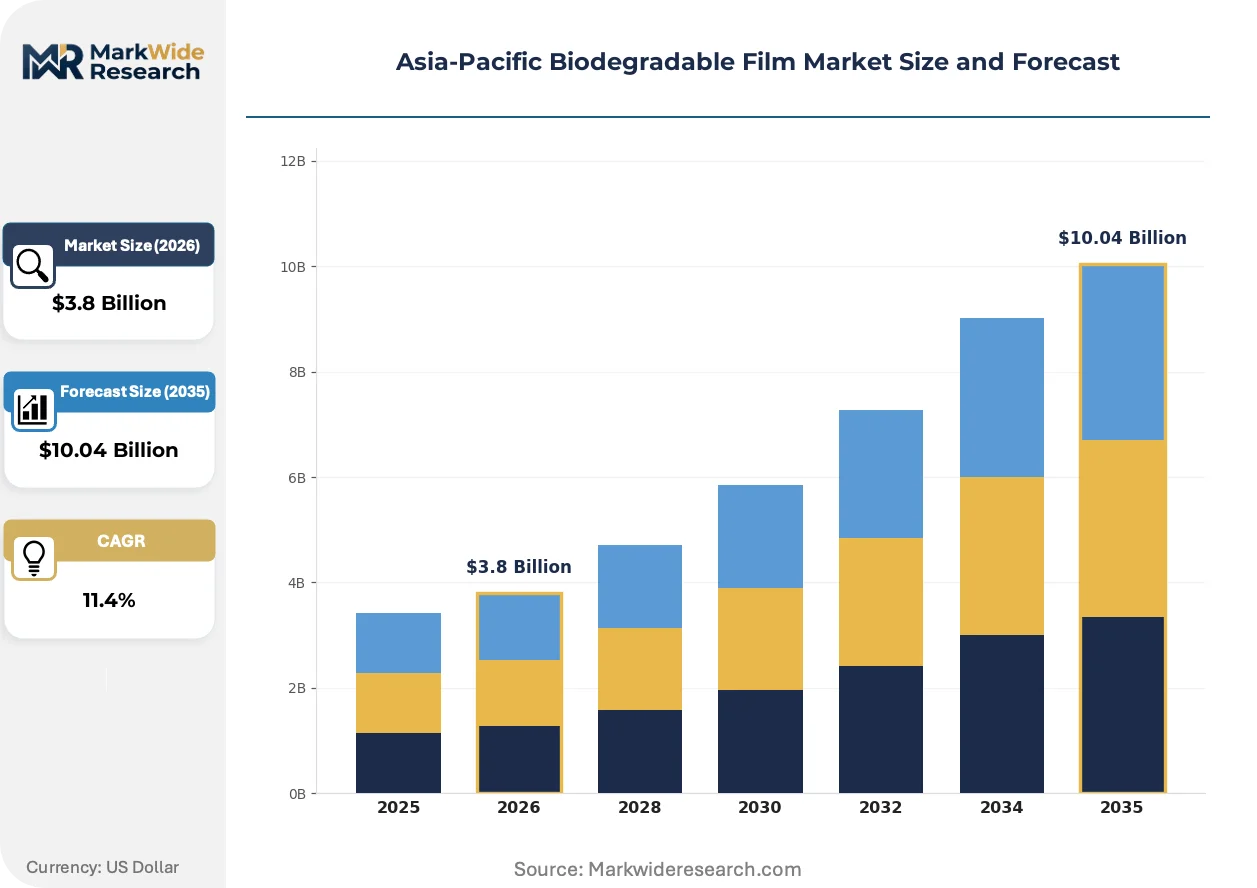
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-Based, Cellulose End User: Food Packaging, Agriculture, Pouches, Medical Supplies Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | BASF SE, Kingfa Technology, Futamura Chemical Co., Ltd., BioBag International, Taghleef Industries, Novamont S.p.A, RKW Group, Cortec Corporation, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biodegradable Film Market Strategic Shifts
Active reformulation of barrier properties and feedstock diversification is compressing the performance gap between biodegradable films and conventional petroleum-based alternatives across food, medical, and agricultural end-uses.
Multilayer co-extrusion technology is virtualizing the functionality of aluminum-oxide-coated films by embedding bio-based barrier layers within PLA substrates. Japanese medical packagers are adopting these structures for oxygen-sensitive pharmaceutical blister packs. The technology is virtualizing premium pricing tiers previously reserved for metallized petroleum films.
METI's updated JIS biodegradability certification requirements now mandate marine environment testing for films labeled as ocean-degradable. Japanese food exporters must recertify existing product lines by revised deadlines. Agricultural mulch suppliers are accelerating PHA development to meet the new saltwater degradation protocols.
Consolidation of procurement decisions into centralized sustainability offices is displacing fragmented buying across Asia-Pacific retail chains. Category managers now mandate compostability certification as a gate criterion for supplier qualification. This concentration is most visible in South Korean supermarket private-label programs where single-source film contracts cover multiple banner formats.
Asia-Pacific Biodegradable Film Market Segmentation
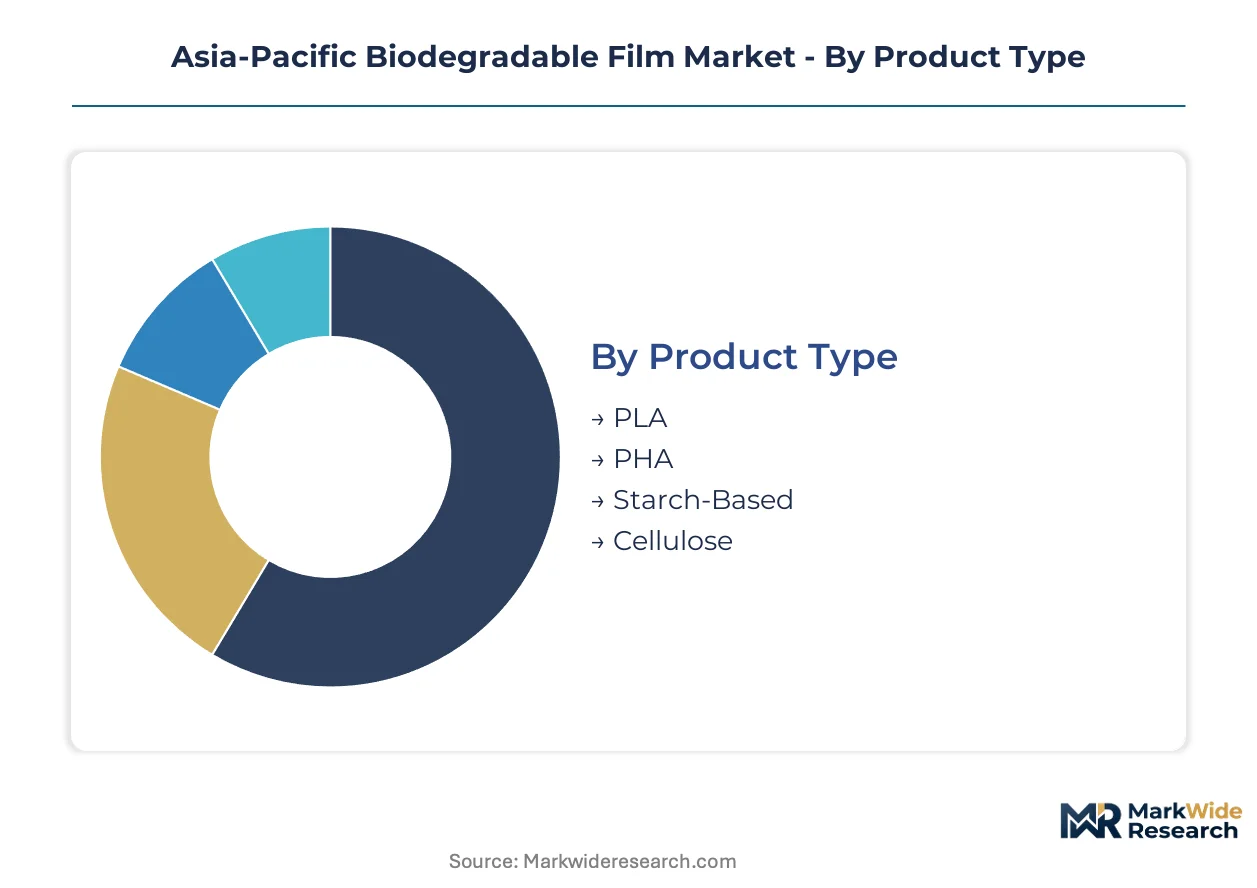
Segmentation in the Asia-Pacific biodegradable film market reveals distinct performance profiles across material chemistry, application intensity, and channel velocity. Understanding these divides allows suppliers to align extrusion capacity with the segments commanding premium pricing versus those driving volume throughput.
Product Type:
PLA formulations turn inventory fastest in China's eastern manufacturing corridor, while cellulose films sit longest in Japanese medical supply chains awaiting JIS certification cycles.
- PLA:Polylactic acid films dominate blown film extrusion lines across Guangzhou and Shanghai clusters due to scalable fermentation from corn and cassava feedstocks. Food packagers in China's Pearl River Delta specify PLA for thermal sealing performance in ready-meal trays under SAMR's GB compostable standards.
- Starch-Based:These formulations compete aggressively on cost-per-hectare in India's western agricultural belt where BIS thickness mandates govern mulch film procurement. Maharashtra and Gujarat farmers prioritize starch blends for single-season degradation in sugarcane and cotton fields.
- PHA:Polyhydroxyalkanoates production from organic waste feedstocks is scaling for marine-degradable aquaculture netting under Japan's updated METI saltwater protocols.
- Cellulose:Regenerated cellulose films from Futamura Chemical command extended production cycles for oxygen barrier specifications in pharmaceutical blister packs.
PLA anchors the volume base while PHA gains share at the steepest rate.
End User:
Cost tiers separate commodity agricultural applications from certified medical packaging where barrier performance justifies unit economics multiples above food service grades.
- Food Packaging:Compostable trays, wraps, and bags absorb the majority of PLA and starch-based film output across China, Japan, and South Korea. Centralized sustainability procurement at South Korean retail chains now mandates compostability certification as a gate criterion for supplier qualification.
- Agriculture:Mulch films in India's western industrial belt and Thailand's central plains prioritize rapid soil burial degradation over mechanical durability, compressing price points toward commodity levels.
- Pouches:Stand-up and flat pouches for dry goods concentrate demand in Vietnam's northern export processing zones where e-commerce fulfillment specifications drive thickness standardization.
- Medical Supplies:Oxygen-sensitive pharmaceutical packaging in Japan requires cellulose-derived barrier layers under JIS certification, extending validation timelines to 18-24 months.
Food packaging commands the widest extrusion capacity allocation while medical supplies extract the highest margin per kilogram.
Thickness:
Volume concentrates in medium gauges where blown film lines achieve optimal output rates, while ultra-thin specifications demand specialized cast film equipment with tighter tolerance control.
- Thin Film:10-25 micron gauges serve lightweight carry bag applications across India where BIS mandates minimum thickness for mechanical integrity. Mumbai and Ahmedabad converters balance gauge reduction against compliance testing costs.
- Medium Film:25-50 micron specifications dominate food tray lidding and agricultural mulch where tear resistance and degradation rate intersect at commercially viable price points.
- Thick Film:Above 50 micron gauges absorb punishment in industrial pallet wrapping and heavy-duty agricultural applications across Australia's horticulture sector.
- Ultra-Thin Film:Sub-10 micron specifications for premium cosmetic and electronics packaging concentrate in Japanese and South Korean precision cast film facilities.
Medium film absorbs the majority of resin throughput while ultra-thin commands the steepest per-kilogram premium.
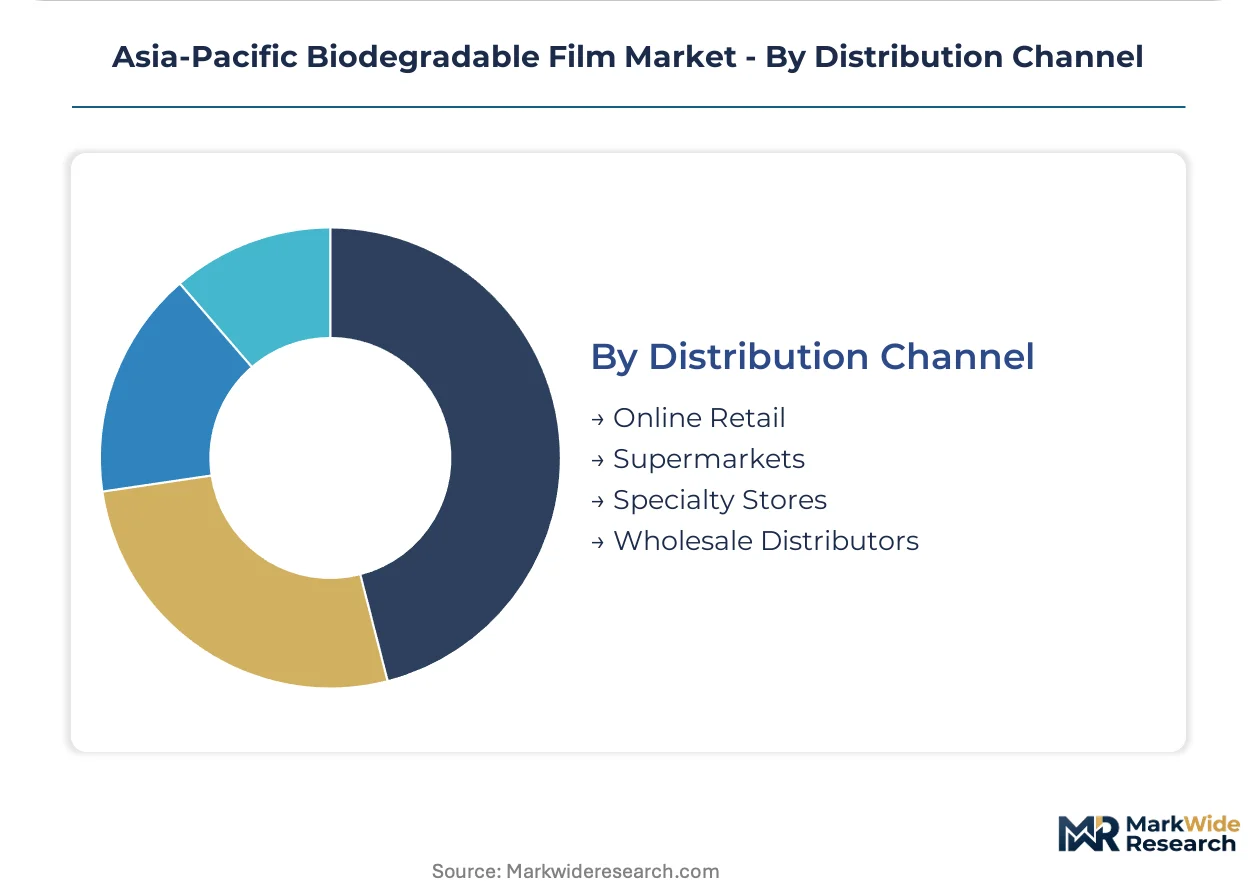
Distribution Channel:
Customer type fragmentation is collapsing as centralized procurement offices displace fragmented specialty store networks across Southeast Asia.
- Wholesale Distributors:Bulk procurement contracts now capture majority volume in Indonesia, Vietnam, and Thailand where mill-to-warehouse relationships bypass traditional tiered distribution. Bangkok and Jakarta distributors stock PLA and starch-based rolls for immediate converter delivery.
- Online Retail:E-commerce platforms aggregate small-batch orders from independent food service operators and agricultural cooperatives, compressing delivery timelines to 48-72 hours in China's tier-one cities.
- Supermarkets:Private-label sustainability mandates at South Korean and Japanese retail chains consolidate film sourcing through single-source contracts covering multiple banner formats.
- Specialty Stores:Technical film suppliers serving medical and premium agricultural niches retain relevance in Osaka and Tokyo clusters where JIS certification consultation accompanies product sales.
Wholesale distributors capture the volume base while online retail expands most quickly among small and mid-sized converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards enforcement anchors China's dominance in Asia-Pacific biodegradable film demand, compressing compliance timelines for extrusion lines across the eastern manufacturing corridor. Japan's METI directives and India's BIS thickness mandates reshape procurement patterns in parallel, while Southeast Asian export zones absorb overflow capacity.
China
Food packagers in the Pearl River Delta specify PLA formulations for ready-meal trays under SAMR's compostable plastic standards. The dual carbon goals accelerate line retooling in Guangzhou and Shanghai clusters. Kingfa Technology anchors domestic supply chains through its Guangzhou manufacturing complex.
Japan
Medical supply packagers demand cellulose-derived oxygen barriers for pharmaceutical blister packs under METI's updated JIS certification protocols. Futamura Chemical specializes in regenerated cellulose films for premium agricultural and medical applications. Osaka and Tokyo clusters retain specialty technical suppliers alongside certification consultation services.
India
Maharashtra and Gujarat farmers prioritize starch-based mulch films where BIS thickness mandates govern cost-per-hectare procurement decisions. Mumbai and Ahmedabad converters balance gauge reduction against compliance testing costs for carry bag applications. The western industrial belt captures the majority of agricultural film deployments.
South Korea
Centralized sustainability procurement offices at retail chains mandate compostability certification as a gate criterion for supplier qualification. Seoul-based supermarket private-label programs consolidate film sourcing through single-source contracts spanning multiple banner formats. Domestic converters serve food tray and pouch specifications under MFDS-aligned standards.
Vietnam
Export-oriented food packagers in northern processing zones lack qualified local biodegradable film suppliers, creating white space for technical partnerships. Ho Chi Minh City distributors stock imported PLA and starch-based rolls for immediate converter delivery. E-commerce fulfillment specifications drive thickness standardization for stand-up pouches.
Asia-Pacific Biodegradable Film Market Competitive Environment
Multinational chemical conglomerates and specialized biopolymer fabricators split the market along technology-licensing versus captive-manufacturing lines. The structure concentrates around three archetypes: fermentation-feedstock-integrated resin suppliers, blown-film extrusion specialists, and cellulose-regeneration experts. Capacity expansion and strategic partnerships dominate competitive moves as players secure composting certification across multiple jurisdictions.
Among German-headquartered chemical conglomerates, BASF SE exemplifies the resin-supplier archetype through its Ludwigshafen-based R&D network. Kingfa Technology occupies a position as a China-based fabricator anchoring domestic supply chains. Futamura Chemical Co., Ltd. represents the cellulose-specialist tier with Japanese medical and agricultural market positioning.
| Leading Market Players |
|---|
| BASF SE |
| Kingfa Technology |
| Futamura Chemical Co., Ltd. |
| BioBag International |
| Taghleef Industries |
| Novamont S.p.A |
| RKW Group |
| Cortec Corporation |
| Mitsubishi Chemical Group Corporation |
| Others |
Value Chain & Pricing Dynamics
Guangzhou's blown film extrusion clusters anchor Asia-Pacific biodegradable film supply, with Kingfa Technology's captive fermentation-to-film integration creating pricing power that downstream converters in Vietnam and Indonesia cannot replicate without JIS or GB certification investments.
Pricing Analysis
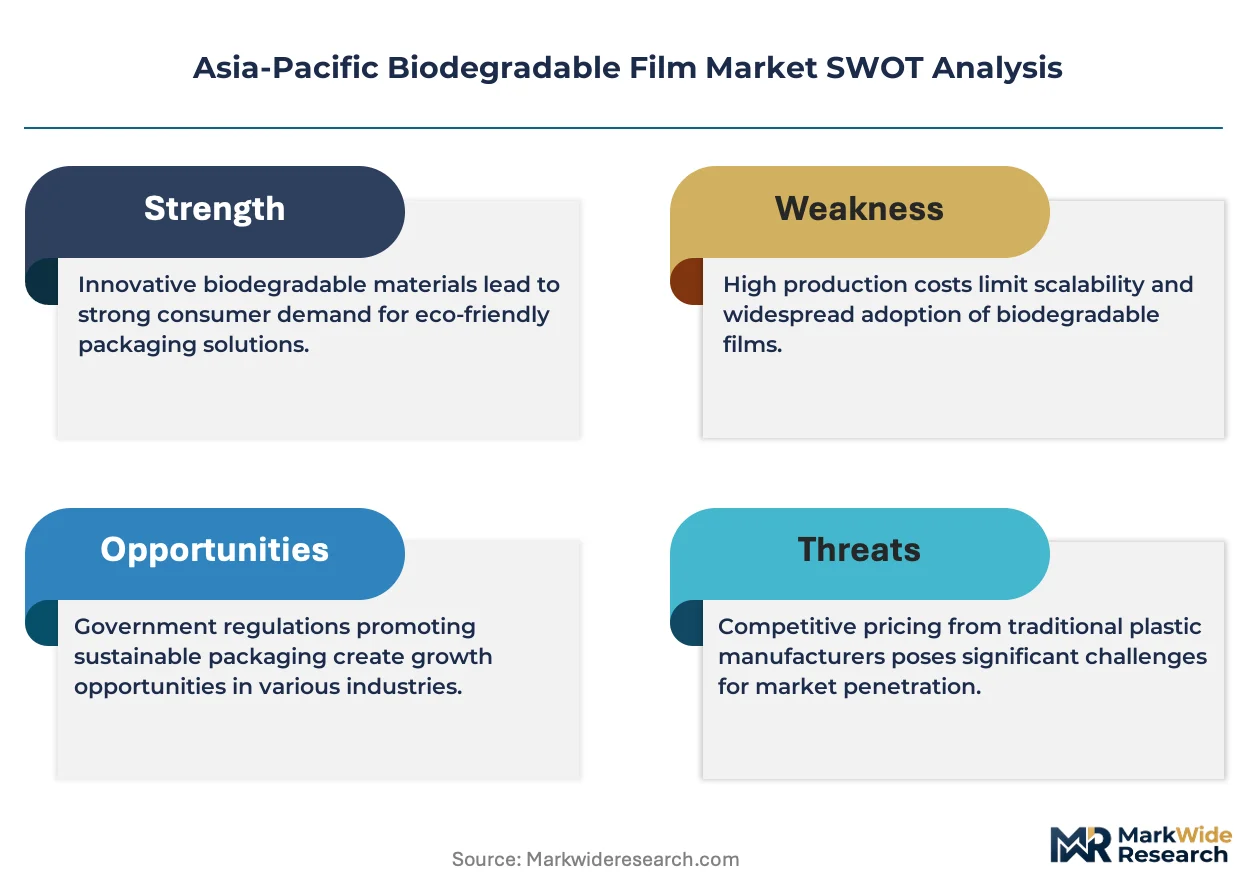
Price spreads between Chinese PLA rolls and Japanese cellulose films stretch across certification-grade tiers. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified medical grades from SAMR-compliant food service films and uncertified agricultural mulch. Pricing pressure stems from cassava feedstock volatility in Southeast Asian harvest cycles, compressing margins for non-integrated extruders. Agricultural buyers in India's western belt exhibit highest price sensitivity, while Japanese pharmaceutical packagers accept premium positioning for oxygen barrier performance.
Supply Chain Analysis
Export control regimes on fermentation technology from European licensors restrict PHA scale-up in Vietnamese and Indonesian processing zones. Supply concentrates in China's eastern corridor, Thailand's cassava belt, and Japan's cellulose regeneration facilities. Raw material dependencies center on corn starch, cassava chips, and dissolving pulp from Southeast Asian plantations. Single-source vulnerability runs through BASF's Ludwigshafen resin licensing network. Distribution runs through Bangkok and Jakarta wholesale distributors stocking PLA and starch-based rolls for immediate converter delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable film incumbents face substitution defense against petroleum-based plastic alternatives that retain cost advantages where composting infrastructure remains underdeveloped.
For Market Incumbents: Insulate certification portfolios by accelerating JIS and GB standard pre-approvals before METI and SAMR tighten biodegradability testing timelines. Backward integration into cassava fermentation secures margin control against Southeast Asian feedstock volatility. Channel control through direct mill-to-warehouse relationships with Vietnamese export packagers limits distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in northern Vietnam's export-oriented food processing zones where qualified local biodegradable film suppliers remain scarce. Technical partnerships with Ho Chi Minh City distributors bypass capital-intensive extrusion line investments. Marine-degradable PHA formulations for aquaculture netting exploit Japan's updated saltwater degradation protocols as a differentiated entry angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cellulose-specialist fabricators serving Japanese medical packaging with 18-24 month certification lock-in cycles. Long-term viability hinges on composting infrastructure build-out across Indonesia, Vietnam, and Thailand. Acquisition targets with captive GB or JIS certification pipelines command defensive moats. The inflection signal to watch is industrial composting capacity expansion announcements in Southeast Asian metropolitan waste management tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Fermentation | Captive PLA resin supply secures margin stability against Southeast Asian harvest volatility. |
| JIS Certification Pre-Approval Investment | Accelerated biodegradability testing timelines lock out competitors from Japanese medical packaging. |
| Mill-to-Warehouse Distribution Partnership | Direct supply relationships with Vietnamese export packagers displace tiered distributor networks. |
| Marine-Degradable PHA Scale-Up | Organic waste feedstock fermentation aligns with METI's updated saltwater degradation protocols. |
| Multi-Layer Co-Extrusion Technology Licensing | Bio-based barrier layers embedded in PLA substrates virtualize metallized petroleum film functionality. |
Study Parameters
A standing panel of blown film extrusion plant managers, SAMR compliance officers at Chinese food packagers, JIS certification consultants in Osaka, and procurement leads at South Korean retail chains provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings from resin suppliers, GB standard documentation from SAMR, and METI directive releases. Bottom-up extrusion capacity counts triangulated with top-down polymer consumption estimates across the analysis window.
Scenario-bracketing framed low, base, and high cases around composting infrastructure build-out velocity and cassava price volatility. Segmentation dimensions modeled include material chemistry tier, end-use application intensity, thickness gauge specifications, and distribution channel concentration. CAGRs derived from resin throughput projections and value-per-kilogram trends across certification grades. Industry-specific inputs incorporated BIS thickness mandate enforcement timelines and JIS testing cycle durations.
Sensitivities concentrate around SAMR enforcement intensity for GB standards, METI marine biodegradability protocol adoption, and industrial composting capacity commissioning delays. Forecasts reflect assumptions on regulatory compliance timelines and feedstock cost trajectories. Material shifts in Southeast Asian cassava harvest patterns or JIS certification requirement updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Plastic Bags and Sacks Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Biodegradable Food Packaging Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market