
 Asia-Pacific Biodegradable Paper and Plastic Packaging Market | 2026-2036
Asia-Pacific Biodegradable Paper and Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biodegradable Paper and Plastic Packaging Market Outlook
India's expanding production corridors for molded fiber and polylactic acid resins is reshaping supply availability across South and Southeast Asia. Amcor leverages integrated film extrusion and converting assets to sustain cost leadership in compostable flexible packaging. Mondi anchors European-Australasian technology transfer through its kraft paper innovation centers in the region. SCG Packaging dominates Thai domestic food service demand while extending biopolymer sourcing partnerships into Vietnamese manufacturing.
Asia-Pacific biodegradable paper and plastic packaging comprises materials engineered to decompose through microbial action within industrial composting or marine environments, typically incorporating polylactic acid, polyhydroxyalkanoates, or kraft paper substrates with moisture barriers below 2% water vapor transmission rates, serving primarily to replace petroleum-derived packaging in perishable goods distribution. Corn starch formulations lead material adoption due to established fermentation supply chains and price accessibility across ASEAN processing hubs. Food containers represent the fastest-expanding product category as quick-service restaurants and meal-kit platforms mandate fiber-based alternatives to expanded polystyrene. Bamboo-derived substrates occupy premium positioning within Japanese and Australian retail channels where certification requirements exceed baseline compostability standards.
China's SAMR enforces GB standards for biodegradable plastics labeling while India's BIS mandates testing protocols under the Plastic Waste Management Rules, collectively raising compliance costs for non-certified imports and redirecting procurement toward verified domestic suppliers. Japan's METI circular economy framework incentivizes packaging redesign through material efficiency benchmarks that favor lightweight paper-barrier structures. Stakeholders must monitor evolving interoperability between national certification schemes to avoid fragmentation of cross-border product registrations.
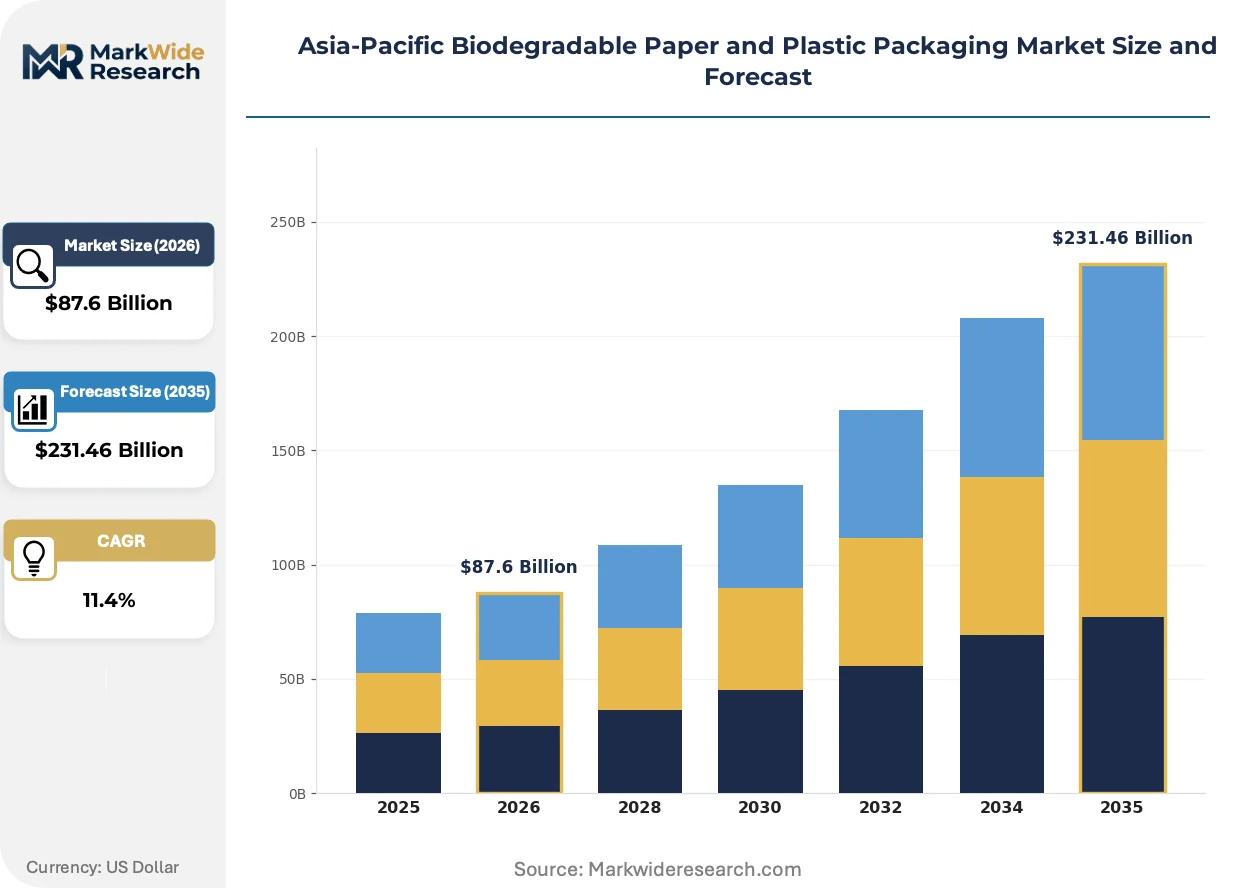
Market Dynamics
India's BIS certification mandates under the Plastic Waste Management Rules are compressing supply timelines for conventional plastic converters while redirecting procurement volumes toward verified domestic biopolymer producers.
Growth Catalysts
- Quick-service restaurant mandates:Major food chains across Southeast Asia now specify fiber-based containers in procurement tenders, creating guaranteed offtake for molded fiber producers in Vietnam's packaging export zones.
- China's dual carbon goals:Provincial MEE offices enforce GB standards for biodegradable labeling that disqualify petroleum-derived alternatives from government procurement catalogs.
- PLA fermentation scale-up:Thai and Indian corn starch processors are expanding polylactic acid resin capacity to serve ASEAN converting clusters.
Market Restraints
- Industrial composting infrastructure gaps:Vietnam and Indonesia lack certified composting facilities at scale, forcing exporters to rely on European or Japanese end-of-life verification.
- PBAT feedstock volatility:Butanediol prices fluctuate with Asian petrochemical cycles, squeezing margin predictability for film extruders.
- Import certification friction:India's BIS testing protocols add 8-12 week clearance delays for non-domestic biopolymer suppliers.
Strategic Opportunities
- Philippines food service penetration:Quick-service chains in Manila and Cebu remain underpenetrated by certified compostable packaging, offering first-mover positioning before anticipated EPR regulations.
- Bamboo-barrier premium tier:Japanese retail channels pay certification premiums for FSC-bamboo substrates with sub-2% moisture transmission, a specification few ASEAN suppliers currently meet.
- Japan's METI material efficiency incentives:Lightweight paper-barrier structures qualify for circular economy tax credits that reduce effective packaging costs for exporters.
Industry Challenges
- Cross-border certification interoperability:Divergent testing protocols between China's SAMR, India's BIS, and Japan's JIS standards force manufacturers to maintain multiple product variants.
- Molded fiber tooling lead times:Precision thermoforming equipment for sugarcane bagasse containers commands 14-18 month delivery schedules from European and Taiwanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biodegradable Paper and Plastic Packaging Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Bags, Compostable Films, Food Containers, Biodegradable Wraps End Use: Food Packaging, Consumer Goods, Healthcare, Retail Material: Corn Starch, Sugarcane, Bamboo, Recycled Paper Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Amcor, Mondi, International Paper Company, Huhtamaki, Oji Holdings Corporation, SCG Packaging, Ranpak Corp, Uflex, Tetra Pak, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biodegradable Paper and Plastic Packaging Market Strategic Shifts
Active barrier coatings derived from algae and chitosan are replacing petroleum-based moisture barriers while preserving compostability certifications. These material shifts are compressing the performance gap between fiber-based and plastic packaging.
Water-based barrier coatings is collapsing the cost premium between kraft paper and conventional flexible film. Quick-service chains in Thailand and Australia are specifying these coatings for hot-fill applications previously reserved for multilayer plastics. The technology is collapsing resistance among procurement teams who prioritized shelf-life performance over sustainability metrics.
India's Plastic Waste Management Rules mandate extended producer responsibility thresholds that phase in through 2024-2026 compliance windows. Brand owners must now register packaging formats with state pollution control boards and meet annual recycling targets. Food exporters targeting Maharashtra-Gujarat industrial corridors are reformulating specifications to qualify as biodegradable under BIS IS/ISO 17088 protocols.
Meal-kit platforms are consolidating supplier relationships around single-source compostable packaging contracts that bundle containers, films, and labels. This procurement compression eliminates multi-vendor coordination costs but raises switching barriers for incumbent converters. The pattern is most pronounced in Australian and Japanese urban markets where platform concentration exceeds 60% share of prepared meal distribution.
Asia-Pacific Biodegradable Paper and Plastic Packaging Market Segmentation
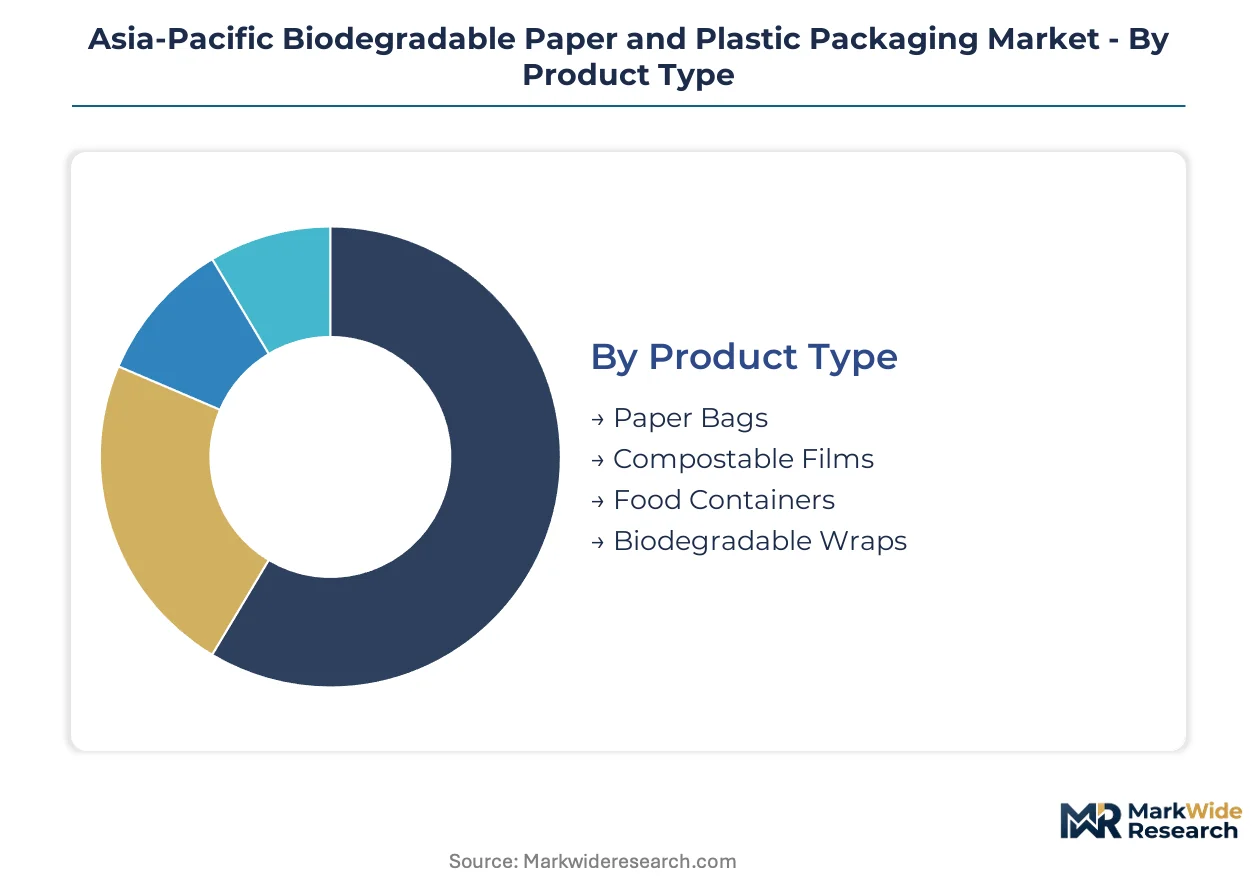
Segmentation in Asia-Pacific biodegradable packaging reveals how material specifications, channel economics, and end-use compliance requirements create distinct competitive arenas. Each dimension carries different margin profiles and certification burdens that reshape supplier priorities across the region.
Product Type:
Application requirements dictate performance thresholds and compostability certification paths across the four product categories.
- Food Containers:Molded fiber and bagasse structures with grease-resistant barriers serve quick-service restaurants and meal-kit platforms. Maharashtra-Gujarat industrial corridors concentrate manufacturing for export to ASEAN food service chains facing expanded polystyrene bans.
- Compostable Films:PLA and PBAT multilayer structures with sub-2% moisture vapor transmission rates replace conventional flexible packaging. Vietnamese packaging export zones drive demand as European importers mandate marine biodegradability verification.
- Paper Bags:Kraft paper with water-based coatings for retail carryout applications.
- Biodegradable Wraps:Thin-gauge films for produce and bakery overwrap in Japanese and Australian supermarket channels.
Food containers command the established base. The steepest expansion runs through compostable films.
End Use:
Customer compliance mandates and volume concentration create divergent procurement patterns across the four application sectors.
- Food Packaging:Perishable goods distribution requires barrier performance against oxygen and moisture while meeting BIS IS/ISO 17088 protocols in India and GB standards in China. Quick-service chains across Thailand and Vietnam now specify fiber-based alternatives in procurement tenders.
- Retail:Carryout and shopping bag applications face fragmented municipal regulations across Indonesian and Philippine cities.
- Consumer Goods:Electronics and personal care overwrap with lower barrier requirements.
- Healthcare:Sterile barrier applications with stringent validation protocols limiting biopolymer penetration.
Food packaging anchors volume concentration. Retail applications are climbing the fastest as municipal bans proliferate.
Material:
Feedstock availability and processing infrastructure determine regional supply economics for each substrate category.
- Corn Starch:Fermentation-derived PLA resins leverage established supply chains across Thai and Indian processing hubs. Corn starch formulations lead adoption due to price accessibility and scale in ASEAN converting clusters.
- Sugarcane:Bagasse fiber for molded containers serves food service demand with lower energy intensity than tree pulp. Thai domestic production extends into Vietnamese manufacturing through SCG Packaging partnerships.
- Bamboo:FSC-certified substrates occupy premium positioning in Japanese retail channels where certification requirements exceed baseline compostability standards.
- Recycled Paper:Post-consumer kraft pulp with water-based barrier coatings for cost-sensitive applications.
Corn starch anchors the supply base. Bamboo substrates are gaining share fastest on certification premiums.
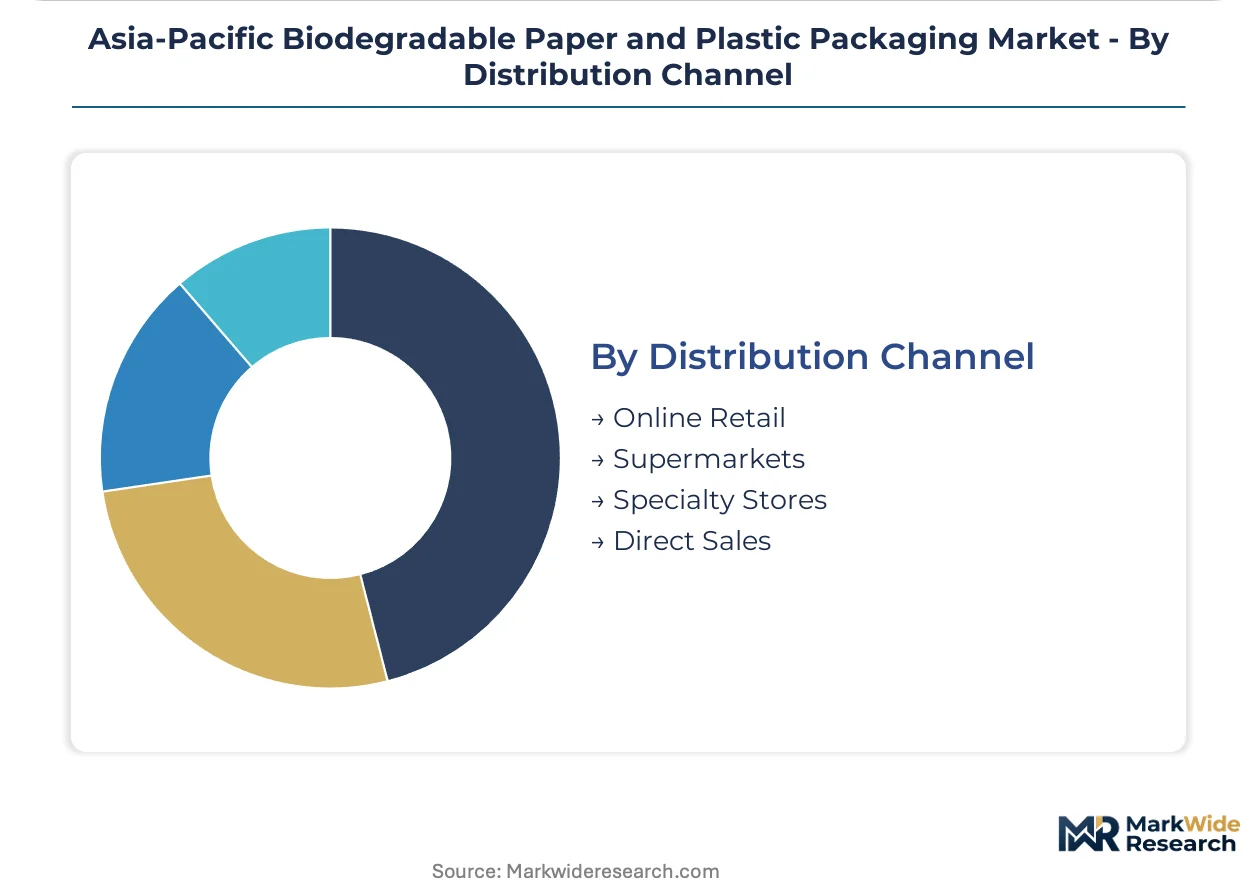
Distribution Channel:
Channel economics and customer technical support requirements fragment go-to-market strategies across the four pathways.
- Direct Sales:Large food chains and meal-kit platforms consolidate supplier relationships around single-source contracts bundling containers, films, and labels. Australian and Japanese urban markets show platform concentration exceeding 60% share of prepared meal distribution.
- Supermarkets:Private-label packaging procurement for produce and bakery departments.
- Specialty Stores:Premium organic and zero-waste retail channels with certification-conscious consumers.
- Online Retail:E-commerce fulfillment packaging with lower technical specifications and higher price sensitivity.
Direct sales commands the established base. Supermarkets show the steepest expansion trajectory as private-label specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors regulatory momentum across the Asia-Pacific biodegradable packaging landscape through its GB standards enforcement and dual carbon procurement mandates.
China
Provincial MEE offices disqualify petroleum-derived alternatives from government procurement catalogs under GB biodegradable labeling standards. Shanghai and Shenzhen municipal governments mandate compostable food containers in public sector catering contracts. Yangtze River Delta manufacturing clusters concentrate PLA film extrusion capacity to serve domestic quick-service restaurant chains.
India
Maharashtra-Gujarat industrial corridors drive molded fiber and polylactic acid resin production for export to ASEAN food service markets. BIS certification mandates under Plastic Waste Management Rules compress supply timelines for conventional plastic converters. State pollution control boards in Gujarat and Maharashtra enforce EPR registration deadlines that redirect procurement toward verified domestic biopolymer producers.
Japan
METI's circular economy framework incentivizes lightweight paper-barrier structures through material efficiency tax credits. Japanese retail channels pay certification premiums for FSC-bamboo substrates with sub-2% moisture transmission specifications. Kanto and Kansai metropolitan markets concentrate meal-kit platform demand exceeding 60% share of prepared meal distribution.
Vietnam
Packaging export zones in Ho Chi Minh City and Hanoi drive demand for compostable films with marine biodegradability verification for European importers. Quick-service restaurant procurement tenders now specify fiber-based containers, creating guaranteed offtake for molded fiber producers. Industrial composting infrastructure gaps force exporters to rely on Japanese or European end-of-life certification.
Thailand
Domestic corn starch processors expand polylactic acid resin capacity to serve ASEAN converting clusters. SCG Packaging dominates Thai food service demand while extending biopolymer sourcing partnerships into Vietnamese manufacturing. Bangkok metropolitan quick-service chains specify water-based barrier coatings for hot-fill applications previously reserved for multilayer plastics.
Asia-Pacific Biodegradable Paper and Plastic Packaging Market Competitive Environment
Integrated multinationals and regional converters split the market between scale-driven film extrusion and specialized fiber molding capabilities. Three archetypes dominate: global packaging conglomerates with captive resin supply, ASEAN-focused converters leveraging agricultural feedstock proximity, and Japanese-Australian premium specialists commanding certification premiums. Competitive moves concentrate on backward integration into fermentation-derived biopolymers and technology licensing partnerships for water-based barrier coatings.
Within the integrated multinational tier, Amcor and Mondi occupy positions that exemplify divergent geographic anchoring strategies. Amcor leverages Australian and Southeast Asian film extrusion assets to serve ASEAN quick-service restaurant procurement consolidation. Mondi anchors European-Australasian technology transfer through regional kraft paper innovation centers. Among Asia-Pacific specialists, SCG Packaging represents the agricultural feedstock-integrated archetype with Thai domestic dominance extending into Vietnamese manufacturing partnerships.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| International Paper Company |
| Huhtamaki |
| Oji Holdings Corporation |
| SCG Packaging |
| Ranpak Corp |
| Uflex |
| Tetra Pak |
| Others |
Value Chain & Pricing Dynamics
PBAT feedstock volatility compresses margin predictability for film extruders while simultaneously widening price spreads between premium-certified and economy-grade biodegradable packaging tiers across ASEAN converting clusters. This commodity-driven risk vector forces procurement teams to balance long-term offtake contracts against spot-market exposure, reshaping supplier selection criteria toward backward-integrated resin producers with captive butanediol supply.
Pricing Analysis
Price spreads between Indian domestic production and Vietnamese import-dependent supply stretch the widest in the region, with Maharashtra-Gujarat molded fiber commanding premiums over Ho Chi Minh City bagasse containers due to BIS certification velocity. Three-tier pricing structure across premium FSC-bamboo substrates, standard PLA films, and economy-grade recycled kraft separates buyers by certification tolerance and barrier performance requirements. Pricing pressure stems from Thai corn starch processors expanding fermentation capacity, eroding margin buffers for non-integrated converters. Quick-service restaurant procurement teams show highest price sensitivity, while Japanese meal-kit platforms absorb certification premiums for sub-2% moisture transmission specifications.
Supply Chain Analysis
Extended payment terms from Vietnamese packaging export zone buyers now stretch 90-120 days, forcing Thai biopolymer suppliers to leverage supply-chain finance facilities anchored in Bangkok commercial banking networks. Raw material flows concentrate across Thai corn starch fermentation hubs, Indian sugarcane bagasse processing corridors, and Chinese PBAT petrochemical complexes. Supply chain risk centers on single-source dependency for European-sourced precision thermoforming equipment with 14-18 month delivery schedules. Distribution runs through direct sales contracts with large food chains and supermarket private-label procurement desks, bypassing traditional distributor markups in Australian and Japanese urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compostable barrier formulation expertise remains scarce relative to procurement mandate velocity, creating a capability gap that favors early movers with in-house R&D infrastructure over pure-play converters dependent on licensed coating technologies.
For Market Incumbents: Harden defensible positions through captive PLA resin supply from Thai fermentation partnerships, insulating margin structures from butanediol price cycles that squeeze non-integrated film extruders. Accelerate BIS pre-certification for Maharashtra-Gujarat production lines before India's Plastic Waste Management Rules enforcement windows compress competitor supply timelines. Prioritize water-based barrier coating R&D to collapse cost premiums against multilayer plastic alternatives in Thai quick-service hot-fill applications. For New Entrants and Emerging Players: Build out Philippine food service penetration in Manila and Cebu ahead of anticipated extended producer responsibility regulations, securing first-mover positioning in an underpenetrated market with concentrated quick-service chain procurement. Target Vietnamese molded fiber production for European export markets requiring marine biodegradability verification, leveraging lower labor costs against Indian competitors facing BIS compliance overhead. Establish single-source compostable packaging contracts with emerging meal-kit platforms in Indonesian secondary cities. For Investors and Strategic Acquirers: India's 2024-2026 EPR compliance window reshapes the acquisition landscape toward verified domestic biopolymer producers with state pollution control board registrations already secured. Long-term viability hinges on backward integration into fermentation-derived feedstocks rather than petrochemical-dependent PBAT exposure. Monitor BIS testing protocol clearance velocity as the signal for which imported resin suppliers will retain market access versus facing 8-12 week disqualification delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Resins | Thai corn starch processors capture margin from PLA supply bottlenecks facing Vietnamese converters. |
| Water-Based Barrier Coating Scale-Up | Bangkok metropolitan quick-service chains displace multilayer plastics for hot-fill specifications. |
| BIS Pre-Certification Investment | Maharashtra-Gujarat producers lock in procurement preference before Plastic Waste Management Rules enforcement. |
| Marine Biodegradability Verification Partnership | Vietnamese exporters secure European importer compliance without domestic composting infrastructure. |
| Precision Thermoforming Equipment Forward Booking | Molded fiber producers secure 14-18 month delivery slots from European and Taiwanese suppliers. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with biopolymer procurement managers at ASEAN quick-service chains, fermentation plant managers at Thai corn starch processors, BIS certification consultants, and water-based coating R&D directors; alongside secondary validation through customs trade data, SEC filings of listed packaging multinationals, GB standards documentation from China's SAMR, and BIS testing protocol circulars. Bottom-up triangulation across resin production volumes, converting capacity utilization, and end-use procurement specifications was cross-checked against top-down market sizing.
Forecast inputs considered material segmentation across corn starch PLA, sugarcane bagasse, bamboo substrates, and recycled kraft grades; end-use concentration in food packaging, retail carryout, consumer goods overwrap, and healthcare sterile barriers; and distribution channel splits between direct sales, supermarkets, specialty stores, and online retail. CAGRs were derived from segment-level volume trajectories weighted by price realization trends across the projection horizon. Industry-specific inputs incorporated BIS compliance timeline phasing and METI material efficiency tax credit eligibility thresholds.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Thai fermentation specialists or accelerated BIS enforcement by Maharashtra pollution control boards would shift outcomes. Macroeconomic deviation in Asian petrochemical cycles, regulatory harmonization between China's SAMR and India's BIS protocols, or breakthroughs in algae-derived barrier coatings would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Biodegradable Packaging Products Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Biodegradable Cutlery Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Global Biodegradable Films Market
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
Biodegradable Packaging Materials Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market