
 Europe Biodegradable Film Market | 2026-2036
Europe Biodegradable Film Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biodegradable Film Market Foresight
Italy is rewriting competitive dynamics in European biodegradable film manufacturing as Novamont S.p.A leverages its home-market polymerization infrastructure and deep vertical integration. BASF SE anchors supply through its Ludwigshafen-based ecovio production platform. Futamura Chemical Co., Ltd. competes from its European converting assets with certified home-compostable cellulose grades.
Biodegradable film comprises polymer matrices engineered to mineralize under composting conditions within defined temperature and humidity parameters, typically achieving complete disintegration within industrial composting cycles. Polylactic acid dominates current volume due to mature fermentation feedstock supply chains and optical clarity matching conventional orientated films. Starch blends occupy the fastest-expanding niche as European converters seek cost-competitive alternatives to petroleum-derived barriers for short-shelf-life food packaging. Cellulose films retain premium positioning in high-barrier medical and pharmaceutical wrapping where grease resistance and dead-fold characteristics command margin pools.
The EU Green Deal, REACH compliance frameworks, and EN 13432 compostability certification collectively mandate measurable biodegradation timelines and heavy-metal thresholds, effectively filtering non-compliant imports from Asian suppliers. ECHA substance evaluation protocols further restrict certain plasticizers and additives, pushing formulation innovation toward bio-based plasticizer systems. Stakeholders must monitor pending revisions to the Packaging and Packaging Waste Regulation that could mandate minimum recycled and renewable content thresholds across all flexible packaging placed on the European market.
Market Dynamics
EU Green Deal mandates and F-Gas Regulation phase-outs are compressing adoption timelines for certified compostable packaging across European food and pharmaceutical supply chains. The regulatory pressure is forcing converters to requalify entire film portfolios within compressed windows.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for virgin petroleum-based plastics are redirecting brand procurement toward EN 13432-certified films for fresh produce and ready-meal applications.
- Industrial composting infrastructure expansion:Germany and the Netherlands are scaling anaerobic digestion and aerobic composting capacity, creating viable end-of-life pathways for PLA and starch-blend films.
- Supermarket private-label transitions:Discounters and premium grocers across France and Italy are mandating compostable packaging for own-brand organic product lines.
Market Restraints
- Lactic acid feedstock cost volatility:Corn and sugar beet prices fluctuate with agricultural commodity cycles, squeezing PLA resin margins and film converter pricing power.
- Asian import certification gaps:Non-EU suppliers face ECHA substance evaluation barriers and EN 13432 testing failures, limiting supply diversification.
- Barrier performance limitations:Biodegradable films exhibit inferior oxygen and moisture transmission rates versus conventional multilayer structures in extended-shelf-life applications.
Strategic Opportunities
- Eastern European packaging conversion:Poland and Romania host underdeveloped flexible packaging sectors where first-mover compostable film capacity can capture multinational brand regional supply contracts.
- Pharmaceutical blister pack substitution:Cellulose-based cold-form foils are penetrating European generic drug packaging as PVC-PVdC alternatives face REACH scrutiny.
- Mechanical recycling hybrid streams:Bio-based content mandates in pending Packaging and Packaging Waste Regulation revisions create pull for certified compostable films with detectable bio-based carbon content.
Industry Challenges
- Composting certification timeline compression:EN 13432 and OK Compost HOME testing protocols require 6-18 month validation cycles that mismatch quarterly brand procurement calendars.
- Multilayer coextrusion equipment reconfiguration:Existing blown film lines require screw and die modifications to process PLA and starch blends without thermal degradation, demanding capital deployment amid uncertain volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biodegradable Film Market |
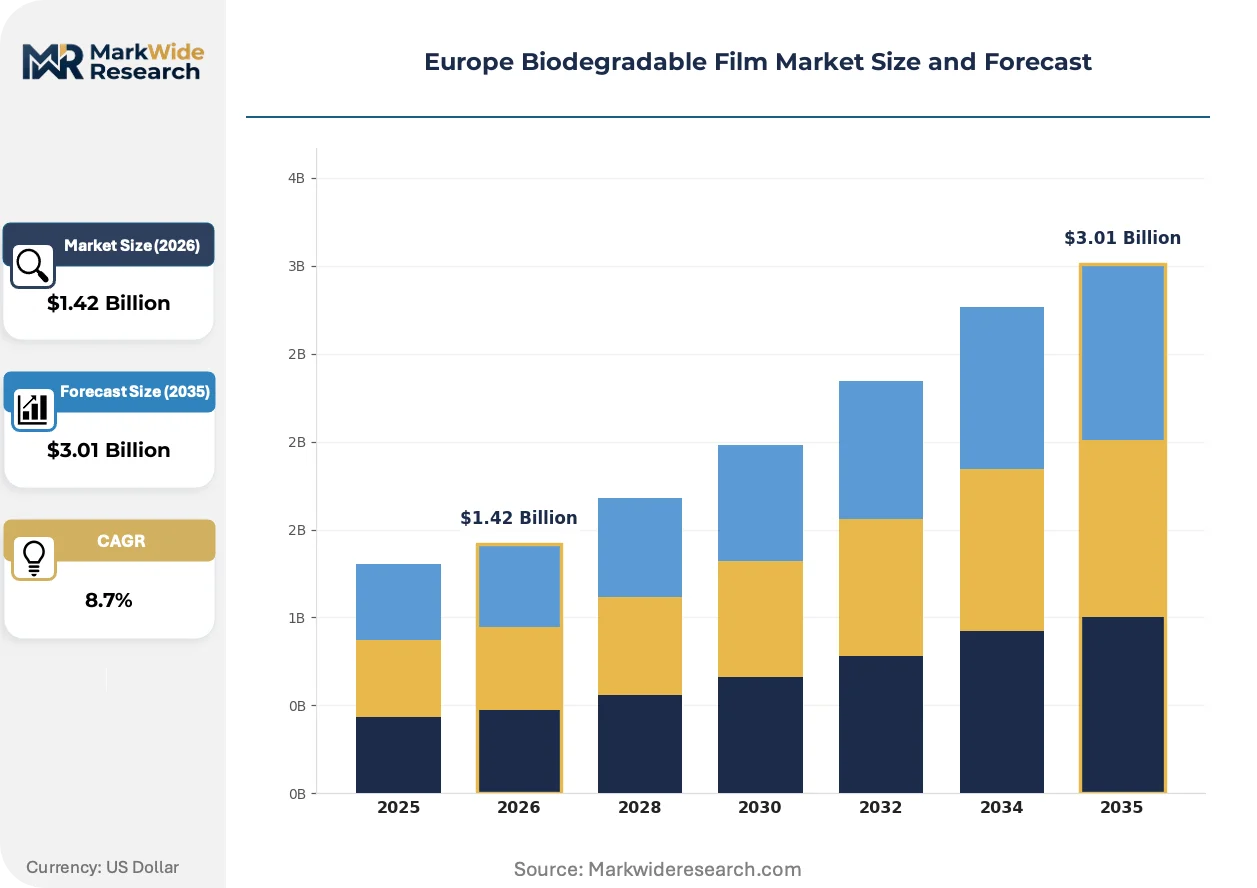
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Polyhydroxyalkanoates, Starch Blends, Cellulose Films, Aliphatic Polyester Application: Food Packaging, Agriculture Mulch Film, Consumer Goods Wrap, Industrial Packaging, Medical Packaging End User Industry: Food Processing, Agricultural Operations, Consumer Electronics, Pharmaceutical Firms, Manufacturing Plants Packaging Type: Rolls, Bags, Sheets, Pouches, Labels |
| Companies Covered | BASF SE, Novamont S.p.A, Futamura Chemical Co., Ltd., BioBag International, Tipa, Taghleef Industries, Innovia Films, RKW Group, Clondalkin Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biodegradable Film Market Shifts & Advancements
Digital traceability and bio-based formulation science are converging to reshape how European converters validate compostability claims and secure brand supply contracts. Material innovation cycles are compressing as regulatory deadlines approach.
Blockchain-enabled supply chain verification is digitizing certificate-of-origin documentation for bio-based feedstocks across European film manufacturing. Major food retailers in Germany and France are piloting QR-code-linked compostability credentials that authenticate industrial versus home-compostable grades at point-of-sale. This traceability layer is compressing due-diligence timelines for procurement teams and filtering uncertified imports from tender processes.
REACH substance evaluation protocols are restricting phthalate and certain epoxy-based additives in food-contact films, forcing reformulation toward bio-based plasticizer systems. ECHA's 2024-2025 rolling substance assessments are specifically targeting slip agents and anti-fog coatings used in fresh produce packaging. Converter technical service teams are accelerating migration testing for citrate and acetylated monoglyceride alternatives to maintain compliance windows.
Centralized purchasing consortiums among European supermarket chains are consolidating biodegradable film procurement into multi-year framework agreements with certified converters. This buyer concentration is displacing spot-market transactions and favoring suppliers with captive composting certification and vertically integrated resin supply. The shift is most visible in German and Dutch fresh produce packaging, where three retail groups now control majority category volume.
Europe Biodegradable Film Market Segmentation
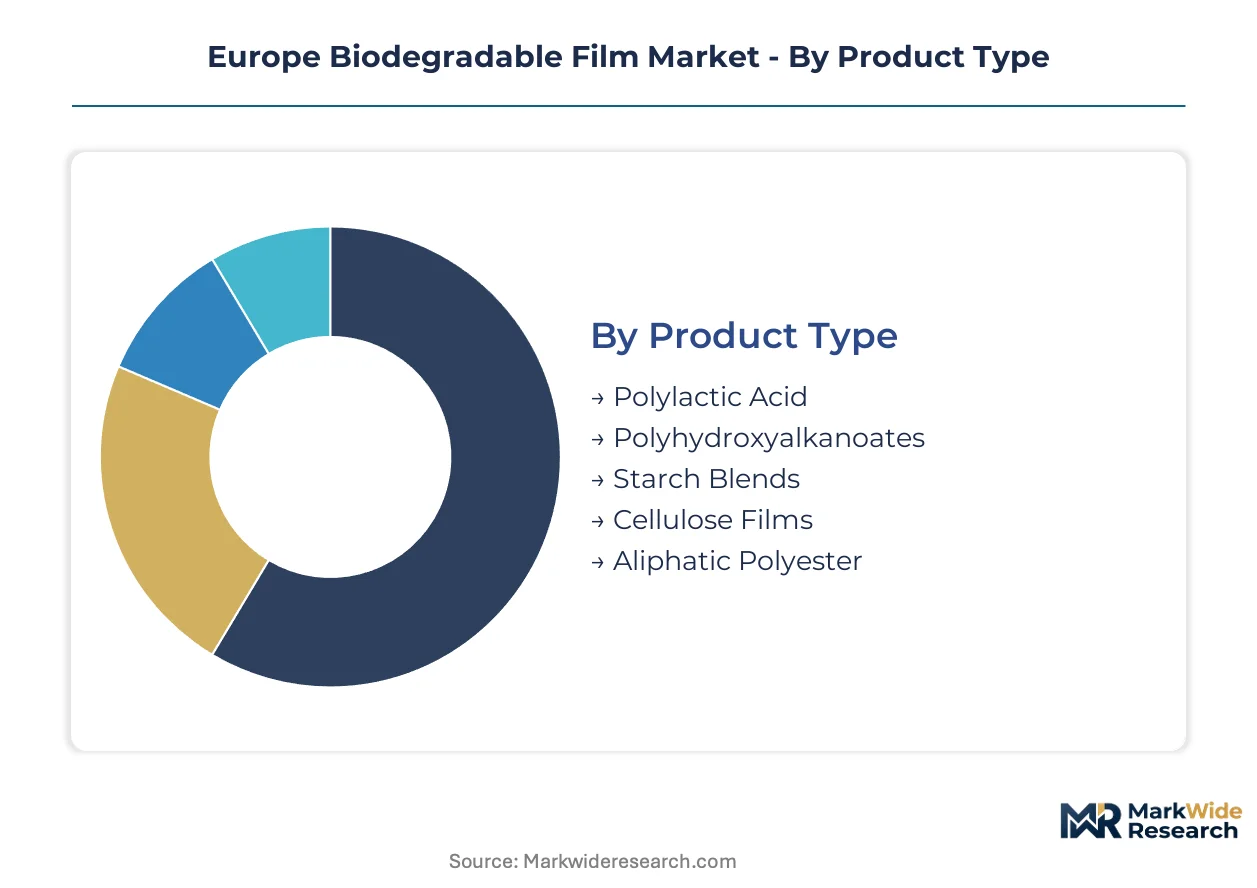
European biodegradable film procurement patterns diverge sharply across material chemistry, application stress requirements, and end-of-life infrastructure availability. Segmentation reveals how EN 13432 certification tiers and composting route economics reshape supplier selection and converter qualification timelines.
Product Type:
Use-case spectrum spans optical clarity demands in food display packaging through to soil-biodegradation requirements in agricultural mulch applications.
- Polylactic Acid:Fermentation-derived aliphatic polyester delivers glass-like transparency and heat-seal integrity comparable to conventional OPP films. German fresh produce converters favor PLA for breathable flow-wrap windows where shelf aesthetics drive purchase decisions.
- Starch Blends:Thermoplastic starch compounded with aliphatic polyesters creates cost-competitive blown films with moderate moisture barrier performance. Italian pasta and bakery packaging lines specify starch blends for short-shelf-life applications where rapid industrial composting is contractually guaranteed.
- Cellulose Films:Regenerated wood pulp matrices with premium dead-fold and grease resistance for pharmaceutical blister cold-form foils.
- Polyhydroxyalkanoates:Bacterial fermentation polymers with marine biodegradation credentials for coastal agriculture and aquaculture packaging.
- Aliphatic Polyester:Petroleum-derived but biodegradable polybutylene succinate grades bridging cost and performance gaps in industrial pallet wrap.
Established volume favors Polylactic Acid; emerging adoption favors Starch Blends.
Application:
Performance requirements escalate from single-use food contact through to multi-season agricultural durability and sterile medical barrier integrity.
- Food Packaging:Primary contact films for fresh produce, ready meals, and bakery goods requiring migration-compliant formulations under EFSA food contact regulations. French supermarket private-label mandates are compressing converter qualification timelines for certified compostable flow-wrap and lidding films.
- Agriculture Mulch Film:Soil-biodegradable films that eliminate retrieval labor costs while meeting EN 13432 biodegradation thresholds in soil environments. Spanish and Italian vegetable growers are scaling mulch film trials under EU CAP eco-scheme subsidies.
- Consumer Goods Wrap:Secondary packaging for cosmetics and personal care with premium tactile and print surface characteristics.
- Industrial Packaging:Pallet stretch wrap and protective films where load containment competes with compostability claims.
- Medical Packaging:Sterile barrier systems for surgical instruments and pharmaceutical devices requiring validated seal integrity and ethylene oxide sterilization compatibility.
Food Packaging commands current procurement volume; Agriculture Mulch Film is climbing the fastest under CAP incentive structures.
End User Industry:
Customer technical sophistication ranges from high-throughput food processing automation through to pharmaceutical validation protocols and seasonal agricultural purchasing cycles.
- Food Processing:Large-scale ready-meal and fresh-cut produce operations with automated form-fill-seal lines requiring consistent film gauge and coefficient of friction. Dutch and Belgian processors are consolidating biodegradable film procurement through centralized purchasing consortiums.
- Pharmaceutical Firms:Generic drug manufacturers seeking PVC-PVdC alternatives for European blister packaging under REACH substance restrictions. German and Swiss generic producers are qualifying cellulose-based cold-form foils for pediatric and geriatric dose packaging.
- Agricultural Operations:Specialty vegetable and soft-fruit growers with seasonal demand concentration and price sensitivity to petroleum-derived film alternatives.
- Consumer Electronics:Device manufacturers with anti-static and moisture barrier requirements for component shipping protection.
- Manufacturing Plants:Industrial goods producers with internal logistics wrap and protective film consumption.
Food Processing dominates contract value; Pharmaceutical Firms are gaining share fastest through REACH-driven material substitution.
Packaging Type:
Format selection dictates converting equipment compatibility, printing method, and end-consumer handling ergonomics across the value chain.
- Rolls:Master roll supply to downstream converters with slitting and printing capabilities. German and Polish flexible packaging converters prefer roll supply for in-house pouch and bag fabrication to capture margin and customize dimensions.
- Bags:Pre-formed carrier and produce bags with handle integration and venting features. French and Italian retail chains are mandating home-compostable certified bags for organic produce sections.
- Sheets:Flat die-cut or thermoformed trays for ready-meal and bakery presentation.
- Pouches:Stand-up and flat pouch formats for dry goods and liquid products with spout and reclosure features.
- Labels:Pressure-sensitive and in-mold labels with print receptivity and compostability certification for bottle and container decoration.
Rolls anchor converter supply relationships; Bags are expanding most quickly through retail private-label mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors regulatory momentum across European biodegradable film demand, with national implementation timelines diverging based on composting infrastructure maturity and retail procurement consolidation.
Germany
Industrial composting capacity expansion and supermarket private-label mandates drive film procurement from converters in the Rhine-Main and Ruhr industrial clusters. The F-Gas Regulation phase-out accelerates material transitions in fresh produce packaging. BASF SE's Ludwigshafen polymerization complex supplies PLA and ecovio grades to downstream flexible packaging operations.
Italy
Pasta and bakery packaging specifications favor starch-blend films with rapid industrial composting credentials under CAP eco-scheme subsidies. Novamont S.p.A leverages its Terni-based biopolymer infrastructure to serve domestic converters. The Po Valley agricultural belt generates concentrated demand for soil-biodegradable mulch films in vegetable cultivation.
France
Centralized retail purchasing consortiums mandate EN 13432-certified packaging for organic product lines across Carrefour and Intermarché supply chains. ECHA substance evaluation protocols restrict legacy additives in food-contact films. The Lyon-Grenoble corridor hosts specialist converters qualifying cellulose-based pharmaceutical blister alternatives.
Netherlands
Anaerobic digestion infrastructure expansion creates viable end-of-life pathways for PLA films in ready-meal packaging. Dutch food processors consolidate biodegradable film procurement through cooperative purchasing structures. The Rotterdam-Antwerp port cluster facilitates bio-based feedstock import logistics for regional resin production.
Spain
Vegetable grower cooperatives in Murcia and Almería trial soil-biodegradable mulch films under EU CAP incentive structures. REACH compliance barriers filter non-EU import competition in flexible packaging. Barcelona-based converters develop starch-blend formulations for short-shelf-life food applications with guaranteed composting collection.
Europe Biodegradable Film Market Competitive Landscape
Capability concentration sits with integrated resin producers; scale advantage sits with diversified chemical conglomerates with existing polymerization assets. The vendor base stratifies across three tiers: captive biopolymer producers with fermentation infrastructure, specialty film converters with composting certification, and regional packaging suppliers with retail private-label relationships. Dominant competitive moves include backward integration into lactic acid fermentation feedstocks and strategic partnerships with supermarket purchasing consortiums for multi-year supply frameworks.
Among integrated European producers, BASF SE and Novamont S.p.A exemplify the resin-forward archetype with captive polymerization and compounding capabilities. Futamura Chemical Co., Ltd. occupies a distinct position as a cellulose film specialist leveraging regenerated wood pulp technology for high-barrier pharmaceutical and food applications. These three entities represent divergent strategic postures: petrochemical diversification into bio-based grades, dedicated biopolymer pure-play focus, and natural polymer conversion expertise respectively.
| Leading Market Players |
|---|
| BASF SE |
| Novamont S.p.A |
| Futamura Chemical Co., Ltd. |
| BioBag International |
| Tipa |
| Taghleef Industries |
| Innovia Films |
| RKW Group |
| Clondalkin Group |
| Others |
Supply & Pricing Matrix
REACH substance evaluation chokepoints determine both three-tier pricing spreads across premium, standard, and economy certification levels and the geographic clustering of resin production. Lactic acid feedstock volatility feeds directly into PLA film converter margins, compressing pricing power for non-integrated players while rewarding backward integration into fermentation infrastructure.
Pricing Analysis
Italian starch-blend films trade at meaningful discounts to German PLA grades due to lower polymerization energy costs and CAP eco-scheme subsidies. Pricing stratifies across premium, standard, and economy tiers based on EN 13432 certification grade and composting route compatibility. Cost compression in standard-grade starch blends is intensifying because agricultural commodity cycles squeeze converter margins. Agricultural operations exhibit highest price sensitivity; pharmaceutical firms demonstrate lowest sensitivity due to REACH-driven substitution mandates.
Supply Chain Analysis
Lactic acid fermentation feedstock draws from corn and sugar beet cultivation concentrated in France, Germany, and Poland. Cellulose pulp inputs rest on Nordic and Brazilian forestry operations, while aliphatic polyester precursors hinge on petrochemical complexes in Belgium and the Netherlands. Single-source vulnerability sits with Novamont's Terni biopolymer complex for Italian domestic starch supply. Distribution runs through Rhine-Main and Rotterdam-Antwerp logistics clusters to downstream flexible packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EN 13432 certification creates defensive moats for early movers, as switching costs for brand requalification exceed twelve-month validation cycles. Network effects concentrate among integrated resin producers with captive composting certification infrastructure.
For Market Incumbents: Harden certification moats by accelerating OK Compost HOME validation for retail private-label mandates before pending Packaging and Packaging Waste Regulation revisions. Expand polymerization capacity in Ludwigshafen or Terni to capture lactic acid feedstock cost advantages. Lock in multi-year framework agreements with German and Dutch supermarket purchasing consortiums to foreclose spot-market competition.
For New Entrants and Emerging Players: Build out composting-certified converting capacity in Poland and Romania where multinational brand regional supply contracts remain contestable. Target pharmaceutical blister pack substitution as the most penetrable segment given REACH scrutiny on PVC-PVdC alternatives. Lead with cellulose-based cold-form foil technical service capabilities to differentiate from resin-integrated incumbents.
For Investors and Strategic Acquirers: Pending Packaging and Packaging Waste Regulation revisions reshape the acquisition landscape toward vertically integrated biopolymer producers with detectable bio-based carbon content capabilities. Five-to-ten-year viability favors resin-forward specialists over pure-play converters exposed to margin compression. Watch for ECHA substance evaluation protocol expansions targeting slip agents as the inflection signal for formulation innovation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactic Acid Fermentation | Captive feedstock supply insulates BASF and Novamont from agricultural commodity cycle volatility. |
| OK Compost HOME Certification Investment | Home-compostable credentials unlock French and Italian retail private-label procurement mandates. |
| Cellulose Cold-Form Foil Capacity Expansion | Pharmaceutical blister alternatives capture REACH-driven substitution away from PVC-PVdC structures. |
| Eastern European Converting Footprint | Polish and Romanian sites capture multinational brand regional supply contracts with shorter logistics loops. |
| Blockchain-Enabled Traceability Platform | German and French retailers pilot QR-code-linked compostability credentials to filter uncertified imports. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biopolymer plant managers, flexible packaging procurement leads at food processors, EN 13432 certification auditors, and supermarket category buyers; and secondary validation through ECHA substance evaluation protocols, EU customs trade data, Cefic chemical industry reports, and SEC filings from listed materials companies. Bottom-up resin production estimates and top-down packaging demand modeling were triangulated to reconcile volume figures.
Forecast inputs considered material chemistry segmentation, composting infrastructure maturity by member state, and application stress requirements across food packaging and pharmaceutical barrier grades. CAGRs were derived from regression analysis against EU Green Deal implementation timelines and F-Gas Regulation phase-out schedules. Modeled variables included lactic acid feedstock cost indices, industrial composting capacity buildout rates, and retail private-label transition velocities across the analysis window.
Stress conditions across agricultural commodity price bands, REACH substance evaluation expansion scopes, and composting certification timeline compressions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and infrastructure investment continuity. Cross-checking against ECHA rolling substance assessment calendars and national composting capacity disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Europe Biodegradable Cups Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Biodegradable Plastic Packaging Market
Biodegradable Packaging
Bioadhesives for Packaging Market
Biodegradable Packaging
Global Bioplastic Multi-Layer Films Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Asia-Pacific Biodegradable Film Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Biodegradable Water Bottles Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Bioplastic Packaging Bag Market