
 Starch-Based Bioplastics Packaging Market | 2026-2036
Starch-Based Bioplastics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Bioplastics Packaging Market Analytics
The capital-intensity divergence between integrated biopolymer producers and downstream converters is collapsing as scale thresholds for fermentation and compounding equipment fall. Novamont S.P.A leverages captive starch supply from Italian agricultural networks to control raw material costs across its Mater-Bi production chain. Cargill anchors North American demand through its NatureWorks joint venture, sustaining corn-derived PLA output for food packaging applications. BASF SE competes via its Ecovio starch-blend platform, positioning engineered biodegradability for industrial composting streams.
Starch-based bioplastics packaging comprises films, containers, and molded articles formulated from thermoplastic starch or starch-polymer blends, typically processed by extrusion or injection molding at moisture levels below fifteen percent to preserve mechanical integrity. These materials serve primarily as drop-in replacements for conventional polyethylene and polypropylene in single-use applications where end-of-life composting is accessible. Flexible packaging leads current volume due to its compatibility with existing blown-film lines and lower reformulation costs for brand owners. Rigid packaging represents the fastest-growing category as thermoforming and injection molding advances close the durability gap with fossil-based alternatives for food trays and cutlery. Starch blends concentrate margin pools where proprietary compatibilizer chemistry enables performance parity at reduced biopolymer loading rates.
The European Commission's Packaging and Packaging Waste Regulation shapes mandatory recyclability and compostability criteria, while FDA food-contact notifications govern starch-based film approvals in the United States and BIS certification requirements apply to biodegradable packaging claims in India. These frameworks collectively shift procurement specifications toward third-party-certified compostable grades and away from unverified biodegradable assertions. Stakeholders must monitor enforcement variance across national competent authorities and pre-position compliance documentation ahead of anticipated tightening of home-composting claim standards.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing reformulation timelines for converters as mandatory compostability certification replaces voluntary sustainability claims across member state procurement specifications.
Growth Catalysts
- EU Green Deal packaging mandates:Binding recycled content thresholds and biodegradability verification requirements are pulling food service operators toward certified starch-based alternatives ahead of enforcement deadlines.
- Industrial composting infrastructure expansion:Germany's anaerobic digestion network and Netherlands' organic waste separation programs are creating accessible end-of-life pathways that validate premium pricing for certified grades.
- Thermoplastic starch compatibilizer advances:Proprietary grafting chemistry is closing mechanical performance gaps with polyethylene in blown-film applications at reduced biopolymer loading rates.
Market Restraints
- Corn and potato starch price volatility:Agricultural commodity swings tied to weather patterns and biofuel diversion are compressing margin predictability for compounders without captive supply.
- Industrial composting facility concentration:Centralized processing capacity in Northern Europe leaves Southern and Eastern European markets with limited end-of-life infrastructure for certified products.
- Polyethylene mechanical property superiority:Fossil-based films retain cost-performance advantages in high-moisture and extended shelf-life applications where starch hydrophilicity degrades barrier function.
Strategic Opportunities
- Home-composting certification standardization:Anticipated tightening of EN 13432 home-composting claim protocols by ECHA creates first-mover advantage for validated film grades in premium retail channels.
- Flexible packaging-to-rigid packaging pivot:Thermoforming equipment upgrades at European converters are unlocking food tray and cutlery applications where durability specifications previously excluded starch blends.
- Agricultural waste feedstock integration:Cassava and rice starch valorization programs in Southeast Asian supply chains are diversifying raw material sourcing beyond corn-dependent North American networks.
Industry Challenges
- Compostability certification timeline compression:Third-party laboratory testing queues for TÜV Austria and DIN CERTCO verification are extending product launch cycles by six to nine months.
- Fermentation scale-up capital requirements:Commercial lactic acid and polyhydroxyalkanoate production facilities demand nine-figure investment thresholds that constrain mid-cap biopolymer producer expansion.
- Moisture-sensitive processing expertise scarcity:Extrusion operators with sub-fifteen-percent moisture control experience in thermoplastic starch compounding remain concentrated in Italian and German technical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Bioplastics Packaging Market |
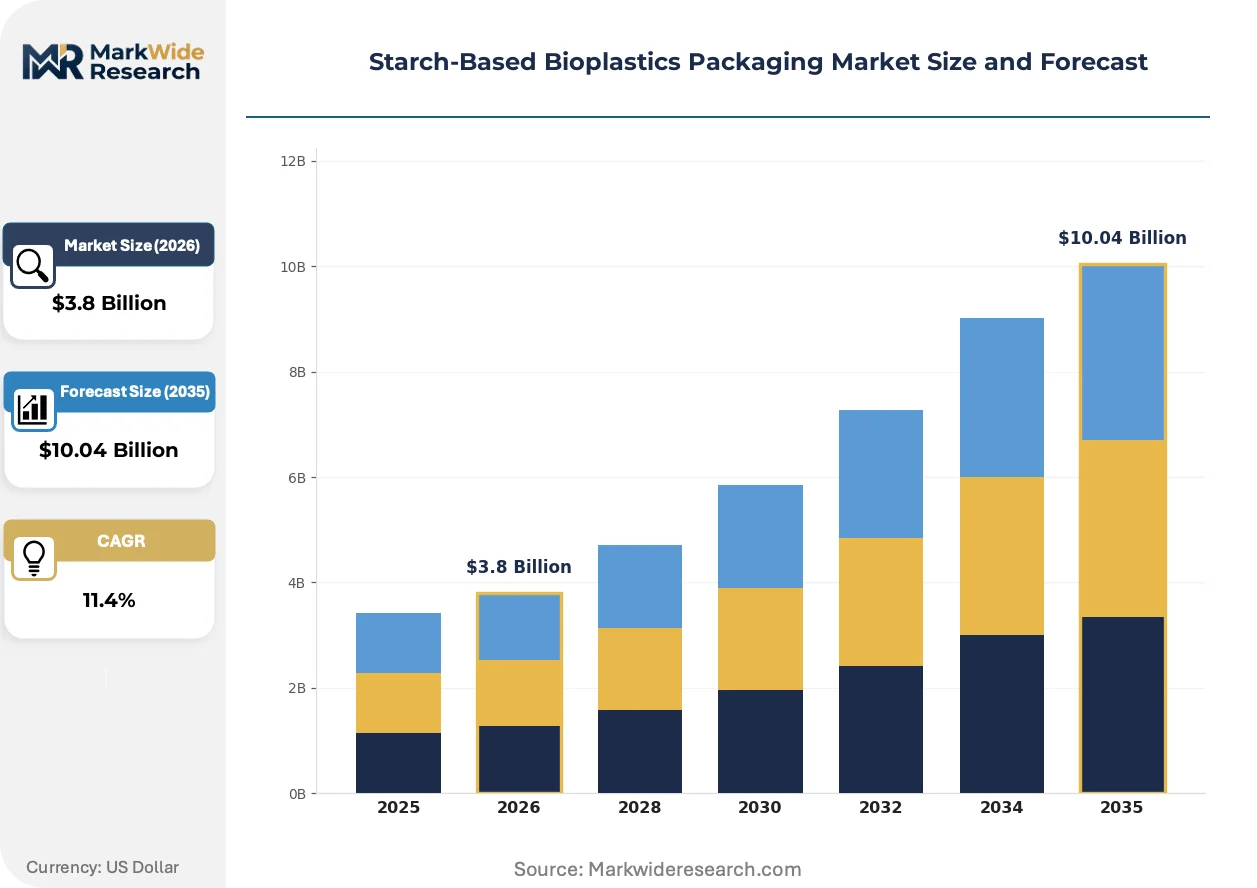
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Films, Containers End User: Food Industry, Consumer Goods, Pharmaceuticals, Agriculture Material: PLA, PHA, Starch Blends, Other Biopolymers Form: Granules, Sheets, Coatings, Extrusions |
| Companies Covered | Novamont S.P.A, Cargill, BASF SE, NatureWorks LLC, Biome Bioplastics Limited, Cardia Bioplastics Ltd, TotalEnergies Corbion, Green Dot Bioplastics, Plantic Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Bioplastics Packaging Market Evolving Landscape
Active reformulation of starch-polymer interfaces is collapsing the durability gap with fossil-based packaging while regulatory enforcement tightens verification standards for compostability claims.
Multilayer coextrusion technology incorporating thermoplastic starch tie layers is decomposing the historical trade-off between barrier performance and end-of-life compostability. European fresh produce distributors are adopting these structures for breathable film applications at accelerated pace. The technology is decomposing incumbent polyethylene's lock-in in modified atmosphere packaging where oxygen transmission rate specifications previously excluded biobased alternatives.
REACH authorization requirements for persistent organic pollutants in conventional plastic additives are redirecting food-contact film development toward starch-based formulations with inherently lower toxicity profiles. The industrial consequence is accelerated substitution in infant food and organic product packaging segments where contaminant thresholds are most stringent. French and German retailers are responding by mandating certified compostable primary packaging for private-label product lines ahead of regulatory deadlines.
Brand-owner sustainability scorecard integration is elevating certified compostability to a procurement gatekeeping criterion alongside cost and performance metrics. Food service management companies are displacing conventional procurement committees with dedicated circular economy sourcing functions that screen suppliers against third-party certification databases. This behavioral shift is most visible in Nordic markets where retailer consortiums have standardized compostability verification requirements across cooperative purchasing agreements.
Starch-Based Bioplastics Packaging Market Segmentation
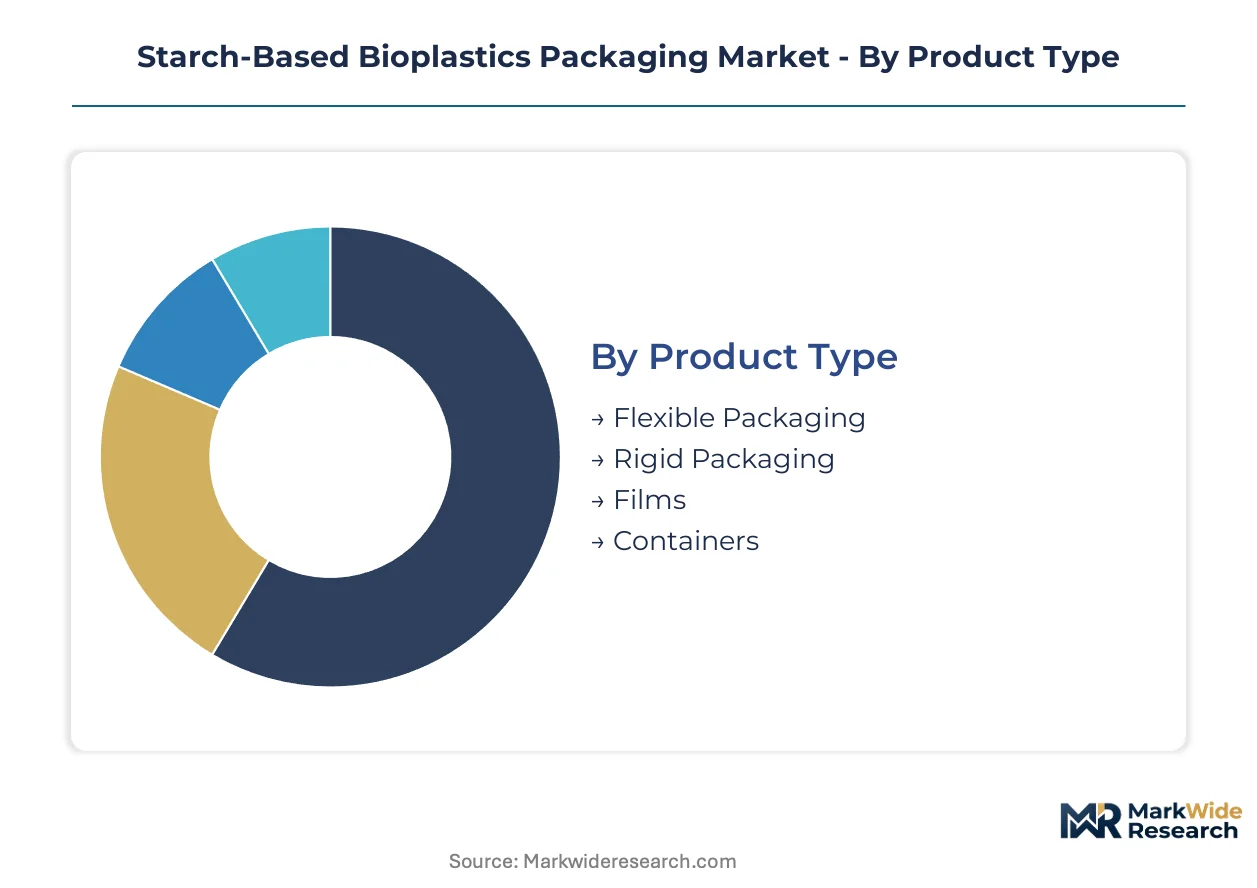
Segmentation in starch-based bioplastics packaging reveals how technical specifications, end-use requirements, and material chemistry intersect to determine commercial viability. Each dimension carries distinct regulatory and infrastructure dependencies that shape procurement patterns across European markets.
Product Type:
Flexible packaging dominates export-oriented production from Italian and German compounders, while rigid packaging growth concentrates in domestic food service supply chains serving quick-service restaurant networks.
- Flexible Packaging:Blown-film structures processed from thermoplastic starch blends at sub-fifteen-percent moisture levels serve produce bags and food wrap applications. German retailers are mandating certified compostable flexible formats for private-label organic lines ahead of EU Packaging and Packaging Waste Regulation enforcement deadlines.
- Rigid Packaging:Injection-molded trays and thermoformed containers leverage compatibilizer advances to close durability gaps with polypropylene. Netherlands-based food service distributors are expanding procurement specifications to include starch-based rigid formats for institutional catering contracts.
- Films:Monolayer and multilayer breathable structures for modified atmosphere packaging of fresh produce.
- Containers:Clamshells, cups, and deli containers targeting single-use food service applications with industrial composting access.
Flexible packaging holds the largest share; momentum sits with rigid packaging as thermoforming equipment upgrades unlock food tray applications.
End User:
Cost tier stratification separates premium-certified food-grade applications from standard industrial uses, with pharmaceutical and agricultural segments occupying narrower specification bands.
- Food Industry:Primary packaging for fresh produce, baked goods, and prepared meals requiring FDA or EFSA food-contact compliance. French supermarket chains are consolidating purchasing power to demand EN 13432-certified compostable packaging across cooperative procurement agreements.
- Consumer Goods:Non-food applications including cosmetic containers and household product overwrap where barrier requirements are less stringent.
- Pharmaceuticals:Blister packs and secondary packaging for solid-dose medications requiring moisture barrier validation and extractables testing under pharmacopeial standards.
- Agriculture:Mulch films, nursery pots, and controlled-release fertilizer coatings designed for soil biodegradation without industrial composting infrastructure.
Food industry applications command premium pricing tiers; consumer goods represent the steepest expansion trajectory as brand-owner sustainability scorecards elevate compostability to gatekeeping status.
Material:
Volume concentration in corn-derived supply chains creates geographic clustering, while cassava and potato starch alternatives diversify sourcing for risk-mitigation strategies.
- PLA:Polylactic acid derived from corn starch fermentation offers crystallinity control for heat-resistant applications. NatureWorks production in Nebraska supplies North American food packaging converters with consistent resin grades for thermoforming lines.
- PHA:Microbial polyesters produced through fermentation of agricultural feedstocks enable marine biodegradation certification. Danimer Scientific capacity expansion in Kentucky is targeting straw and cutlery applications where home-composting claims require validation.
- Starch Blends:Thermoplastic starch compounded with synthetic biodegradable polymers to balance cost and performance.
- Other Biopolymers:Cellulose derivatives and protein-based materials occupying niche pharmaceutical and luxury packaging segments.
Starch blends hold the largest share; PHA is climbing the fastest as marine biodegradability certifications open coastal market access.
Form:
Customer type segmentation separates compounders serving converters from converters serving brand owners, with form selection determining equipment compatibility and margin structure.
- Granules:Pelletized compounds ready for injection molding or extrusion processing. Novamont Mater-Bi granule supply to European converters enables just-in-time production without captive compounding capability.
- Sheets:Pre-extruded roll stock for thermoforming operations serving food tray manufacturers.
- Coatings:Aqueous or solvent-based barrier layers applied to paperboard substrates for grease resistance in fast-food packaging.
- Extrusions:Profile and film outputs from integrated producer-converter operations with captive blown-film lines.
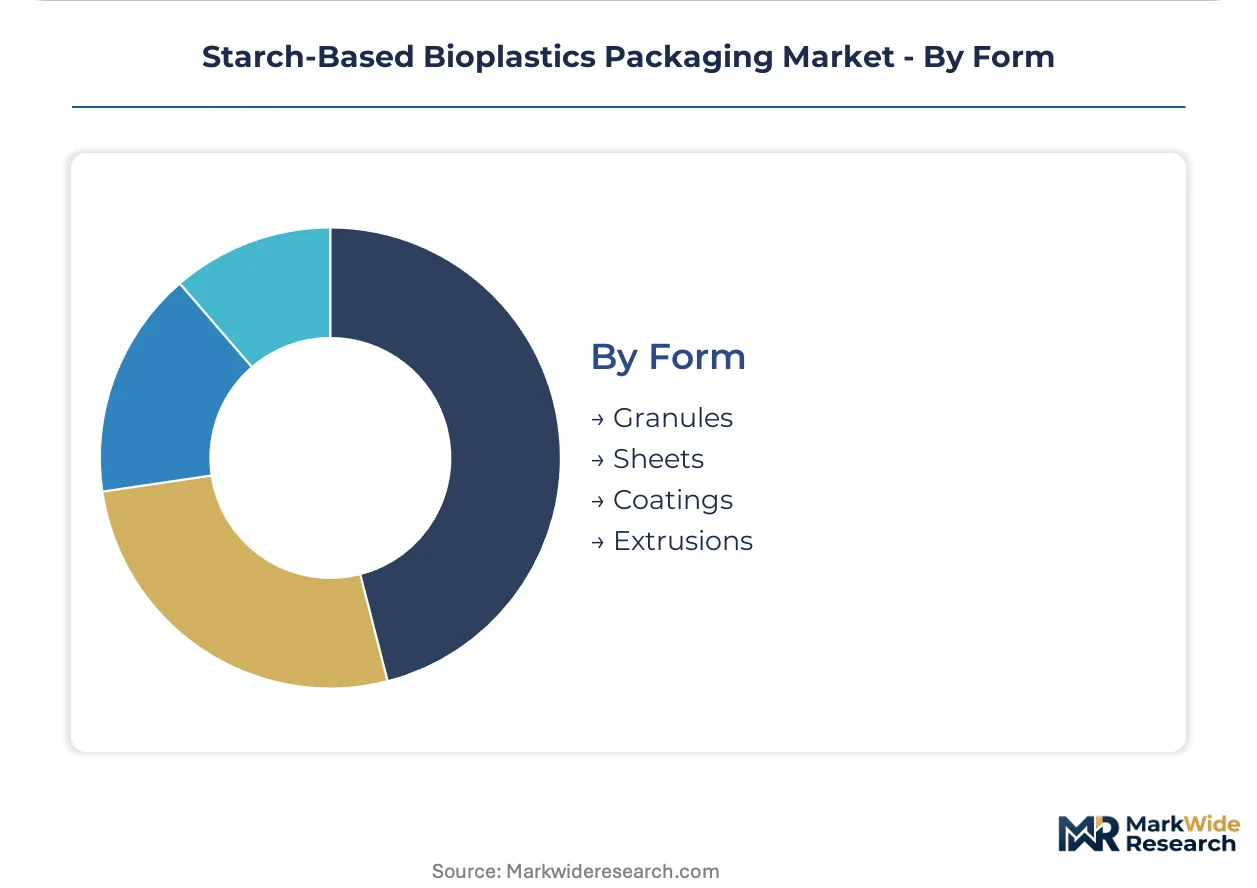
Granules hold the largest share; coatings are gaining share fastest as paperboard substrate compatibility expands addressable market for fiber-based food service containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes starch-based bioplastics packaging through industrial composting infrastructure, while the United States and India prioritize cost-driven food service applications with divergent certification requirements.
Germany
Food retailers and quick-service chains are expanding procurement of certified compostable trays and cutlery. The EU Packaging and Packaging Waste Regulation mandates recycled content thresholds that favor starch-blend formats. Industrial composting clusters around Cologne-Düsseldorf and Hamburg process certified waste streams at scale.
United States
Food service management companies are adopting compostable containers for corporate catering contracts. FDA food-contact notifications govern starch-based film approvals for fresh produce applications. NatureWorks operates fermentation capacity in Nebraska supplying PLA resin to Midwestern converters.
Italy
Novamont leverages captive starch supply from Po Valley agricultural networks for Mater-Bi production. REACH authorization requirements for persistent organic pollutants redirect film development toward starch-based alternatives. Compounding technical expertise concentrates in Novara and Terni industrial districts.
India
Food delivery platforms are piloting compostable packaging for quick-service restaurant partnerships. BIS certification requirements apply to biodegradable packaging claims in consumer markets. Cassava starch processing clusters in Kerala and Tamil Nadu diversify raw material sourcing beyond corn-dependent supply chains.
Netherlands
Organic waste separation programs create accessible end-of-life pathways for certified grades. EFSA compliance standards shape food-contact film specifications for fresh produce distribution. Rotterdam-Amsterdam logistics corridors enable just-in-time granule supply to European converters.
Starch-Based Bioplastics Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation scale and captive agricultural supply determining tier placement. The market structure concentrates margin pools where proprietary compatibilizer chemistry enables performance parity at reduced biopolymer loading rates. Three archetypes dominate: integrated biopolymer producers with captive starch supply, downstream converters with compounding expertise, and specialty compounders serving niche certification grades. Capacity expansion and strategic partnerships represent the dominant competitive moves as scale thresholds for fermentation equipment fall.
Within the integrated producer tier, Novamont S.P.A and BASF SE exemplify archetypes combining captive agricultural networks with proprietary blend platforms. Cargill occupies a position anchoring North American demand through joint venture structures. These three represent the scale-driven end of the market where fermentation capacity and raw material integration determine competitive positioning.
| Leading Market Players |
|---|
| Novamont S.P.A |
| Cargill |
| BASF SE |
| NatureWorks LLC |
| Biome Bioplastics Limited |
| Cardia Bioplastics Ltd |
| TotalEnergies Corbion |
| Green Dot Bioplastics |
| Plantic Technologies Limited |
| Others |
Value Network & Pricing Analysis
Fermentation capacity utilization above eighty percent in Italian and German biopolymer plants compresses unit economics and anchors price floors for certified compostable grades. This scale concentration grants integrated producers margin resilience against agricultural commodity swings while forcing mid-cap compounders toward tolling arrangements or backward integration into captive starch supply.
Pricing Analysis
After-sales certification renewal revenue from EN 13432 and TÜV Austria verification programs sustains lifetime value for compounders serving brand-owner procurement committees. Three-tier pricing structure across premium-certified, standard industrial, and economy non-certified grades reflects divergence in compostability validation depth and food-contact compliance tier. Cost compression in economy grades is intensifying as corn starch price volatility feeds through to spot resin markets. Quick-service restaurant chains exhibit highest price sensitivity, while organic retail private-label buyers accept premium positioning for validated home-composting claims.
Supply Chain Analysis
Italy and Germany anchor thermoplastic starch compounding capacity, while the United States feeds from NatureWorks fermentation output in Nebraska for PLA resin supply. Raw material sourcing draws from Po Valley corn networks, Midwest grain elevators, and emerging cassava processing clusters in Kerala. Single-source vulnerability concentrates in fermentation equipment supply, where European and Asian reactor fabricators face order backlogs extending installation timelines. Distribution runs through Rotterdam-Amsterdam logistics corridors for just-in-time granule delivery to European converters, with North American supply moving via rail-served Midwestern distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against fossil-based polyethylene and polypropylene incumbents, with mechanical property parity and composting infrastructure access determining competitive survival.
For Market Incumbents: Consolidate compounding technical expertise through acquisition of Italian and German mid-cap specialists with sub-fifteen-percent moisture control capabilities. Deepen backward integration into Po Valley or Midwestern agricultural networks to insulate margin structures from biofuel diversion-driven starch price spikes. Priority lever sits with pre-positioning home-composting certification documentation ahead of ECHA protocol tightening.
For New Entrants and Emerging Players: TÜV Austria certification fast-track programs unlock first-mover positioning in premium retail channels where French and German cooperative purchasing agreements are consolidating supplier pools. White-space targets concentrate in rigid packaging thermoforming for institutional catering contracts in the Netherlands and Belgium, plus cassava-starch-based film grades for Indian food delivery platforms. Go-to-market angle emphasizes marine biodegradability validation for coastal quick-service restaurant chains.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biopolymer producers with captive agricultural supply and proprietary compatibilizer chemistry. Long-term viability across the five-to-ten-year window rests on fermentation scale thresholds continuing to fall and industrial composting infrastructure expanding beyond Northern European clusters. Acquisition target archetype: mid-cap compounders with validated EN 13432 film grades and established relationships with retailer consortiums. Signal to watch is queue compression at DIN CERTCO and TÜV Austria testing laboratories as certification demand outpaces laboratory capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Supply | Captive corn and cassava starch sourcing insulates Novamont and Cargill from commodity volatility. |
| Home-Composting Certification Investment | EN 13432 validation ahead of ECHA protocol tightening secures premium channel access. |
| Thermoforming Equipment Upgrade Partnerships | Rigid packaging pivot unlocks food tray applications for Dutch institutional catering contracts. |
| Marine Biodegradability Validation | PHA-based grades with TÜV Austria marine certification access coastal quick-service restaurant chains. |
| Composting Infrastructure Joint Development | Collaboration with German anaerobic digestion networks validates end-of-life pathways for brand owners. |
Research Methodology
The analysis maps thermoplastic starch compounding, PLA fermentation, PHA production, and multilayer coextrusion processing segments, each validated through plant managers at integrated biopolymer producers, procurement leads at European food service distributors, technical R&D directors at compounders, and sustainability officers at retailer consortiums. Primary interview findings triangulate against customs and trade data for starch and biopolymer resin flows, SEC 10-K filings for publicly traded parent entities, Cefic and Plastics Europe industry association reports, and national packaging waste registry data. Bottom-up volume builds from named production facility capacities and utilization assumptions; top-down cross-checks against regulatory mandate-driven demand projections.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include product type, material chemistry, end-use industry, and regional composting infrastructure maturity. CAGRs derived from regression analysis of historical price-volume relationships and scenario-weighted regulatory enforcement timelines. Industry-specific forecast inputs incorporate EU Packaging and Packaging Waste Regulation implementation pacing and industrial composting facility commissioning schedules.
Underlying assumptions cover sustained enforcement of EU recycled content mandates, with deviation risk concentrated in home-composting certification standardization delays and agricultural commodity price spikes. Forecasts reflect these conditions with acknowledgment that Southern and Eastern European infrastructure gaps or fermentation scale-up capital constraints could revise trajectory. Recalibration cycles align with material shifts in regulatory enforcement variance across national competent authorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
North America Biodegradable Film Market
Biodegradable Packaging
Bioplastic Packaging Bag Market
Biodegradable Packaging
Middle East and Africa Biodegradable Film Market
Biodegradable Packaging
Biopolymer Packaging Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Bioplastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
North America Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Europe Biodegradable Film Market
Biodegradable Packaging
Biodegradable Packing Peanuts Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Biofoam Packaging Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
Global Biodegradable Tableware Market
Biodegradable Packaging
Biodegradable Packaging Materials Market