
 North America Biodegradable Film Market | 2026-2036
North America Biodegradable Film Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biodegradable Film Market Analytics
Price-performance divergence between premium certified-compostable films and commodity-grade biodegradable alternatives is rebalancing procurement patterns across North American supply chains. NatureWorks anchors biopolymer supply through its Blair, Nebraska PLA production complex, the largest of its kind on the continent. Danimer Scientific leverages microbial fermentation technology to sustain differentiated PHA resin output for high-barrier packaging applications. BioBag Americas competes through Nordic and BPI certification dominance in retail compostable bag channels.
Biodegradable film comprises thin-gauge polymer sheets engineered from renewable feedstocks such as polylactic acid, polyhydroxyalkanoates, or thermoplastic starch, designed to mineralize under industrial composting conditions within 180 days per ASTM D6400 standards; its primary purpose is to replace petroleum-derived flexible packaging in applications requiring end-of-life biodegradation. PLA formulations occupy the largest volume share given mature resin infrastructure, while PHA grades command premium positioning due to marine biodegradation credentials and broader composting acceptance. Foodservice applications generate the fastest growth trajectory as quick-service chains and institutional cafeterias face operational plastic bans across multiple U.S. states and Canadian provinces.
The U.S. Federal Trade Commission's Green Guides and California's SB 54 extended producer responsibility framework shape labeling compliance and market access requirements, while Canada's pending federal plastics registry under Environment and Climate Change Canada will mandate granular reporting on biodegradable product flows. ASTM D6400 and D6868 certification standards administered by the Biodegradable Products Institute function as de facto gatekeepers for municipal composting facility acceptance across the continent. Stakeholders must monitor evolving state-level definitions of biodegradability, as conflicting regulatory thresholds between industrial and home composting environments threaten to fragment product specifications and testing protocols.
Market Dynamics
California's SB 54 extended producer responsibility framework is redirecting procurement budgets toward certified compostable materials, forcing converters to requalify resin supply chains around BPI certification standards. Foodservice operators across the United States and Canada face operational plastic bans that compress switching timelines from conventional films to biodegradable alternatives.
Growth Catalysts
- State-level plastic bans:California, New York, and Washington have enacted operational prohibitions on conventional plastic wrap in foodservice settings, mandating ASTM D6400-certified alternatives for institutional procurement.
- Industrial composting infrastructure:Municipal facilities across the Great Lakes corridor are expanding acceptance capacity for certified biopolymer films, reducing end-of-life friction for foodservice packaging.
- PHA marine biodegradation credentials:Polyhydroxyalkanoate formulations meet broader composting acceptance standards than PLA alternatives, opening coastal markets where marine litter concerns dominate regulatory attention.
Market Restraints
- Resin supply concentration:NatureWorks' Blair, Nebraska facility anchors North American PLA production, creating geographic single-point vulnerability for converters dependent on corn-derived feedstock supply.
- Certification cost burden:ASTM D6400 and D6868 testing protocols administered by the Biodegradable Products Institute impose fixed compliance costs that disproportionately burden small-volume film converters.
- Performance gaps in high-barrier applications:Oxygen and moisture transmission rates in thermoplastic starch formulations limit replacement potential for meat and cheese packaging requiring extended shelf life.
Strategic Opportunities
- Canadian federal plastics registry:Environment and Climate Change Canada's pending granular reporting mandate will create first-mover advantage for suppliers with established biodegradable product flow documentation.
- Home composting certification gap:No North American standard currently validates home composting performance, creating white space for ASTM D6400-plus formulations that mineralize in backyard conditions.
- Quick-service chain central procurement:National restaurant operators are consolidating flexible packaging purchasing through sustainability scorecards, favoring certified suppliers with verified lifecycle data.
Industry Challenges
- Composting facility contamination protocols:Municipal operators reject film loads with visible conventional plastic residue, requiring foodservice buyers to implement staff training programs that slow rollout velocity.
- Resin-to-film processing skill scarcity:Thermoplastic starch and PHA formulations require modified extrusion parameters compared to polyethylene, constraining converter capacity expansion without specialized technical hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biodegradable Film Market |
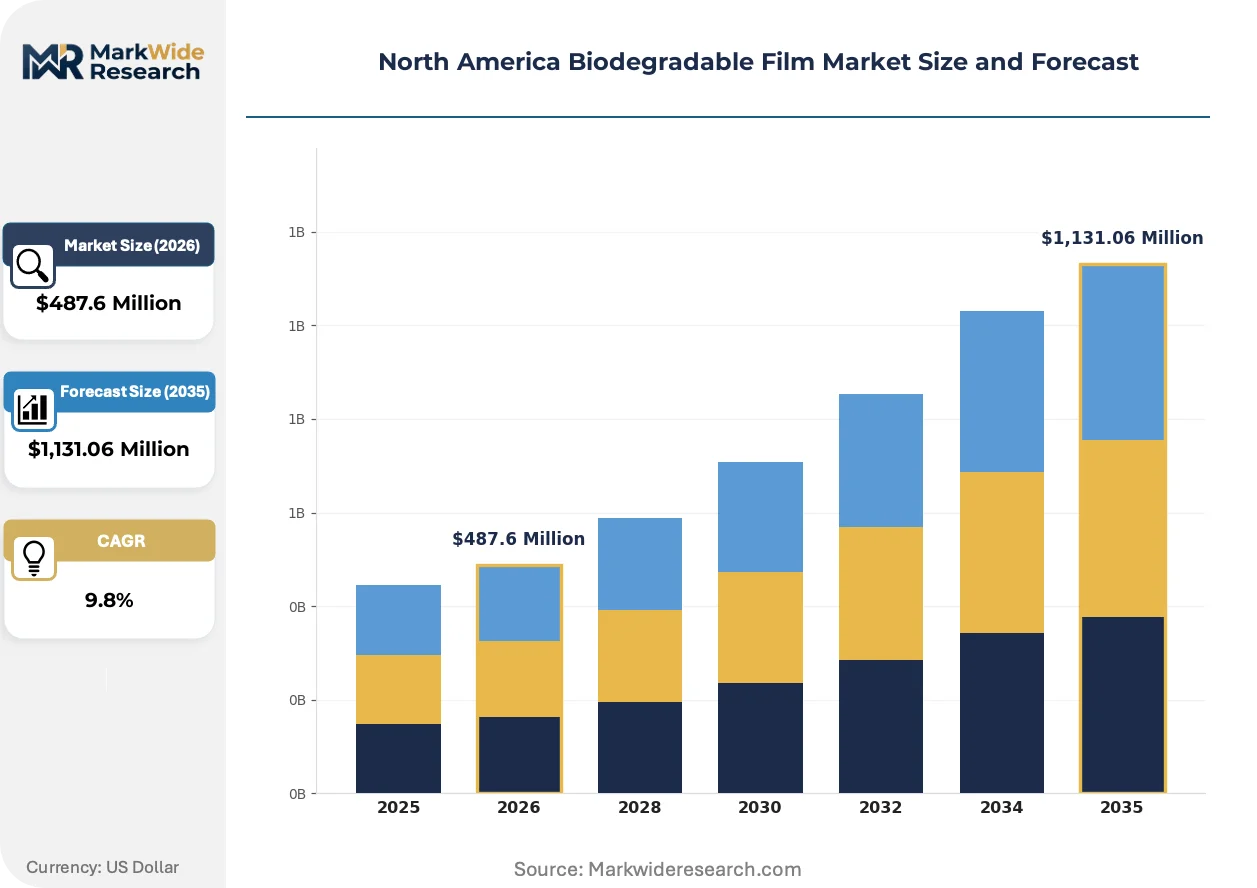
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch-based, Others Application: Agriculture, Packaging, Foodservice, Textiles End User: Retail, Food & Beverage, Healthcare, Consumer Goods Distribution Channel: Online, Offline, Wholesale, Direct Sales |
| Companies Covered | BioBag Americas, Organix Solutions, NatureWorks, Cortec Corporation, Bi-Ax International, Danimer Scientific, Eastman Chemical Company, Green Dot Bioplastics, Layfield Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biodegradable Film Market Evolving Landscape
Active barrier technologies and regulatory compliance automation are compressing product development cycles while expanding the addressable application set for biodegradable films. These shifts are redefining competitive positioning around certification depth rather than commodity scale.
Multilayer coextrusion systems incorporating PHA tie layers are absorbing oxygen transmission requirements previously met by ethylene vinyl alcohol barriers in protein packaging. Quick-service chains in California and Washington are piloting these structures for hot sandwich wrap applications. The technology is absorbing market share from metallized polyester laminates in segments where microwaveability and compostability converge as procurement criteria.
The FTC Green Guides revision process is tightening substantiation requirements for biodegradability claims, forcing label redesigns across retail bag channels. Film converters now face liability exposure for unqualified "compostable" terminology in interstate commerce. Foodservice distributors are responding by demanding BPI certification documentation upstream of purchase orders, shifting compliance verification from end-user discretion to supply chain precondition.
Certification-driven specification is consolidating buyer decision-making around third-party validation rather than supplier performance claims. Institutional procurement offices at universities and hospital systems are embedding ASTM D6400 compliance into RFP scoring rubrics, displacing price-only sourcing for flexible packaging. This pattern is most visible in the U.S. Pacific states where municipal composting access correlates with buyer willingness to pay certification premiums.
North America Biodegradable Film Market Segmentation
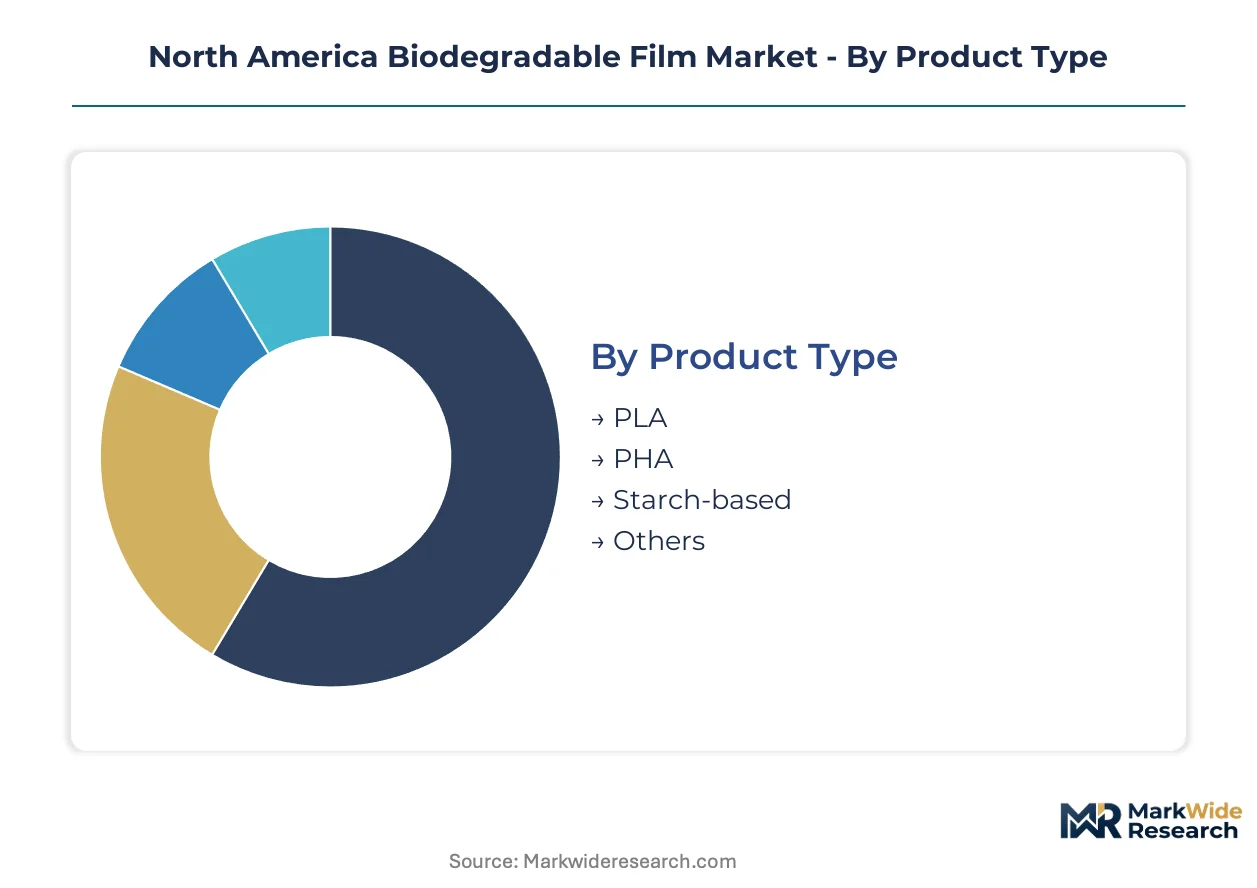
Biodegradable film procurement in North America diverges sharply by resin chemistry and certification tier, with PLA and PHA commanding distinct supply chains and price points. Segmentation discipline reveals where capital deployment yields competitive moats versus commodity exposure.
Product Type:
Capital intensity peaks with PHA fermentation infrastructure, while PLA extrusion lines offer lower barriers to entry for converters.
- PLA:Polylactic acid formulations dominate installed capacity given NatureWorks' Blair, Nebraska production complex and mature corn-derived feedstock logistics. Great Lakes converters cluster within 500 miles of this anchor facility to minimize resin freight costs and secure volume allocation.
- PHA:Microbial fermentation of polyhydroxyalkanoates requires dedicated bioreactor capital and longer batch cycles, limiting producer count to Danimer Scientific and select toll manufacturers. Marine biodegradation credentials open coastal California and Washington markets where municipal composting access remains uneven.
- Starch-based:Thermoplastic starch compounds utilize modified extrusion parameters and lower-cost agricultural feedstocks, though oxygen barrier limitations constrain protein packaging applications.
- Others:Cellulose derivatives and protein-based films occupy niche positions in medical and specialty textile segments requiring specific dissolution properties.
Most installed capacity flows through PLA. Expansion is steepest in PHA.
Application:
Application mix determines certification burden and composting facility compatibility, with foodservice facing the most stringent operational plastic bans.
- Packaging:Flexible primary packaging for dry goods and produce drives volume throughput, with ASTM D6400 compliance now mandatory for California retail distribution. Multi-layer coextrusion systems incorporating oxygen barriers absorb technical requirements previously met by conventional laminates.
- Foodservice:Quick-service chains and institutional cafeterias across California, New York, and Washington face compressed switching timelines under state-level operational prohibitions. BPI certification documentation has shifted from end-user discretion to supply chain precondition.
- Agriculture:Mulch films and silage wrap applications in the U.S. Midwest and Central Valley prioritize soil biodegradation over composting certification, creating specification divergence from food-contact grades.
- Textiles:Garment bags and nonwoven interlinings serve boutique retail channels where composting access correlates with urban coastal demographics.
Volume concentrates in packaging. Regulatory pressure is most intense in foodservice.
End User:
End-user sophistication varies by procurement centralization and sustainability scorecard maturity, with national accounts driving standardization.
- Food & Beverage:National restaurant operators and beverage distributors consolidate flexible packaging purchasing through verified lifecycle data requirements, favoring suppliers with established BPI certification. Central procurement offices embed ASTM D6400 compliance into RFP scoring rubrics.
- Retail:Grocery chains and big-box retailers face FTC Green Guides substantiation requirements for biodegradability claims, forcing label redesigns and liability exposure assessments across private-label bag programs.
- Healthcare:Hospital systems in the U.S. Pacific states specify compostable films for cafeteria operations, though medical device packaging maintains stricter sterilization barriers.
- Consumer Goods:Brand owners in personal care and household products experiment with home-composting formulations where no North American validation standard currently exists.
Procurement consolidation runs deepest in food and beverage. Healthcare represents the most compliance-intensive expansion pathway.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and certification documentation needs.
- Wholesale:Foodservice distributors aggregate demand from fragmented operator bases, managing BPI certification verification upstream of purchase orders to mitigate FTC liability exposure.
- Direct Sales:Large-format converters and national accounts negotiate resin allocation directly with NatureWorks or Danimer Scientific, bypassing distributor markups for volume commitments.
- Offline:Regional film converters and packaging distributors serve mid-tier accounts requiring technical support for extrusion parameter optimization.
- Online:E-commerce channels capture small-volume buyers and specialty textile applications where specification complexity remains low.
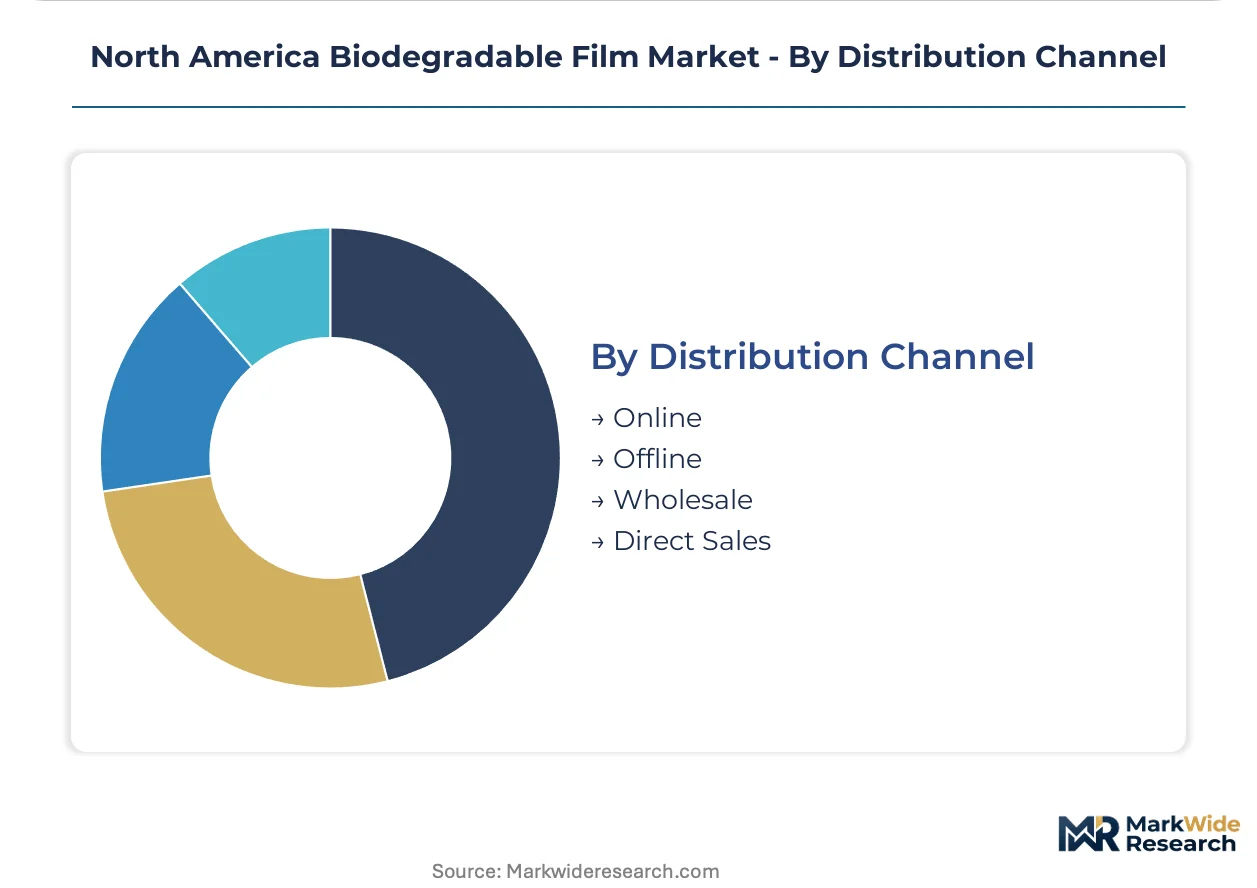
Wholesale handles the broadest account base. Direct sales capture the largest individual contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the larger volume share of biodegradable film consumption, while Canada pursues tighter federal reporting mandates that will reshape supplier documentation requirements.
United States
California's SB 54 extended producer responsibility law redirects procurement budgets toward certified compostable materials, forcing foodservice operators to accelerate switching timelines. The FTC Green Guides impose stricter substantiation requirements for biodegradability claims, elevating liability exposure for unsubstantiated labeling. The Great Lakes manufacturing corridor clusters resin compounders and film converters within 500 miles of NatureWorks' Blair, Nebraska PLA facility to minimize freight costs.
Canada
Environment and Climate Change Canada's pending federal plastics registry will mandate granular reporting on biodegradable product flows, creating first-mover advantage for suppliers with established documentation systems. Provincial operational plastic bans in British Columbia and Quebec compress adoption timelines for institutional foodservice buyers. Toronto and Vancouver municipal composting facilities are expanding acceptance capacity for certified biopolymer films, reducing end-of-life friction for packaging distributors.
Mexico
Mexico City Metro foodservice operators face mounting pressure from North American supply chain customers to align with U.S. certification standards for export-bound packaging. The Secretariat of Environment and Natural Resources (SEMARNAT) is developing national biodegradable standards that will eventually harmonize with ASTM D6400 protocols. The Bajío Region automotive and electronics manufacturing clusters generate emerging demand for industrial compostable films in component packaging applications.
North America Biodegradable Film Market Competitive Landscape
Top-tier vendors anchor resin production and certification infrastructure, while mid-tier converters compete on extrusion specialization and regional logistics. The market structure concentrates upstream biopolymer supply around fermentation and corn-derived feedstock assets, with downstream film conversion fragmenting across application-specific niches. Three strategic archetypes dominate: integrated resin-to-film producers, certified-compostable specialists, and commodity converters pivoting from polyethylene. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure BPI certification and resin allocation agreements.
Within the integrated resin production tier, NatureWorks and Danimer Scientific occupy positions as anchor suppliers for PLA and PHA chemistries respectively. BioBag Americas exemplifies the certified-compostable specialist archetype, competing through Nordic and BPI certification dominance in retail channels. These three companies represent the upstream concentration that downstream converters must navigate for supply security.
| Leading Market Players |
|---|
| BioBag Americas |
| Organix Solutions |
| NatureWorks |
| Cortec Corporation |
| Bi-Ax International |
| Danimer Scientific |
| Eastman Chemical Company |
| Green Dot Bioplastics |
| Layfield Group |
| Others |
Value Network & Pricing Analysis
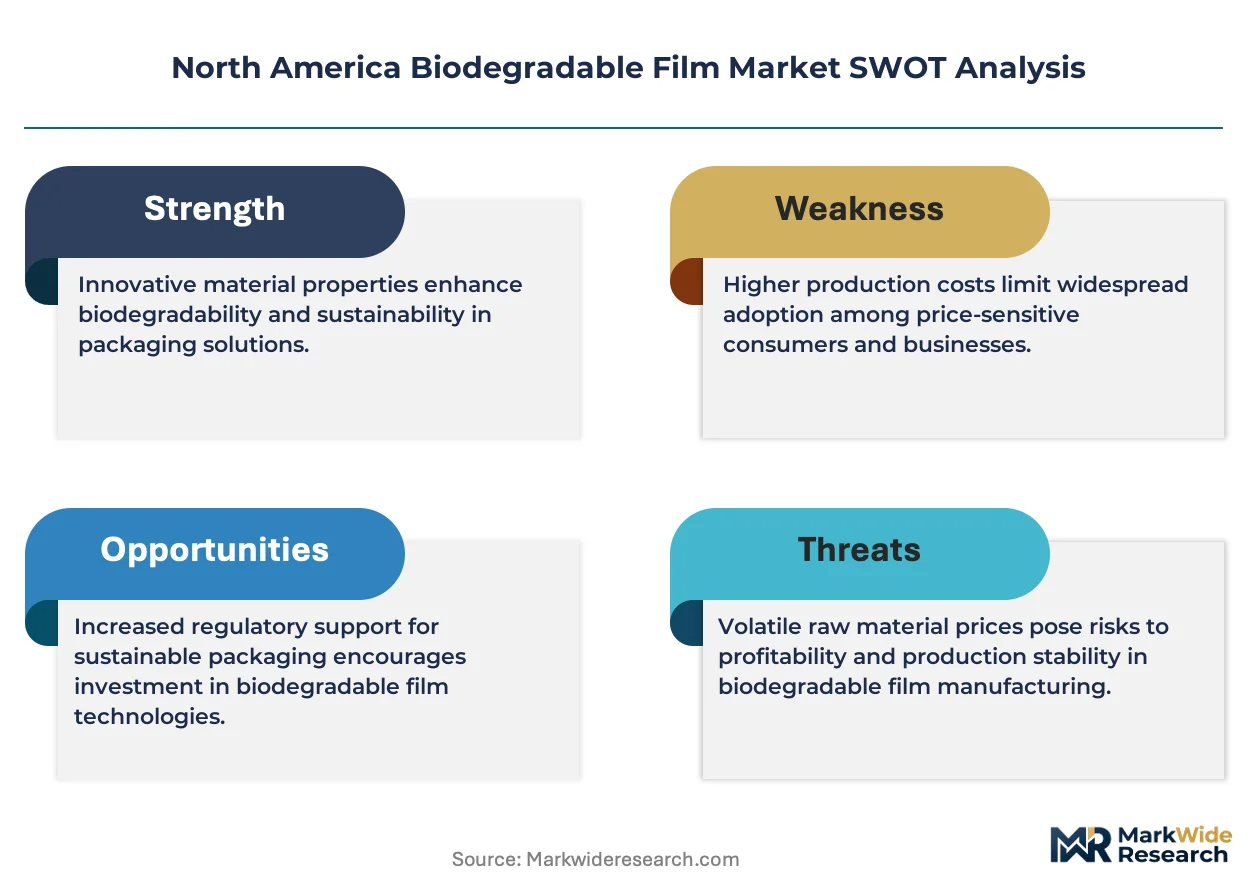
Family-owned mid-cap resin compounders in the Great Lakes corridor anchor pricing discipline through long-term offtake agreements with NatureWorks, locking in volume allocation that insulates converters from spot-market volatility while compressing margins for non-integrated film producers competing on price alone.
Pricing Analysis
Bundled certification-plus-resin contracts dominate premium tiers, while unbundled spot resin purchases serve economy-grade converters. Three-tier pricing structure across BPI-certified premium, ASTM-compliant standard, and uncertified economy levels tracks certification burden and volume scale. Cost compression in standard tiers is intensifying because resin freight differentials widen for converters beyond 500 miles of Blair, Nebraska. Quick-service chains exhibit lowest price sensitivity, prioritizing BPI documentation over per-unit cost.
Supply Chain Analysis
Direct-to-converter channels handle hyperscale buyer demand from national foodservice distributors, while wholesale distributors aggregate fragmented regional accounts. Geographic supply concentrates in the United States, Canada, and Mexico, with resin production anchored in Nebraska and Kentucky fermentation facilities. Raw material dependencies center on corn-derived dextrose, canola oil feedstocks, and microbial culture media. Single-source vulnerability around NatureWorks' PLA output creates allocation risk during demand surges. Distribution runs through foodservice distributors with embedded certification verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Biodegradable Film Market functions as a geographic-arbitrage play: California's SB 54 compliance costs exceed Canadian federal registry requirements by a factor that rewards suppliers with cross-border documentation systems.
For Market Incumbents: To counter resin supply concentration risk, secure backward integration into fermentation capacity or toll manufacturing agreements with Danimer Scientific. Prioritize BPI certification depth over SKU expansion to defend procurement scorecard positioning against emerging PHA specialists. For New Entrants and Emerging Players: The premium-to-economy price-point gap in home-composting formulations offers entry traction where no ASTM validation standard exists. Target Pacific Northwest institutional buyers with marine-biodegradable PHA alternatives. Lead with certification documentation as the go-to-market wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among toll-manufacturing converters with underutilized extrusion lines and latent BPI certification pathways. Five-to-ten-year viability hinges on federal plastics registry compliance infrastructure. Watch for Environment and Climate Change Canada's reporting mandate enforcement as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive PHA resin supply insulates against NatureWorks allocation constraints for high-barrier film converters. |
| BPI Certification Program Expansion | Third-party validation unlocks California SB 54 procurement budgets and municipal composting facility acceptance. |
| Long-term Supply Agreement with Foodservice Distributors | Embedded certification verification reduces FTC Green Guides liability exposure for national quick-service chains. |
| Joint Venture for Home-Composting Formulation Development | First-mover positioning in uncertified backyard biodegradation segment ahead of ASTM standardization. |
| Geographic Manufacturing Footprint Expansion | Great Lakes corridor proximity to Blair, Nebraska minimizes resin freight costs and secures volume allocation. |
Research Methodology
Multiple input streams — executive interviews with resin compounders and film converters, regulatory filings with the FTC and Environment and Climate Change Canada, and trade data from U.S. customs records — were reconciled against BPI certification databases and ASTM testing protocols. Primary discussions included plant managers at Great Lakes extrusion facilities, procurement leads at national foodservice distributors, technical R&D directors at biopolymer developers, and sustainability officers at quick-service chains. Secondary validation drew from SEC 10-K disclosures, California SB 54 implementation reports, and municipal composting facility capacity surveys. Bottom-up volume estimates triangulated with top-down market sizing across resin chemistry segments.
Data-stream reconciliation applied a structured analytical framework across the projection horizon. Segmentation dimensions modeled include resin chemistry tier, certification grade, end-use application, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to historical resin shipment data and forward procurement commitments. Industry-specific forecast inputs incorporated municipal composting capacity buildout schedules and state-level operational plastic ban implementation timelines.
Caveats apply where resin supply disruptions, conflicting state biodegradability definitions, or delays in Canadian federal registry enforcement could materially shift the outlook. Forecasts reflect documented assumptions regarding certification adoption rates and composting infrastructure expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biodegradable Packaging
Biodegradable Cups Market
Biodegradable Packaging
North America Biodegradable Plastic Market
Biodegradable Packaging
Clear Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Lidding Films Market
Biodegradable Packaging
Oxo Biodegradable Bags Market
Biodegradable Packaging
Biodegradable Lids Market
Biodegradable Packaging
India Biodegradable Tableware & Packaging Products Market
Biodegradable Packaging
Botanical Packaging Market
Biodegradable Packaging
Oxo-Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Paper and Plastic Packaging Market
Biodegradable Packaging
Compostable Shrink Wrap Market
Biodegradable Packaging
Biodegradable Packaging Market
Biodegradable Packaging
Europe Biodegradable Plastic Packaging Market
Biodegradable Packaging
Biodegradable Meal Trays Market
Biodegradable Packaging
Starch-Based Bioplastics Packaging Market
Biodegradable Packaging
Biodegradable Cutlery Market