
 India Industrial Pump Market | 2026-2036
India Industrial Pump Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Pump Market Foresight
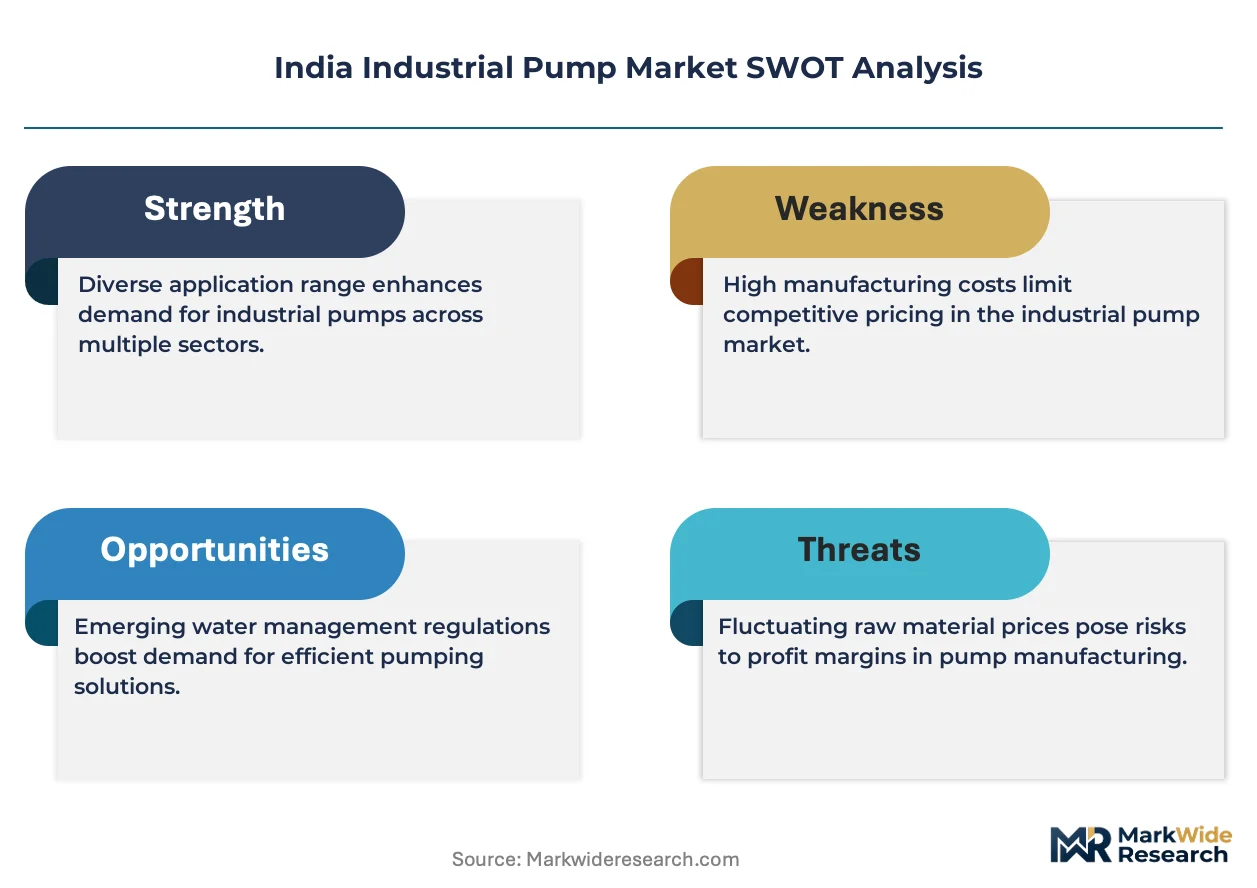
Modular pump-skid packaging is restructuring procurement patterns across Indian process industries. Kirloskar Brothers Limited anchors its position through deep manufacturing scale in Pune and Kolhapur facilities. Grundfos Pumps India Private Limited differentiates via energy-efficient circulator technology tailored to local voltage conditions. Shakti Pumps leverages backward integration into motor and controller production to control cost structures in agricultural segments.
Industrial pumps are mechanical devices engineered to move fluids through piping systems via rotational kinetic energy or positive displacement action, typically constructed from cast iron, stainless steel, or specialized alloys with flow rates spanning liters per minute to thousands of cubic meters per hour. Their primary purpose is to ensure reliable fluid transfer, pressure boosting, and process circulation across continuous manufacturing operations. Centrifugal pumps dominate volume in water treatment and power generation applications where high-flow, moderate-head conditions prevail. Positive displacement systems capture premium margins in chemicals and oil refineries handling viscous or shear-sensitive media. Submersible configurations are expanding fastest in agriculture as borewell depths increase across depleting aquifer zones in Punjab, Haryana, and western Uttar Pradesh.
BIS efficiency standards and CEA power-quality regulations are mandating minimum performance thresholds for pumps deployed in municipal water schemes and thermal power stations. The country's national petroleum regulator enforces material specifications and leakage-rate protocols for hydrocarbon transfer equipment. PLI scheme incentives for advanced manufacturing are drawing foreign component suppliers to establish domestic motor and seal production. Stakeholders must monitor how state-level water policy fragmentation between NITI Aayog guidelines and individual state irrigation department tender rules affects standardization and aftermarket service economics.
Market Dynamics
Modular pump-skid packaging is restructuring procurement patterns across Indian process industries, compressing project timelines and shifting vendor selection criteria toward integrated system capability rather than standalone equipment specifications.
Growth Catalysts
- CEA Power-Quality Mandates:The Central Electricity Authority's regulations for thermal power stations are mandating minimum pump efficiency thresholds, forcing replacement cycles in aging coal and gas-fired plants across Maharashtra and Gujarat.
- Submersible Technology:Borewell depths exceeding 300 feet in Punjab and Haryana are accelerating demand for high-head submersible configurations in agricultural groundwater extraction.
- PLI Scheme Incentives:Production-linked incentives for advanced manufacturing are drawing foreign motor and seal suppliers to establish domestic production, reducing import dependency for critical rotating components.
Market Restraints
- Cast Iron Input Volatility:Foundry-grade pig iron prices fluctuate with scrap metal and coking coal costs, compressing margins for mid-tier manufacturers serving municipal water schemes.
- Import Concentration in Seals:Mechanical seal technology remains concentrated among German and Japanese suppliers, exposing domestic assemblers to currency risk and extended lead times.
- Shear Sensitivity Limits:Centrifugal designs face technical constraints handling viscous chemical slurries above 500 centipoise, ceding share to positive displacement alternatives in refinery applications.
Strategic Opportunities
- Tamil Nadu Power Hub:The state's concentration of thermal, nuclear, and renewable generation assets creates concentrated demand for cooling water and feedwater pump systems.
- IoT-Enabled Condition Monitoring:Sensor integration with vibration analysis and predictive maintenance algorithms is unifying hardware and software procurement decisions among large water utilities.
- BIS Efficiency Labeling:Star-rating protocols for agricultural pumps are creating tiered replacement demand as state irrigation departments mandate minimum ratings in tender specifications.
Industry Challenges
- Foundry Skill Shortage:Precision casting expertise for duplex stainless steel impellers remains scarce in domestic labor markets, constraining capacity expansion for corrosion-resistant product lines.
- Legacy Control Integration:Digital pump controllers face protocol incompatibility with existing SCADA infrastructure in decades-old municipal water treatment plants, complicating retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Pump Market |
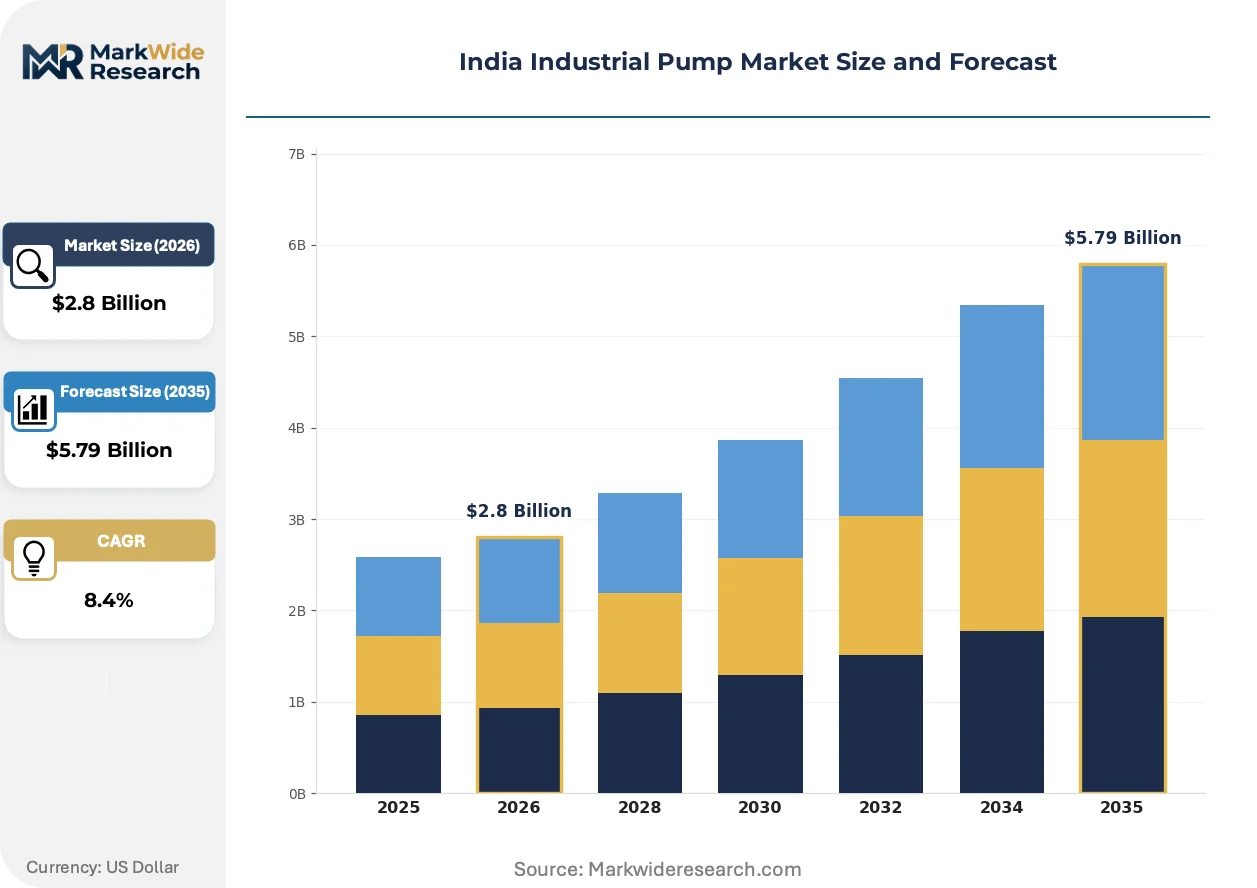
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Diaphragm Pumps Application: Water Treatment, Oil & Gas, Chemicals, Food & Beverage End User: Manufacturing, Oil refineries, Agriculture, Power Generation Technology: Electric, Pneumatic, Hydraulic, Solar |
| Companies Covered | KSB, Crompton Greaves Consumer Electricals Limited, Kirloskar Brothers Limited, CG Power and Industrial Solutions Limited, Xylem, Shakti Pumps, Grundfos Pumps India Private Limited, Oswal Pumps Ltd., CRI Pumps Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Pump Market Shifts & Advancements
Digitalization of fluid systems is compressing the traditional separation between mechanical equipment and control architecture, creating new competitive battlegrounds around data integration rather than hydraulic performance alone.
Variable frequency drive technology is unifying motor control with pump hydraulics into single-source procurement decisions. Large manufacturing complexes in Gujarat's chemical belt are specifying VFD-integrated packages to reduce energy consumption during partial-load operation. This convergence is compressing the addressable market for standalone pump vendors lacking electrical engineering capabilities.
BIS certification mandates for minimum efficiency standards are tightening compliance thresholds for equipment deployed in municipal water schemes. The Bureau of Indian Standards' star-rating protocols now govern agricultural and industrial pump categories, forcing redesign cycles among domestic manufacturers. Maharashtra's urban water utilities are prioritizing five-star rated centrifugal systems in tender evaluations, shifting procurement criteria toward lifecycle cost rather than initial capital outlay.
Service contract unbundling is disrupting traditional aftermarket relationships between OEMs and municipal operators. Large water utilities in Tamil Nadu are separating maintenance agreements from initial equipment supply, opening entry paths for independent service providers with diagnostic capabilities. This fragmentation is most visible in Chennai's metropolitan water distribution network, where third-party condition monitoring specialists now compete directly with manufacturer service divisions for multi-year maintenance awards.
India Industrial Pump Market Segmentation
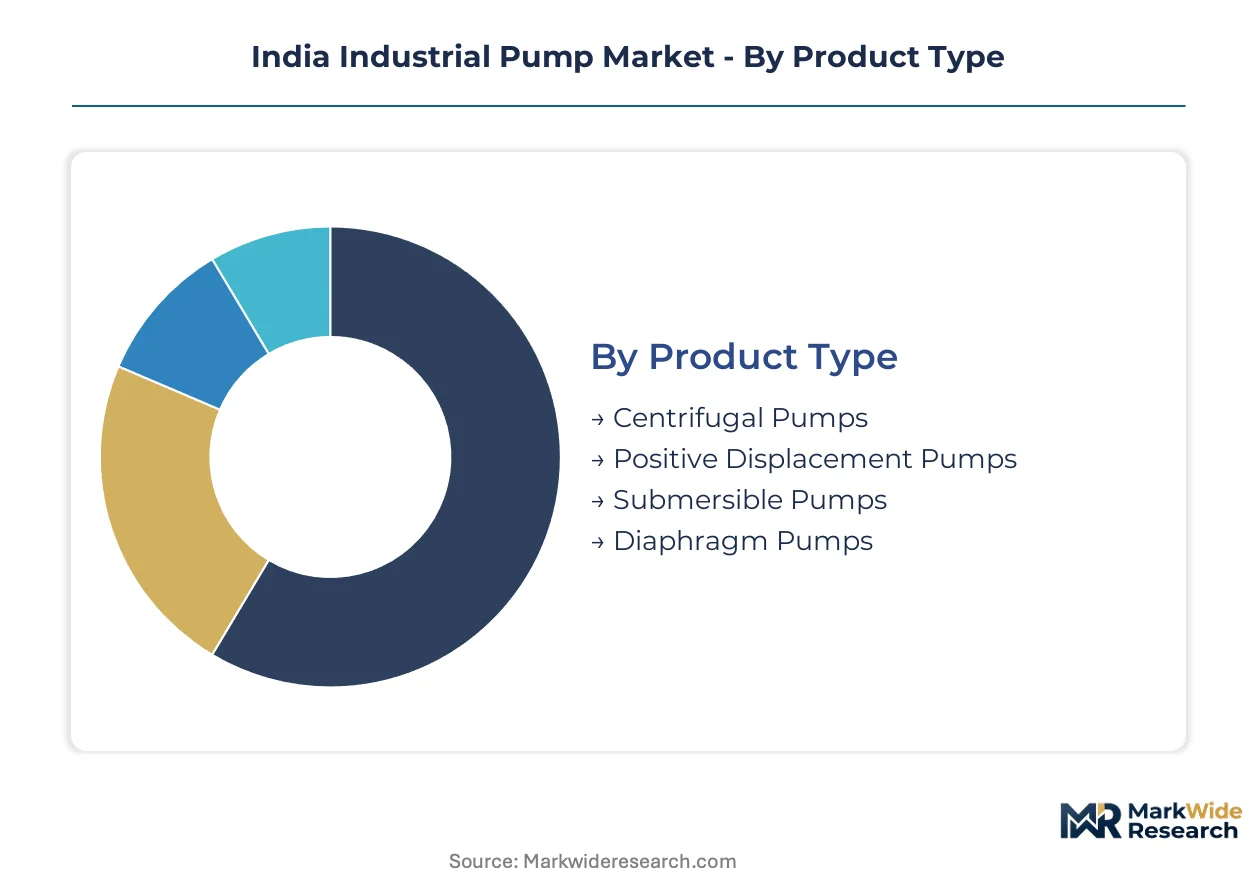
Pump specification in India follows distinct procurement logics across process industries, with efficiency mandates and fluid characteristics dictating technology selection. Segment boundaries blur where VFD integration and modular skid packaging compress traditional category distinctions into unified system procurement.
Product Type:
Capital allocation patterns favor centrifugal architectures for high-flow municipal applications while viscous media handling drives positive displacement specification in chemical corridors.
- Centrifugal Pumps:Rotodynamic designs transfer kinetic energy through impeller rotation to move low-viscosity fluids at high flow rates. Maharashtra's urban water utilities specify five-star BIS-rated centrifugal systems in tender evaluations, prioritizing lifecycle cost over initial outlay as CEA mandates tighten efficiency thresholds in thermal power stations.
- Positive Displacement Pumps:These systems trap fixed fluid volumes and mechanically displace them against discharge pressure, maintaining consistent flow regardless of system resistance. Gujarat's chemical belt deploys progressive cavity and gear pump configurations for viscous slurries above 500 centipoise where centrifugal designs face shear sensitivity constraints.
- Submersible Pumps:Motor-pump integrated units operate below liquid surface in borewell applications across depleting aquifers.
- Diaphragm Pumps:Air-operated double-diaphragm designs isolate process fluid from mechanical components in corrosive chemical transfer.
Volume sits with centrifugal configurations; growth tilts toward submersible systems as groundwater depths exceed 300 feet in Punjab and Haryana.
Application:
End-use concentration maps directly onto India's industrial corridor geography, with water treatment commanding procurement scale and chemicals delivering premium margin capture.
- Water Treatment:Municipal filtration, distribution, and sewage handling operations specify corrosion-resistant cast iron and stainless steel constructions. Tamil Nadu's metropolitan utilities unbundle maintenance contracts from equipment supply, creating entry paths for independent condition monitoring specialists in Chennai's distribution network.
- Oil & Gas:Hydrocarbon transfer, pipeline boosting, and refinery process circulation require API-compliant material specifications. The national petroleum regulator enforces leakage-rate protocols and metallurgical standards that concentrate procurement among certified domestic assemblers with documented quality systems.
- Chemicals:Acid handling, solvent transfer, and reactor feed applications drive demand for exotic alloy constructions.
- Food & Beverage:Hygienic pump designs with sanitary surface finishes serve dairy processing and beverage production in Maharashtra and Karnataka.
Procurement value concentrates in water treatment; margin expansion tracks chemical applications where material specifications limit vendor qualification.
End User:
Customer scale and technical sophistication fragment vendor relationships, with large utilities demanding system integration and agricultural buyers prioritizing first-cost minimization.
- Manufacturing:Process cooling, boiler feed, and wastewater handling operations across automotive and textile plants specify modular pump-skid packages. Gujarat's chemical belt manufacturers are compressing project timelines by shifting vendor selection criteria toward integrated system capability rather than standalone equipment specifications.
- Oil Refineries:Crude transfer, distillation unit feed, and product loading operations require continuous-duty reliability. Reliance Industries and Indian Oil Corporation maintenance schedules drive replacement demand for API 610-compliant centrifugal and positive displacement systems.
- Agriculture:Borewell irrigation and flood irrigation pumping dominate rural procurement volumes.
- Power Generation:Cooling water circulation, condensate extraction, and boiler feed pumping serve thermal, nuclear, and renewable assets.
Unit volume flows to agriculture; technical complexity and service contract value concentrate in power generation.
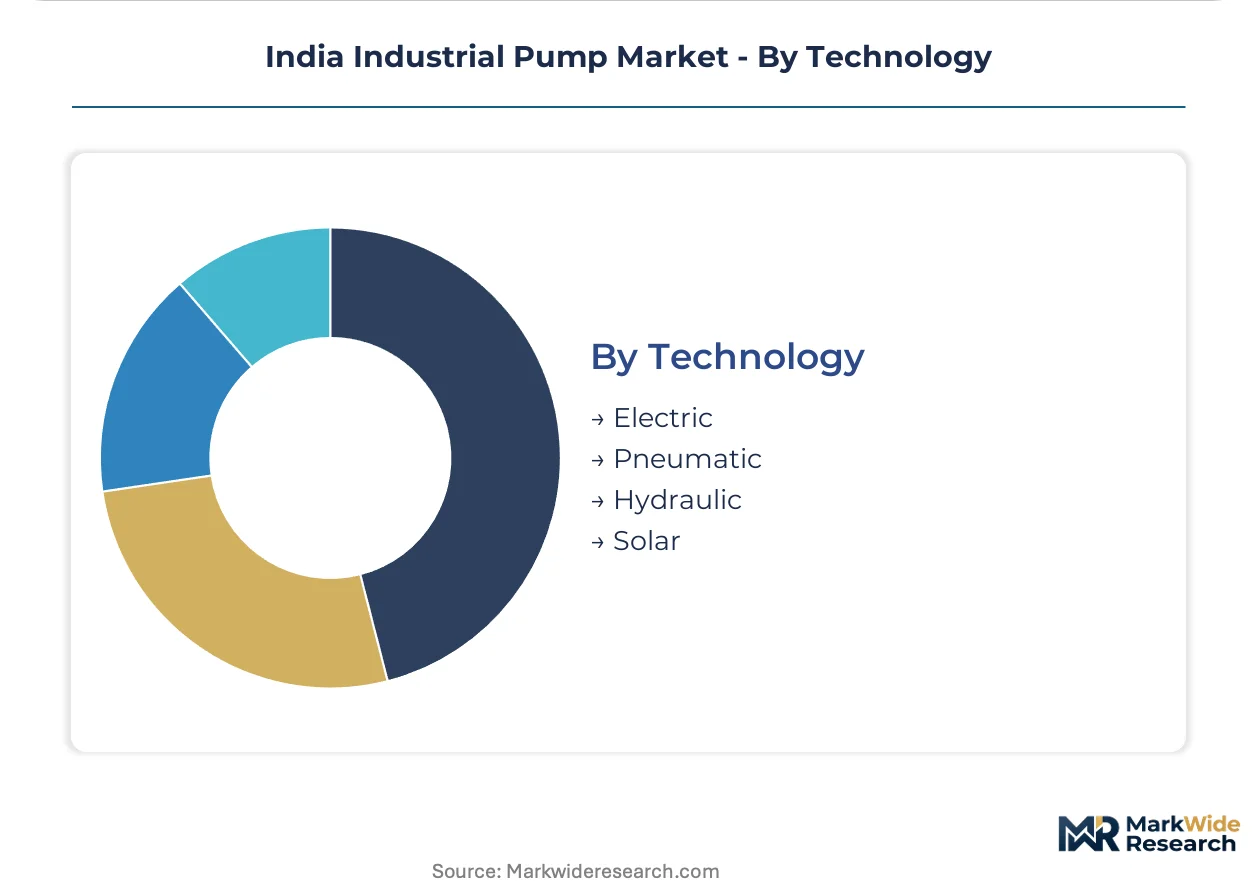
Technology:
Energy source selection increasingly intertwines with control architecture, as variable frequency drive integration reshapes motor-pump procurement decisions.
- Electric:Grid-connected induction and permanent magnet motors dominate industrial installations. Large manufacturing complexes in Gujarat specify VFD-integrated packages to reduce energy consumption during partial-load operation, compressing the addressable market for standalone pump vendors lacking electrical engineering capabilities.
- Pneumatic:Compressed air power serves explosion-hazard environments and portable dewatering applications. Chemical plants in Maharashtra deploy air-operated diaphragm pumps where electrical ignition risks preclude standard motor drives.
- Hydraulic:Fluid power transmission enables high-pressure applications in mining and construction dewatering.
- Solar:Photovoltaic-powered surface and submersible pumps expand in off-grid agricultural zones.
Installed base remains electric; solar configurations gain share fastest as PM-KUSUM subsidies reduce capital barriers in Rajasthan and Madhya Pradesh.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in western and southern states while northern regions drive consumption through agricultural groundwater extraction and thermal power replacement cycles.
Maharashtra
Pune and Kolhapur host the densest concentration of domestic pump manufacturing facilities serving national distribution networks. BIS certification mandates for municipal water schemes force continuous redesign cycles among local fabricators. Mumbai's metropolitan water utilities specify five-star rated centrifugal systems in tender evaluations, compressing procurement timelines toward integrated system suppliers.
Gujarat
The chemical belt generates concentrated demand for positive displacement configurations handling viscous slurries above 500 centipoise. CEA power-quality regulations mandate minimum efficiency thresholds in thermal power stations across the state. Large manufacturing complexes in Vadodara and Ankleshwar specify VFD-integrated packages to reduce energy consumption during partial-load operation.
Tamil Nadu
Thermal, nuclear, and renewable generation assets create concentrated demand for cooling water and feedwater pump systems. State-level water policy fragmentation between NITI Aayog guidelines and irrigation department tender rules complicates standardization. Chennai's metropolitan water distribution network unbundles maintenance contracts from equipment supply, opening entry paths for independent condition monitoring specialists.
Punjab and Haryana
Borewell depths exceeding 300 feet accelerate demand for high-head submersible configurations in agricultural groundwater extraction. PM-KUSUM subsidies reduce capital barriers for solar-powered surface and submersible pumps across depleting aquifer zones. Ludhiana and Ambala serve as procurement hubs where first-cost minimization dominates buyer behavior among smallholder farmers.
Andhra Pradesh and Telangana
Power generation clusters and expanding pharmaceutical manufacturing drive specification of corrosion-resistant alloy constructions. State irrigation departments mandate minimum BIS star ratings in tender specifications for agricultural pumps. Visakhapatnam's industrial corridor concentrates demand for API-compliant material specifications in hydrocarbon transfer applications.
India Industrial Pump Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base separates into three strategic archetypes: integrated domestic manufacturers with captive motor production, foreign-owned technology licensors with localized assembly, and regional fabricators serving price-sensitive agricultural segments. Capacity expansion and backward integration into controller production represent the dominant competitive moves reshaping cost structures.
Among integrated domestic specialists, Kirloskar Brothers Limited and Shakti Pumps occupy positions defined by manufacturing scale and captive supply of rotating components. Grundfos Pumps India Private Limited exemplifies the foreign technology archetype with localized adaptation to Indian voltage conditions. These three anchors illustrate how competitive positioning fragments across efficiency-tier specialization rather than consolidating around unified national standards.
| Leading Market Players |
|---|
| KSB |
| Crompton Greaves Consumer Electricals Limited |
| Kirloskar Brothers Limited |
| CG Power and Industrial Solutions Limited |
| Xylem |
| Shakti Pumps |
| Grundfos Pumps India Private Limited |
| Oswal Pumps Ltd. |
| CRI Pumps Pvt. Ltd. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators anchor Maharashtra's foundry belt, transmitting cast iron input volatility directly into tender pricing while resisting the margin discipline that integrated players impose through captive motor production.
Pricing Analysis
Margin tightening in municipal water tenders reflects BIS star-rating mandates that force redesign costs onto manufacturers before procurement committees award lifecycle-cost contracts. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates Grundfos and Kirloskar from regional assemblers. Cost compression accelerates because state irrigation departments mandate minimum efficiency thresholds in agricultural pump awards. Smallholder farmers in Punjab and Haryana exhibit extreme price sensitivity, while Tamil Nadu power utilities prioritize technical specification compliance over first-cost minimization.
Supply Chain Analysis
Mechanical seal technology rests on German and Japanese specialty producers, exposing domestic assemblers to euro-yen currency risk and sixteen-week lead times that disrupt project schedules. Foundry-grade pig iron draws from Indian mini-mills and Chinese export cargoes, with coking coal costs feeding through to impeller casting prices. Single-source vulnerability concentrates in high-performance duplex stainless steel grades required for chemical belt corrosion resistance. Distribution runs through authorized dealer networks in agricultural zones and direct OEM relationships for utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as BIS certification mandates and CEA efficiency regulations raise compliance costs beyond the reach of unbranded regional fabricators.
For Market Incumbents: Deploy backward integration into controller production to capture VFD-integrated package demand in Gujarat's chemical belt. Kirloskar Brothers Limited exemplifies this path through captive motor manufacturing in Kolhapur. Seal technology licensing agreements with Japanese suppliers reduce currency exposure while blocking emerging competitors from specification-compliant tenders. For New Entrants and Emerging Players: Direct-to-utility digital platforms offer low-friction entry into Tamil Nadu's unbundled maintenance contract market. Chennai's metropolitan water distribution network separates equipment supply from service agreements, creating white-space for condition-monitoring specialists with IoT-enabled diagnostic capabilities. Agricultural solar pump segments under PM-KUSUM subsidies present the most penetrable volume opportunity. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision casting specialists in western India with dormant duplex stainless steel capacity and dormant BIS certification relationships. Foundry skill scarcity for corrosion-resistant impellers constrains expansion among mid-tier players. Watch for state-level water policy harmonization between NITI Aayog guidelines and irrigation department tender rules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Shakti Pumps controls cost structures through captive controller manufacturing in agricultural segments. |
| VFD-Integrated Package Development | Gujarat chemical manufacturers specify unified motor-pump procurement to reduce partial-load energy consumption. |
| BIS Five-Star Certification Investment | Maharashtra urban utilities prioritize star-rated centrifugal systems in lifecycle-cost tender evaluations. |
| IoT Condition Monitoring Capability | Tamil Nadu utilities unbundle maintenance contracts, opening entry for diagnostic specialists in Chennai. |
| Precision Casting Capacity Expansion | Duplex stainless steel impeller expertise remains scarce, constraining corrosion-resistant product line growth. |
Research Methodology
Document review covered BIS certification registries, CEA power-quality mandates, and state irrigation department tender specifications, complemented by interviews with plant engineers at thermal power stations, procurement leads at municipal water utilities, aftermarket service heads, and foundry operations managers. Secondary validation drew from customs trade data on mechanical seal imports, PLI scheme disclosures, and Bureau of Indian Standards efficiency rating protocols. Bottom-up demand modeling across end-use segments triangulated against top-down industrial production indices.
Segment-level outputs across the projection horizon reflect centrifugal, positive displacement, submersible, and diaphragm product architectures combined with water treatment, oil and gas, chemical, and power generation applications. CAGRs were derived from replacement cycle analysis of aging coal and gas-fired plants, agricultural borewell depth trajectories, and municipal infrastructure investment pipelines. Forecast inputs incorporated BIS star-rating adoption curves and PM-KUSUM subsidy disbursement rates.
The model holds under continued regulatory enforcement of CEA efficiency mandates and BIS certification requirements; deviation in state-level water policy fragmentation or foundry input cost spikes would shift replacement timelines. A small set of triggers—mechanical seal import tariff adjustments, PLI scheme expansion into controller components, and NITI Aayog guideline adoption rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Solar Pump Inverter Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Latin America Hydraulic Filtration Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Commercial Booster Pumps Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Fuel Transfer Pump Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
Asia Pacific Submersible Pump Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
North America Dispensing Pumps Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Gear Pump Market
Pumps and Control Devices
Pool Heat Pumps Market