
 Anti-Static Control Products Market | 2026-2036
Anti-Static Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Static Control Products Market Outlook
Software-defined ESD monitoring is recalibrating how anti-static control products get sold, shifting hardware vendors toward subscription-based compliance dashboards. Desco Industries leverages its deep catalog of grounding and monitoring equipment to anchor recurring service relationships with electronics OEMs. Phoenix Contact competes through embedded sensor integration that extends its industrial connectivity portfolio into cleanroom environments.
Anti-static control products encompass conductive and static-dissipative materials engineered to surface resistivity specifications between 10^4 and 10^11 ohms per square, primarily manufactured through polymer compounding with carbon black, metal fibers, or intrinsically conductive polymers to protect sensitive electronic components from electrostatic discharge damage. Floor mats and wrist straps represent mature, high-volume categories where margin pools have compressed, while ESD bags and garments command stronger pricing due to cleanroom certification requirements and material complexity. Electronics manufacturing dominates application demand, though automotive module assembly is emerging as a faster-growing segment driven by electric vehicle power electronics sensitivity.
EPA regulations on workplace volatile organic compound emissions shape coating and solvent choices for U.S.-based manufacturers, while China's GB standards for electrostatic safety in explosive atmospheres mandate product certifications that filter market access. The EU's REACH framework restricts certain conductive additives, pushing European suppliers toward alternative polymer formulations. Stakeholders must monitor how evolving semiconductor fabrication node transitions below three nanometers alter ESD threshold requirements and corresponding product specification demands.
Market Dynamics
Semiconductor fabrication node transitions below three nanometers are recalibrating ESD threshold tolerances, forcing anti-static control suppliers to engineer materials with tighter surface resistivity windows and real-time ionization monitoring.
Growth Catalysts
- Taiwan Semiconductor Expansion:Foundry capacity additions in Hsinchu and Tainan Science Parks are mandating upgraded EPA-grade flooring and garment programs. Contract values for fab ESD infrastructure are scaling with cleanroom square footage.
- REACH Framework Restrictions:ECHA's evolving substance restrictions on carbon black conductive additives are accelerating alternative polymer formulation R&D. European compounders are qualifying intrinsically conductive polymer substitutes ahead of sunset dates.
- Electric Vehicle Power Electronics:Automotive inverter and onboard charger assembly lines are adopting semiconductor-grade ESD protocols. Tier-1 module suppliers in Germany and South Korea are specifying Class 0 dissipative materials for SiC device handling.
Market Restraints
- Carbon Black Feedstock Volatility:Petroleum-derived conductive filler pricing tracks crude oil indices, compressing margin stability for compounded sheet and flooring manufacturers.
- East Asian Supply Concentration:Carbon fiber and stainless steel fiber conductive yarn production clusters in Zhejiang Province create single-source vulnerability for global ESD garment weavers.
- RoHS Substitution Complexity:Lead-free solder alloys in electronics assembly generate triboelectric charging profiles that legacy ionization equipment cannot fully neutralize.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for mobile and IT hardware assembly are attracting Foxconn and Dixon Technologies facilities lacking mature ESD infrastructure. First-mover suppliers can anchor specification-setting relationships.
- Wearable ESD Monitoring:Integration of Bluetooth-enabled wrist strap continuity sensors with factory MES platforms is automating compliance documentation. Industrial IoT vendors are seeking hardware partners for bundled offerings.
- Water-Based Coating Transition:EPA VOC emission limits are disqualifying solvent-borne topical antistats from federal contractor supply chains. Aqueous polyurethane dispersions with permanent static-dissipative properties command specification premiums.
Industry Challenges
- Cleanroom Garment Laundering Certification:ISO 14644-1 Class 100 garment reuse programs require validated wash-cycle chemistry and particle testing. In-house laundry investments strain mid-size contract manufacturers.
- Multi-Site ESD Audit Standardization:Electronics OEMs with dispersed assembly in Mexico, Vietnam, and Poland struggle to harmonize grounding impedance testing protocols across facilities with varying electrical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Static Control Products Market |
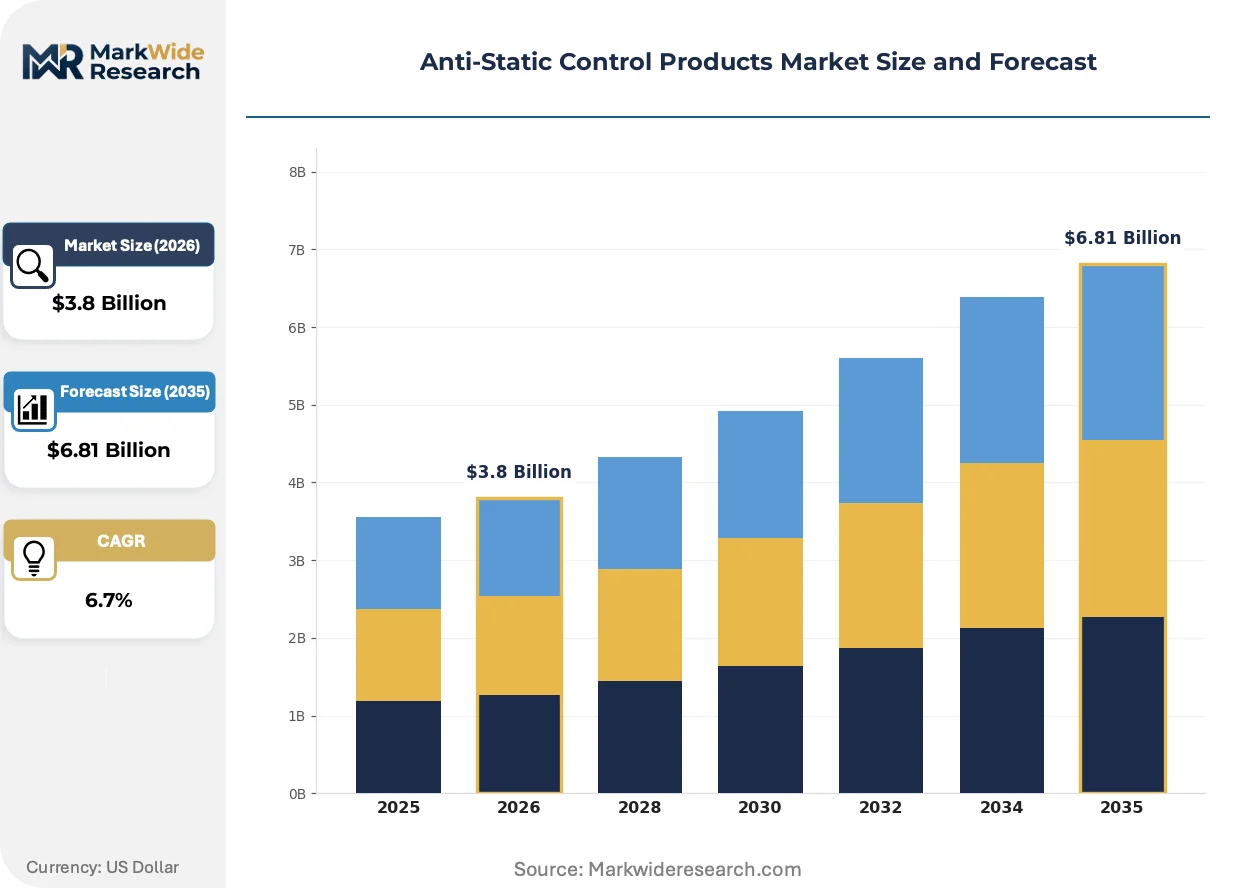
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floor Mats, Wrist Straps, Bags, Garments Material: Vinyl, Rubber, Polyester, Fabric Application: Electronics Manufacturing, Cleanroom, Healthcare, Automotive End User: OEMs, Retail, Industrial, Laboratories |
| Companies Covered | Desco Industries Inc., ACL, Inc., Keystone Electronics Corp., Fraser Anti-Static Techniques Ltd., Meech Static Eliminators Ltd., Cole-Parmer Instrument Company, LLC., Botron Company Inc., Phoenix Contact, Panduit Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Static Control Products Market Strategic Shifts
Real-time environmental sensing and predictive analytics are displacing scheduled manual ESD audits, embedding compliance verification into continuous manufacturing data streams rather than episodic inspection cycles.
Software-defined ESD monitoring systems are automating ionization balance verification through networked sensor arrays that adjust blower output based on particle counts and humidity readings. Semiconductor fabs in Taiwan and South Korea are deploying these platforms to eliminate production holds for manual verification. The technology is automating documentation for automotive and medical device customers demanding lot-level ESD traceability.
EPA regulations on workplace volatile organic compound emissions are restricting solvent-based topical antistatic coatings from federal contractor facilities and California manufacturing sites. Water-based polyurethane and acrylic dispersions with grafted conductive polymers are gaining qualification approvals despite longer cure cycles. Flooring and worksurface manufacturers serving aerospace and defense primes are reformulating product lines to maintain specification eligibility.
Consolidated procurement of ESD consumables through MRO distributors is displacing direct manufacturer relationships for mid-volume electronics assemblers. Large contract manufacturers in China and Mexico are mandating single-source PPE and flooring contracts to simplify supplier management. Regional distributors with captive installation and certification services are capturing specification influence previously held by product manufacturers.
Anti-Static Control Products Market Segmentation
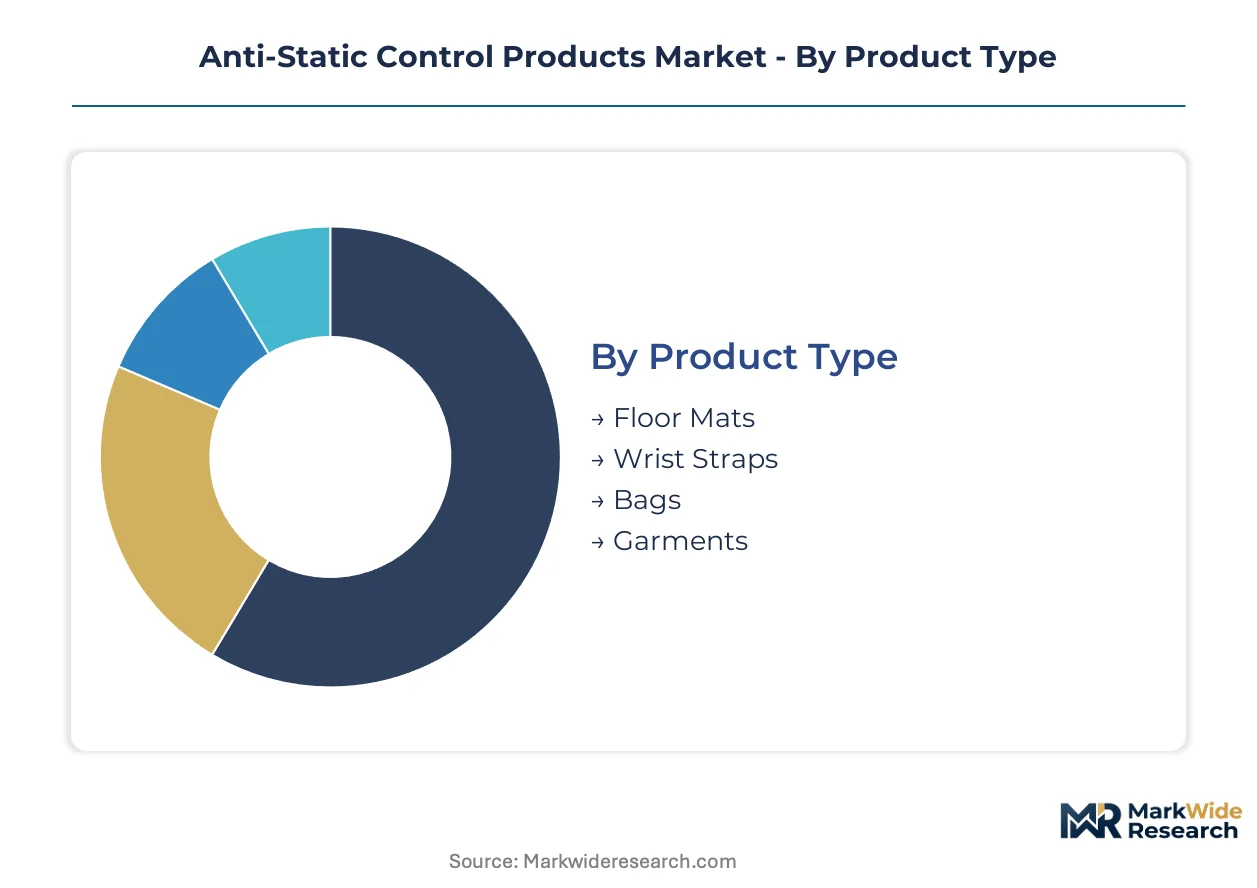
Anti-static control products fragment across four distinct classification axes, each capturing different value pools and replacement dynamics. Material composition and application environment drive specification premiums, while end-user procurement scale determines contract structure and service bundling.
Product Type:
Upgrade cycles vary dramatically across physical form factors, with flooring infrastructure demanding decade-long capital commitments versus consumable garments requiring quarterly replenishment.
- Floor Mats:Multi-layer vinyl or rubber composites with embedded conductive grids anchor EPA infrastructure in semiconductor fabs. Taiwan and South Korea foundry expansions are specifying 10-year warranty programs with embedded RFID tracking for impedance verification.
- Wrist Straps:Coiled cord assemblies with 1-megohm safety resistors represent the most frequently replaced category, with automotive module assembly lines in Germany mandating daily continuity testing and monthly replacement cycles.
- Bags:Metallized shielding laminates protect components during transit and storage.
- Garments:Cleanroom-certified coveralls and smocks with conductive yarn grids.
Volume placements concentrate in wrist straps; the faster expansion belongs to floor mats.
Material:
Raw material selection locks in performance windows, with petroleum-derived feedstocks exposing compounders to energy price volatility while bio-based alternatives command qualification premiums.
- Vinyl:Plasticized PVC formulations with carbon black loading dominate flooring and matting due to cost efficiency and weldability. EPA VOC regulations are disqualifying solvent-borne plasticizers from federal contractor supply chains.
- Rubber:Nitrile and EPDM compounds with metal fiber reinforcement serve heavy-duty industrial applications.
- Polyester:Woven synthetic base fabrics for ESD garments with grafted conductive surface treatments.
- Fabric:Cotton-polyester blends with embedded stainless steel fibers for reusable cleanroom apparel.
Specification density runs highest in vinyl; rubber formulations are climbing fastest on automotive inverter assembly demand.
Application:
Environmental stringency tiers separate commodity-grade workplace protection from semiconductor-class contamination control, with certification requirements multiplying at each ascending level.
- Electronics Manufacturing:PCB assembly and component handling operations drive baseline demand for wrist straps, bench mats, and ionization equipment. China's eastern manufacturing corridor spanning Shanghai, Suzhou, and Shenzhen anchors procurement volume.
- Cleanroom:ISO 14644-1 Class 100 to Class 1000 environments mandate garment laundering certification and real-time particle monitoring integration.
- Healthcare:Pharmaceutical compounding and medical device assembly require sterilizable ESD protocols.
- Automotive:Electric vehicle power electronics assembly is adopting semiconductor-grade ESD thresholds for SiC device handling.
Electronics manufacturing retains the largest installed base; automotive applications are expanding most quickly.
End User:
Procurement sophistication stratifies sharply, with consolidated OEM programs squeezing distributor margins while fragmented industrial accounts reward technical service capabilities.
- OEMs:Foxconn, Dixon Technologies, and tier-1 contract manufacturers mandate single-source ESD infrastructure contracts with embedded installation and certification services.
- Retail:Electronics component distributors and small-scale assembly operations purchase through MRO channels with minimal technical support requirements.
- Industrial:Heavy machinery and process control manufacturers deploy anti-static solutions for explosive atmosphere protection.
- Laboratories:R&D and quality assurance facilities require calibrated instrumentation and audit documentation.
Contract value pools concentrate with OEMs; laboratories deliver the steepest expansion trajectory on biopharma investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian conductive fiber and polymer compounding clusters, while consumption splits between mature electronics manufacturing bases and emerging automotive module assembly corridors. Taiwan and South Korea anchor semiconductor-grade demand, China absorbs volume production, and Germany plus the United States shape regulatory-driven specification premiums.
United States
Automotive inverter assembly lines in Michigan and Ohio are adopting Class 0 dissipative protocols for silicon carbide device handling. EPA VOC emission limits are disqualifying solvent-borne topical antistats from federal contractor supply chains. California's manufacturing corridor spanning San Jose to San Diego anchors aerospace and defense prime demand for water-based coating formulations.
China
GB standards for electrostatic safety in explosive atmospheres mandate product certifications that filter market access for imported materials. The MIIT dual carbon goals are pressuring Zhejiang Province carbon fiber producers toward energy-efficient conductive yarn processes. Shanghai, Suzhou, and Shenzhen form the eastern manufacturing corridor absorbing wrist strap and bench mat procurement volume.
Germany
REACH framework restrictions on carbon black conductive additives are accelerating alternative polymer formulation R&D among compounders. ECHA substance sunset dates are forcing qualification timelines for intrinsically conductive polymer substitutes. Bavaria and Baden-Württemberg host tier-1 automotive module suppliers specifying semiconductor-grade ESD thresholds.
South Korea
Foundry capacity additions in Pyeongtaek and Yongin are mandating upgraded EPA-grade flooring and garment programs with decade-long warranty structures. MFDS pharmaceutical manufacturing guidelines are extending cleanroom ESD protocols into biologics fill-finish operations. Seoul Capital Area contract manufacturers are consolidating single-source ESD infrastructure procurement.
India
PLI scheme subsidies for mobile and IT hardware assembly are attracting Foxconn and Dixon Technologies facilities lacking mature ESD infrastructure. BIS certification requirements for electrostatic protective equipment are creating qualification barriers for unorganized domestic suppliers. Karnataka and Tamil Nadu electronics manufacturing clusters present first-mover specification-setting opportunities.
Anti-Static Control Products Market Competitive Environment
Top-tier vendors anchor semiconductor fab and automotive OEM specification-setting, while mid-tier fabricators compete on MRO distributor relationships and regional installation services. The vendor base stratifies across three functional tiers: polymer compounders controlling conductive filler formulations, systems integrators bundling hardware with compliance documentation, and regional distributors capturing consolidated procurement contracts. Strategic moves concentrate on backward integration into conductive yarn production and geographic expansion into India's PLI-subsidized electronics corridors.
Among diversified industrial connectivity specialists, Phoenix Contact and Panduit Corp. occupy positions bridging factory automation portfolios into cleanroom environments. Desco Industries anchors the dedicated ESD infrastructure tier through its grounding and monitoring equipment catalog. These three exemplify contrasting archetypes: industrial conglomerates extending reach versus pure-play specialists defending specification influence through deep product catalogs.
| Leading Market Players |
|---|
| Desco Industries Inc. |
| ACL, Inc. |
| Keystone Electronics Corp. |
| Fraser Anti-Static Techniques Ltd. |
| Meech Static Eliminators Ltd. |
| Cole-Parmer Instrument Company, LLC. |
| Botron Company Inc. |
| Phoenix Contact |
| Panduit Corp. |
| Others |
Value Chain & Pricing Dynamics
EPA VOC emission limits on solvent-borne topical antistats gate both qualified supply and premium-tier pricing access, as federal contractor eligibility now demands water-based polyurethane formulations with permanent static-dissipative properties that command specification premiums over commodity-grade alternatives.
Pricing Analysis
Cost-down pressure on wrist straps and bench mats accelerates because petroleum-derived carbon black feedstock pricing tracks crude oil indices, compressing margin stability for compounded sheet manufacturers. Three-tier pricing structure across EPA-grade, industrial-grade, and economy levels separates semiconductor-class certification from automotive module assembly from generic electronics handling. Price differentiation hinges on cleanroom certification tier and embedded RFID tracking capability. Contract manufacturers in China and Mexico exhibit highest price sensitivity through consolidated single-source procurement mandates, while aerospace and defense primes absorb premium-tier pricing for water-based coating compliance.
Supply Chain Analysis
Workforce availability constraints in Zhejiang Province carbon fiber production clusters and Taiwan conductive yarn weaving facilities are tightening output flexibility for ESD garment manufacturers. Supply concentrates in China, South Korea, and Germany for conductive polymer compounding and cleanroom garment fabrication. Raw material dependencies rest on petroleum-derived carbon black, stainless steel microfiber, and intrinsically conductive polymer feedstocks. Single-source vulnerability in Zhejiang Province carbon fiber production creates structural risk for global ESD garment weavers. Distribution runs through regional MRO distributors with captive installation and certification services capturing specification influence from product manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined ESD monitoring systems are displacing legacy scheduled manual audit protocols, embedding real-time ionization balance verification and automated compliance documentation into continuous manufacturing data streams.
For Market Incumbents: Extend specification influence through backward integration into conductive yarn production and embedded sensor hardware, defending against industrial IoT vendors seeking bundled software-hardware partnerships. Anchor recurring service relationships via subscription-based compliance dashboards that lock in electronics OEM multi-site standardization needs. Prioritize certification investment for water-based polyurethane formulations ahead of EPA VOC sunset enforcement. For New Entrants and Emerging Players: India's PLI scheme subsidies for mobile and IT hardware assembly open a window for first-mover specification-setting with Foxconn and Dixon Technologies facilities lacking mature ESD infrastructure. Target Karnataka and Tamil Nadu electronics manufacturing clusters through BIS certification qualification as a barrier against unorganized domestic suppliers. Lead with Bluetooth-enabled wrist strap continuity sensors integrated with factory MES platforms as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Semiconductor fabrication node transitions below three nanometers are the leading indicator that ESD threshold tolerance tightening will accelerate demand for Class 0 dissipative materials and real-time monitoring infrastructure. Long-term viability centers on compounders with alternative polymer formulation capabilities ahead of REACH carbon black restrictions and intrinsically conductive polymer substitution timelines. Acquisition target archetype: regional distributors with captive installation services and consolidated procurement contracts. Watch for foundry capacity addition announcements in Taiwan and South Korea as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Yarn Production | Captive supply of stainless steel microfiber reduces Zhejiang Province single-source vulnerability for ESD garment weavers. |
| Water-Based Coating Formulation Qualification | EPA VOC compliance maintains federal contractor eligibility for flooring and worksurface manufacturers serving aerospace primes. |
| Bluetooth-Enabled Wrist Strap Sensor Launch | Factory MES platform integration automates compliance documentation for automotive and medical device lot-level traceability. |
| India PLI Corridor Geographic Expansion | Karnataka and Tamil Nadu facility proximity captures Foxconn and Dixon Technologies specification-setting relationships. |
| Software-Defined Monitoring Platform Partnership | Industrial IoT vendor bundling extends hardware reach into semiconductor fab real-time ionization balance verification. |
Study Parameters
Multi-period observation of semiconductor fab ESD infrastructure contract values, EPA VOC regulatory enforcement patterns, and conductive polymer formulation qualification timelines anchored the trend analysis, supplemented by interviews with cleanroom operations managers, ESD program directors at electronics OEMs, polymer compounder R&D leads, and regional MRO distributor principals. Secondary validation drew from EPA enforcement databases, ECHA substance restriction sunset schedules, MIIT dual carbon policy disclosures, and SEC filings of diversified industrial connectivity specialists. Bottom-up project-level contract aggregation and top-down sectoral demand estimation were triangulated against foundry capacity expansion announcements.
The input-output matrix framed demand drivers through product type, material composition, application environment stringency, and end-user procurement sophistication dimensions across the projection horizon. Modeled segmentation captured floor mats, wrist straps, bags, and garments by vinyl, rubber, polyester, and fabric materials across electronics manufacturing, cleanroom, healthcare, and automotive applications. CAGRs were derived from facility-level ESD infrastructure investment scaling with cleanroom square footage and node transition timelines. Forecast inputs included carbon black feedstock pricing volatility indices and REACH alternative polymer substitution readiness assessments.
The model assumes a particular technology adoption path; alternative pathways for intrinsically conductive polymer substitution ahead of carbon black restriction deadlines would alter the outlook. Forecasts reflect assumptions regarding semiconductor node transition pacing, EPA VOC enforcement consistency, and PLI scheme subsidy continuity. Material deviation in foundry capacity addition schedules, ECHA substance restriction acceleration, or crude oil index volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
UV Light Stabilizers Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Aerosol Cans Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Hydroxypropionic Acid Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Global Silicone Defoamer Market