
 Global Salicylic Acid Market | 2026-2036
Global Salicylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Salicylic Acid Market Foresight
Green chemistry process intensification is narrowing the cost gap between petrochemical and bio-based salicylic acid synthesis routes. Zhenjiang Gaopeng Pharmaceutical anchors large-volume production through backward integration into phenol supply chains. Seqens Group differentiates via pharmaceutical-grade certification breadth across European and North American pharmacopeias. Thermo Fisher Scientific leverages analytical-grade positioning to command premium pricing in laboratory and diagnostic reagent channels.
Salicylic acid is a beta-hydroxy acid (C7H6O3) synthesized via Kolbe-Schmitt carboxylation of sodium phenoxide or extracted from natural salicylate sources, functioning primarily as a keratolytic agent, chemical intermediate, and preservative across industrial and consumer applications. Powder and crystal grades dominate volume throughput for pharmaceutical and coatings applications where flowability and dissolution kinetics determine processing economics. Pharmaceutical purity grade commands the widest margin pool due to USP and EP compliance burdens, while cosmetic-grade demand accelerates from clean-label preservative substitution in Asian and European personal care markets.
FDA monograph requirements for over-the-counter acne treatments set minimum salicylic acid concentration and labeling standards that shape product development budgets for North American entrants. EMA and REACH jointly tighten impurity profiling and environmental release thresholds for European cosmetic and industrial applications, elevating testing costs for non-specialized producers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and Chinese Pharmacopoeia standards to anticipate reformulation and re-registration obligations.
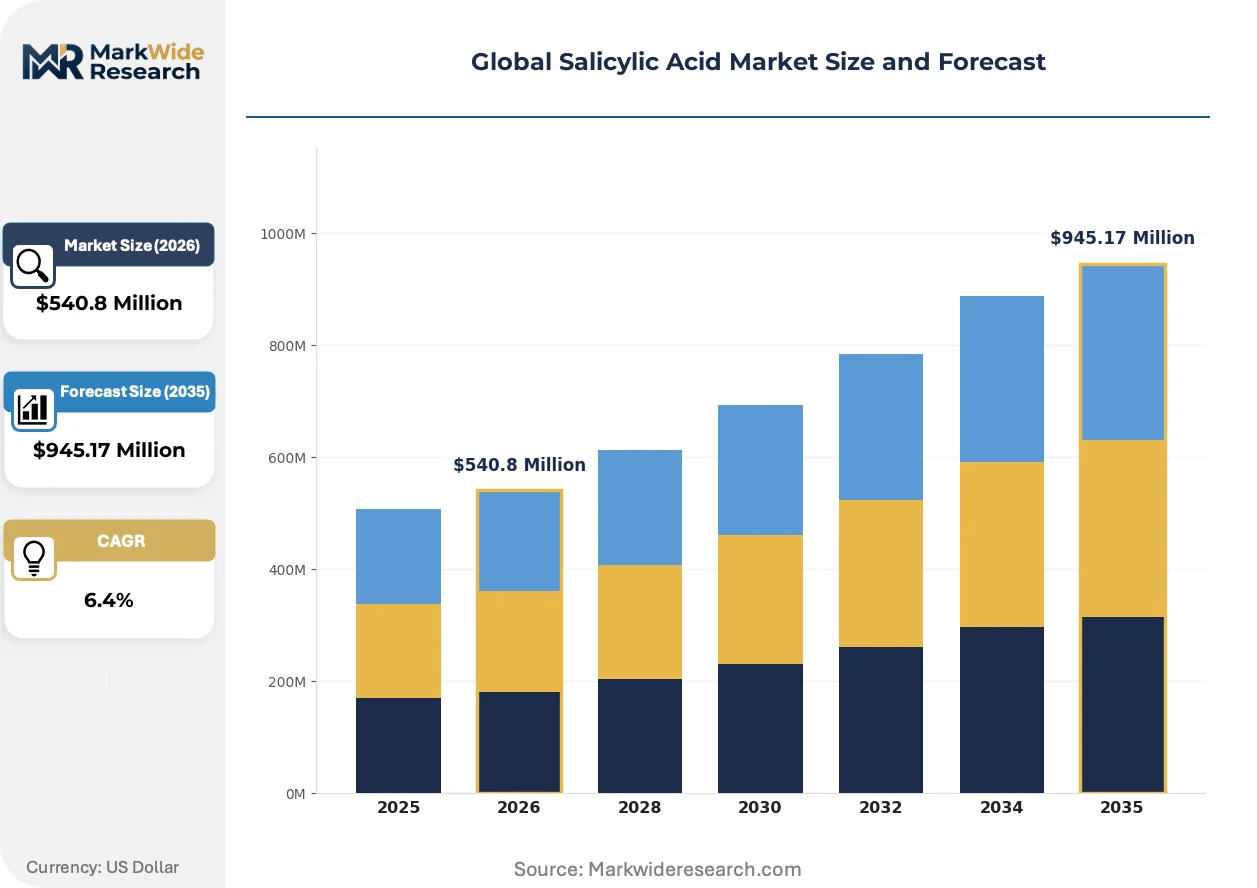
Market Dynamics
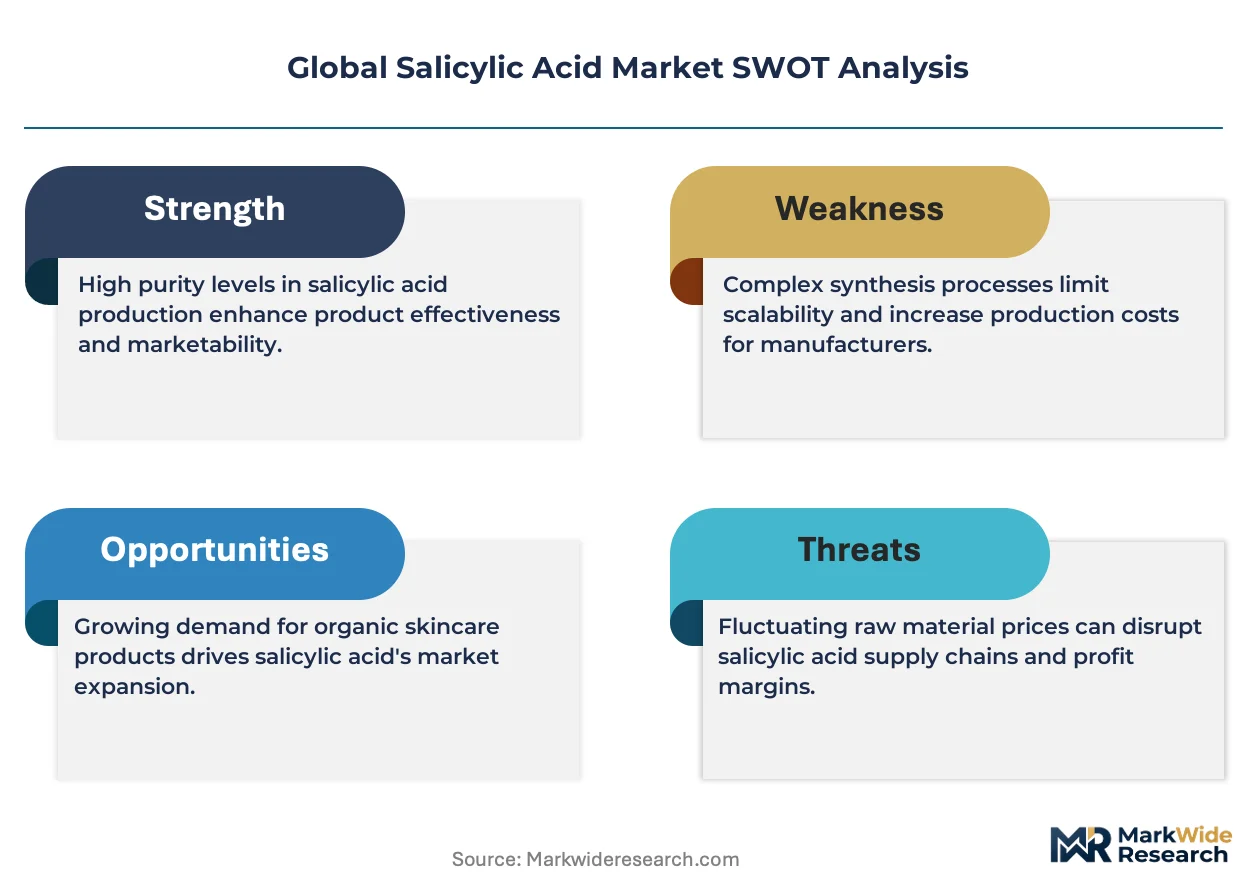
Pharmaceutical-grade purity requirements and REACH compliance burdens are compressing margins for non-specialized producers while rewarding backward-integrated phenol suppliers with captive Kolbe-Schmitt capacity.
Growth Catalysts
- Clean-label preservative substitution:Personal care formulators in Germany and France are replacing parabens with salicylic acid to meet ECHA consumer safety guidelines.
- REACH RoHS alignment:Tighter impurity thresholds for cosmetic-grade material are locking out low-purity imports and securing market position for certified European producers.
- API cluster expansion:Pharmaceutical manufacturing zones in India and China are scaling keratolytic and anti-inflammatory output, pulling upstream salicylic acid demand.
Market Restraints
- Phenol feedstock volatility:Crude benzene price swings transmit directly to Kolbe-Schmitt process economics, squeezing non-integrated producers.
- Single-source supply risk:Zhenjiang Gaopeng and three Chinese state-owned phenol complexes control over half of merchant salicylic acid capacity.
- Natural extraction yield limits:Willow bark and wintergreen sources cannot achieve pharmaceutical-grade purity without prohibitively expensive multi-stage crystallization.
Strategic Opportunities
- Brazilian cosmetic market penetration:ANVISA's streamlined preservative approval pathway is opening formulation opportunities for EP-certified exporters.
- Bio-based synthesis convergence:Cell-free enzymatic carboxylation paired with renewable phenol from lignin is nearing cost parity with petrochemical routes.
- Direct-to-compounder e-commerce:Laboratory reagent distributors are bypassing traditional chemical merchant networks to serve mid-volume cosmetic formulators.
Industry Challenges
- Pharmacopeial harmonization complexity:Divergent USP, EP, and Chinese Pharmacopoeia monograph updates force parallel stability studies and re-registration costs.
- Specialized crystallization engineering shortage:Few process engineers possess simultaneous expertise in GMP compliance and continuous flow Kolbe-Schmitt optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Salicylic Acid Market |
| Market Size in 2026 | $540.8 Million |
| Market Size in 2035 | $945.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Crystals, Flakes Purity Grade: Pharmaceutical, Cosmetic, Industrial, Food, Technical Application: Skin Care, Acne Treatment, Paints, Adhesives, Biocides End User Industry: Pharmaceutical Manufacturers, Cosmetic Producers, Chemical Synthesizers, Coatings Manufacturers, Agriculture Sector |
| Companies Covered | Siddharth Carbochem Products, Zhenjiang Gaopeng Pharmaceutical, Thermo Fisher Scientific, Seqens Group, Novocap, Merck KGaA, Hebei Jingye Group, Alfa Aesar, Alta Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Salicylic Acid Market Shifts & Advancements
Process intensification and regulatory digitization are compressing certification timelines while fragmenting traditional chemical distribution channels.
Continuous flow Kolbe-Schmitt reactors are replacing batch phenoxide carboxylation in pharmaceutical-grade production. Thermo Fisher Scientific and Seqens Group are retrofitting legacy batch assets to reduce solvent use and impurity formation. The technology is migrating from high-volume commodity output toward small-lot, multi-pharmacopeia certified material where batch traceability commands premium positioning.
EMA's tightened nitrosamine impurity guidance for chemically synthesized APIs is forcing salicylic acid producers to implement additional gas chromatography-mass spectrometry screening protocols. European contract manufacturers serving topical drug applicants now require supplier certificates of analysis with expanded nitrosamine declarations. This regulatory layer most affects Indian and Chinese API producers seeking European market access, accelerating investment in dedicated nitrosamine-free production lines.
Cosmetic compounders are consolidating supplier panels from six-to-eight merchant distributors down to two-to-three directly contracted manufacturers with captive analytical laboratories. This concentration is displacing spot-market purchasing and long-payment-term relationships with smaller regional distributors. The shift is most visible in South Korean and Japanese personal care markets where chaebol and keiretsu formulators enforce vendor reduction mandates.
Global Salicylic Acid Market Segmentation
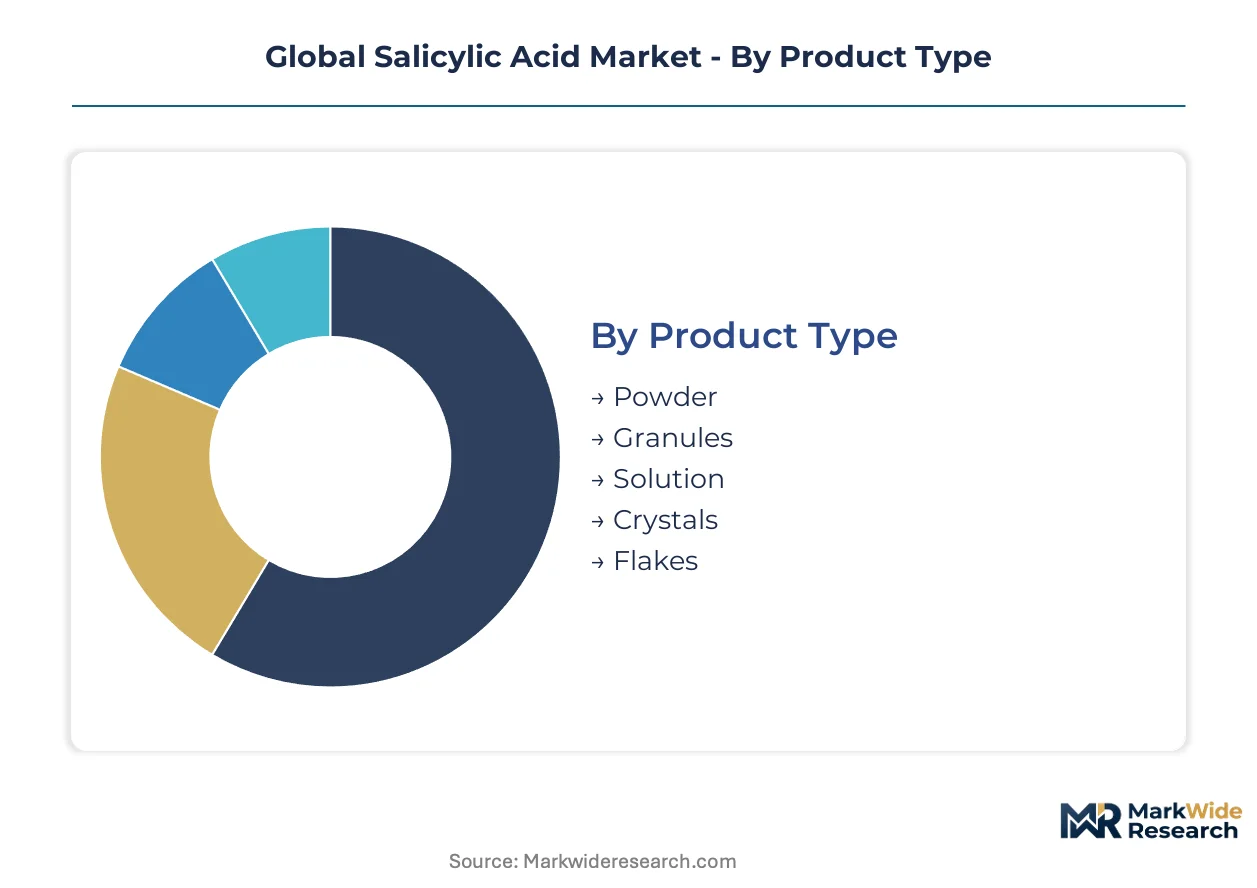
Salicylic acid demand fragments across five distinct product forms, five purity tiers, five application clusters, and five end-use industries. Each dimension carries different certification burdens, margin structures, and geographic concentration patterns that reshape supplier positioning.
Product Type:
Powder and crystal grades anchor pharmaceutical throughput where dissolution kinetics determine processing economics, while solution and flake formats serve industrial coatings and preservative applications with lower purity thresholds.
- Powder:Fine particulate form optimized for tablet compression and topical formulation flowability. Demand concentrates among Indian and Chinese API manufacturers scaling keratolytic output, constrained by USP dissolution rate specifications that disqualify coarse-mesh alternatives.
- Crystals:High-purity solid form produced via multi-stage recrystallization for pharmaceutical-grade certification. German and Swiss topical drug compounders specify this grade for nitrosamine-compliant production lines, paying premiums for batch-specific impurity profiling.
- Granules:Agglomerated particles for controlled-release dermatological preparations and veterinary feed additives.
- Solution:Aqueous or alcoholic preparations serving cosmetic preservative systems and industrial biocide formulations.
- Flakes:Compressed solid form for coatings manufacturing and adhesive resin synthesis where rapid dissolution is unnecessary.
The dominant share belongs to Powder, while Crystals is closing the gap fastest.
Purity Grade:
Certification tier directly determines addressable market scope and testing cost burden, with pharmaceutical and cosmetic grades commanding analytical rigor that industrial and technical specifications escape.
- Pharmaceutical:USP and EP-compliant material with sub-ppm impurity limits for API and topical drug applications. FDA monograph requirements for OTC acne treatments mandate this grade for North American entrants, forcing dedicated production lines with nitrosamine screening protocols.
- Cosmetic:ECHA-guided purity for preservative and exfoliant use in personal care. French and German formulators are consolidating supplier panels around this grade to meet clean-label substitution timelines, displacing paraben alternatives.
- Industrial:Standard purity for chemical intermediate and coatings applications with relaxed heavy metal specifications.
- Food:FSSAI and FDA food additive compliance for preservative use in packaged goods and flavoring systems.
- Technical:Lowest purity tier for rubber manufacturing and general chemical synthesis with minimal analytical documentation.
Pharmaceutical commands the widest margin pool, though Cosmetic is expanding most quickly.
Application:
Functional use case determines whether salicylic acid operates as active pharmaceutical ingredient, cosmetic preservative, or industrial chemical intermediate, with each pathway imposing distinct regulatory gateways.
- Skin Care:Exfoliant and anti-aging active in leave-on and rinse-off formulations. South Korean chaebol formulators are driving specification tightening for BHA content disclosure, favoring suppliers with captive analytical laboratories.
- Acne Treatment:Keratolytic active in OTC and prescription topical drugs. FDA concentration and labeling standards shape product development budgets, while EMA nitrosamine guidance forces additional GC-MS screening for European market access.
- Paints:Coalescing agent and corrosion inhibitor in industrial coatings with REACH release threshold compliance.
- Adhesives:Resin modifier and tackifier in pressure-sensitive and structural bonding systems.
- Biocides:Preservative and antifungal agent in agricultural and industrial applications under BPR review cycles.
Skin Care holds the volume lead, while Acne Treatment is gaining share fastest.
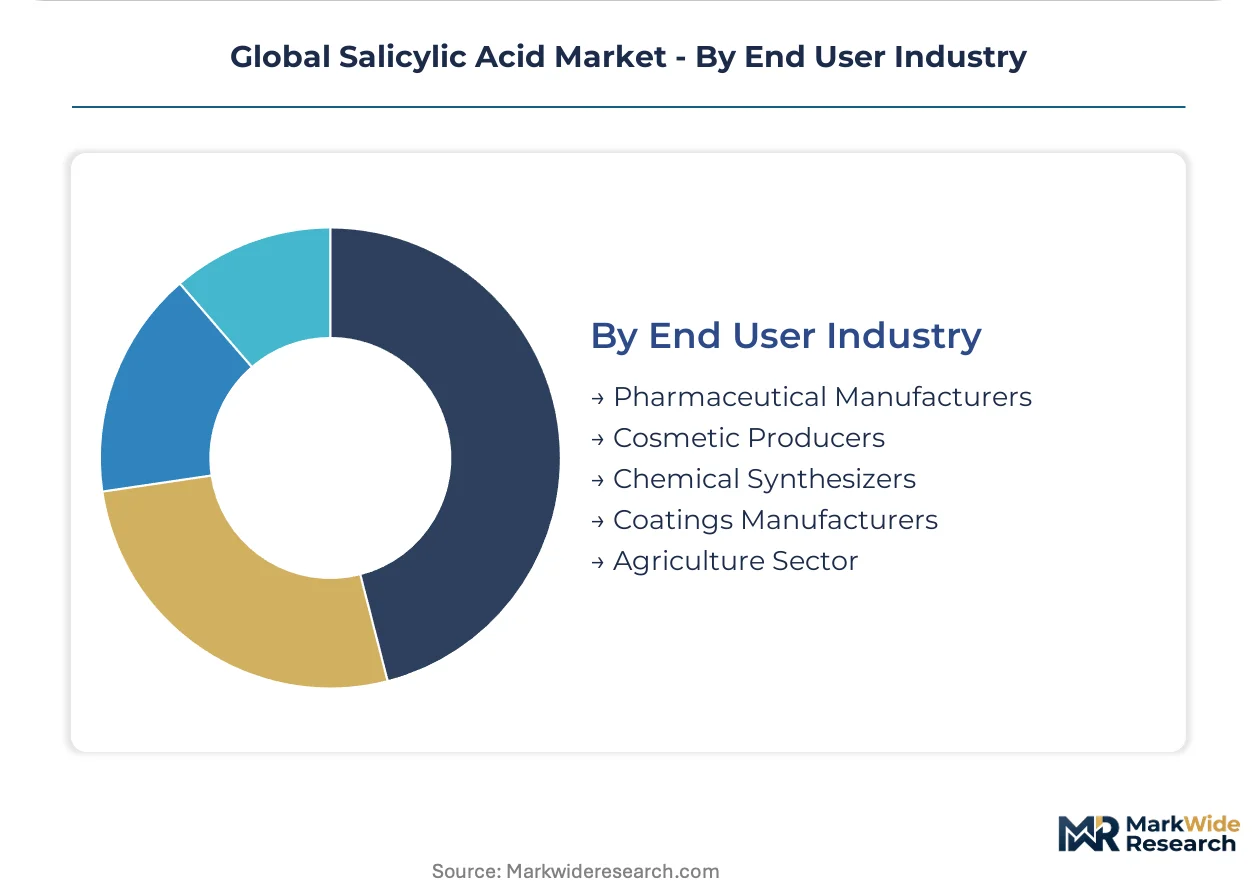
End User Industry:
Customer type shapes procurement modality, with pharmaceutical and cosmetic buyers enforcing vendor reduction mandates that displace spot-market purchasing.
- Pharmaceutical Manufacturers:API and topical drug producers with USP, EP, and Chinese Pharmacopeia compliance requirements. Indian manufacturing zones are scaling capacity fastest, pulling upstream demand for certified material.
- Cosmetic Producers:Personal care formulators replacing parabens under ECHA consumer safety guidelines. Japanese keiretsu and South Korean chaebol enforce two-to-three supplier panels with direct manufacturer contracts.
- Chemical Synthesizers:Intermediate producers for aspirin, dyes, and fragrance manufacturing with technical-grade specifications.
- Coatings Manufacturers:Industrial paint and adhesive compounders with REACH and RoHS impurity thresholds.
- Agriculture Sector:Biocide and plant growth regulator applications with national pesticide registration requirements.
Pharmaceutical Manufacturers dominate procurement volume, while Cosmetic Producers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting trade flows as phenol supply constraints in Europe and pharmaceutical-grade certification requirements in North America reshape sourcing patterns. China maintains surplus production capacity while Germany and India absorb premium-grade imports for compliant manufacturing.
China
Zhenjiang and Shandong phenol complexes feed Kolbe-Schmitt reactors serving both domestic API manufacturers and export markets. NMPA alignment with ICH Q3D elemental impurity guidelines is forcing crystallization upgrades for pharmaceutical-grade output. The Yangtze River Delta cluster concentrates cosmetic-grade production for Southeast Asian personal care formulators.
Germany
REACH Article 33 disclosure obligations and ECHA consumer safety guidelines are locking out non-certified imports for cosmetic applications. The North Rhine-Westphalia chemical corridor hosts Seqens Group pharmaceutical-grade facilities serving European topical drug manufacturers. Importers face nitrosamine screening mandates under EMA's tightened API guidance.
India
CDSCO harmonization with USP and EP monographs is accelerating re-registration costs for export-oriented API producers. Maharashtra and Gujarat pharmaceutical zones are scaling keratolytic manufacturing, pulling upstream demand for USP-compliant material. Domestic phenol supply gaps force reliance on Middle Eastern benzene derivatives.
United States
FDA OTC monograph requirements for acne treatments mandate specific salicylic acid concentrations and labeling standards that shape formulation development. The New Jersey-Pennsylvania pharmaceutical corridor imports pharmaceutical-grade material for topical drug compounding. EPA release reporting under TSCA Section 8(a) affects industrial-grade procurement for coatings applications.
Brazil
ANVISA's streamlined preservative approval pathway is attracting EP-certified exporters for cosmetic formulation opportunities. São Paulo state personal care manufacturers are substituting parabens under consumer safety pressure, expanding salicylic acid demand. Import dependence on Chinese technical-grade material persists for industrial coatings segments.
Global Salicylic Acid Market Competitive Landscape
On the supply side, the industry is bifurcating between backward-integrated phenol producers with captive Kolbe-Schmitt capacity and specialized refiners dependent on merchant feedstock. Three archetypes dominate: integrated petrochemical-to-pharma operators, multi-pharmacopeia certification specialists, and analytical-grade laboratory reagent distributors. Capacity expansion and pharmacopeial certification breadth constitute the primary competitive vectors as margin compression squeezes non-integrated players.
Within the integrated operator tier, Zhenjiang Gaopeng Pharmaceutical exemplifies backward integration into phenol supply chains. Seqens Group and Thermo Fisher Scientific occupy positions on the certification-specialist and analytical-grade vectors respectively. These three anchors illustrate the strategic segmentation between volume-driven commodity production and premium-tier compliance positioning.
| Leading Market Players |
|---|
| Siddharth Carbochem Products |
| Zhenjiang Gaopeng Pharmaceutical |
| Thermo Fisher Scientific |
| Seqens Group |
| Novocap |
| Merck KGaA |
| Hebei Jingye Group |
| Alfa Aesar |
| Alta Laboratories |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta phenol complex anchors global merchant capacity, with Zhenjiang Gaopeng's backward integration into feedstock supply creating asymmetric pricing power over non-integrated refiners dependent on spot benzene markets. This concentration permits selective margin defense in pharmaceutical-grade tiers while squeezing technical-grade competitors exposed to crude benzene volatility.
Pricing Analysis
Batch-to-continuous flow technology gaps define current pricing stratification, with legacy Kolbe-Schmitt operators facing cost compression against retrofit pharmaceutical-grade producers. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades reflects certification burden differentiation, with USP and EP compliance commanding substantial premia over technical specifications. Pricing pressure stems from phenol feedstock volatility transmitting directly to non-integrated producers, while Indian API manufacturers exhibit highest price sensitivity due to CDSCO re-registration cost burdens.
Supply Chain Analysis
Contract manufacturing concentrates among Zhenjiang Gaopeng, Seqens Group, and Hebei Jingye facilities serving distinct pharmacopeia certification tiers. China, India, and Germany anchor production geography, with supply draws from Middle Eastern benzene derivatives, captive phenol complexes, and European specialty chemical corridors. Single-source vulnerability runs through Chinese state-owned phenol complexes controlling majority merchant capacity. Distribution runs through direct-to-compounder channels displacing traditional chemical merchant networks in mid-volume cosmetic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based enzymatic carboxylation routes nearing cost parity, requiring defensive positioning around certification moats and captive feedstock control.
For Market Incumbents: Build pharmacopeial certification breadth as the primary moat, securing simultaneous USP, EP, and Chinese Pharmacopeia compliance to lock out regional specialists. Deepen backward integration into phenol supply chains to neutralize benzene volatility exposure threatening margin stability. Seqens Group's multi-standard positioning illustrates this defensive architecture against emerging bio-based synthesis threats. For New Entrants and Emerging Players: Brazilian cosmetic formulators present underpenetrated white-space, with ANVISA's streamlined preservative approval pathway enabling EP-certified exporters to bypass entrenched European supply relationships. Target direct-to-compounder e-commerce channels serving mid-volume personal care manufacturers in São Paulo state, leveraging nitrosamine-free production line investments as differentiation against incumbent commodity suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-pharmacopeia certification specialists with demonstrated EMA nitrosamine compliance and captive analytical laboratory infrastructure. Long-term viability centers on producers capable of serving both pharmaceutical API and clean-label cosmetic substitution demand simultaneously. Monitor bio-based synthesis cost parity announcements as inflection signal for petrochemical route margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Kolbe-Schmitt Retrofit | Seqens Group's solvent reduction investments align with EMA impurity screening mandates. |
| Backward Integration into Phenol Supply | Zhenjiang Gaopeng's captive feedstock control neutralizes benzene price transmission risk. |
| Nitrosamine-Free Production Line Investment | Dedicated GC-MS screening protocols unlock European topical drug manufacturer procurement panels. |
| Direct-to-Compounder E-Commerce Launch | Laboratory reagent distributors bypass traditional chemical merchant networks serving cosmetic formulators. |
| Bio-Based Enzymatic Carboxylation Scale-Up | Cell-free lignin-derived phenol routes threaten petrochemical cost structures in premium tiers. |
Research Methodology
The analysis maps pharmaceutical-grade, cosmetic-grade, and industrial-grade production tiers, each validated through procurement directors at API manufacturers, cosmetic formulators, and coatings compounders. Primary interviews with plant managers at Kolbe-Schmitt facilities, regulatory affairs leads navigating EMA nitrosamine guidance, and distribution channel partners informed supply chain dynamics. Secondary validation drew from FDA OTC monograph filings, REACH Article 33 disclosure records, CDSCO harmonization circulars, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Forecast assumptions held fixed the current regulatory divergence between USP, EP, and Chinese Pharmacopeia standards while varying bio-based synthesis cost convergence scenarios across the projection horizon. Segmentation modeling incorporated purity grade tier, end-use industry application, product form factor, and regional production hub clustering. CAGRs derived from weighted capacity expansion announcements, re-registration timeline analysis, and substitution elasticity estimates for paraben replacement demand in European personal care markets.
Practitioners should monitor EMA pharmacopeial harmonization proposals, phenol complex outage patterns, and ANVISA regulatory pathway modifications for early signals of forecast revision. Quarterly review of nitrosamine screening protocol adoption rates, bio-based synthesis pilot scale announcements, and benzene derivative import dependency shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Specialty Oxidants Market
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market